Key Takeaways
- A $6.9 billion fund sold all of its Vistra, DT Midstream and Halliburton stock in the third quarter.
- By Sept. 30, BP and Phillips 66 were its two biggest holdings, and it had more than quadrupled its BP share count.
- Vistra and DT Midstream have both fallen 20% since the quarter ended, while analysts’ average targets sit well above both.
- Vistra looks like the best buy of the three, trading near its usual multiple with next year’s output almost fully hedged.
Merewether Investment Management, a firm managing $6.9 billion, just walked away from three energy stocks. Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows it held no Vistra (VST), DT Midstream (DTM) or Halliburton (HAL) at the quarter’s end, after owning all three at June 30.
It didn’t leave energy behind, though. BP (BP) is now the biggest of its 73 positions, and Phillips 66 (PSX) the second.
Vistra trades at its usual multiple again
Vistra was the biggest of the three exits: 1.27 million shares worth $201 million at June 30, 3.8% of its 13F stocks. The stock is down 20% since Sept. 30, even after a third quarter that lifted adjusted EBITDA to $2.38 billion from $1.58 billion. Vistra also guided 2027 adjusted EBITDA to $7.7 billion to $8.5 billion, with about 98% of next year’s output hedged by Oct. 30.
The 25 analysts who cover it have cut their average target from $228 a year ago, and a $234 peak in March, to $198:
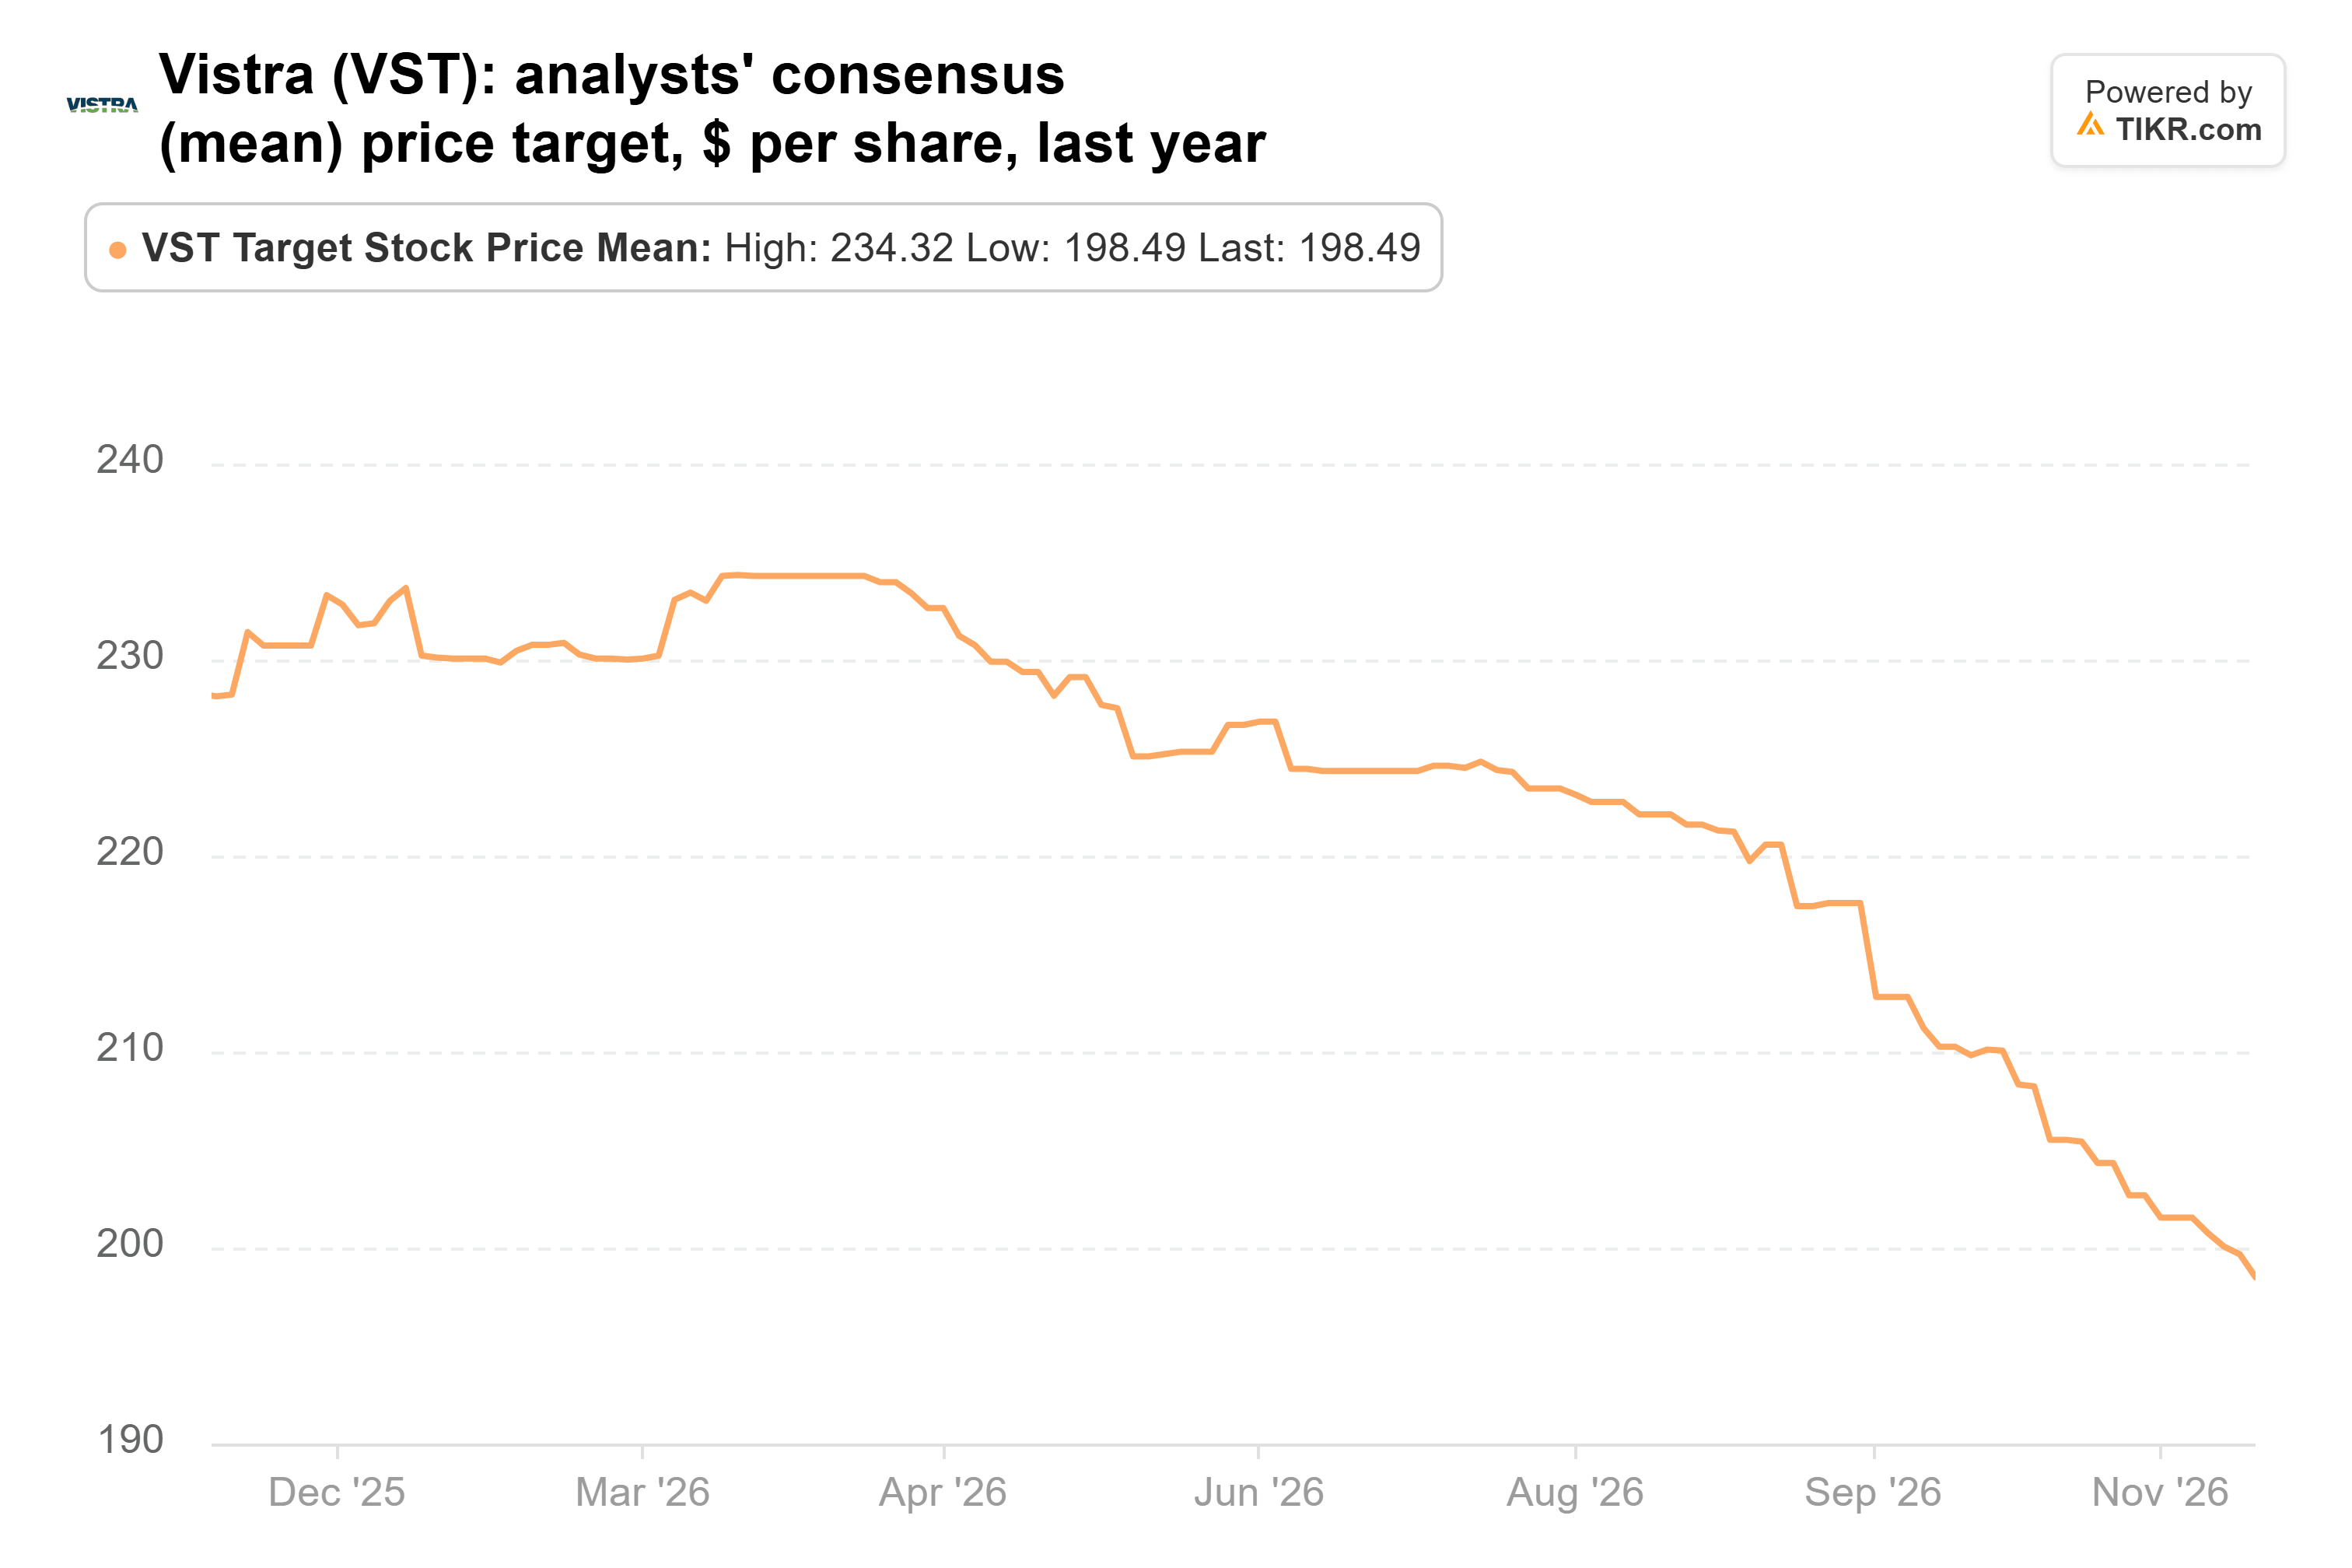
That’s still 56% above the stock. And at about 14x forward earnings, Vistra trades close to its five-year average of 15x and well below its one-year average of 17x.
TIKR tracks 25 analysts on Vistra. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Vistra, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Vistra’s Analyst Ratings
DT Midstream’s outlook rose as its stock fell
DT Midstream was 946,016 shares worth $139 million at June 30, 2.6% of the fund’s 13F stocks. It’s down 20% since Sept. 30 and 23% below its 52-week high, though the business news has been good. In its third-quarter release on Oct. 29, the company raised its 2026 adjusted EBITDA guidance to between $1.19 billion and $1.23 billion, and it stood by an early 2027 outlook of $1.23 billion to $1.30 billion.
Analysts have moved the other way from the stock, lifting their average target to $149 from $117 a year ago:
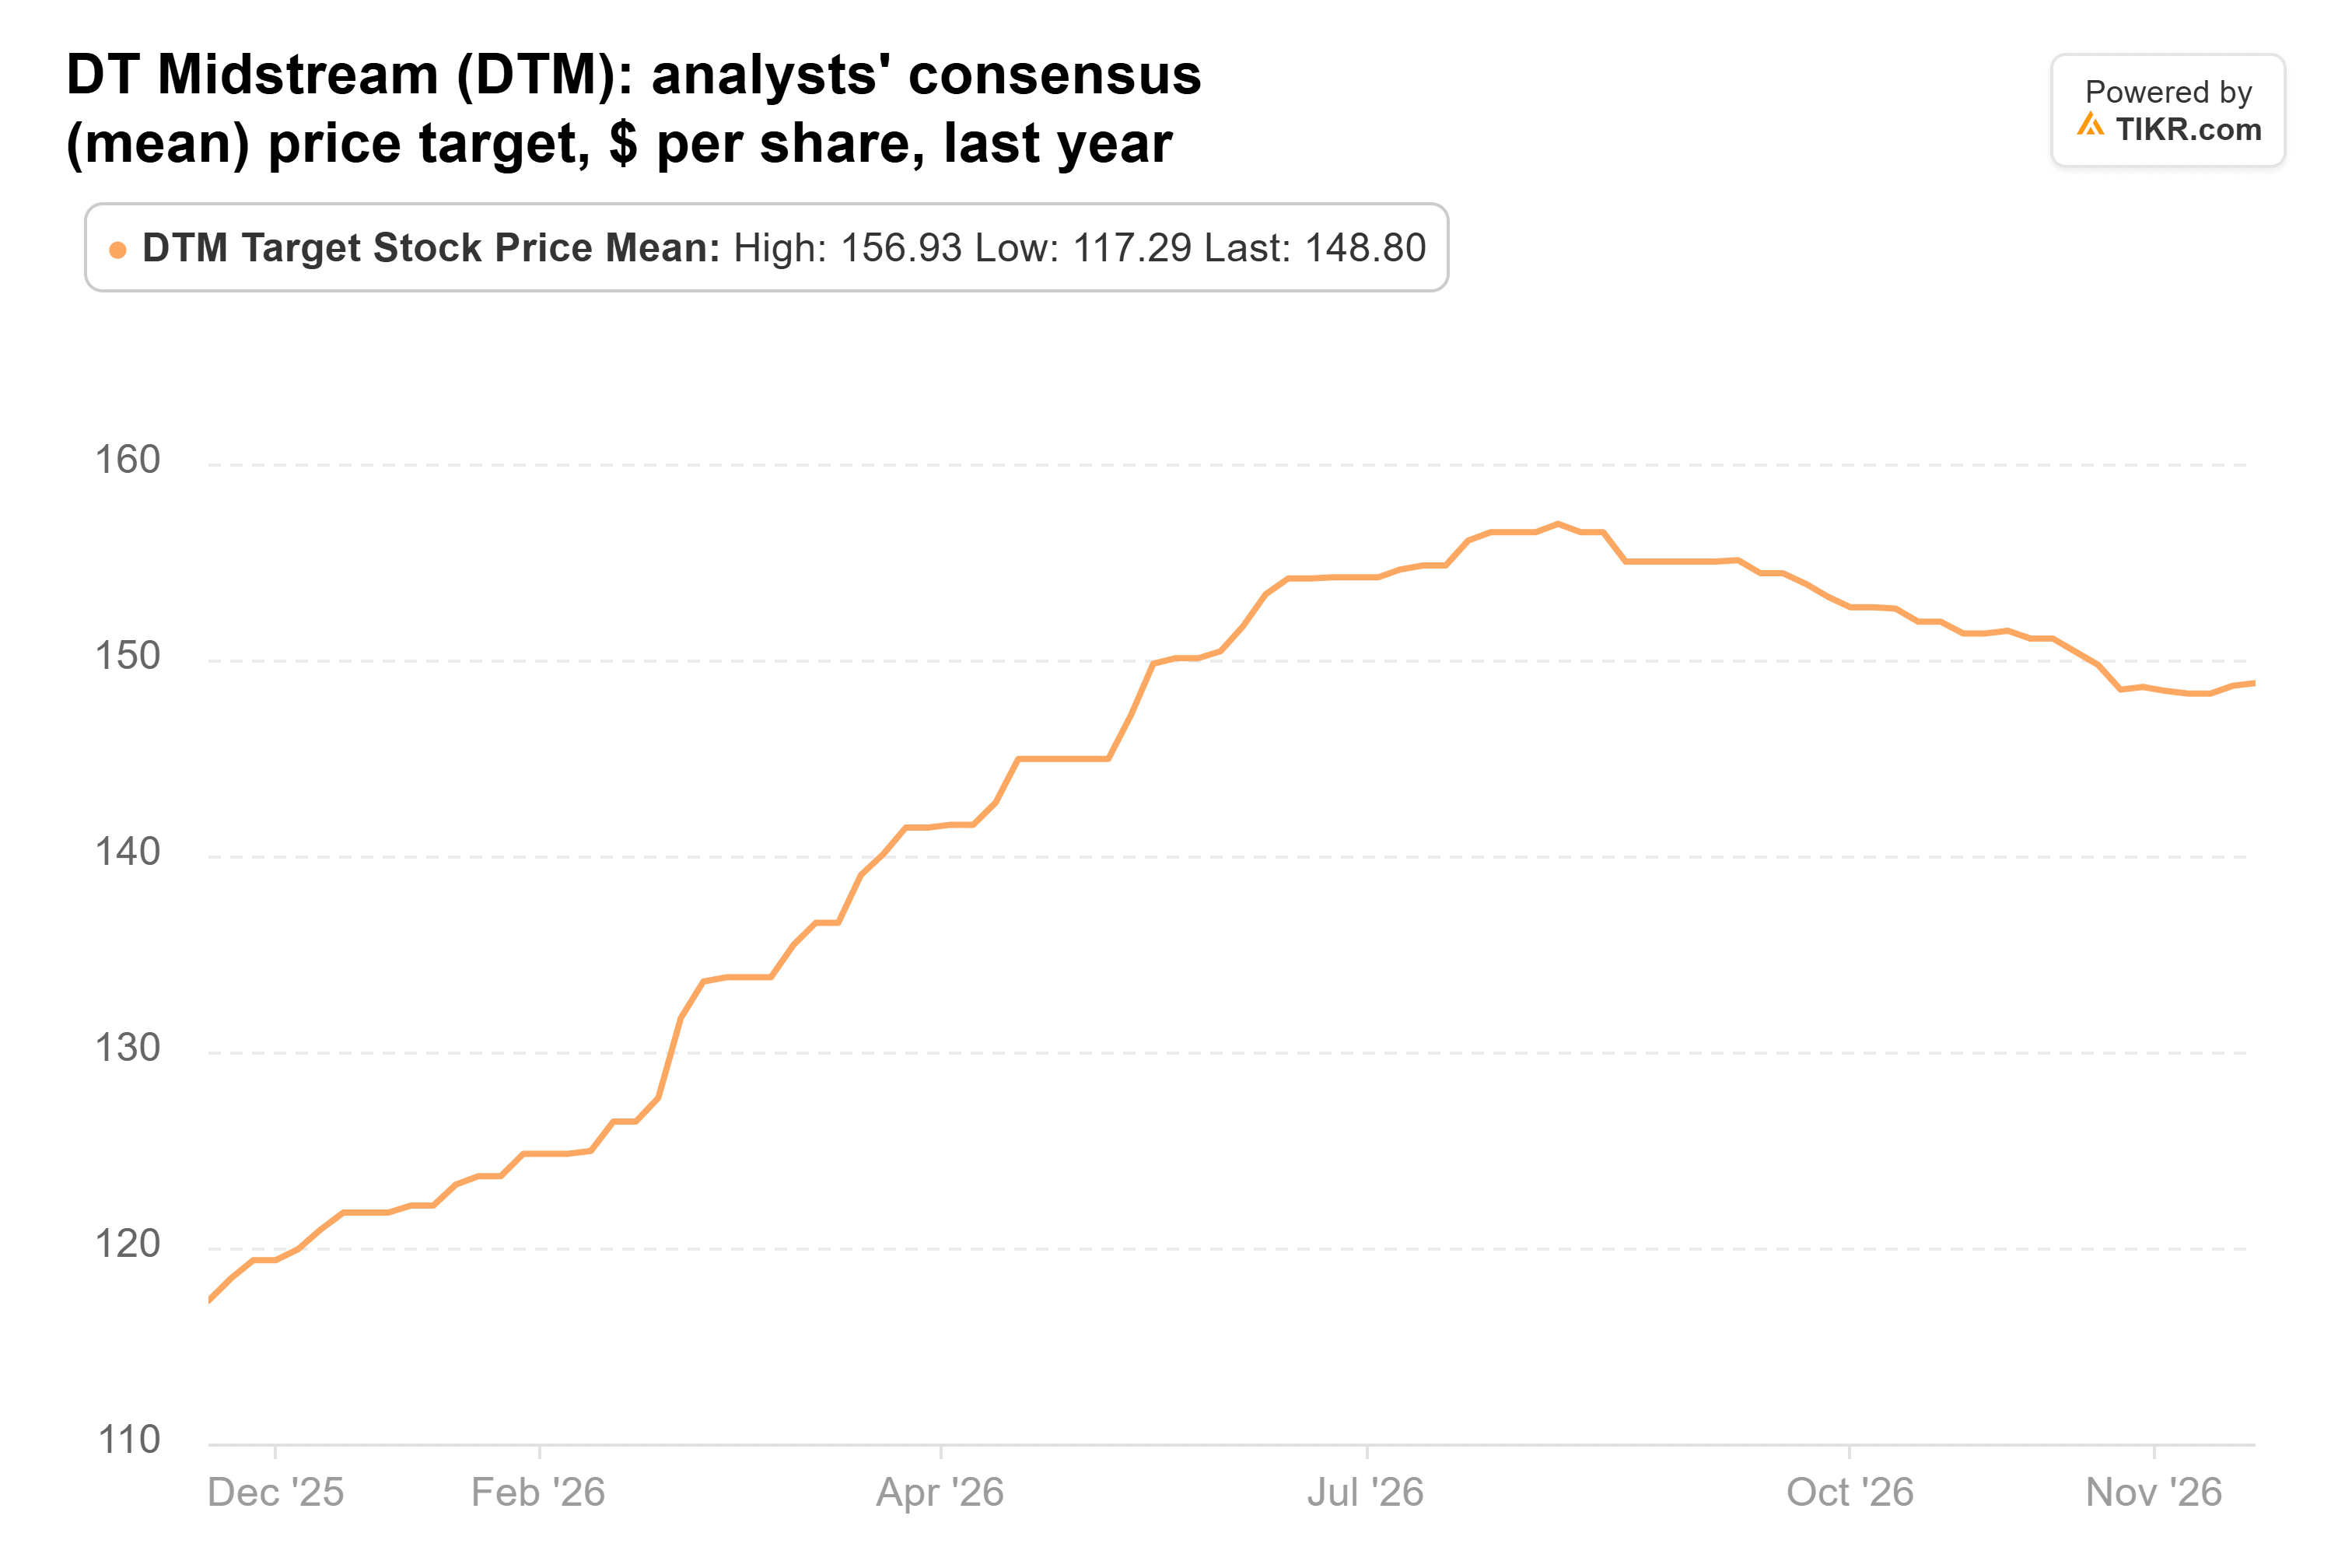
That’s 26% above where the stock trades now. Still, at about 24x forward earnings, DT Midstream asks a full price for a business whose own outlook has EBITDA growing in the single digits next year.
Halliburton still has the Street on its side
Halliburton was the smallest of the three: 2.67 million shares worth $91 million at June 30, 1.7% of the fund’s 13F stocks. It has held up better than the other two, down 6% since Sept. 30, but it’s still 27% below its May high of $42.98.
Analysts have kept raising their average target over the past year, to $44 from $30:
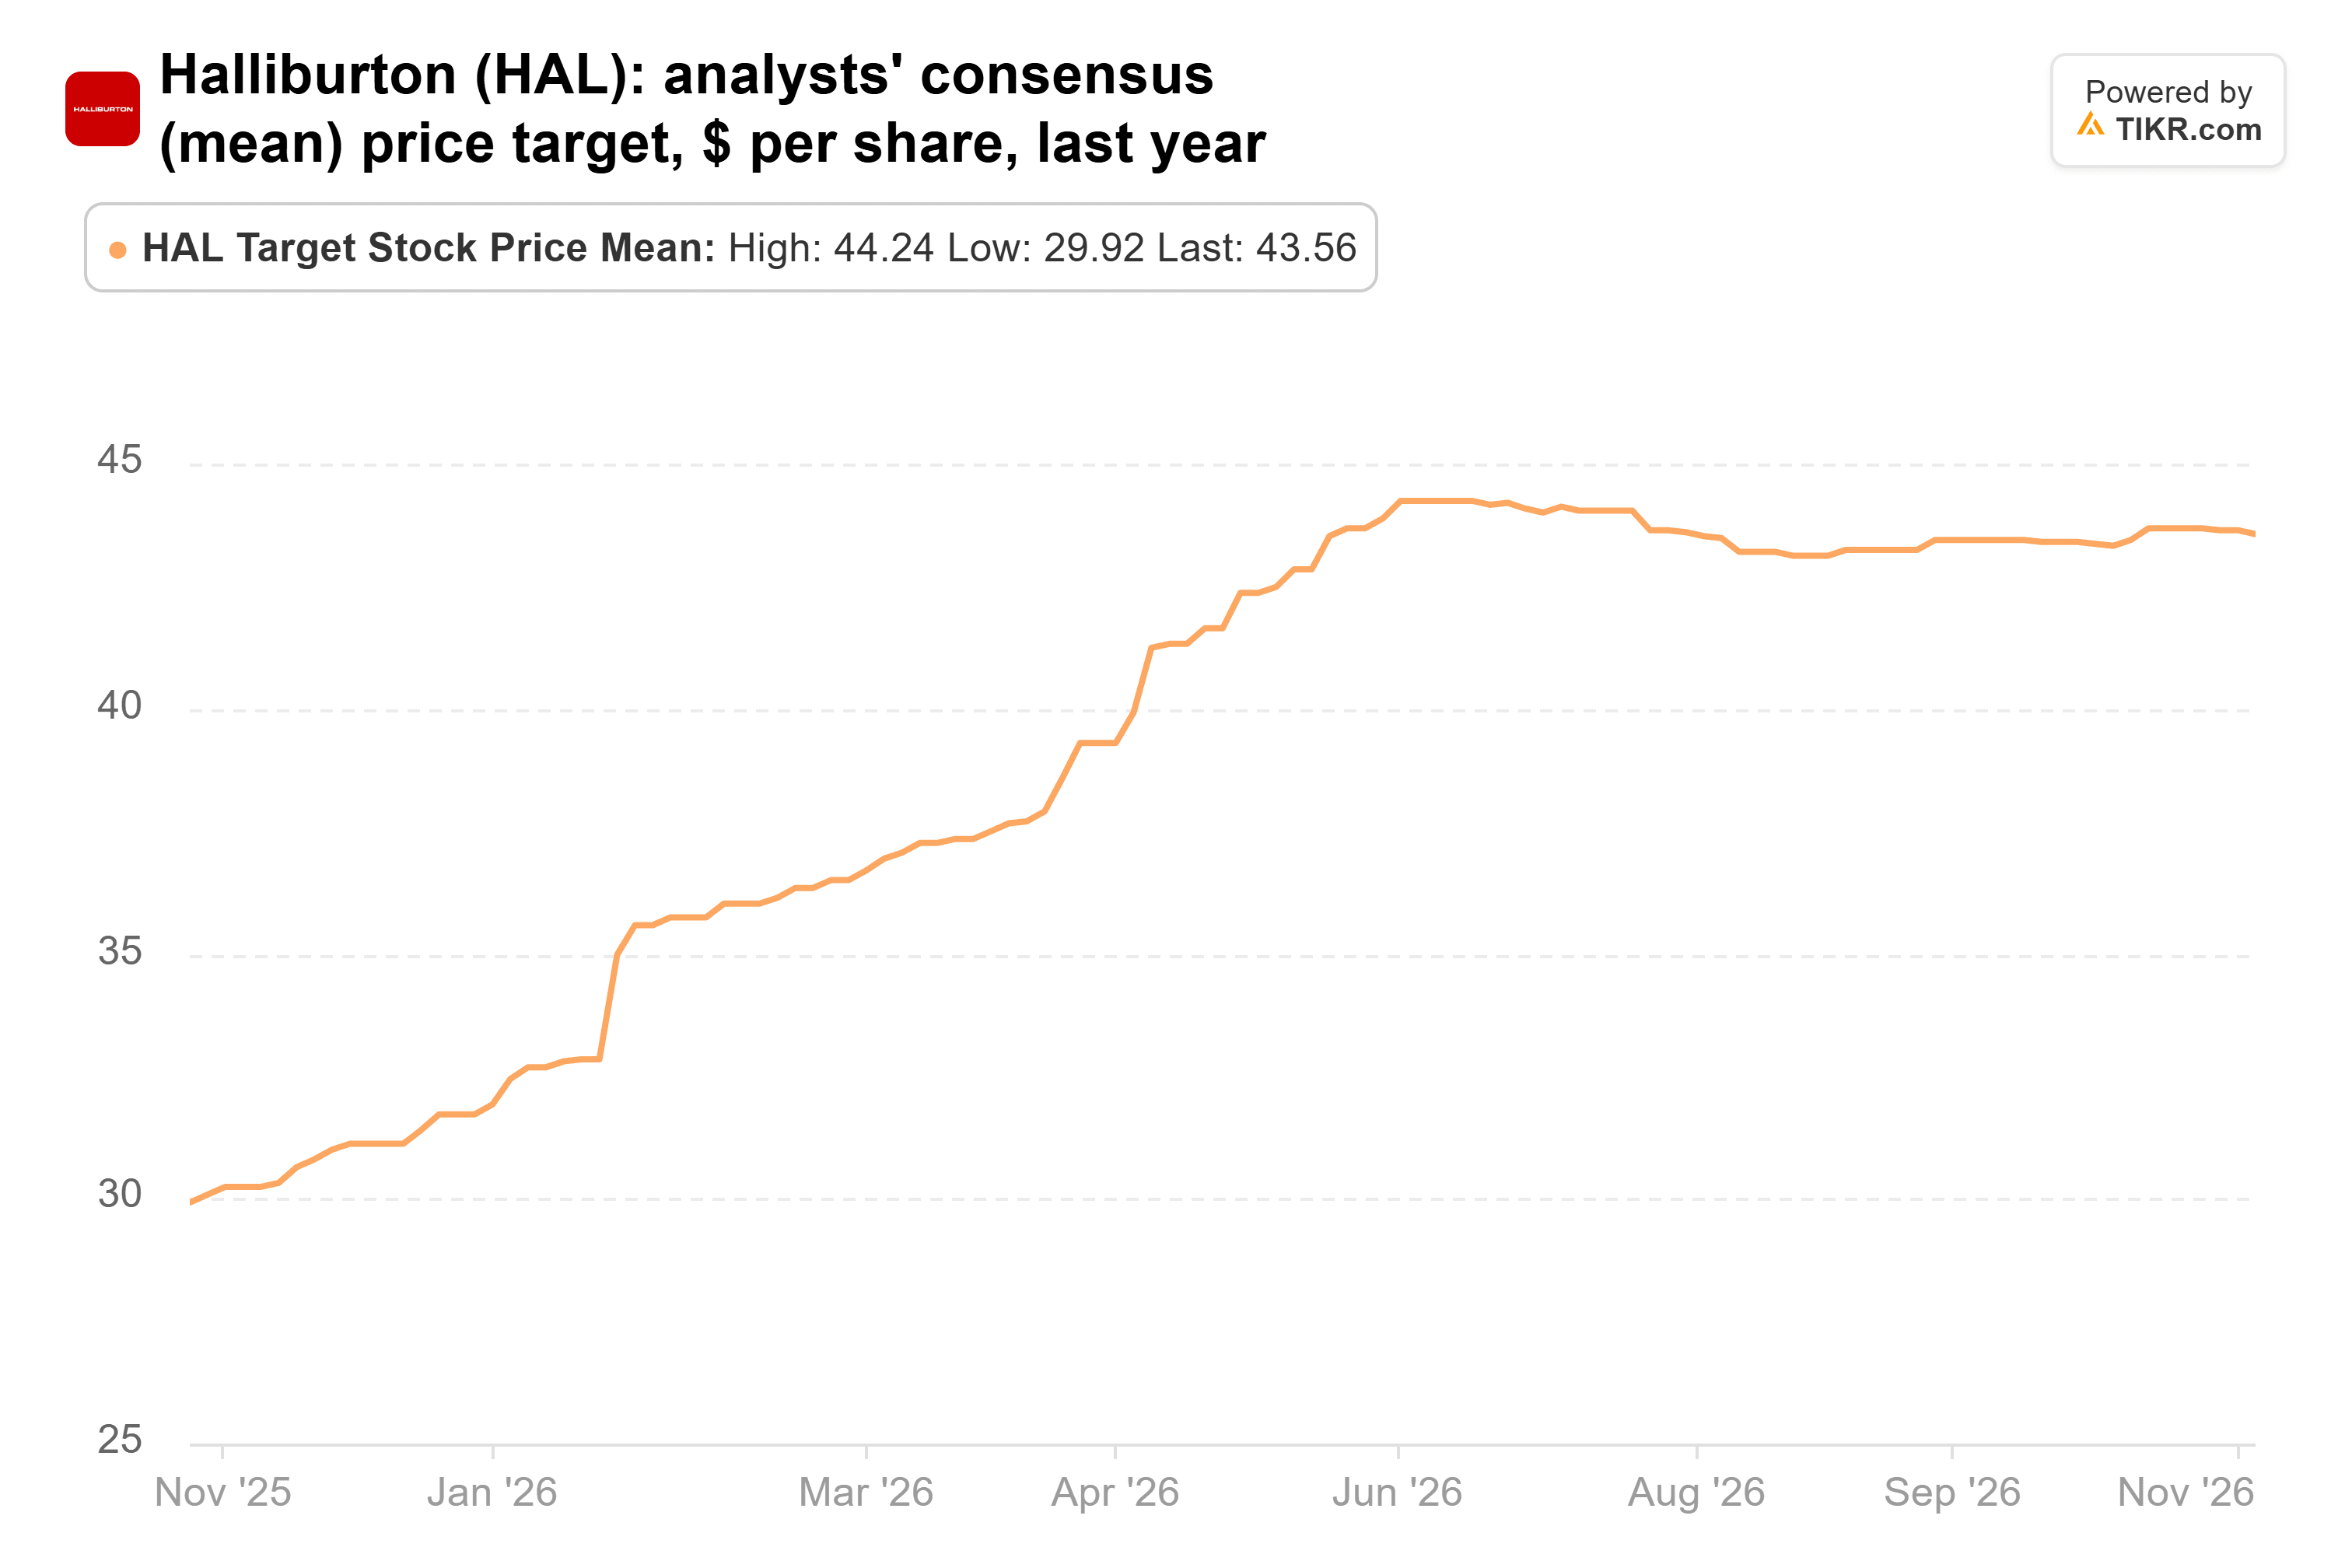
That target is 36% above the stock, which trades at about 12x forward earnings. Of the individual targets, only the lowest, $29, is below the stock, and the highest is $51.
Its two biggest bets are oil
BP was the fund’s No. 1 holding at Sept. 30: 8.11 million shares worth $357 million, 7.2% of its 13F stocks, after a 340% jump in its share count over the quarter. Phillips 66 was No. 2, at 1.24 million shares worth $317 million, or 6.4%, after it added 28% more shares.
Both trade at about 7x forward earnings, half of Vistra’s multiple. Phillips 66 has nearly doubled over the past year, and analysts’ average target of $291 now sits just 13% above it. BP’s $56 average target is 25% above its US shares.
Vistra is the one I’d buy back
If I could only buy one of the three back, it’d be Vistra. It trades near its usual multiple, next year’s output is almost fully hedged, and analysts’ average target is still 56% above the stock after a year of cuts.
The risk is further out. Only about 78% of Vistra’s 2028 output was hedged by Oct. 30, and CEO Jim Burke said it’s much less hedged in Texas that year. Consensus normalized EPS for 2026 has also slipped to $8.55 from $8.72 since late October.
Vistra’s fourth-quarter report, likely in late February, should show how far past 78% it has hedged 2028. The fund’s next 13F, due by mid-February, will show whether it came back to any of these three.
So what is Vistra stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Vistra could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!