Key Takeaways
- Astera Labs and Credo Technology both trade roughly 60% below their highs, but Astera has already delivered its ramp.
- Credo still needs at least $1.46 billion of revenue in its fiscal second half, and Dec. 1 is the first test.
- Coherent’s optical growth supports Credo’s plan, and Marvell Technology reports the same day as Credo.
- At about 17x forward earnings, Credo already prices in a lot of doubt, which makes it the better setup.
Astera Labs (ALAB) and Credo Technology (CRDO) have fallen about as far. Astera trades [58%] below its 52-week high, and Credo is [60%] below its own after a [12%] slide this week.
But Astera reported its ramp on Nov. 3, and Credo reports on Dec. 1, the same day as Marvell Technology (MRVL), which settled a patent fight with Credo on Tuesday. Coherent (COHR) just gave a read on the optical demand Credo is counting on.
Credo needs a monster second half
Credo has guided fiscal 2027 revenue growth of more than 85%, or at least $2.47 billion. With $479.0 million in the first quarter and $525 million to $535 million guided for the second, that leaves at least $1.46 billion for the second half (November through April), up 73% or more from a year earlier. That’s about $730 million a quarter, roughly what Astera has guided for its fourth quarter.
Analysts expect $2.50 billion of revenue this fiscal year and $3.88 billion next year:
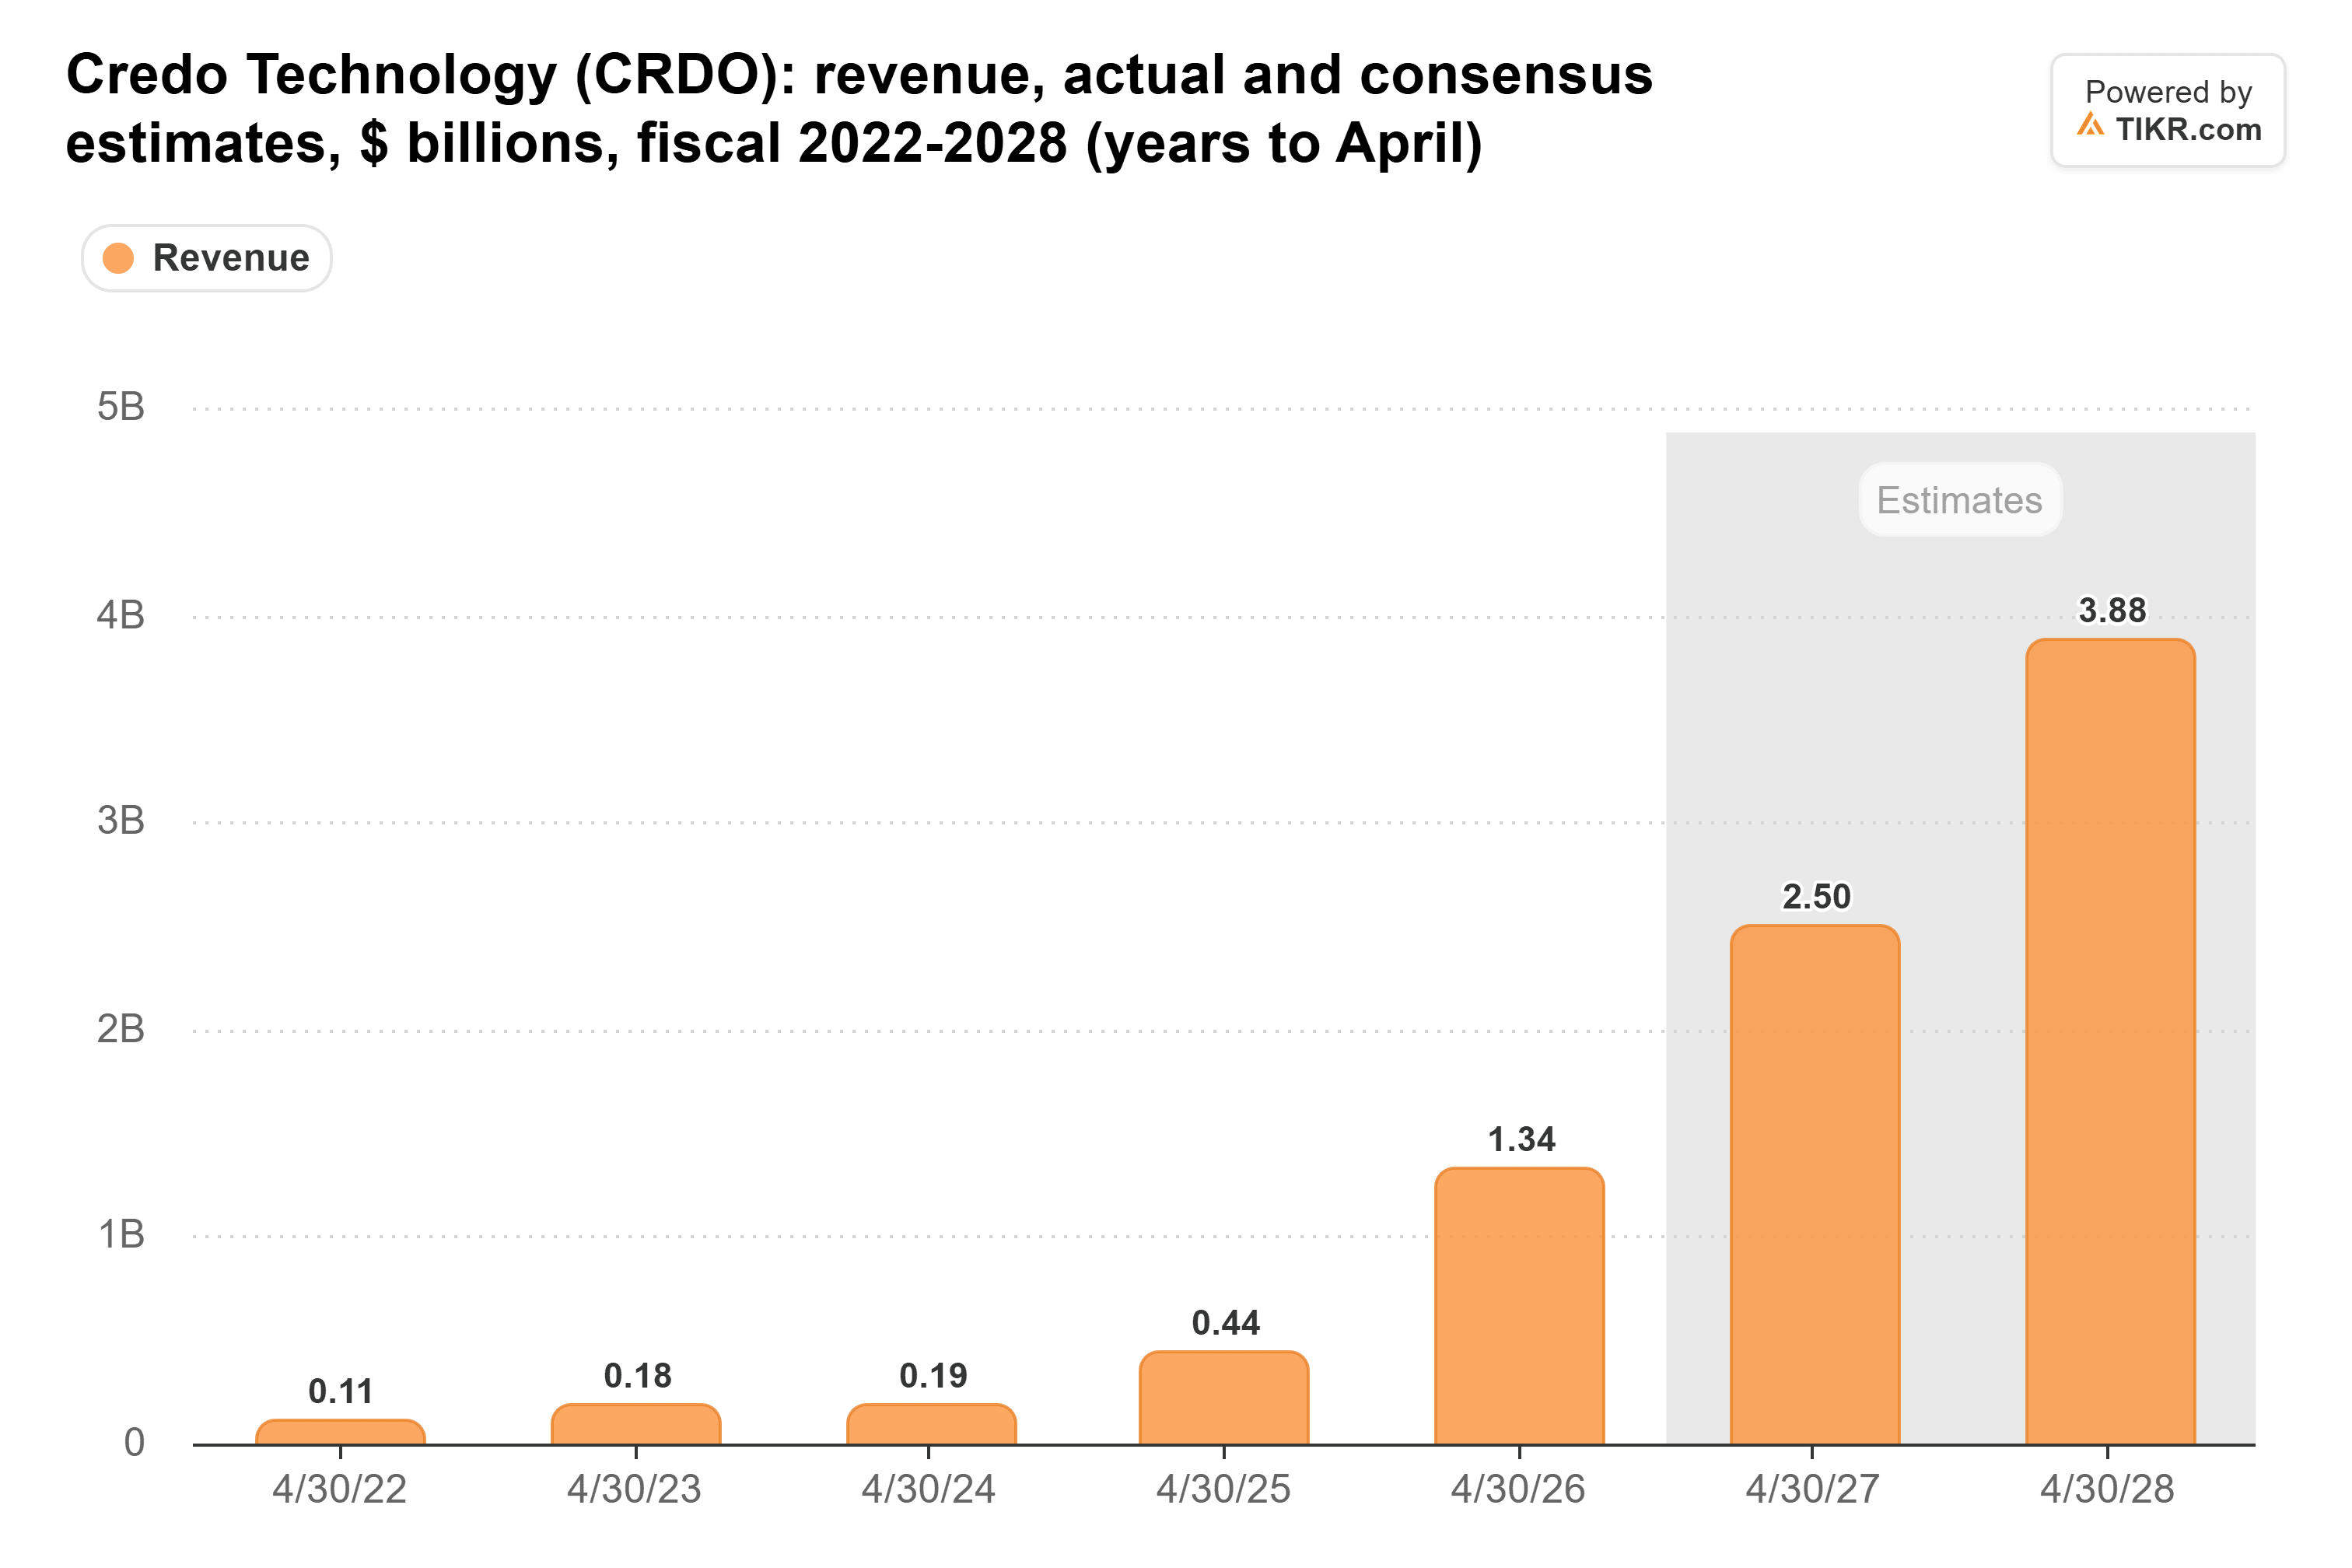
Credo has earned some benefit of the doubt: in December 2025, it guided fiscal 2026 growth of more than 170% and delivered 205.7%.
Optics is the big new piece: more than $600 million expected this fiscal year. Coherent’s revenue grew 50% to $2.37 billion in the September quarter, and CEO Jim Anderson sees AI data centers moving “from copper to optical connectivity.” Credo needs that shift: its copper active electrical cables (AECs) supplied over 99% of its revenue growth last fiscal year.
TIKR tracks 25 analysts on Astera Labs. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Astera Labs, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Astera Labs’ Analyst Ratings
Astera already showed its hand
Astera’s third-quarter revenue came in at $584.9 million, up 154%, and it guided the fourth quarter to $730 million to $750 million, 13% above consensus. Analysts have since raised their numbers, to $2.03 billion of revenue for 2026, $3.39 billion for 2027 and $4.36 billion for 2028:
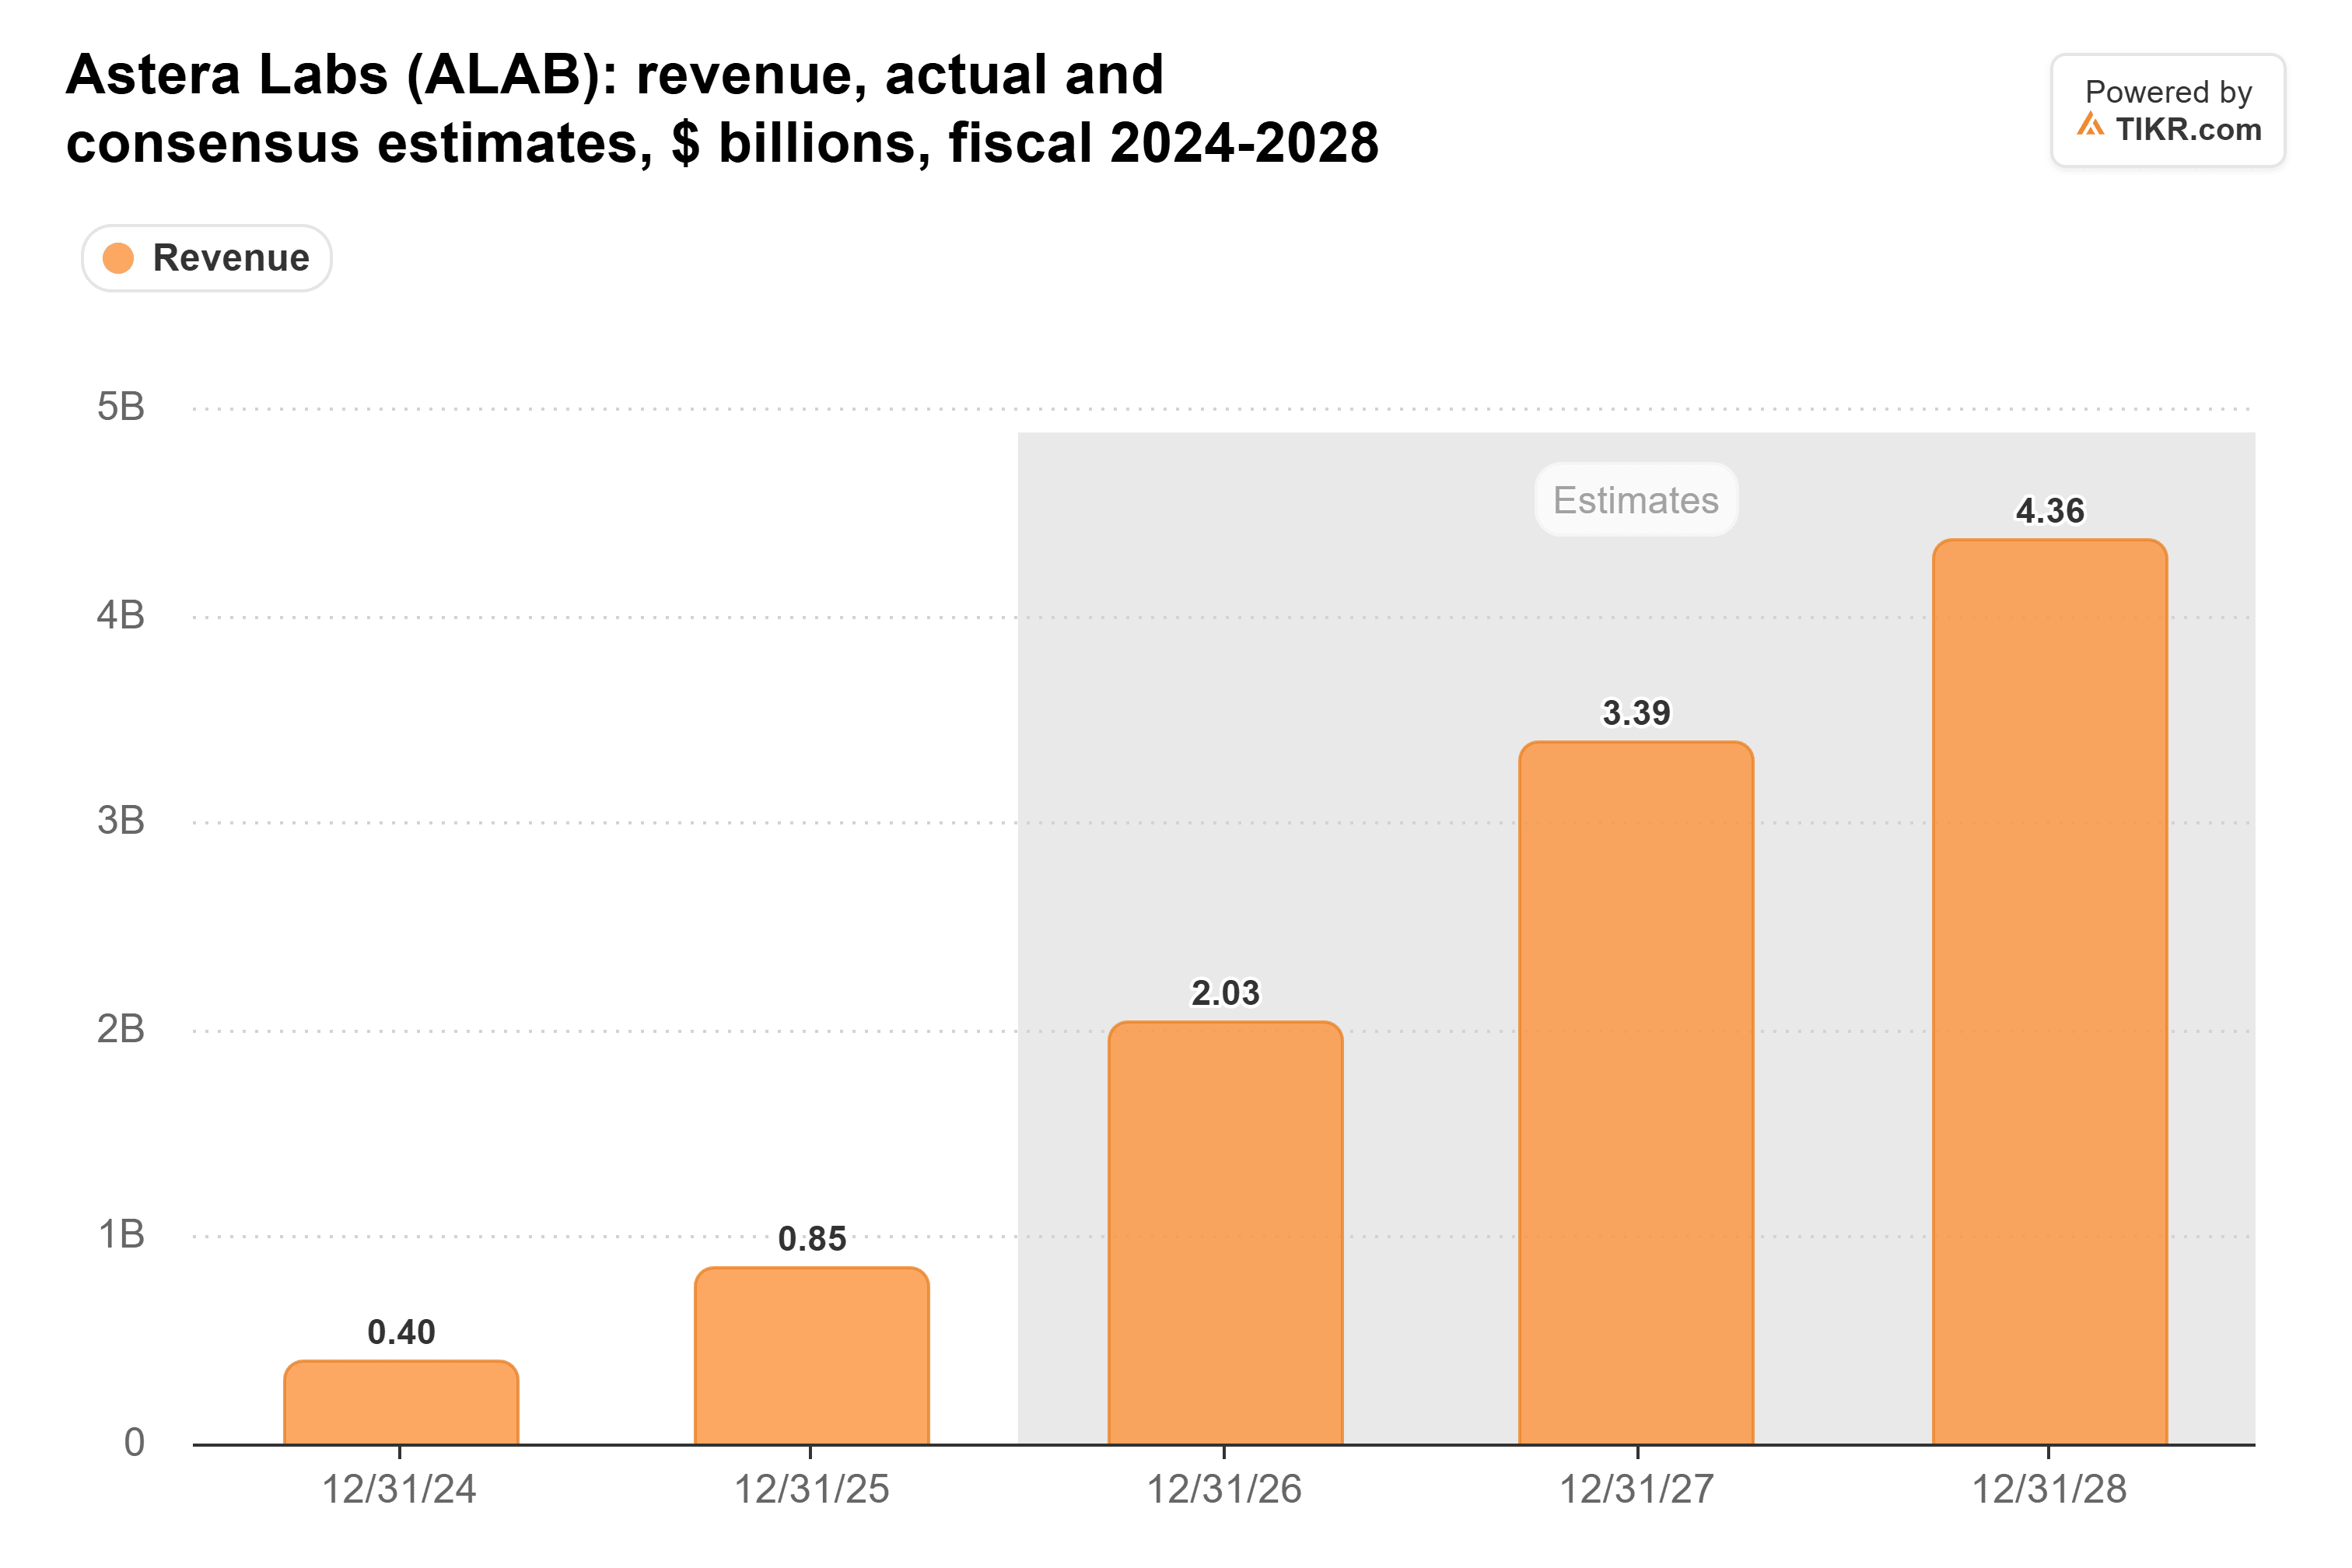
Multiply the fourth-quarter guide’s $740 million midpoint by four, and you get about $2.96 billion. So 2027’s consensus asks for about 15% more than that, a far smaller leap than Credo’s.
The catch with Astera is concentration. As Ritholtz Wealth Management’s Michael Batnick said on The Compound and Friends this week, “the reason why this is not a more popular stock is 70% of its revenue is one customer.”
Credo is priced for a miss
Credo’s stock already reflects a lot of doubt. It trades at about 17x forward earnings, near the bottom of its three-year range:
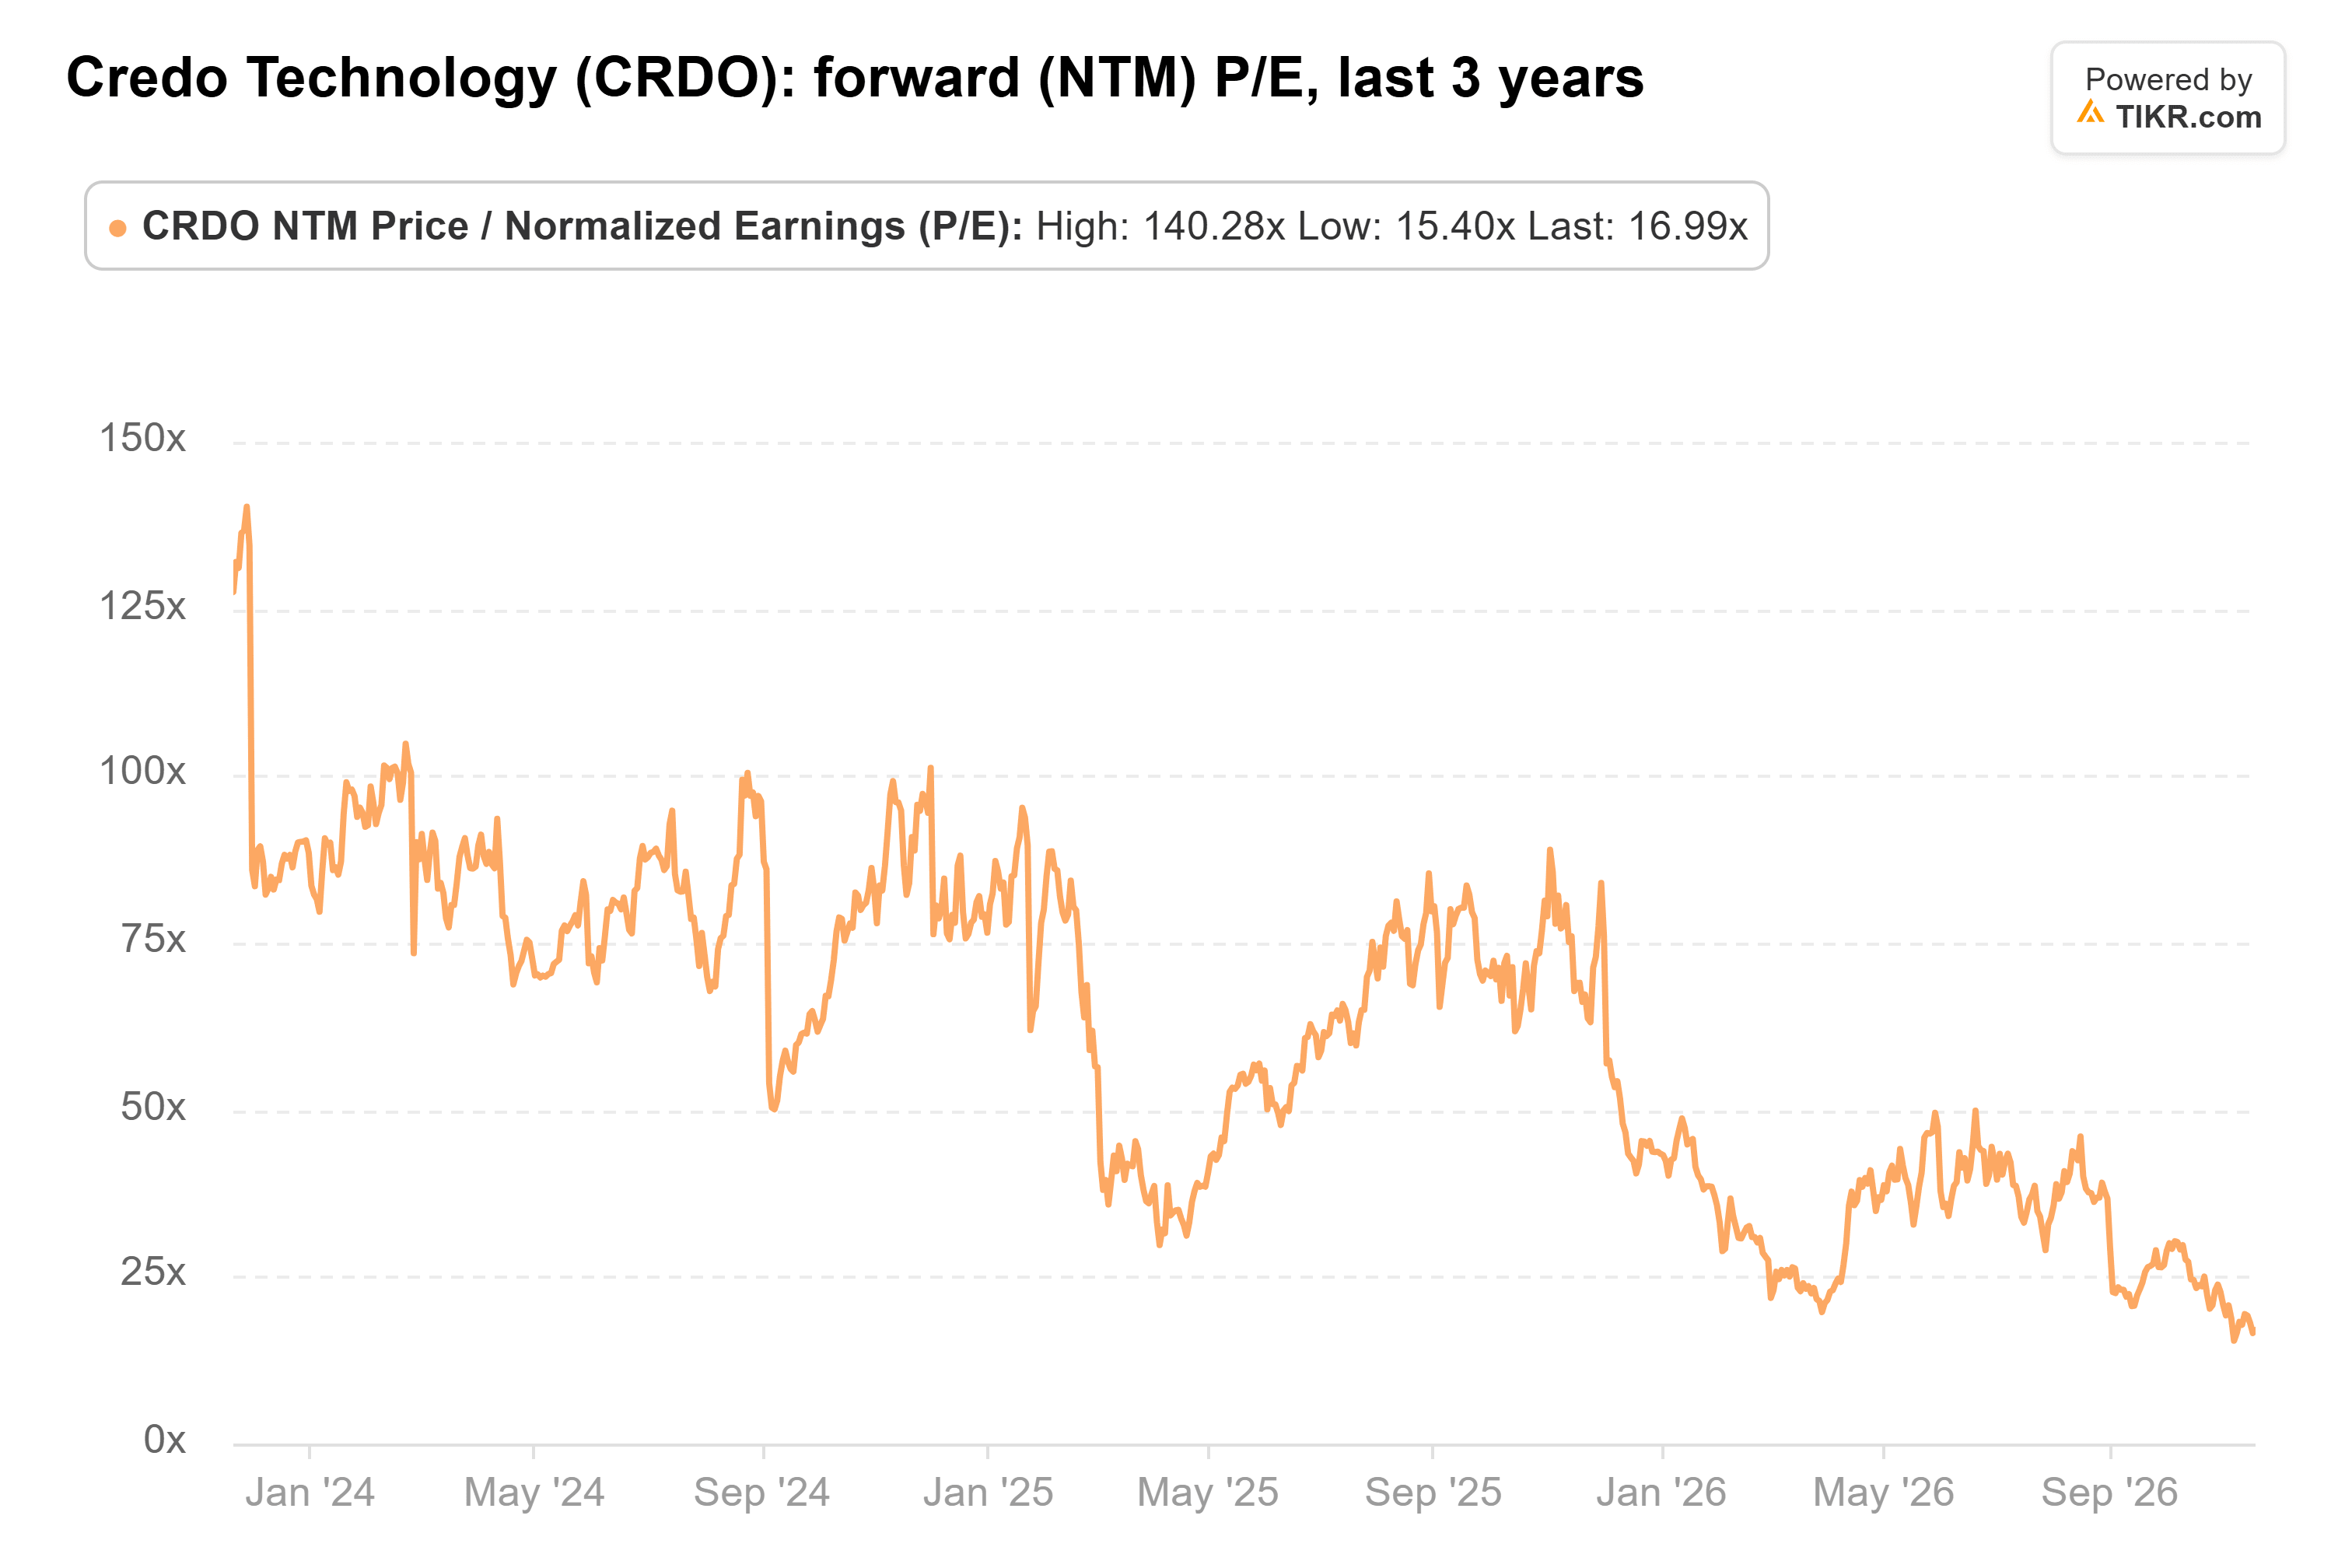
That’s well below its three-year average of 62x.
Marvell is the rival to watch on Dec. 1. If its connectivity business looks strong the same day Credo reports, it gets much harder to argue that the AI demand behind Credo’s guide has dried up.
Credo is the better setup
Credo’s risks are plain: four end customers bought 84% of its fiscal first-quarter revenue, and its CTO and COO have sold more than $45 million of stock since September.
Even so, I’d rather own Credo here. Astera’s drop came after it delivered, and one strong quarter won’t make investors forget its biggest customer. At 17x, Credo’s price leaves room for the second half to slip.
Dec. 1 is the test. If Credo guides its third quarter to only about 10% growth, as it did for the second, its fourth quarter would need roughly $875 million, and I’d stop trusting the year. A guide that keeps $1.46 billion in reach and gives optical revenue in dollars would make 17x look far too cheap.
So what is Credo Technology stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Credo Technology could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Credo Technology for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!