Key Takeaways
- ServiceNow is 42% below its high of a year ago after a weak fourth-quarter backlog guide, and Argus reiterated its Buy rating and $170 target on Nov. 3, 61% above \1.
- For $170 to work, management’s case that the soft cRPO guide comes down to timing has to hold up.
- Argus’s target works out to 37x next-twelve-months earnings, below ServiceNow’s five-year average of 53x. But analysts have cut their 2026 and 2027 EPS estimates over the past month.
- ServiceNow looks cheap enough to buy at 23x forward earnings, but I’d expect it to reach the Street’s $155 average target before Argus’s $170.
ServiceNow (NOW) is 42% below its closing high of a year ago, and its third-quarter report on Oct. 28 knocked it lower still. On Nov. 3, Argus reiterated its Buy rating and $170 price target, 61% above \1.
AI fears, debt and a soft guide
In February, software stocks fell as much as 17% in six sessions on fears that AI agents would replace the human seats ServiceNow charges for.
ServiceNow spent $8.8 billion on Armis and Veza this year, turning $8.6 billion of net cash at the end of 2025 into $810 million of net debt by June 30.
On Oct. 28, ServiceNow raised its full-year outlook, but it guided fourth-quarter cRPO growth to 18.5% in constant currency, below the roughly 19.8% analysts expected.
Argus held its ground
Argus raised its target to $170 from $134 on Oct. 7 and kept it there after the results.
For $170 to work, the cRPO guide has to be about timing, as management says. President and CFO Gina Mastantuono said early renewals pulled into the third quarter made up about half of its cRPO beat, which leaves the fourth quarter short. “cRPO is a very nuanced accounting metric, and it doesn’t necessarily capture all of the momentum in the business,” she said on the call.
TIKR tracks 49 analysts on ServiceNow. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on ServiceNow, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See ServiceNow’s Analyst Ratings
Does $170 add up?
Analysts’ average target was $231 a year ago, bottomed at $139 in late July, and sits at $155 now.
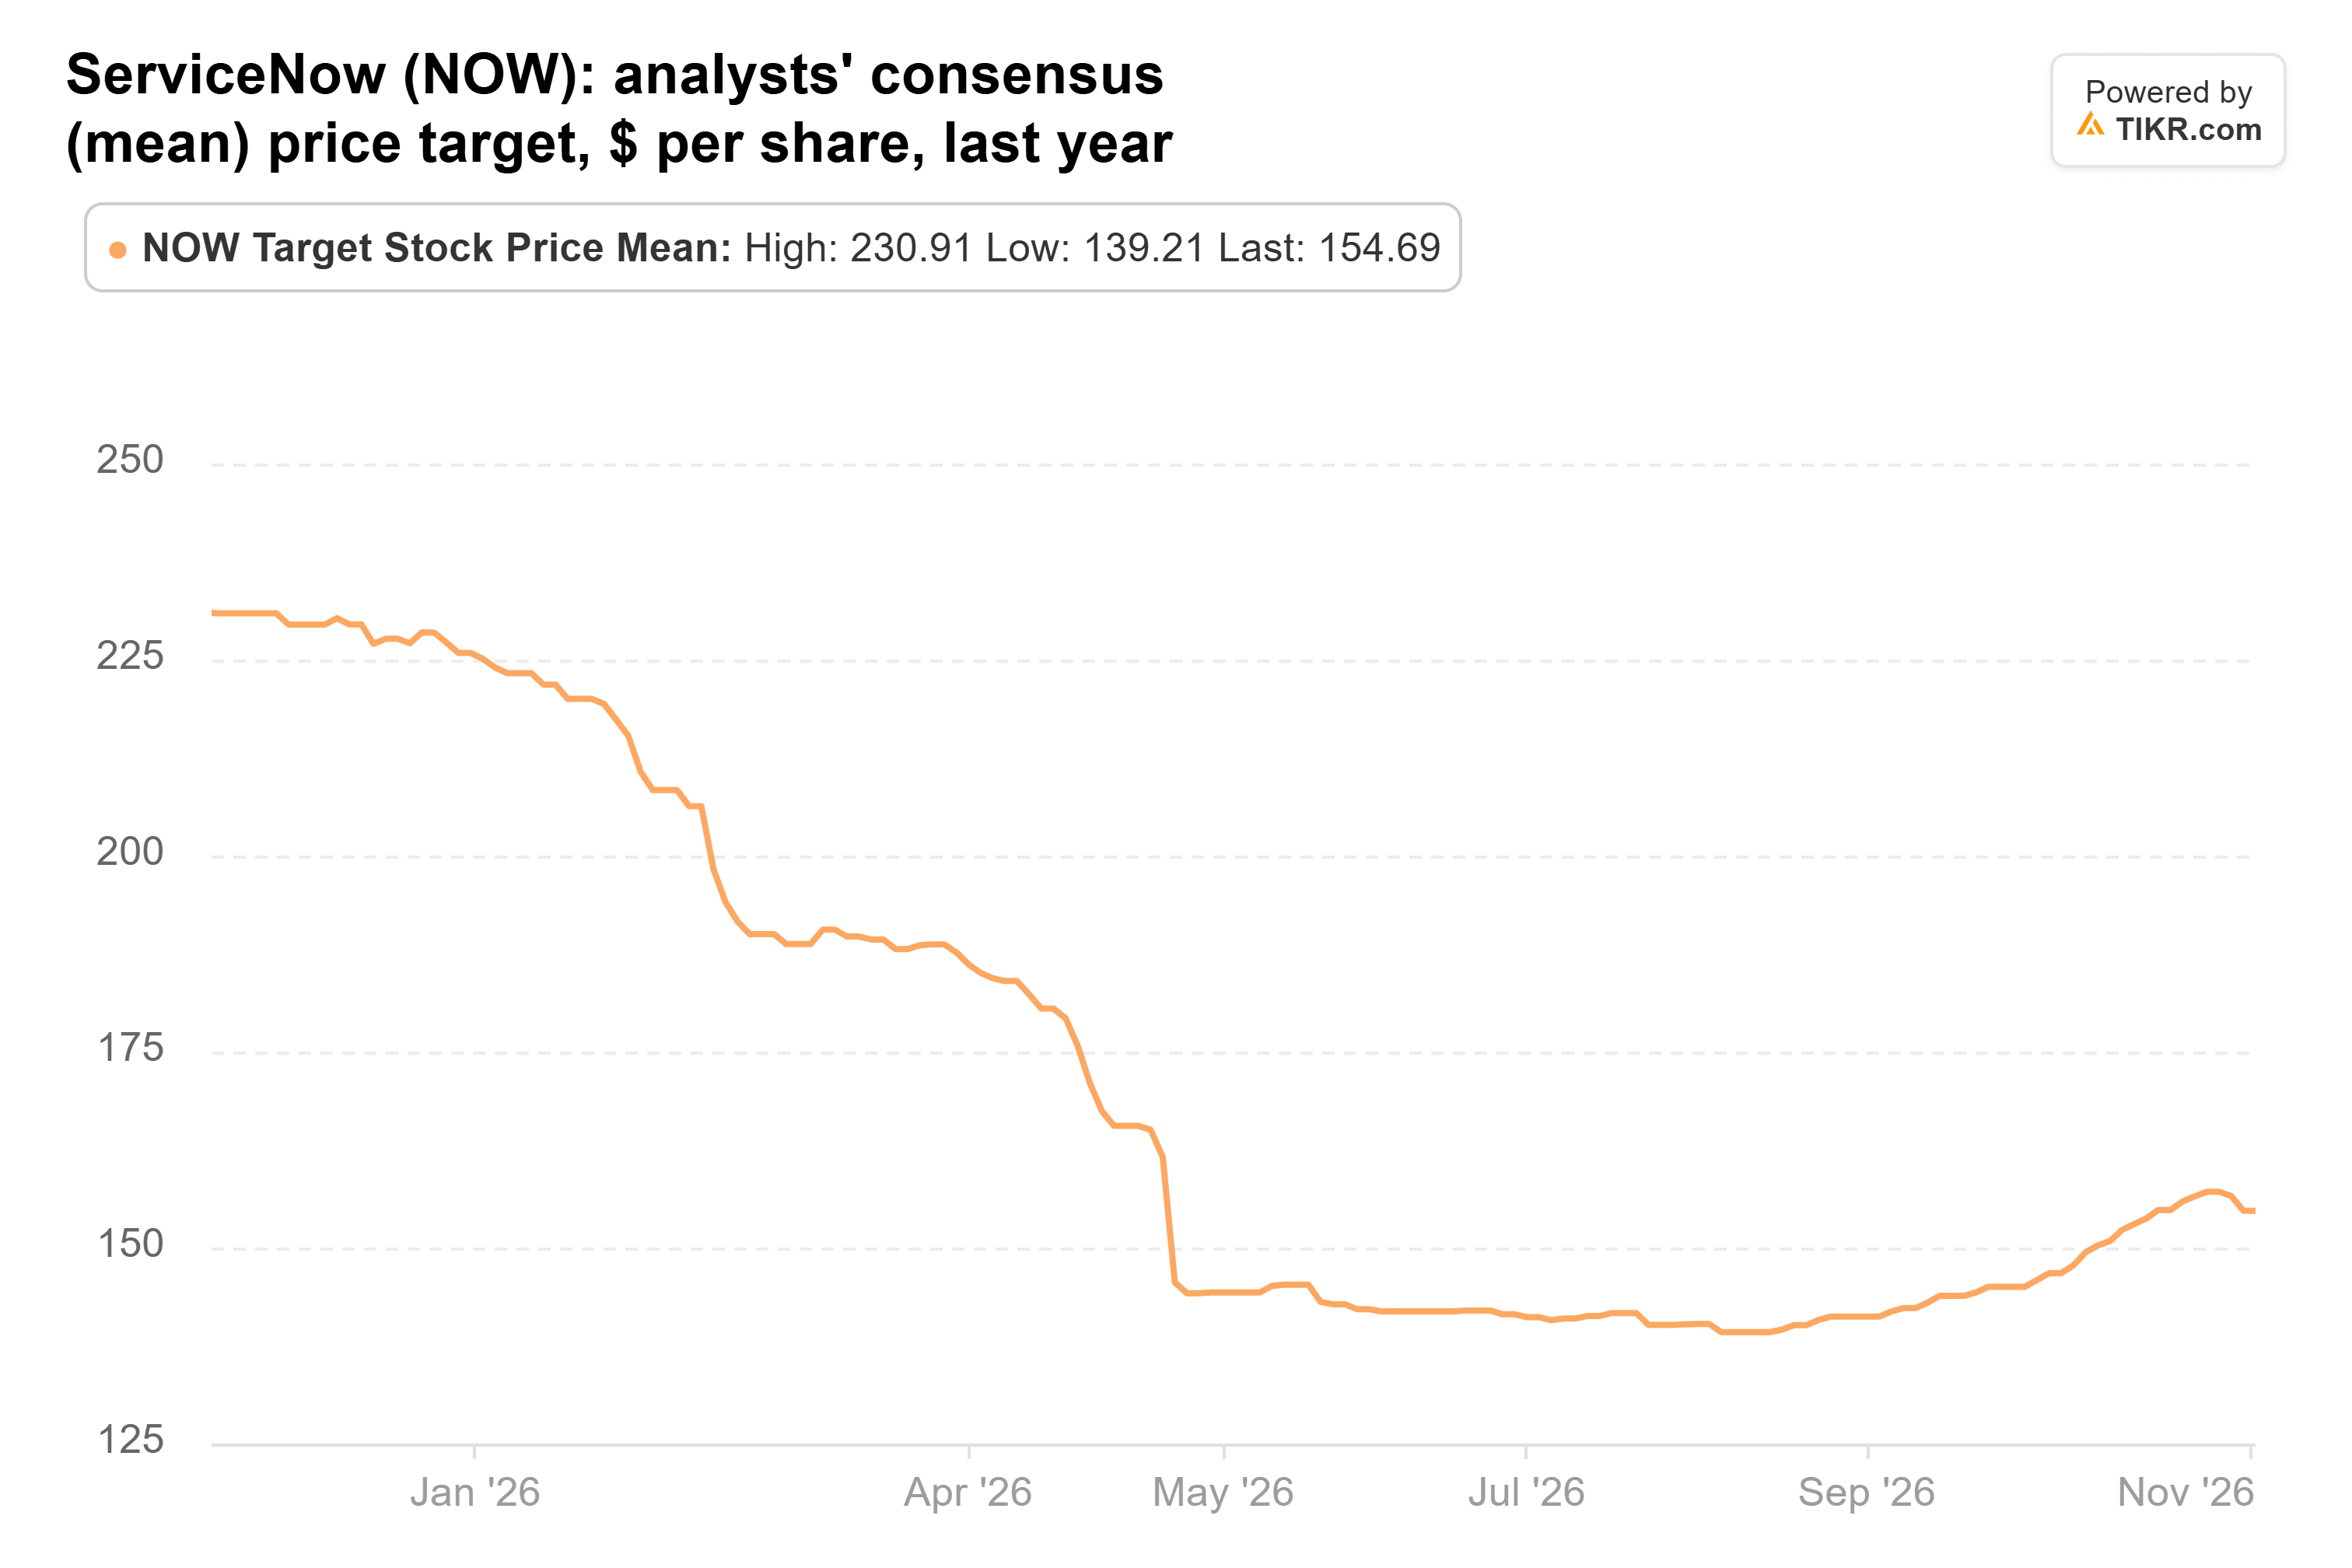
Argus’s $170 is 10% above that, and targets run from $72 to $266.
Analysts expect EPS to climb from $3.51 in 2025 to $5.89 in 2028.

But those numbers are moving the wrong way. Over the past 30 days, analysts cut their 2026 estimate to $3.95 from $4.07, and their 2027 estimate to $4.80 from $5.01.
The stock trades at 23x forward earnings, near its five-year low.

Argus’s $170 works out to 37x the $4.54 a share analysts expect over the next twelve months. That’s well below the five-year average of 53x, though 2021’s 104x peak pulls that average up.
Buy it, but plan on $155
If AI agents cut seats faster than AI consumption grows, the estimates keep falling, and the new debt leaves less room for error.
At 23x, ServiceNow is cheap for a business growing subscription revenue 21%, and I’d buy it on this drop. But with estimates still falling, I’d expect the stock to reach the Street’s $155 well before Argus’s $170.
ServiceNow gives its first 2027 guide with its fourth-quarter report in late January. If constant-currency subscription growth comes in at 20% or more, $170 looks a lot more reachable.
So what is ServiceNow stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ServiceNow could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!