Key Takeaways
- Shopify shares fell 12% after its third-quarter GMV of $119.1 billion came in less than 1% below what analysts expected.
- Revenue grew 32% and operating income rose 66%, and the company expects fourth-quarter revenue growth at or above what analysts expected.
- GMV growth slowed to 29% from 32% in the second quarter, and GMV is the base that Shopify’s revenue is built on.
- The stock still prices in years of fast earnings growth, so it makes sense to wait for a lower multiple before buying.
Shopify (SHOP) reported its third quarter before the open this morning, and shares fell 12%.
The problem was gross merchandise volume. GMV came in at $119.1 billion, below the $120.1 billion analysts expected. That’s a miss of less than 1%.
Which shows how little room for error there is at this valuation.
The rest of the quarter held up
Besides GMV, the quarter gave investors little to complain about:
- Revenue of $3.74 billion, up 32% and in line with expectations
- Operating income of $568 million, up 66%
- Free cash flow of $816 million, a 22% margin (up from 18% a year ago), well ahead of the $723 million analysts expected
- GMV of $119.1 billion, up 29%
The outlook was fine too. Shopify expects fourth-quarter revenue to grow at a low-thirties rate, at or above the roughly 30% analysts had expected, with operating expenses at 29% to 30% of revenue.
But investors have gotten used to more than fine. In each of the three quarters before this one, Shopify grew revenue faster than the top of its own guidance: 31%, 34% and 34%. This time, 32% landed inside its low-thirties guide.
GMV is the number to watch
GMV growth slowed to 29% from 32% in the second quarter. Revenue held up better because Shopify keeps taking a bigger cut of each order, mostly through payments: merchant solutions revenue rose 35%.
But revenue can only grow faster than GMV for so long. If growth in merchants’ sales keeps slowing, Shopify’s revenue growth will slow with it. That’s why such a small miss still counts.
TIKR tracks 54 analysts on Shopify. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Shopify, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Shopify’s Analyst Ratings
Still a premium price
Going into the report, analysts expected Shopify’s normalized EPS to climb from $1.91 this year to $3.36 in 2028, about 33% a year:
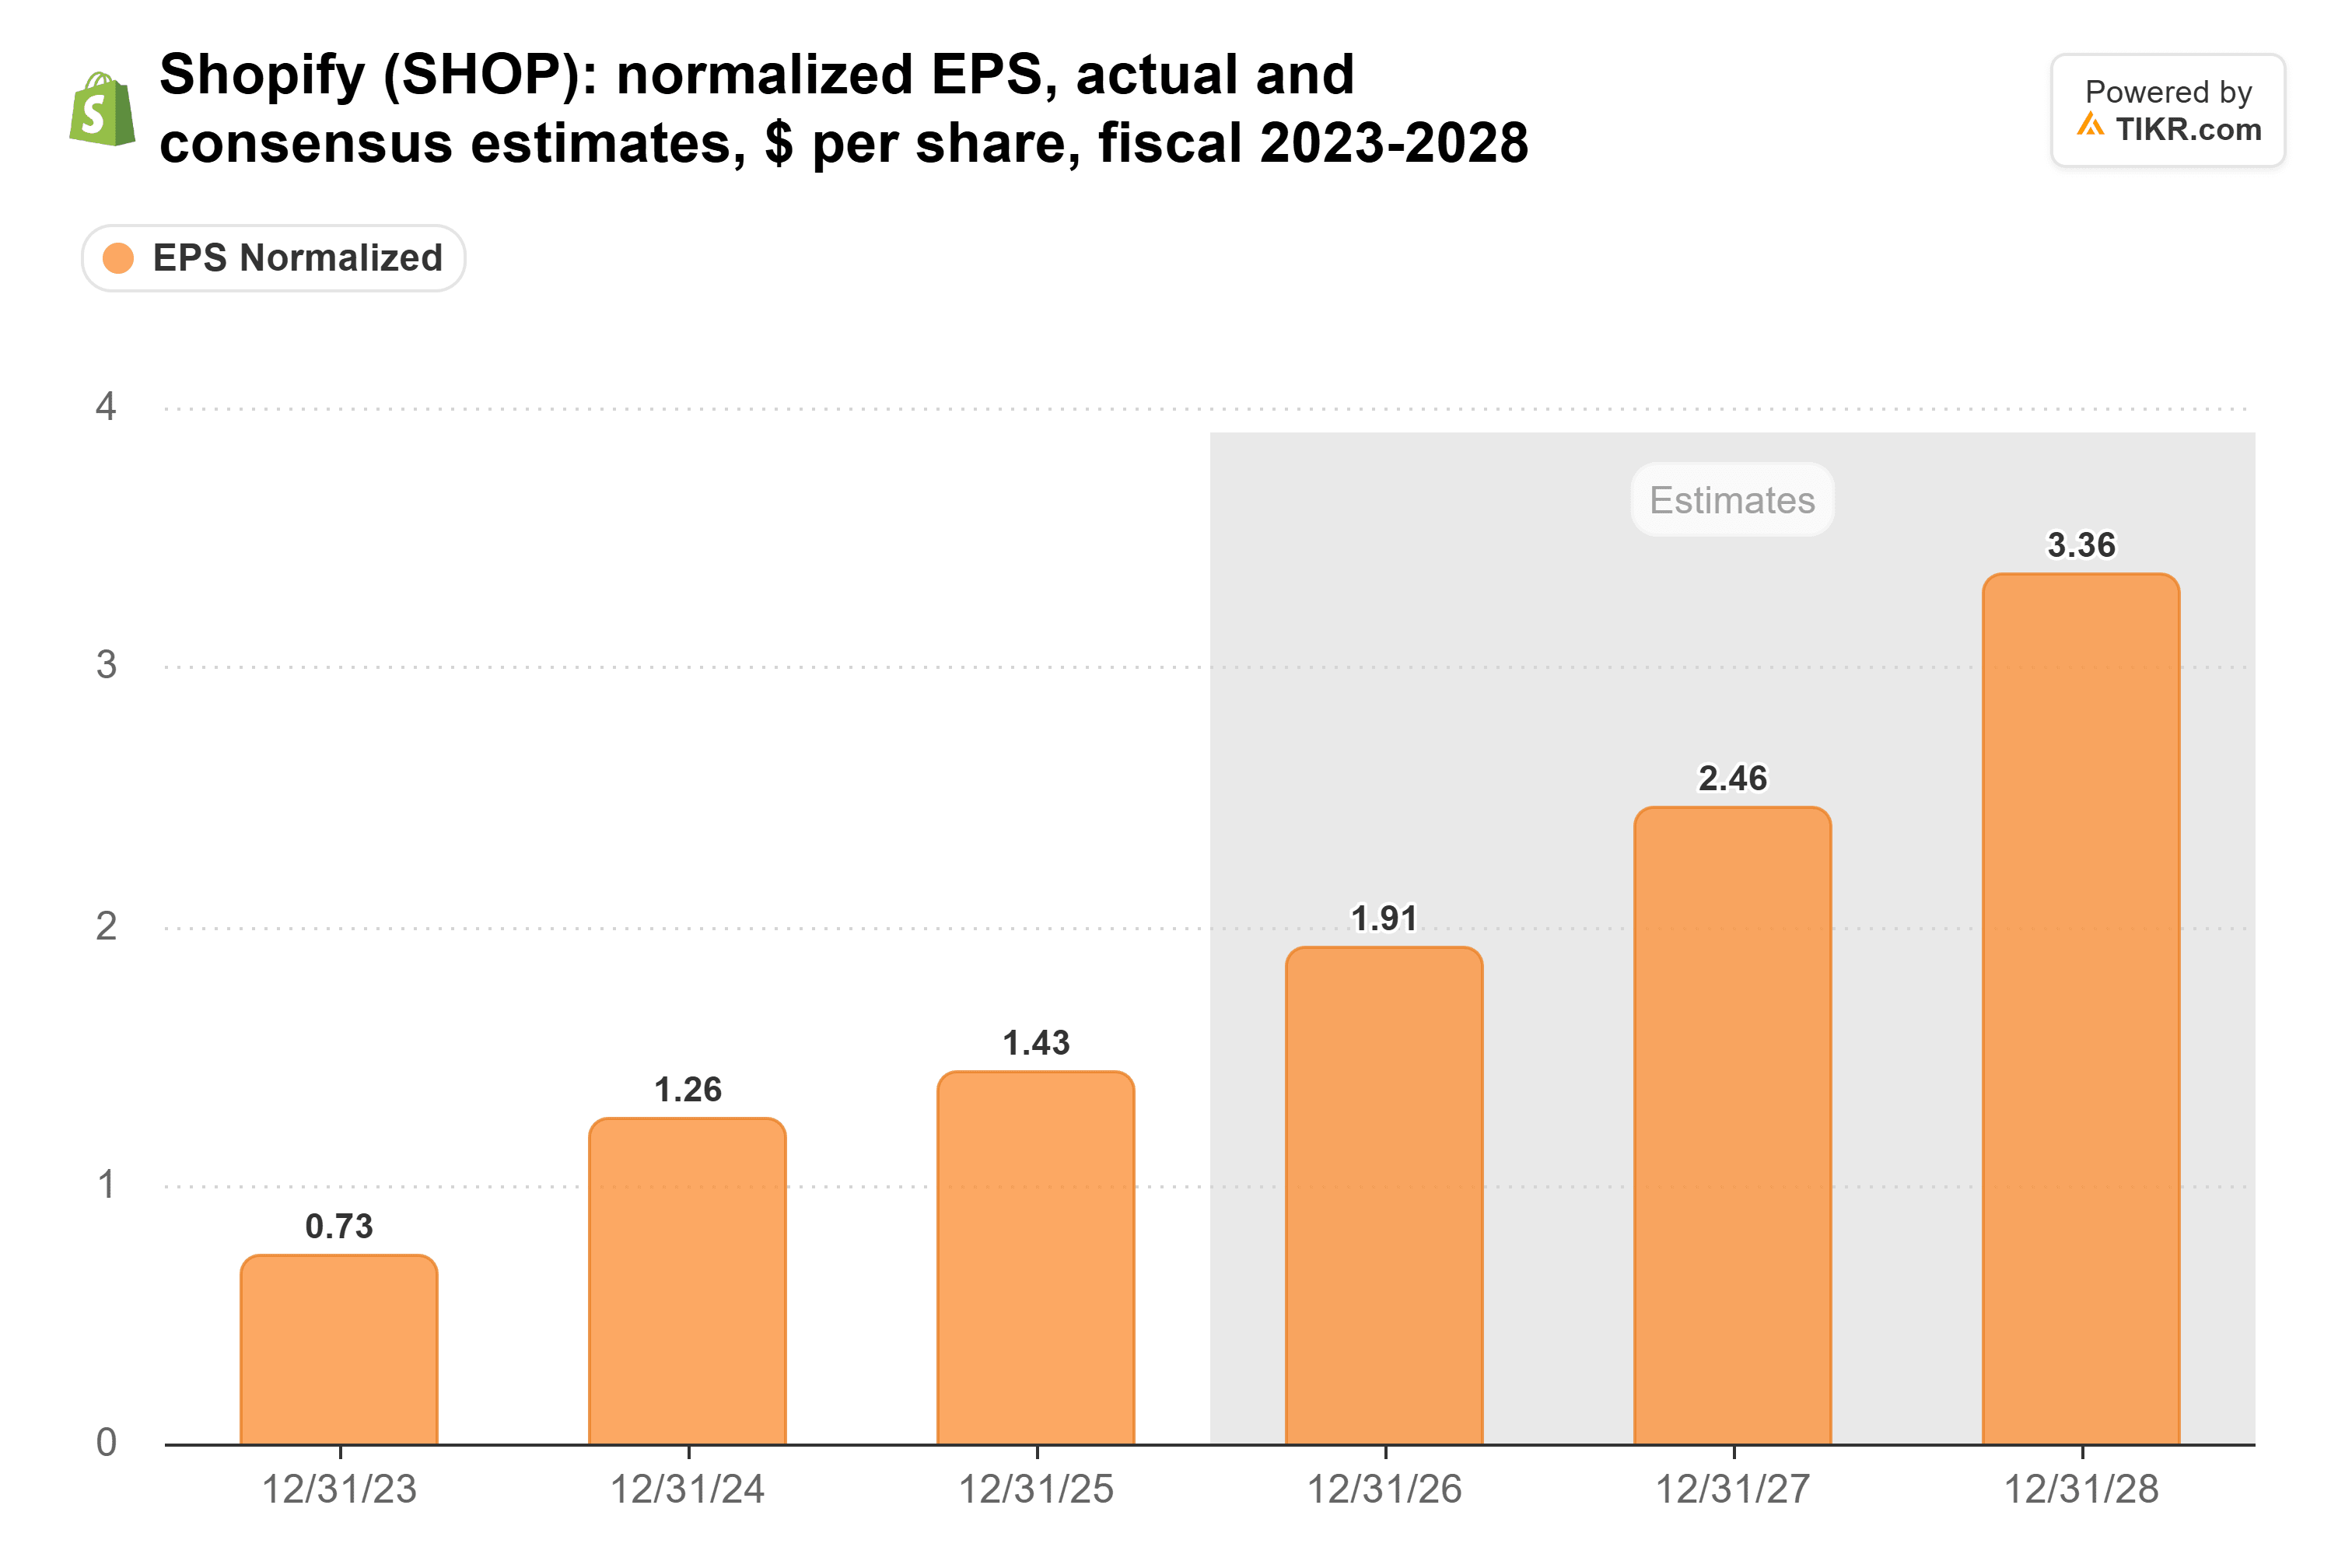
Nothing in this quarter should push those estimates down much: revenue was in line, and free cash flow beat.
Investors are paying for that growth. At yesterday’s close, Shopify traded at 74x forward earnings, right at its three-year average, and at about 64x the 2027 estimate. Over the last three years, the forward multiple has been as low as 60x (at the end of June) and as high as 96x (at the end of 2025).
Today’s drop brings it down, but Shopify still trades at more than 50x 2027 earnings.
Wait for 45x
For me, Shopify still isn’t cheap enough to buy. Analysts already expect revenue growth to slow to 26% in 2027, from 32% this year. At more than 50x 2027 earnings, the stock needs Shopify to keep beating its own guidance, and this quarter showed what happens when it doesn’t.
I’d get interested closer to 45x 2027 earnings. If analysts are right about 2028, that works out to about 33x that year’s EPS. That price would still make sense if growth slows the way the estimates expect.
Of course, the fourth quarter could change that. Shopify reports again in mid-February, and if GMV growth gets back above 30%, today’s sellers may regret it.
So what is Shopify stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Shopify could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!