Key Takeaways
- UBS kept its Buy rating on Pinterest after a third-quarter revenue miss and only trimmed its target to $32 from $33, 61% above the stock’s price.
- The math behind $32 works, but the stock likely needs revenue growth to pick back up before it gets there.
- Revenue growth slowed to 12% from 18% as new European rules pushed cross-border sellers to pull back, and the fourth-quarter guide calls for 8% to 12%.
- UBS’s target works out to about 14x expected earnings over the next year, against a five-year average of 24x, and the 2027 outlook in early February is the next test.
Pinterest (PINS) is down 39% over the past year, and its third-quarter report set off a round of target cuts. UBS barely budged. On Oct. 30, it kept its Buy rating and trimmed its target to $32 from $33, 61% above the stock’s $19.91 price.
Europe’s new rules hit harder than expected
The trouble started in February, when management said US tariffs had large retailers pulling back. In September, management warned about its international business.
Then third-quarter revenue grew 12% to $1.17 billion, below management’s own range and down from 18% in the second quarter. CEO Bill Ready put about 3 points of that slowdown on cross-border sellers pulling back after Europe ended its duty exemption for low-value imports.
“The regulatory impact was greater than we anticipated,” Ready said on Pinterest’s third-quarter call.
Europe’s revenue was flat at $193 million, and the fourth-quarter guide calls for just 8% to 12% growth.
TIKR tracks 39 analysts on Pinterest. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Pinterest, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Pinterest’s Analyst Ratings
UBS stood apart
Others cut far harder the same day: Wells Fargo to $23 from $31, Barclays to $24 from $31, and Mizuho to $25 from $32.
For $32 to work, management’s plan has to deliver on four things:
- The US and Canada keep carrying the business (revenue there grew 14% to $894 million in the quarter).
- Europe steadies: Ready said core European enterprise growth is back above its second-quarter pace so far this quarter.
- The cross-border sellers return. “We do expect these sellers to adapt over time,” Ready said.
- Margins hold, with management still guiding to an adjusted EBITDA margin of about 30% for 2026.
Does $32 add up?
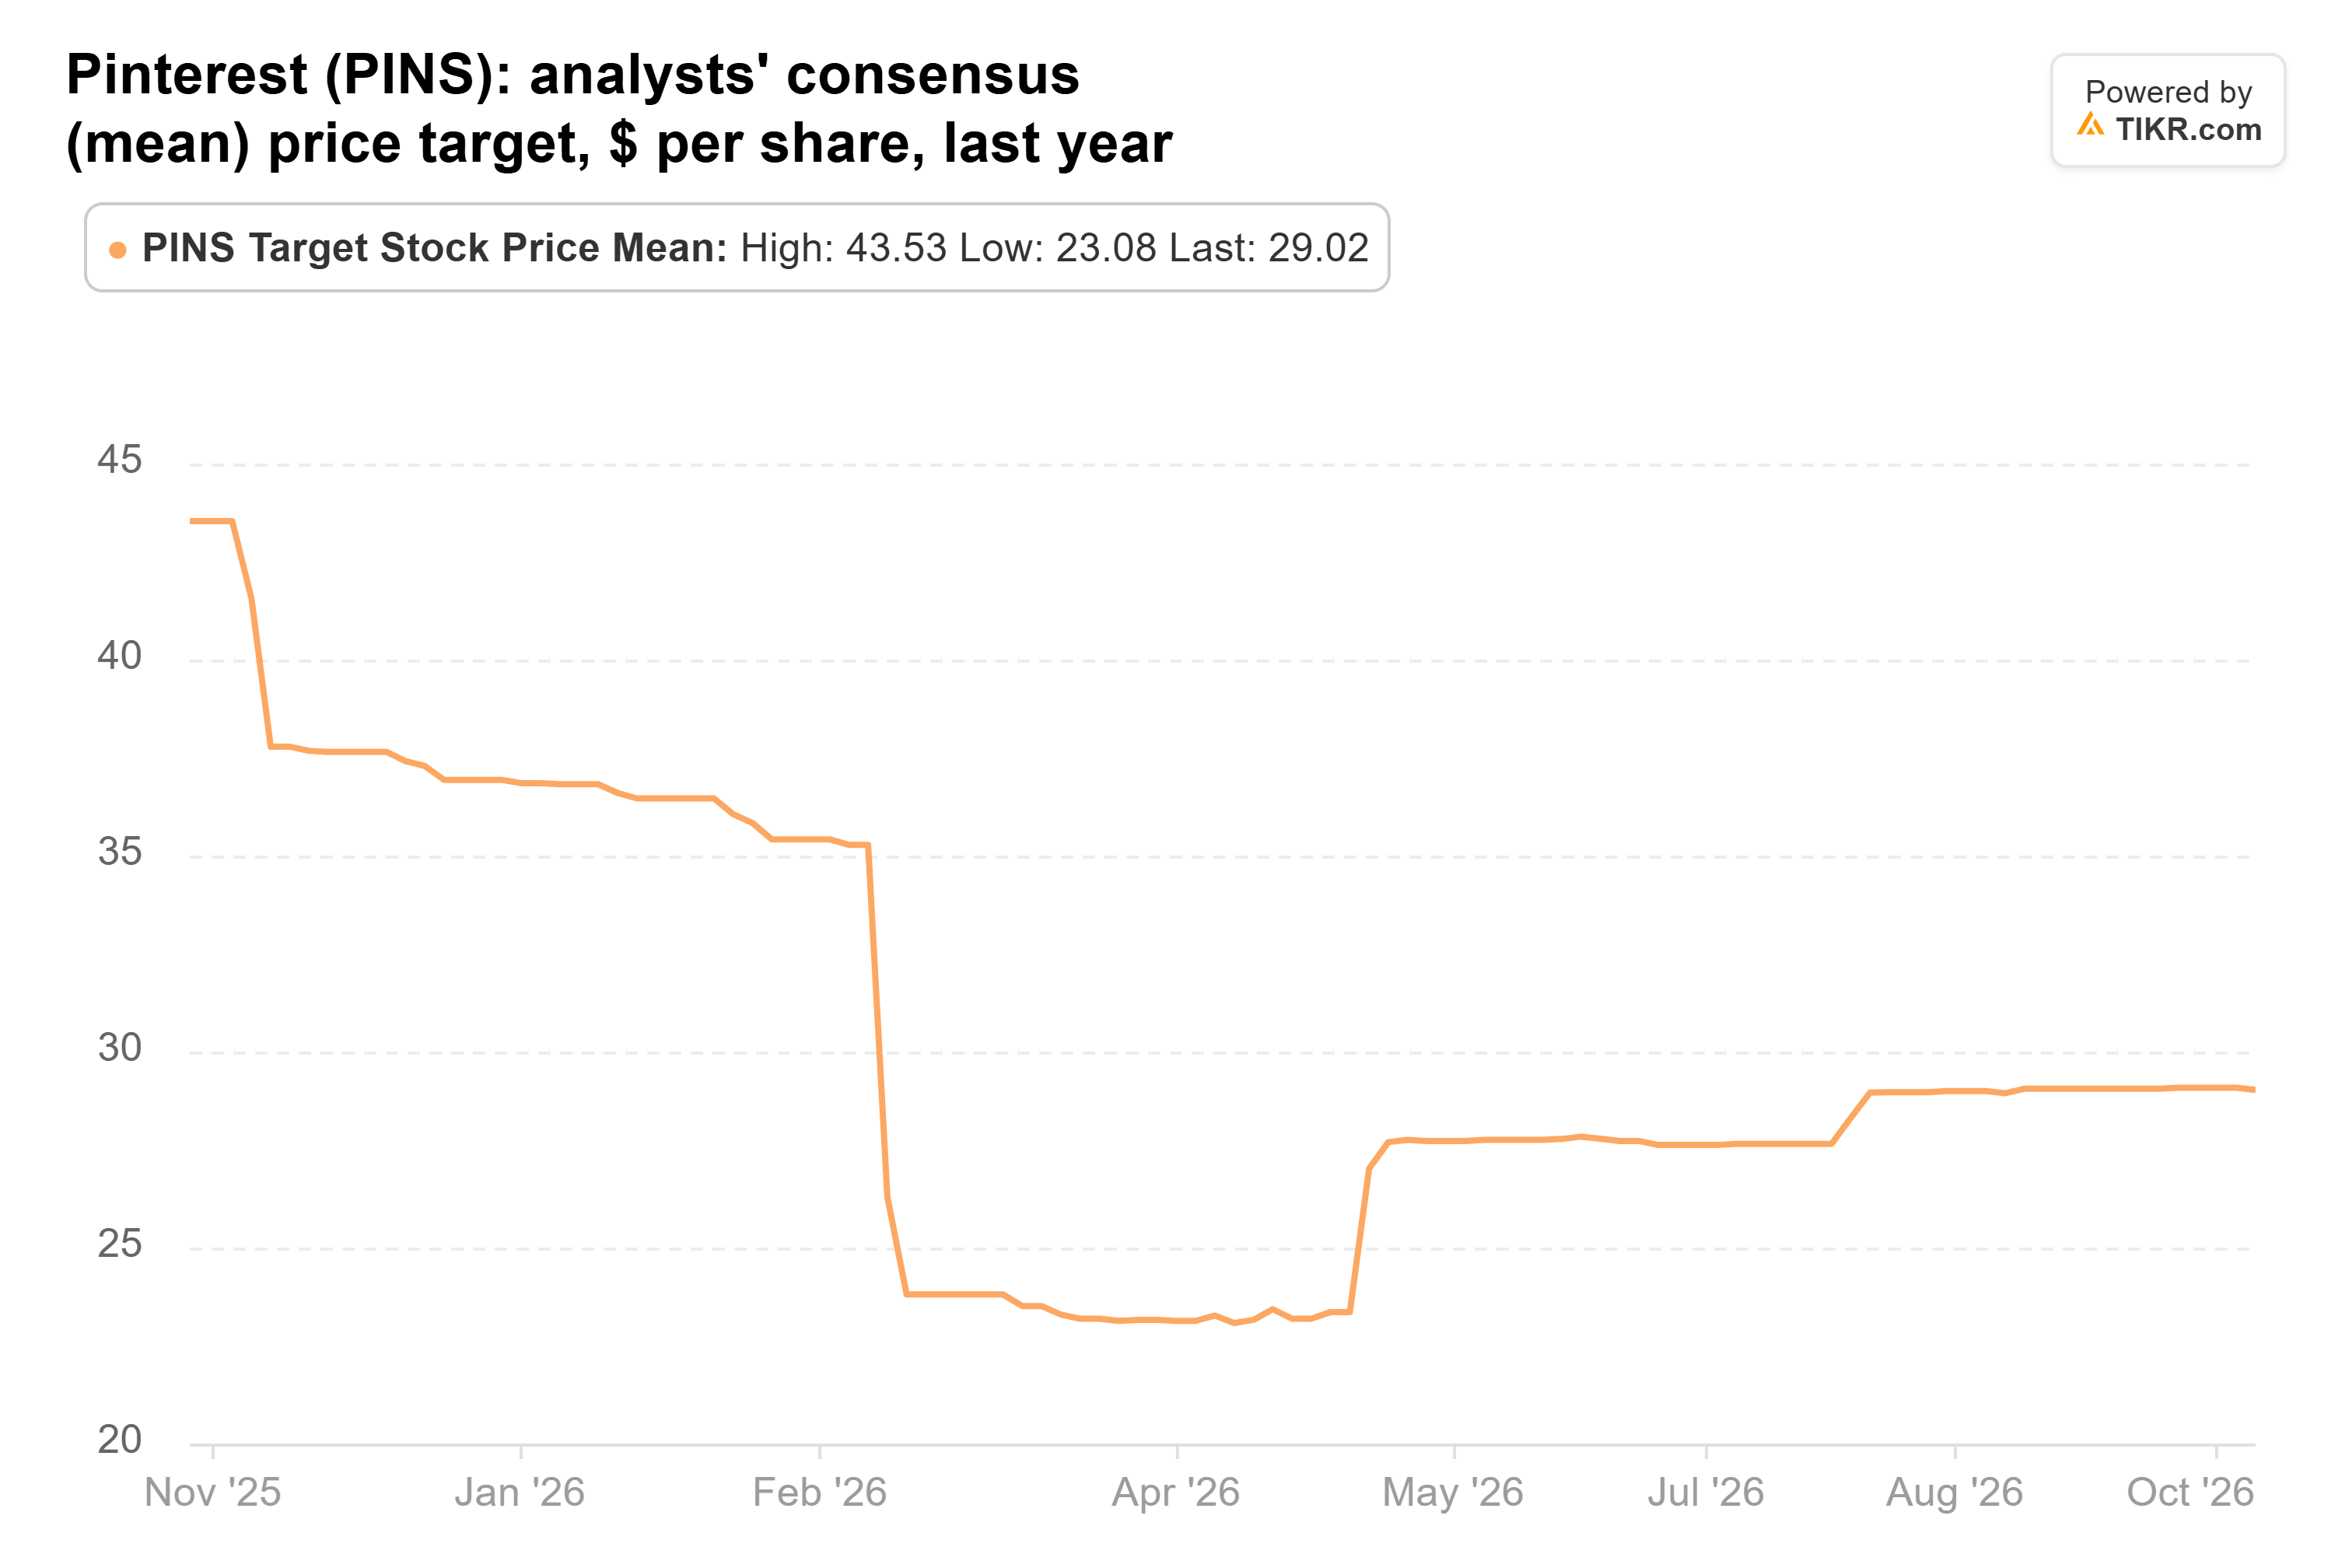
Heading into the report, the consensus target from the 39 analysts covering Pinterest was $29, against $44 a year earlier, with targets from $22 to $42:
Earnings estimates have held up better. Analysts expect normalized EPS to climb from $1.60 in 2025 to $2.39 in 2027 (helped by a buyback that cut the share count 15% in the first half of 2026):
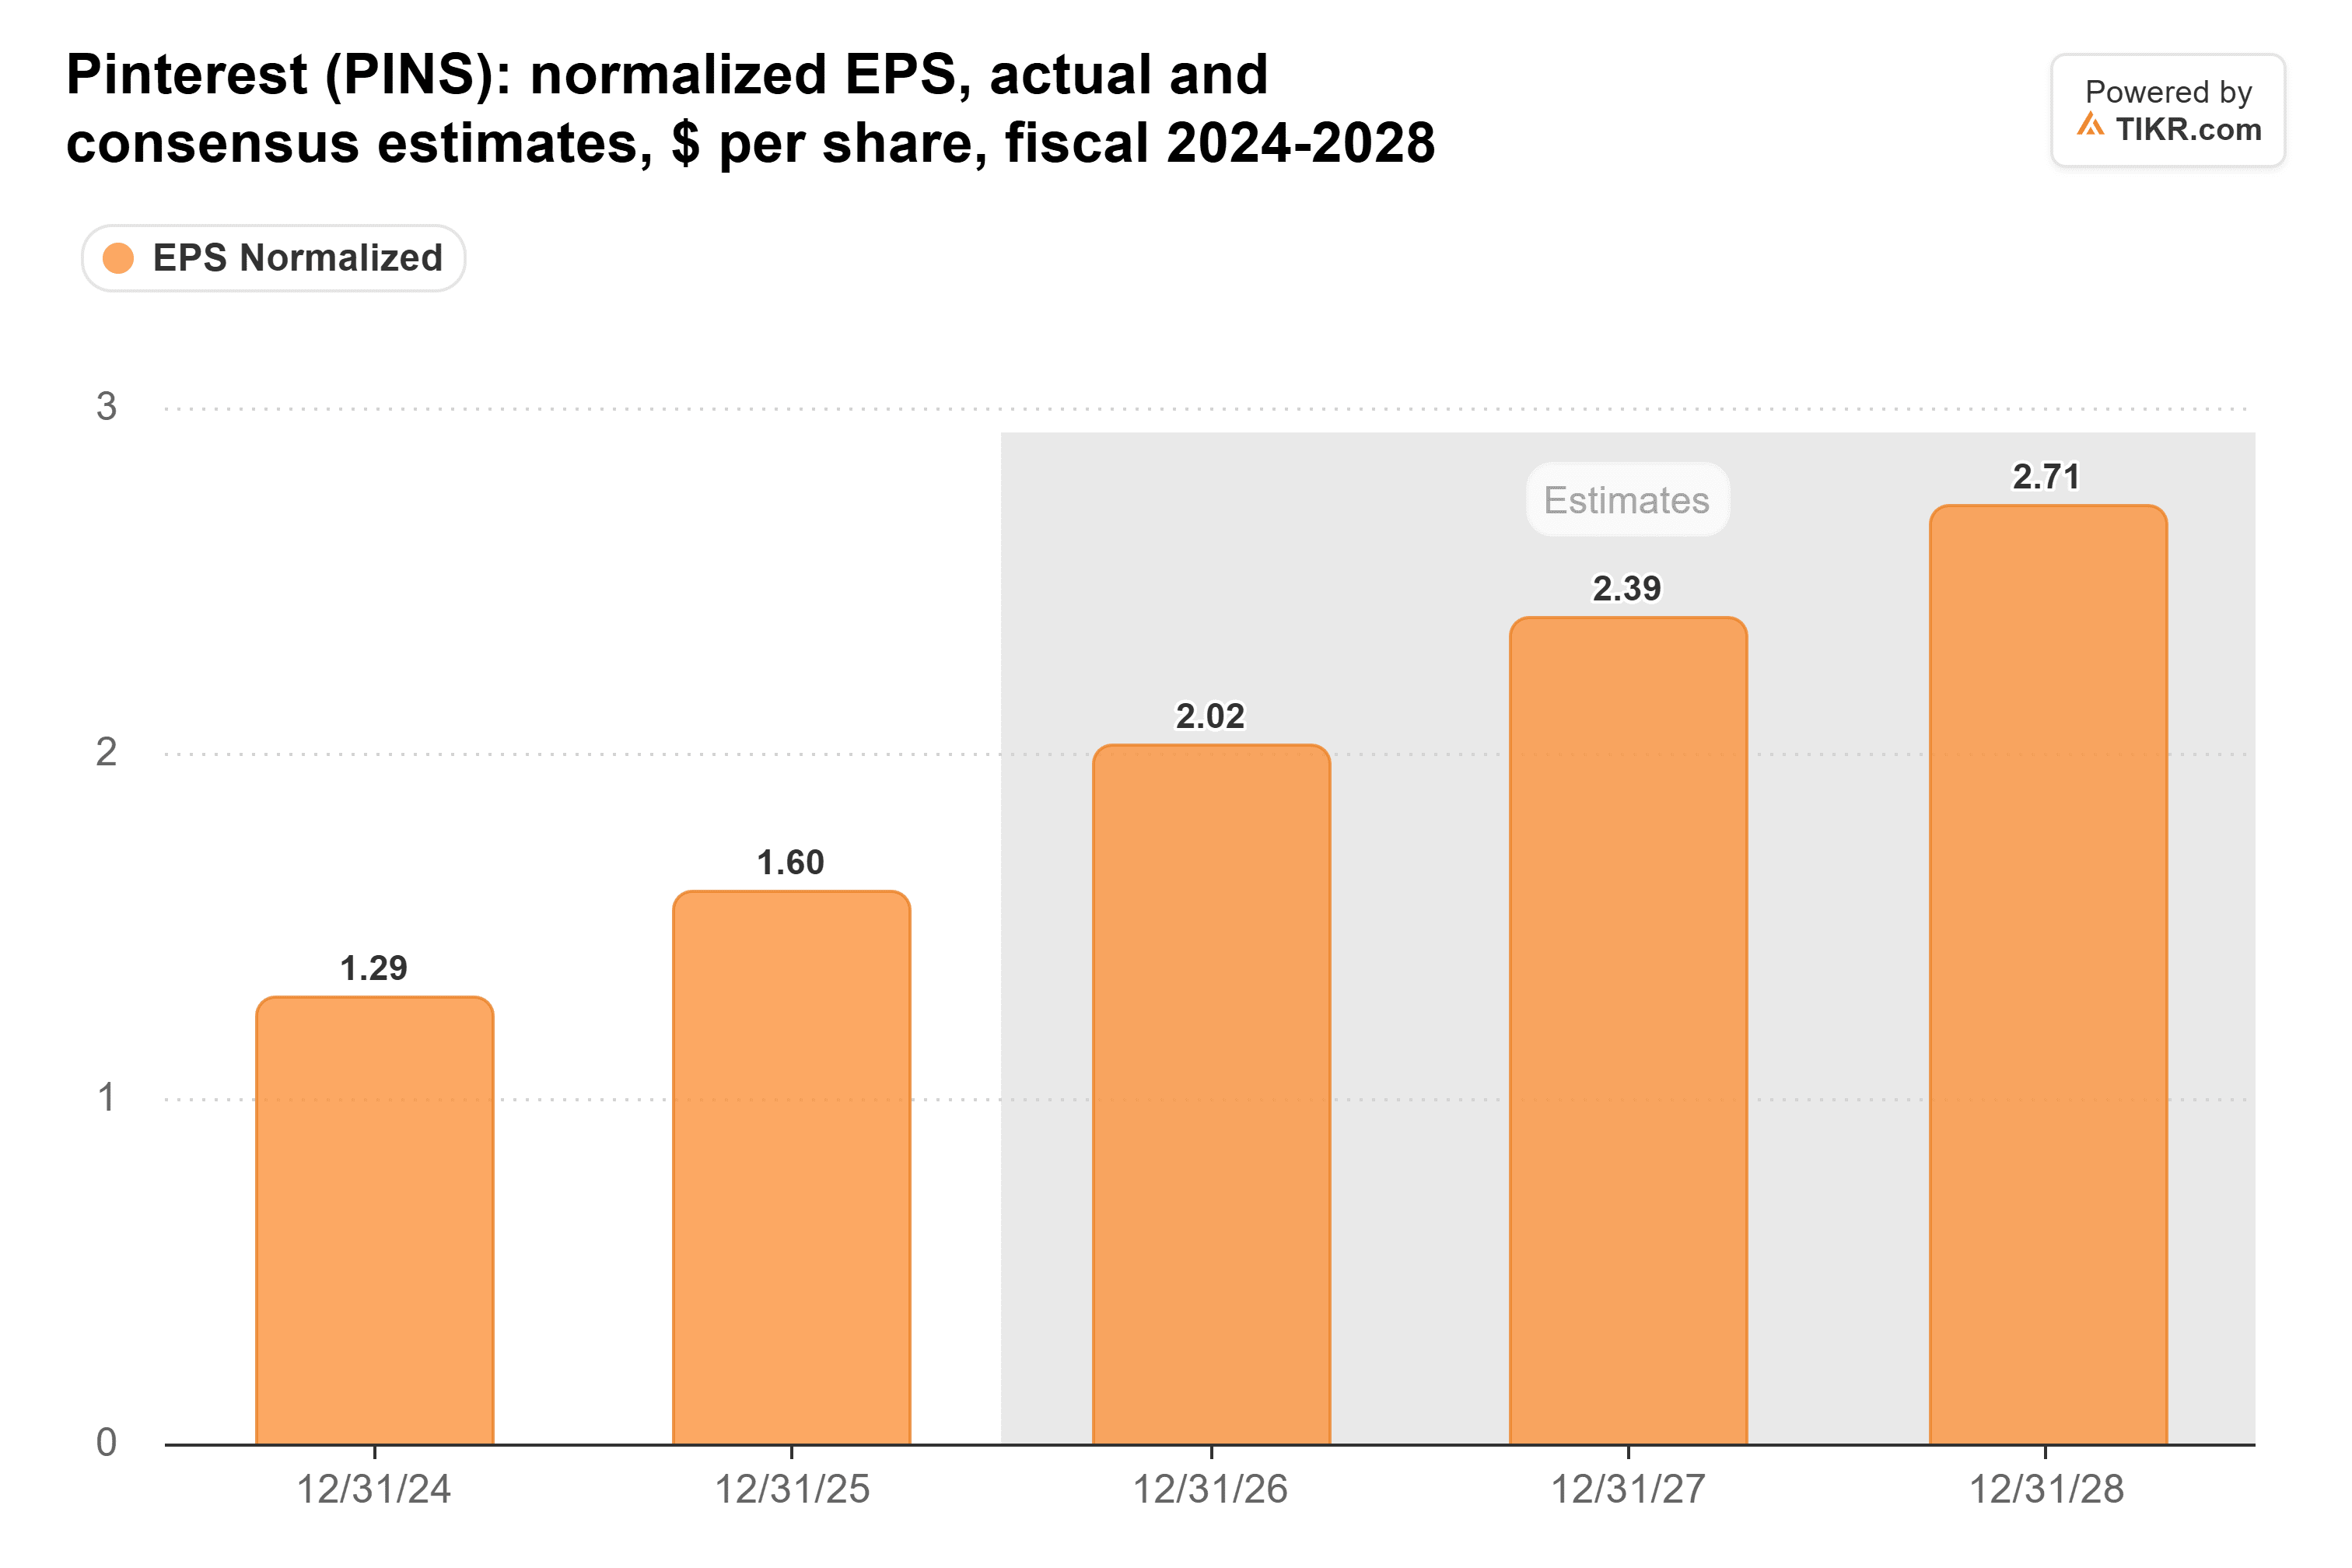
The weaker revenue guide could trim those numbers, but with the margin target intact, I’d expect modest EPS cuts.
The stock trades at [8.8x] forward earnings, near its five-year low and far below its 24x average:
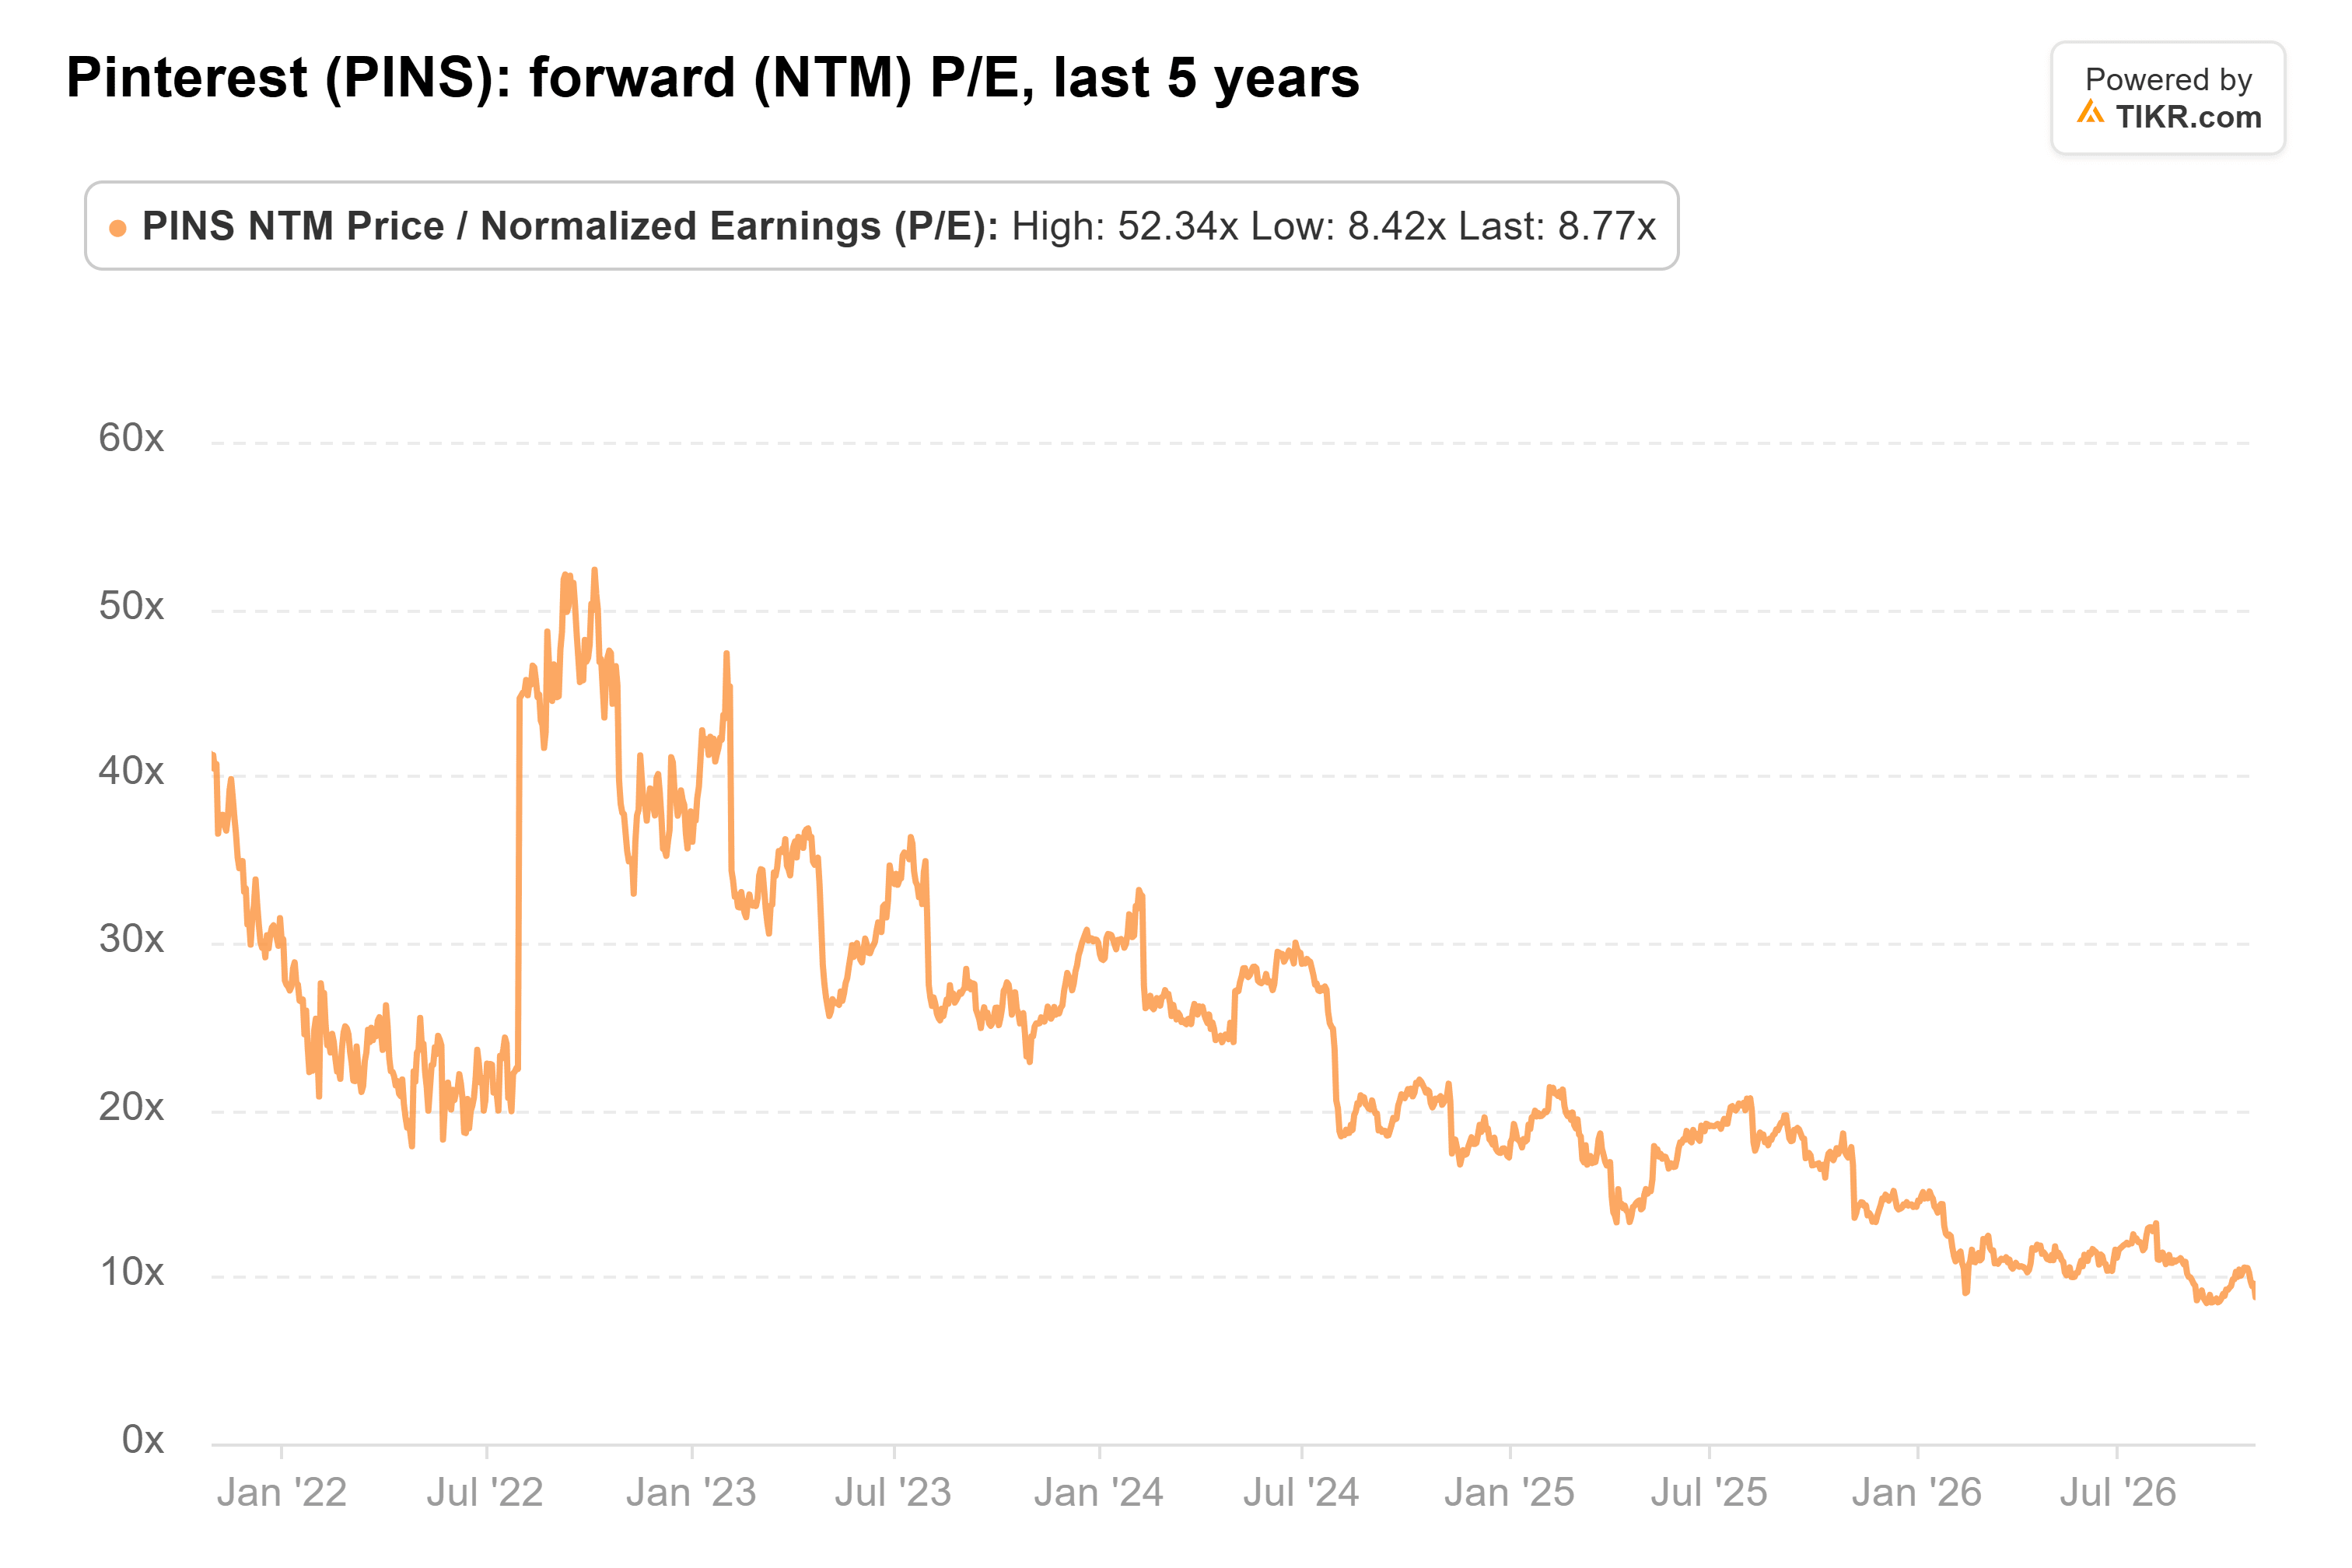
UBS’s $32 works out to about 14x the $2.27 a share analysts expect over the next twelve months, about where Pinterest’s multiple sat at the end of 2025.
Cheap, but growth has to come back
The risk is what normalized EPS leaves out. Stock pay ran at 21% of revenue in 2025, and analysts see just $0.42 a share of GAAP EPS for 2026.
My take: $32 asks only for a multiple Pinterest carried less than a year ago, on earnings analysts already expect, so the math is on UBS’s side. The catch is growth: the stock won’t earn that multiple back until revenue climbs toward the mid-teens again, and an 8% to 12% guide doesn’t show that yet.
The 2027 outlook, due with fourth-quarter results in early February, is the first real test.
So what is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!