


Key Takeaways
- Scotiabank cut its MercadoLibre price target to $2,300 from $2,800 on Nov. 5 but kept its Sector Outperform rating. The target is 52% above the stock price.
- MercadoLibre is down 34% over the past year as free shipping and credit cards have squeezed its margins, and its third-quarter EPS missed estimates.
- If 2028 estimates hold, $2,300 is about 29x earnings a year from now, close to the stock’s 27x on 2027 estimates today.
- The target fits the earnings analysts expect, but those estimates have fallen all year, so MercadoLibre will likely take longer than a year to get there.
MercadoLibre (MELI) stock is down 13% today at about $1,515, after a third-quarter profit miss on Nov. 4. That leaves it down 34% over the past year.
On Nov. 5, Scotiabank cut its price target to $2,300 from $2,800 and kept its Sector Outperform rating. That’s still 52% above today’s price.
MercadoLibre Spent Its Margin on Growth
After MercadoLibre cut Brazil’s free-shipping threshold to R$19 from R$79 in June 2025 and ramped up credit card issuance, its operating margin fell to 6.7% in the second quarter of 2026, from 12.2% a year earlier.
Lula’s surprise win in Brazil’s Oct. 25 runoff sent Brazilian stocks lower, on fears of a weaker real. Brazil brought in 52.6% of MercadoLibre’s 2025 revenue.
In the third quarter, revenue rose 45% to $10.75 billion (41% FX-neutral), but operating income fell 6.6% to $676 million, a 6.3% margin, and EPS of $8.83 missed the $9.27 consensus. Management blamed more free shipping, new fulfillment capacity and extra affiliate marketing in Brazil. CFO Martin de los Santos said on the call that, on the capacity costs, “we expect that part of that to come back in Q4.”
TIKR Tracks 26 Analysts on MercadoLibre. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on MercadoLibre, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See MercadoLibre’s Analyst Ratings
Scotiabank Is Still a MercadoLibre Buyer
Scotiabank started coverage in July 2025 at Sector Outperform with a $3,500 target. When analyst Hector Maya cut it to $2,800 in May, he framed it as a reset to a lower margin base.
Management is making the same bet. Its third-quarter shareholder letter said “the habits we are building are worth more than the margin we are forgoing in the short term to build them.”
Does $2,300 Add Up?
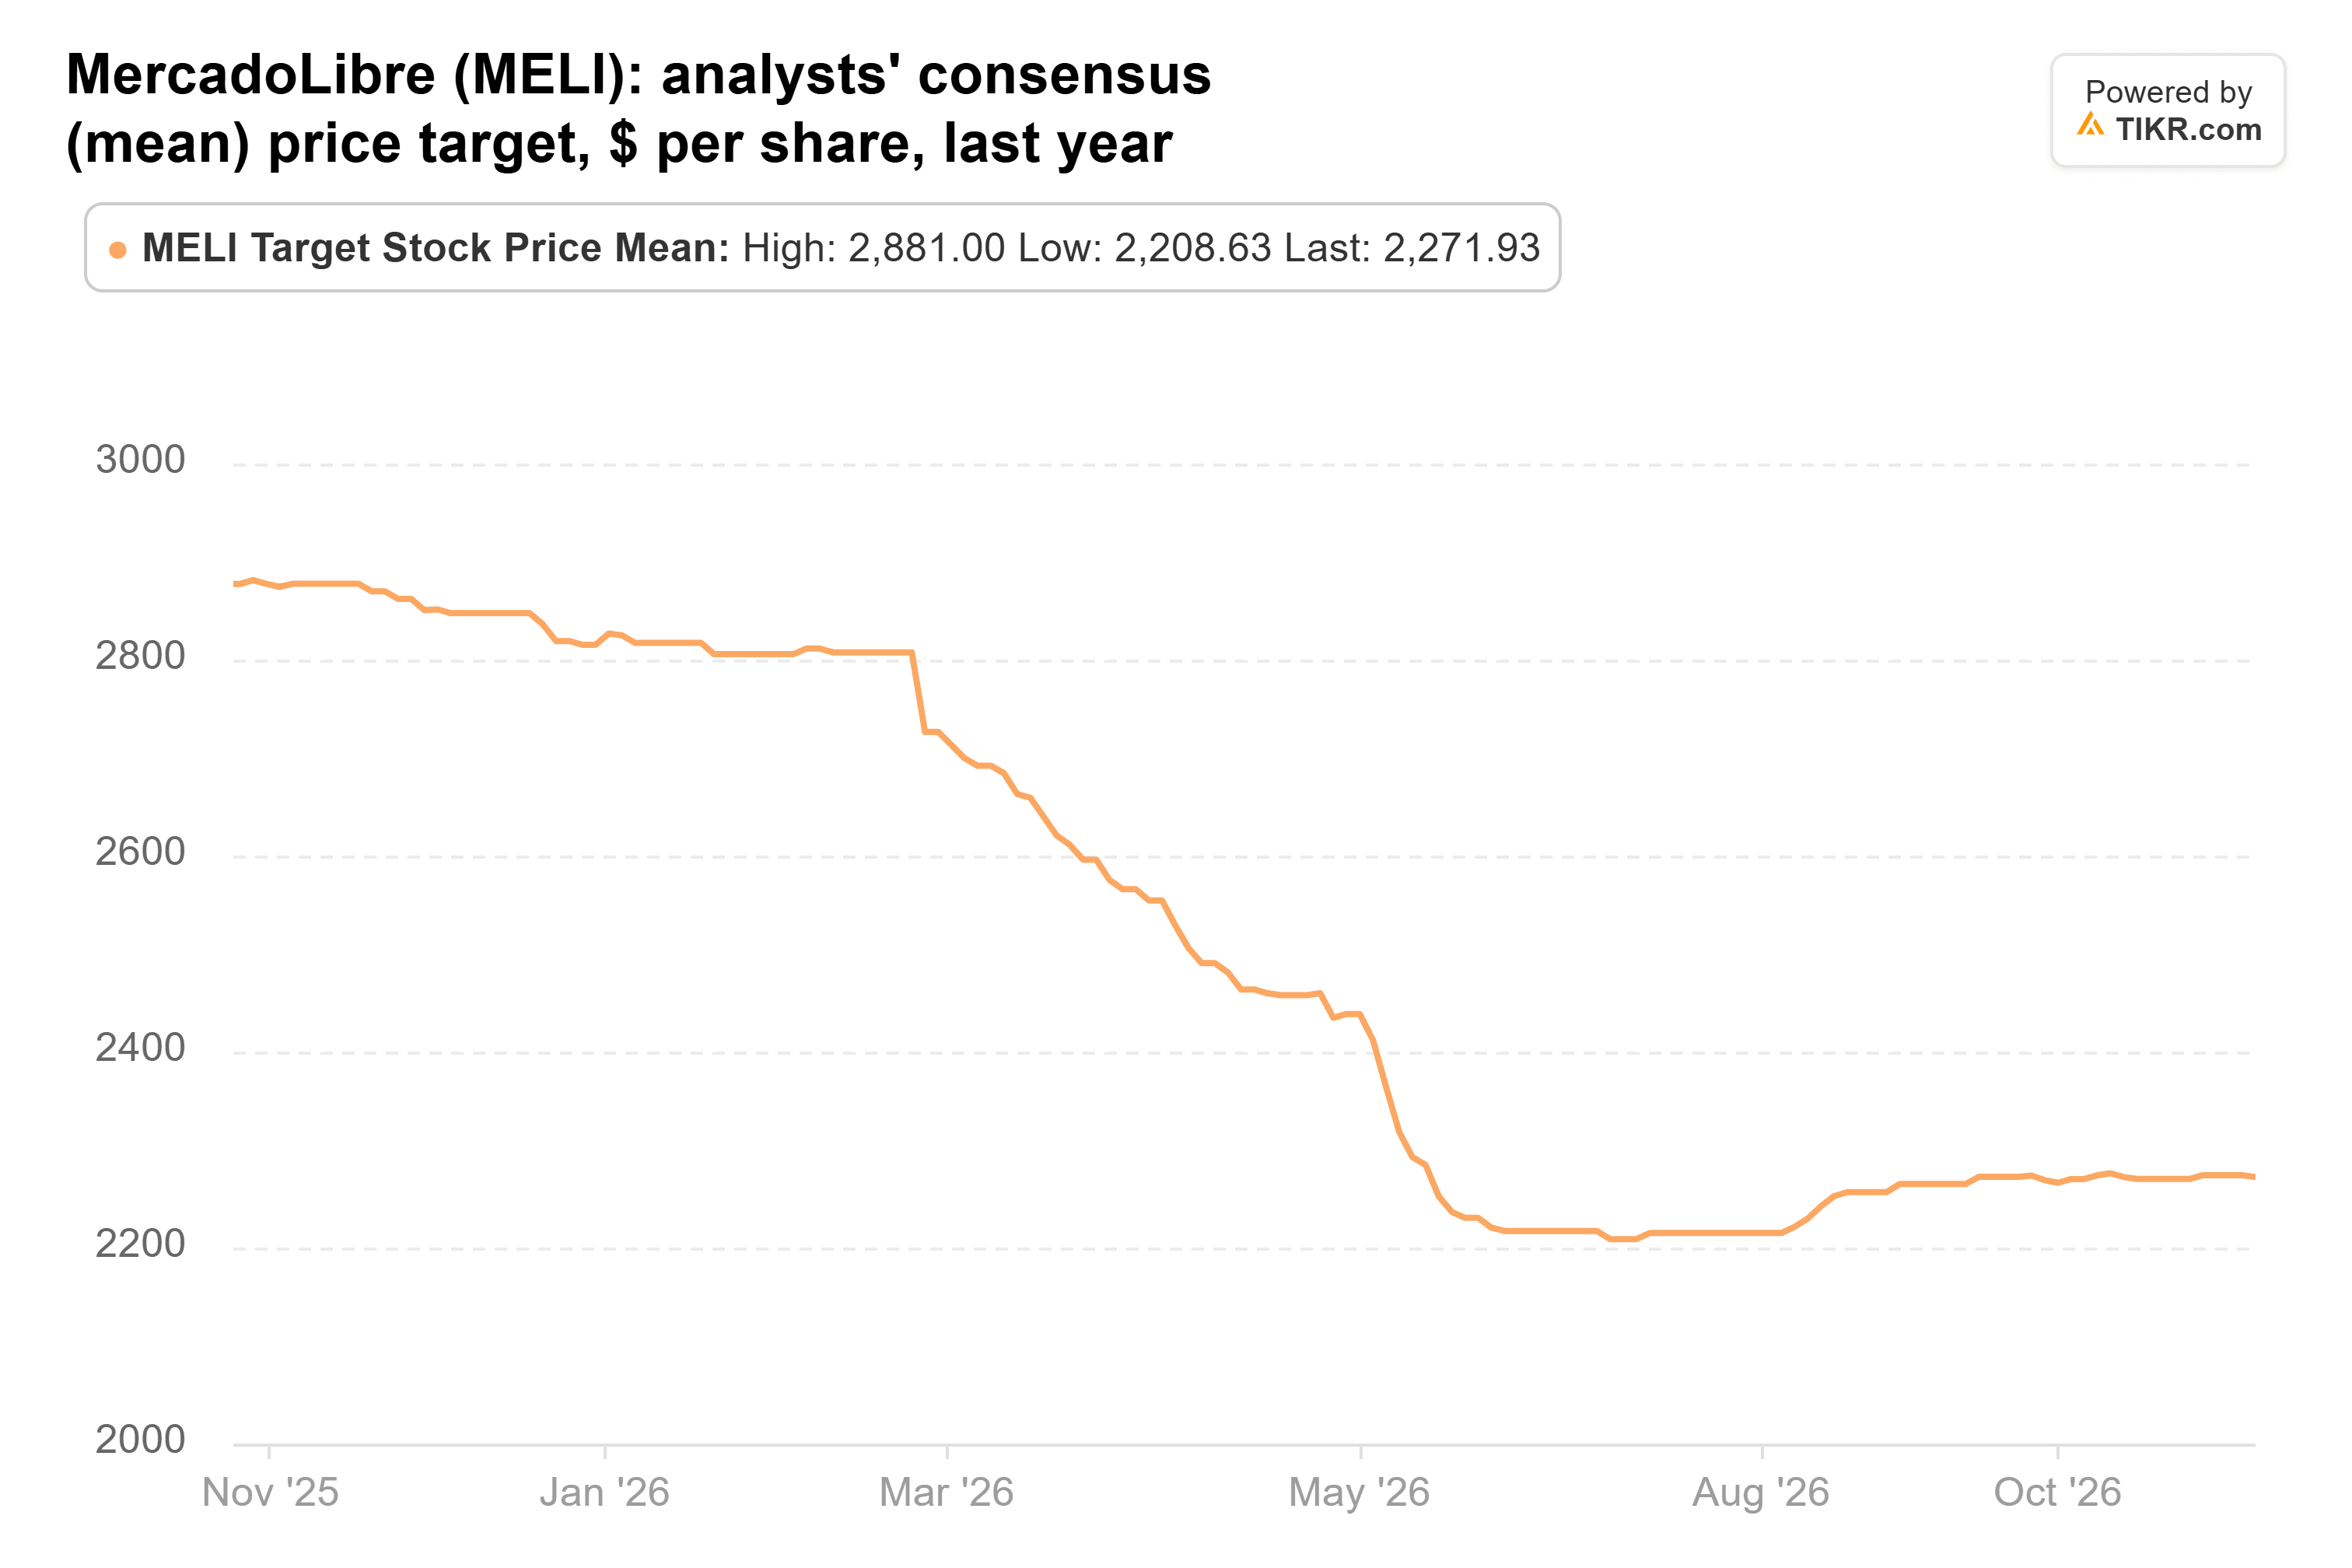
The consensus target has fallen to $2,272, from $2,877 a year ago, so Scotiabank now sits right at the average.
Analysts expect EPS to dip to $38.26 this year, from $39.40 in 2025, then jump to $55.89 in 2027.
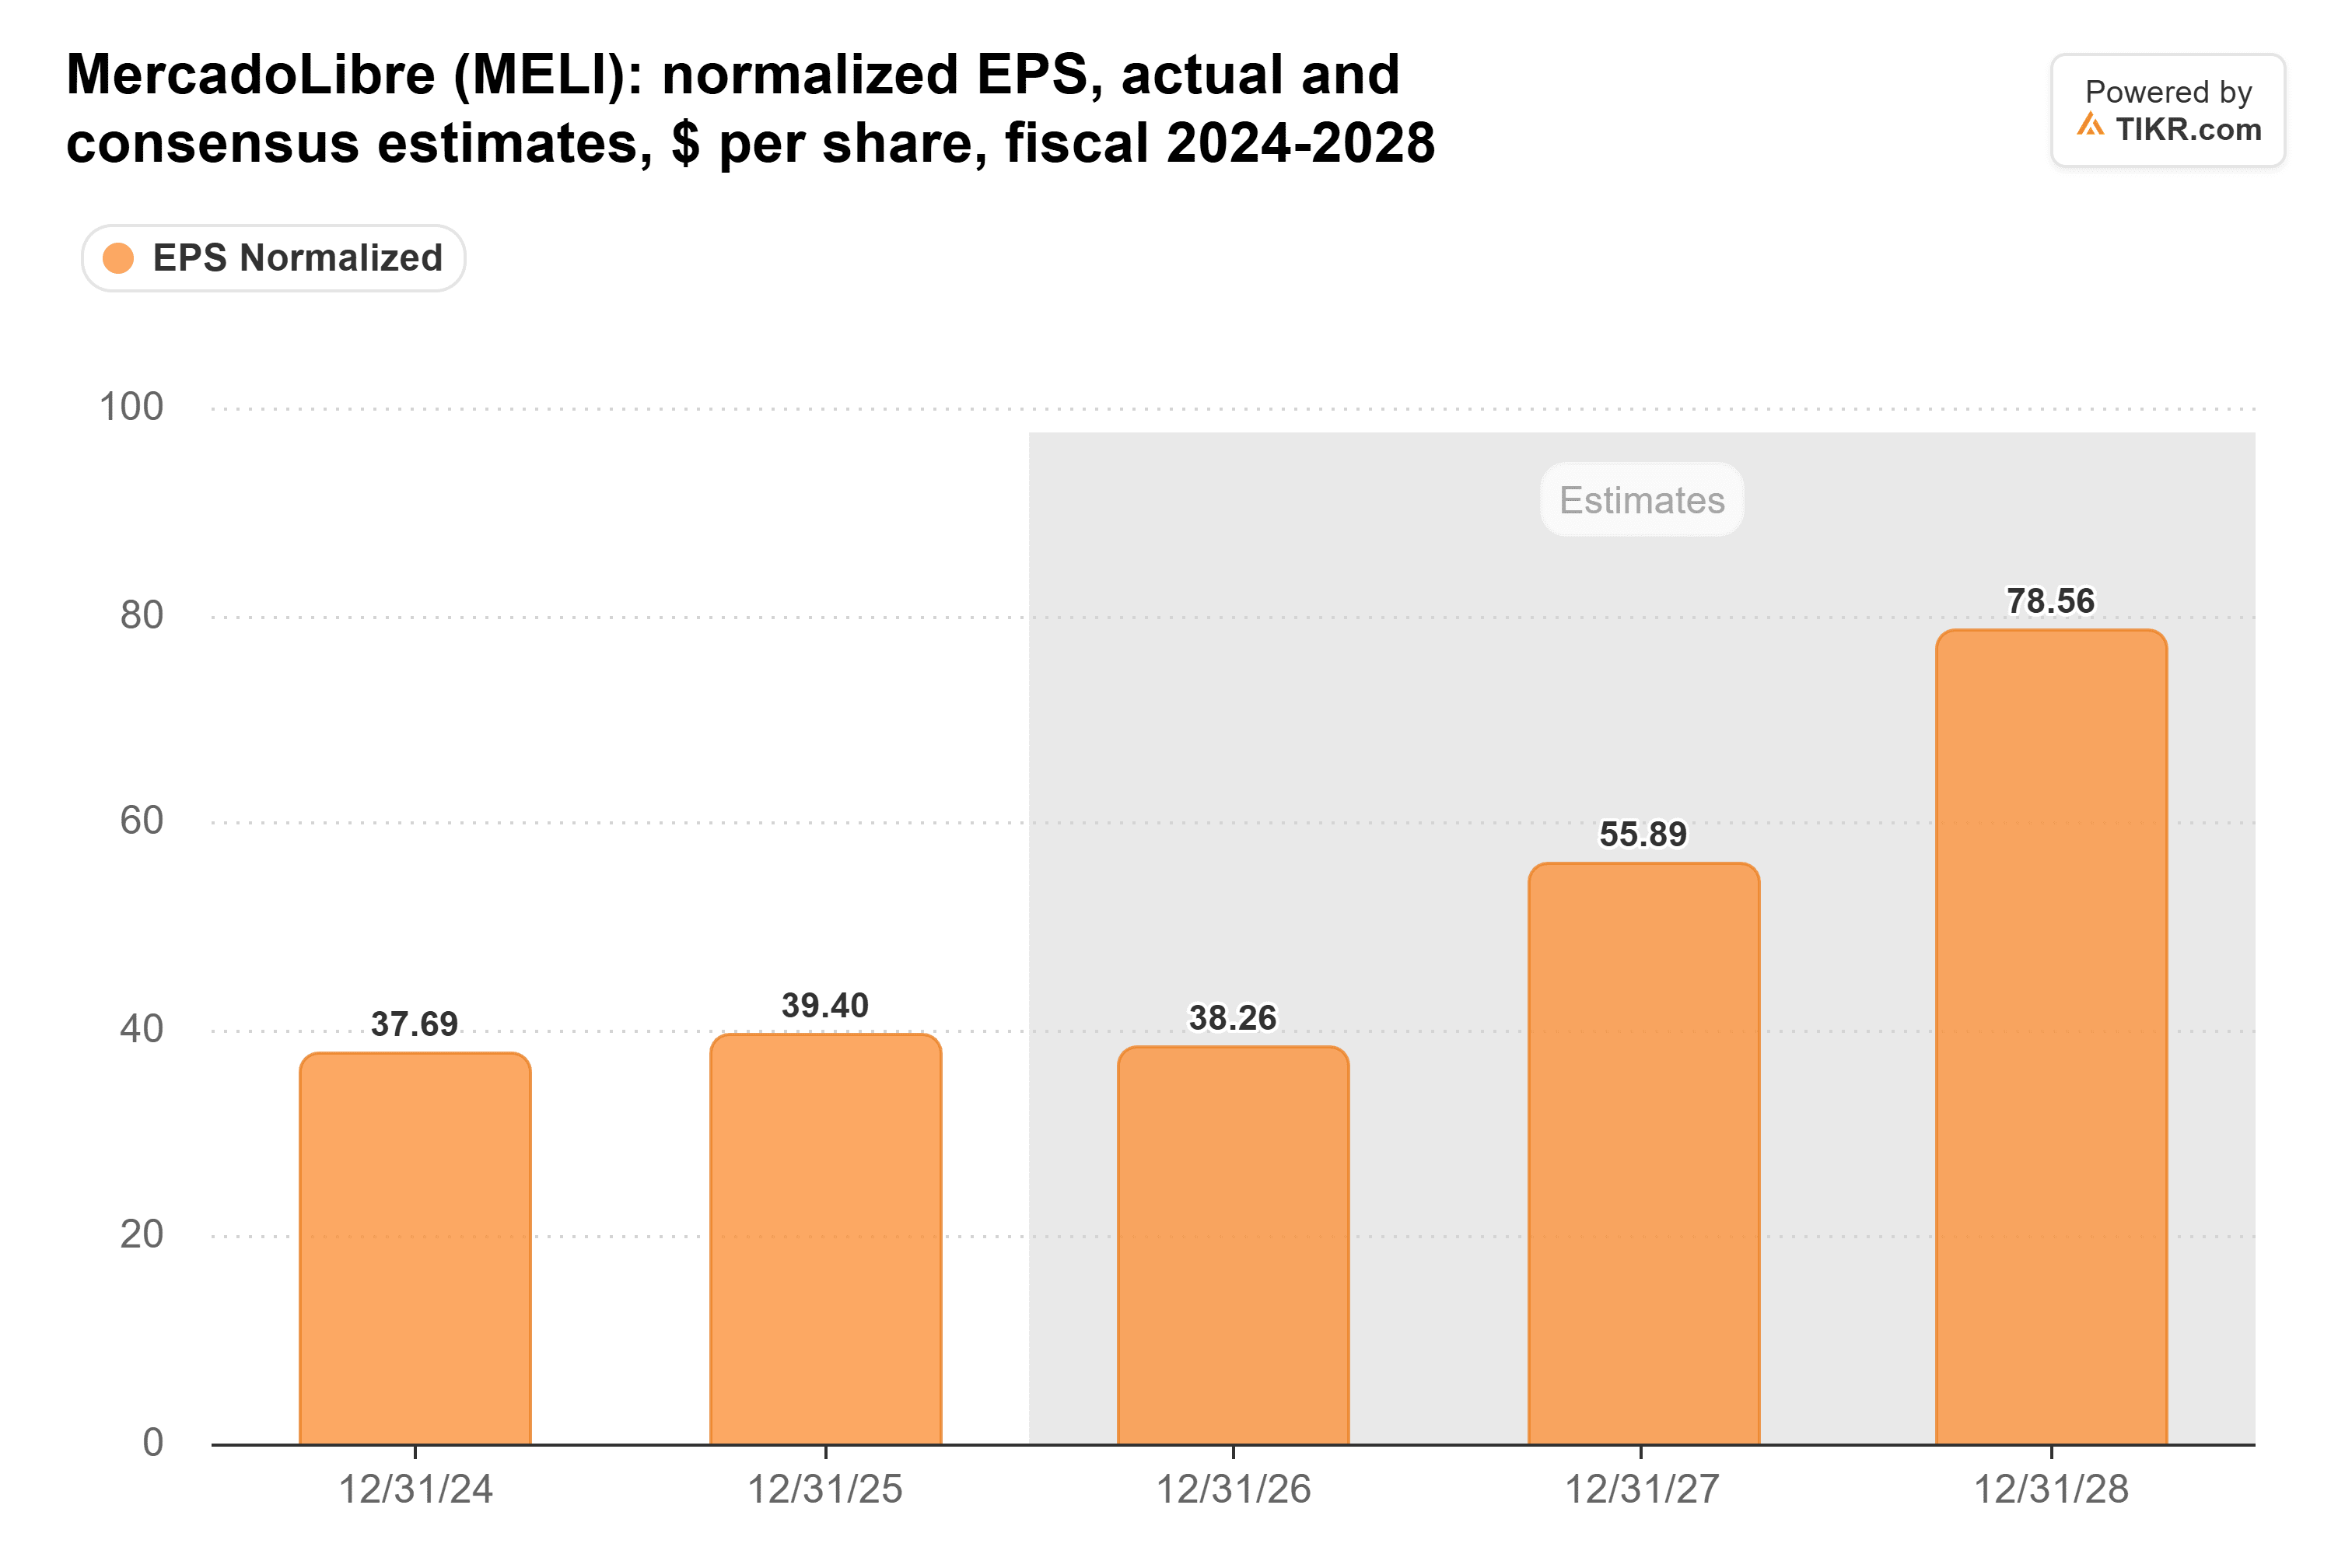
That 2027 estimate has fallen by more than a third since September 2025. With affiliate spending continuing, I’d expect more cuts after this report.
MercadoLibre traded at 41x forward earnings at the Nov. 2 close, against a five-year average of 63x. Today’s drop takes it to about 37x.
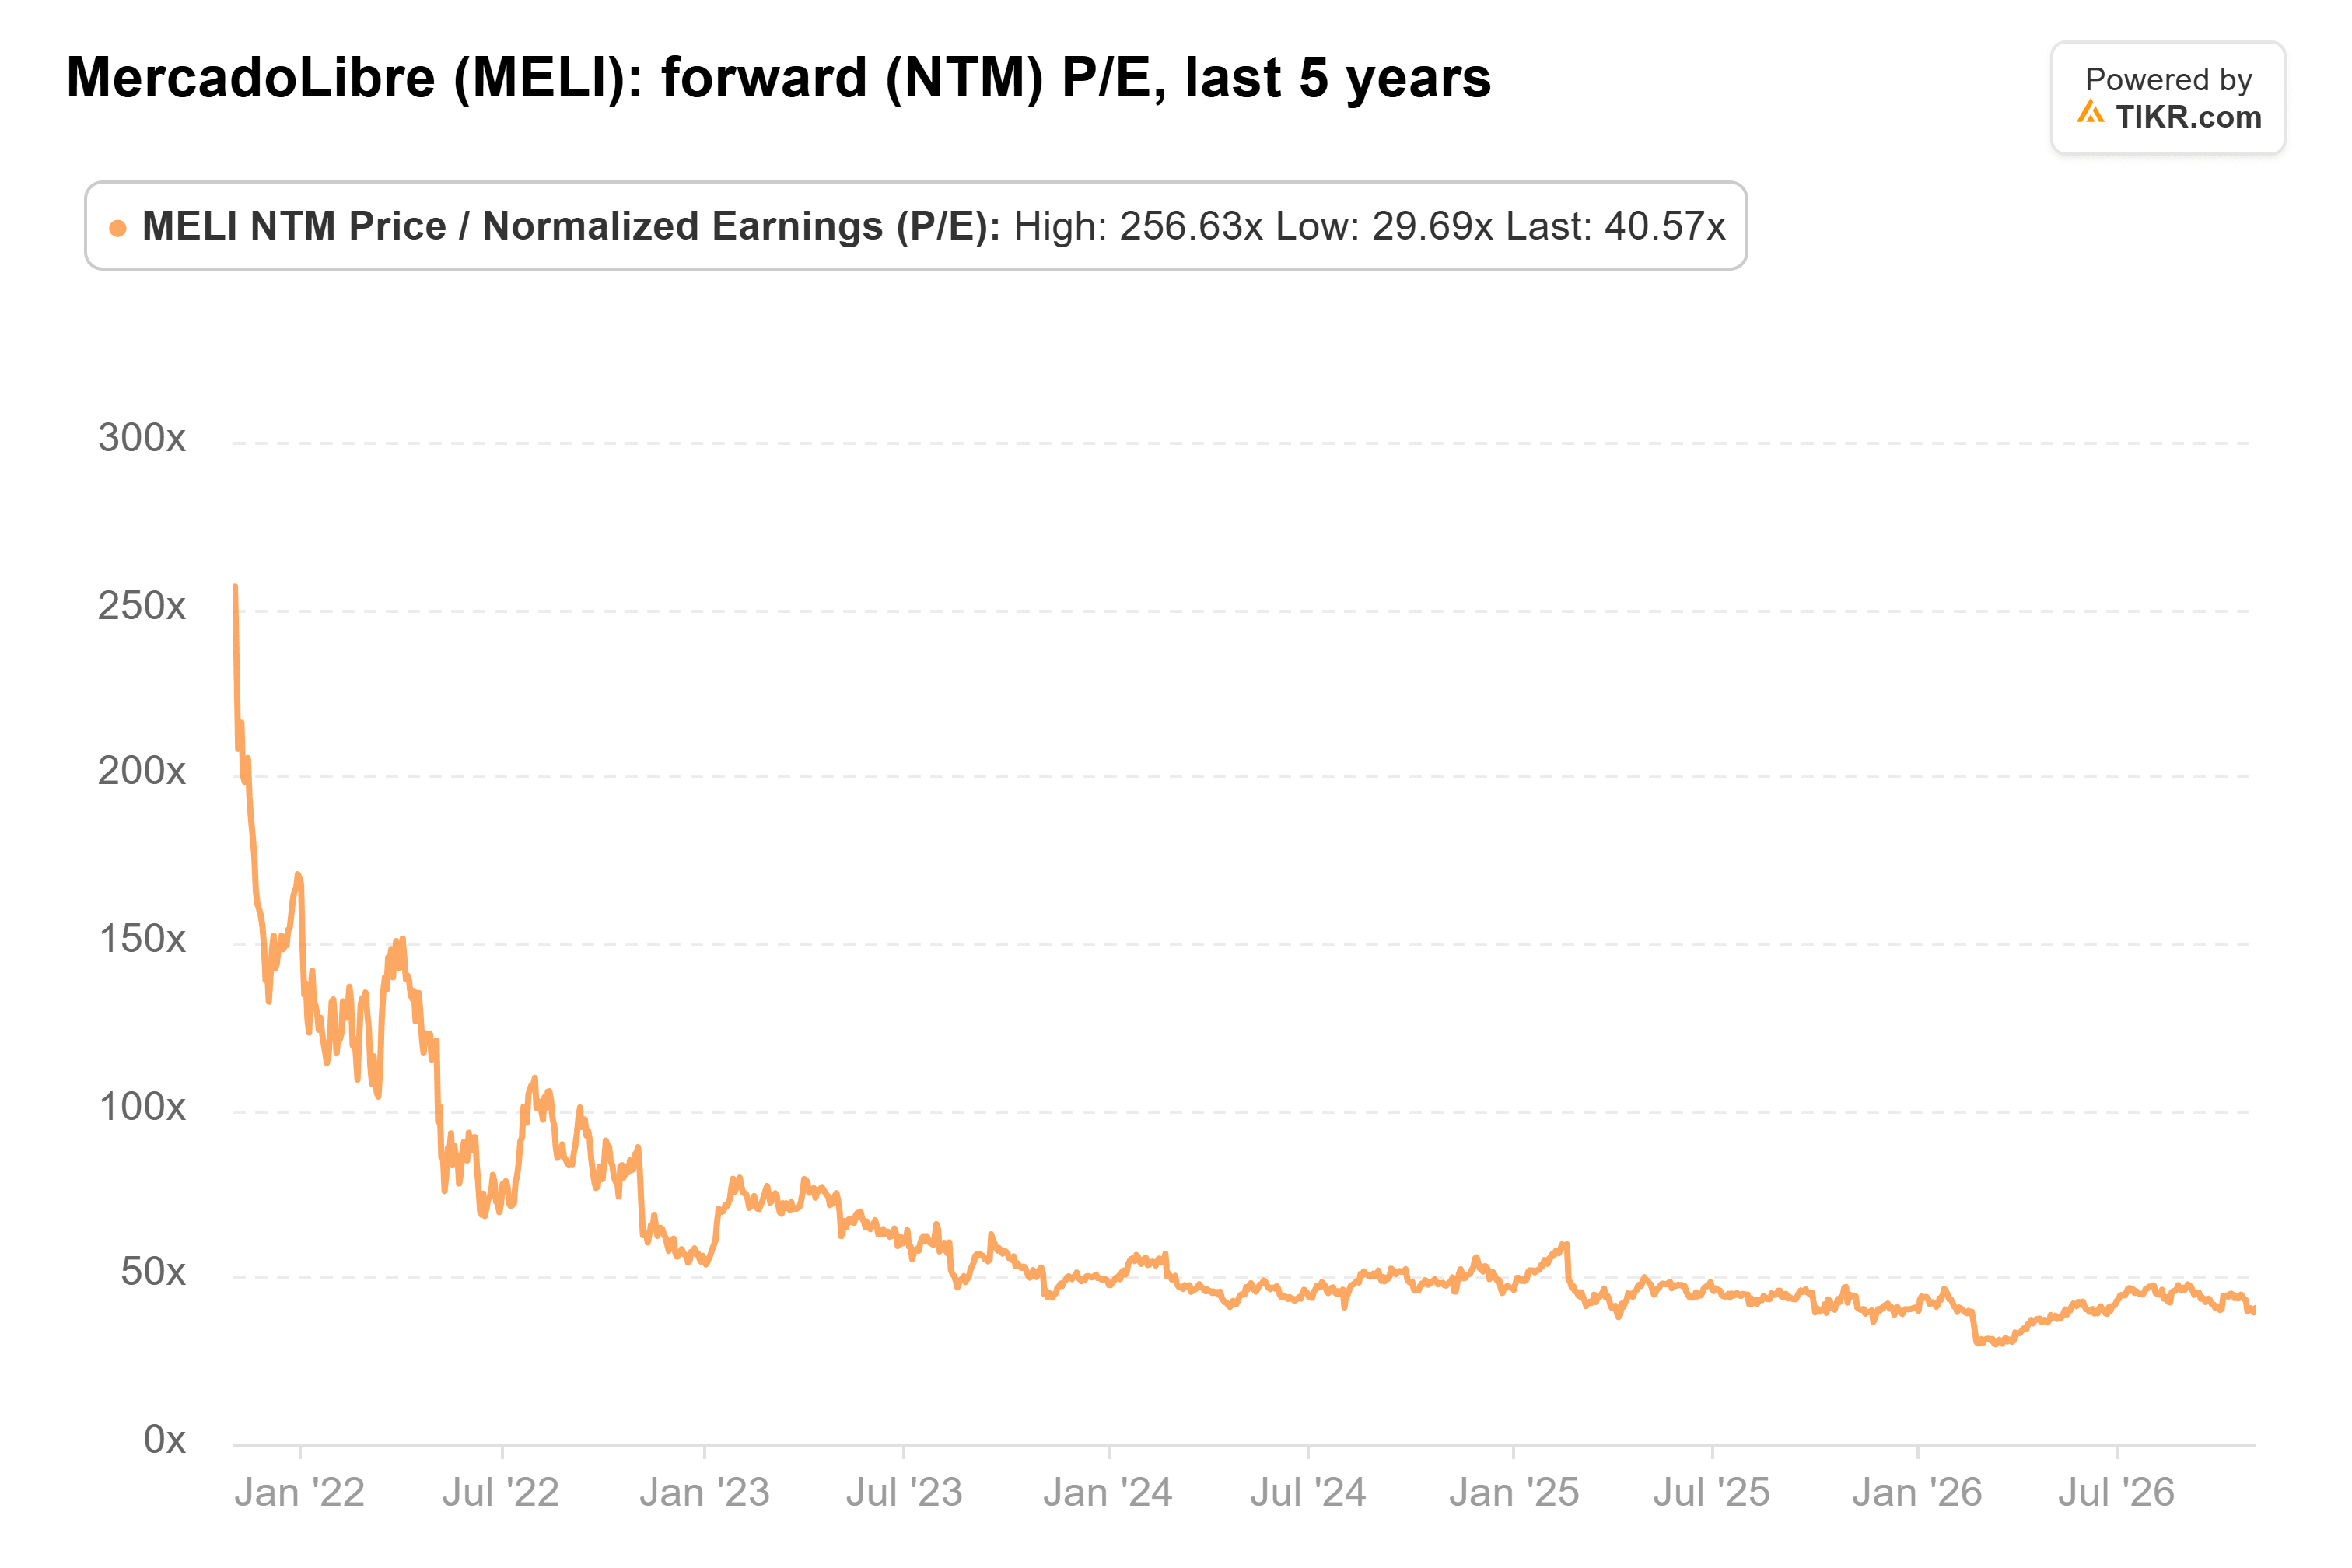
That average leans on 2021’s 257x peak, and MercadoLibre hasn’t ended a quarter above 49x since late 2023.
A 12-month target is judged on the earnings ahead of it. Today that’s mostly 2027, and $1,515 is about 27x the $55.89 estimate. A year from now it’s mostly 2028, and $2,300 is about 29x the $78.56 estimate. If estimates hold, Scotiabank needs only a small rerating.
$2,300 is a fair price for the earnings analysts expect, if they show up. With estimates falling all year and the spending set to continue, I think MercadoLibre gets there later than Scotiabank expects.
The fourth-quarter letter in early 2027 should show how hard MercadoLibre plans to invest next year. If margins recover as the new warehouses fill up, Scotiabank’s timeline looks better.
So What Is MercadoLibre Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MercadoLibre could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



