Key Takeaways
- Of the 460 big funds that have filed 13Fs for the quarter ended Sept. 30, 20 bought Mastercard and 18 sold it.
- Coatue and Viking Global each opened positions worth more than $800 million, while the biggest sellers mostly trimmed stakes they still hold.
- Eight of the buyers sold or cut Visa in the same quarter, though Visa’s latest quarter was about as strong as Mastercard’s.
- Mastercard trades below its five-year average multiple with earnings expected to grow about 16.5% a year, which puts the numbers on the buyers’ side.
Big investors split almost down the middle on Mastercard (MA) last quarter. The buyers just did it in much bigger size.
Of the 460 big funds that have filed 13Fs for the quarter ended Sept. 30 (funds readers know, or ones with $1 billion or more of US stocks, with quant and index funds left out), 20 bought Mastercard, either opening a position or adding 20% or more. Another 18 sold out or cut by 20% or more, and 110 held it on Sept. 30. And 8 of those 20 buyers sold or cut Visa (V) in the same quarter.
The buyers came in big
Philippe Laffont’s Coatue, a firm that manages $93 billion, opened a position of 1.60 million shares worth about $883 million at quarter-end prices, according to its 13F filed Nov. 16. Andreas Halvorsen’s Viking Global, which manages $78 billion, opened one of 1.48 million shares worth about $818 million, per its 13F filed the same day. That made Mastercard 2.5% of Viking’s 13F stocks, its 10th-largest position, and 1.6% of Coatue’s.
Sanders Capital, which manages $122 billion, added 26% to its stake, which now stands at 2.94 million shares worth $1.62 billion. And Alphinity Investment Management took its stake from 11,743 shares to 233,018, which put Mastercard among the three stocks that $4.5 billion fund bought.
TIKR tracks 40 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
The sellers mostly trimmed
The selling side looks a lot less like an exit. Polen Capital, which manages $24 billion, made the biggest sale, cutting its stake 26% to 845,875 shares, per its 13F filed Nov. 13. Even so, Mastercard is still 5.1% of Polen’s 13F stocks and its eighth-largest position. Denmark’s BLS Capital, which manages $7.2 billion, cut 22% in its 13F filed the same day and still has 8.4% of its 13F stocks in Mastercard, its sixth-largest holding. Of the five biggest sellers, only Atreides Management sold out: all 93,629 shares, about $48 million at quarter-end prices.
Mastercard is up 13% since Sept. 30. That’s the stock’s move from the quarter’s last day: a 13F doesn’t show what anyone paid, or whether they still own it.
Visa is the other half of the story. Put the two networks’ latest quarters side by side, and there isn’t much to choose between them. Mastercard’s net revenue grew 14% in its third quarter, with value-added services up 19%, according to its third-quarter release. Visa’s grew 13% in its fiscal fourth quarter, which covers the same three months, and its cross-border volume rose 14% against Mastercard’s 11%. Visa’s non-GAAP EPS rose 17%, and it just raised its dividend 16%.
Wall Street’s numbers side with the buyers
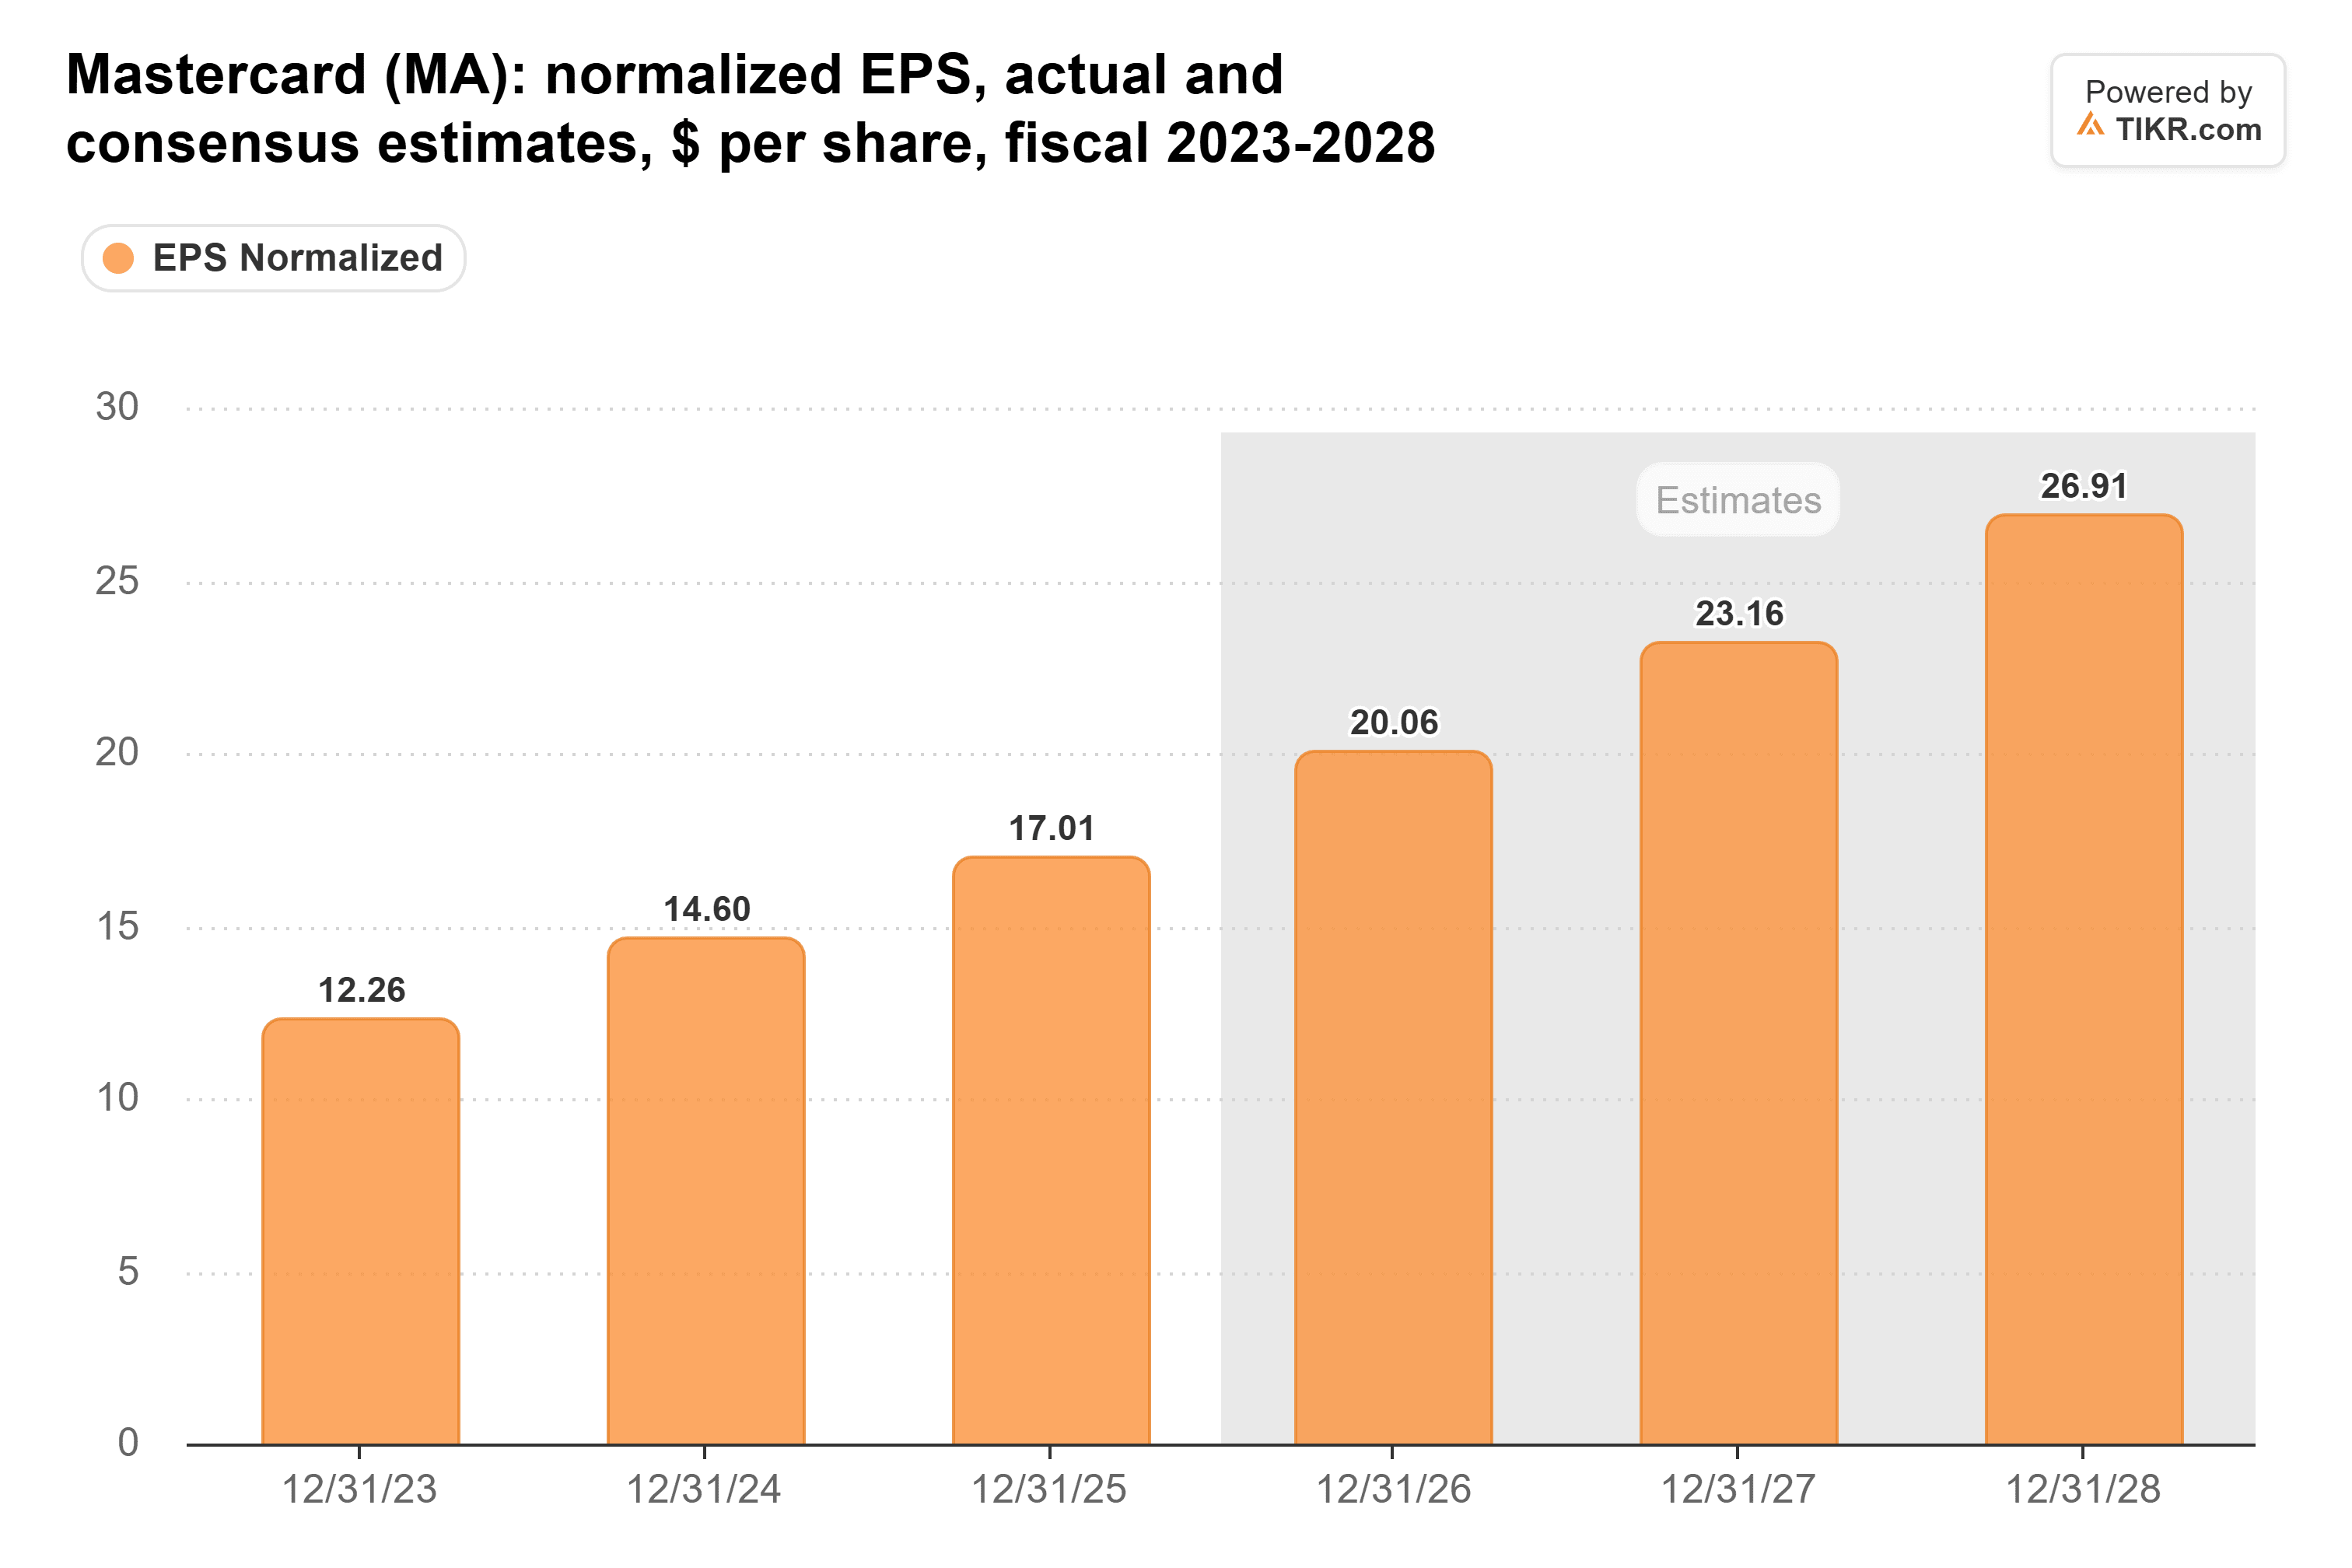
Analysts expect Mastercard’s normalized EPS to climb from $17.01 in 2025 to $26.91 in 2028, about 16.5% a year:
And you aren’t paying up for that growth. Mastercard trades at 28x forward earnings, below its five-year average of 31x and well under its 38x peak in January 2022:
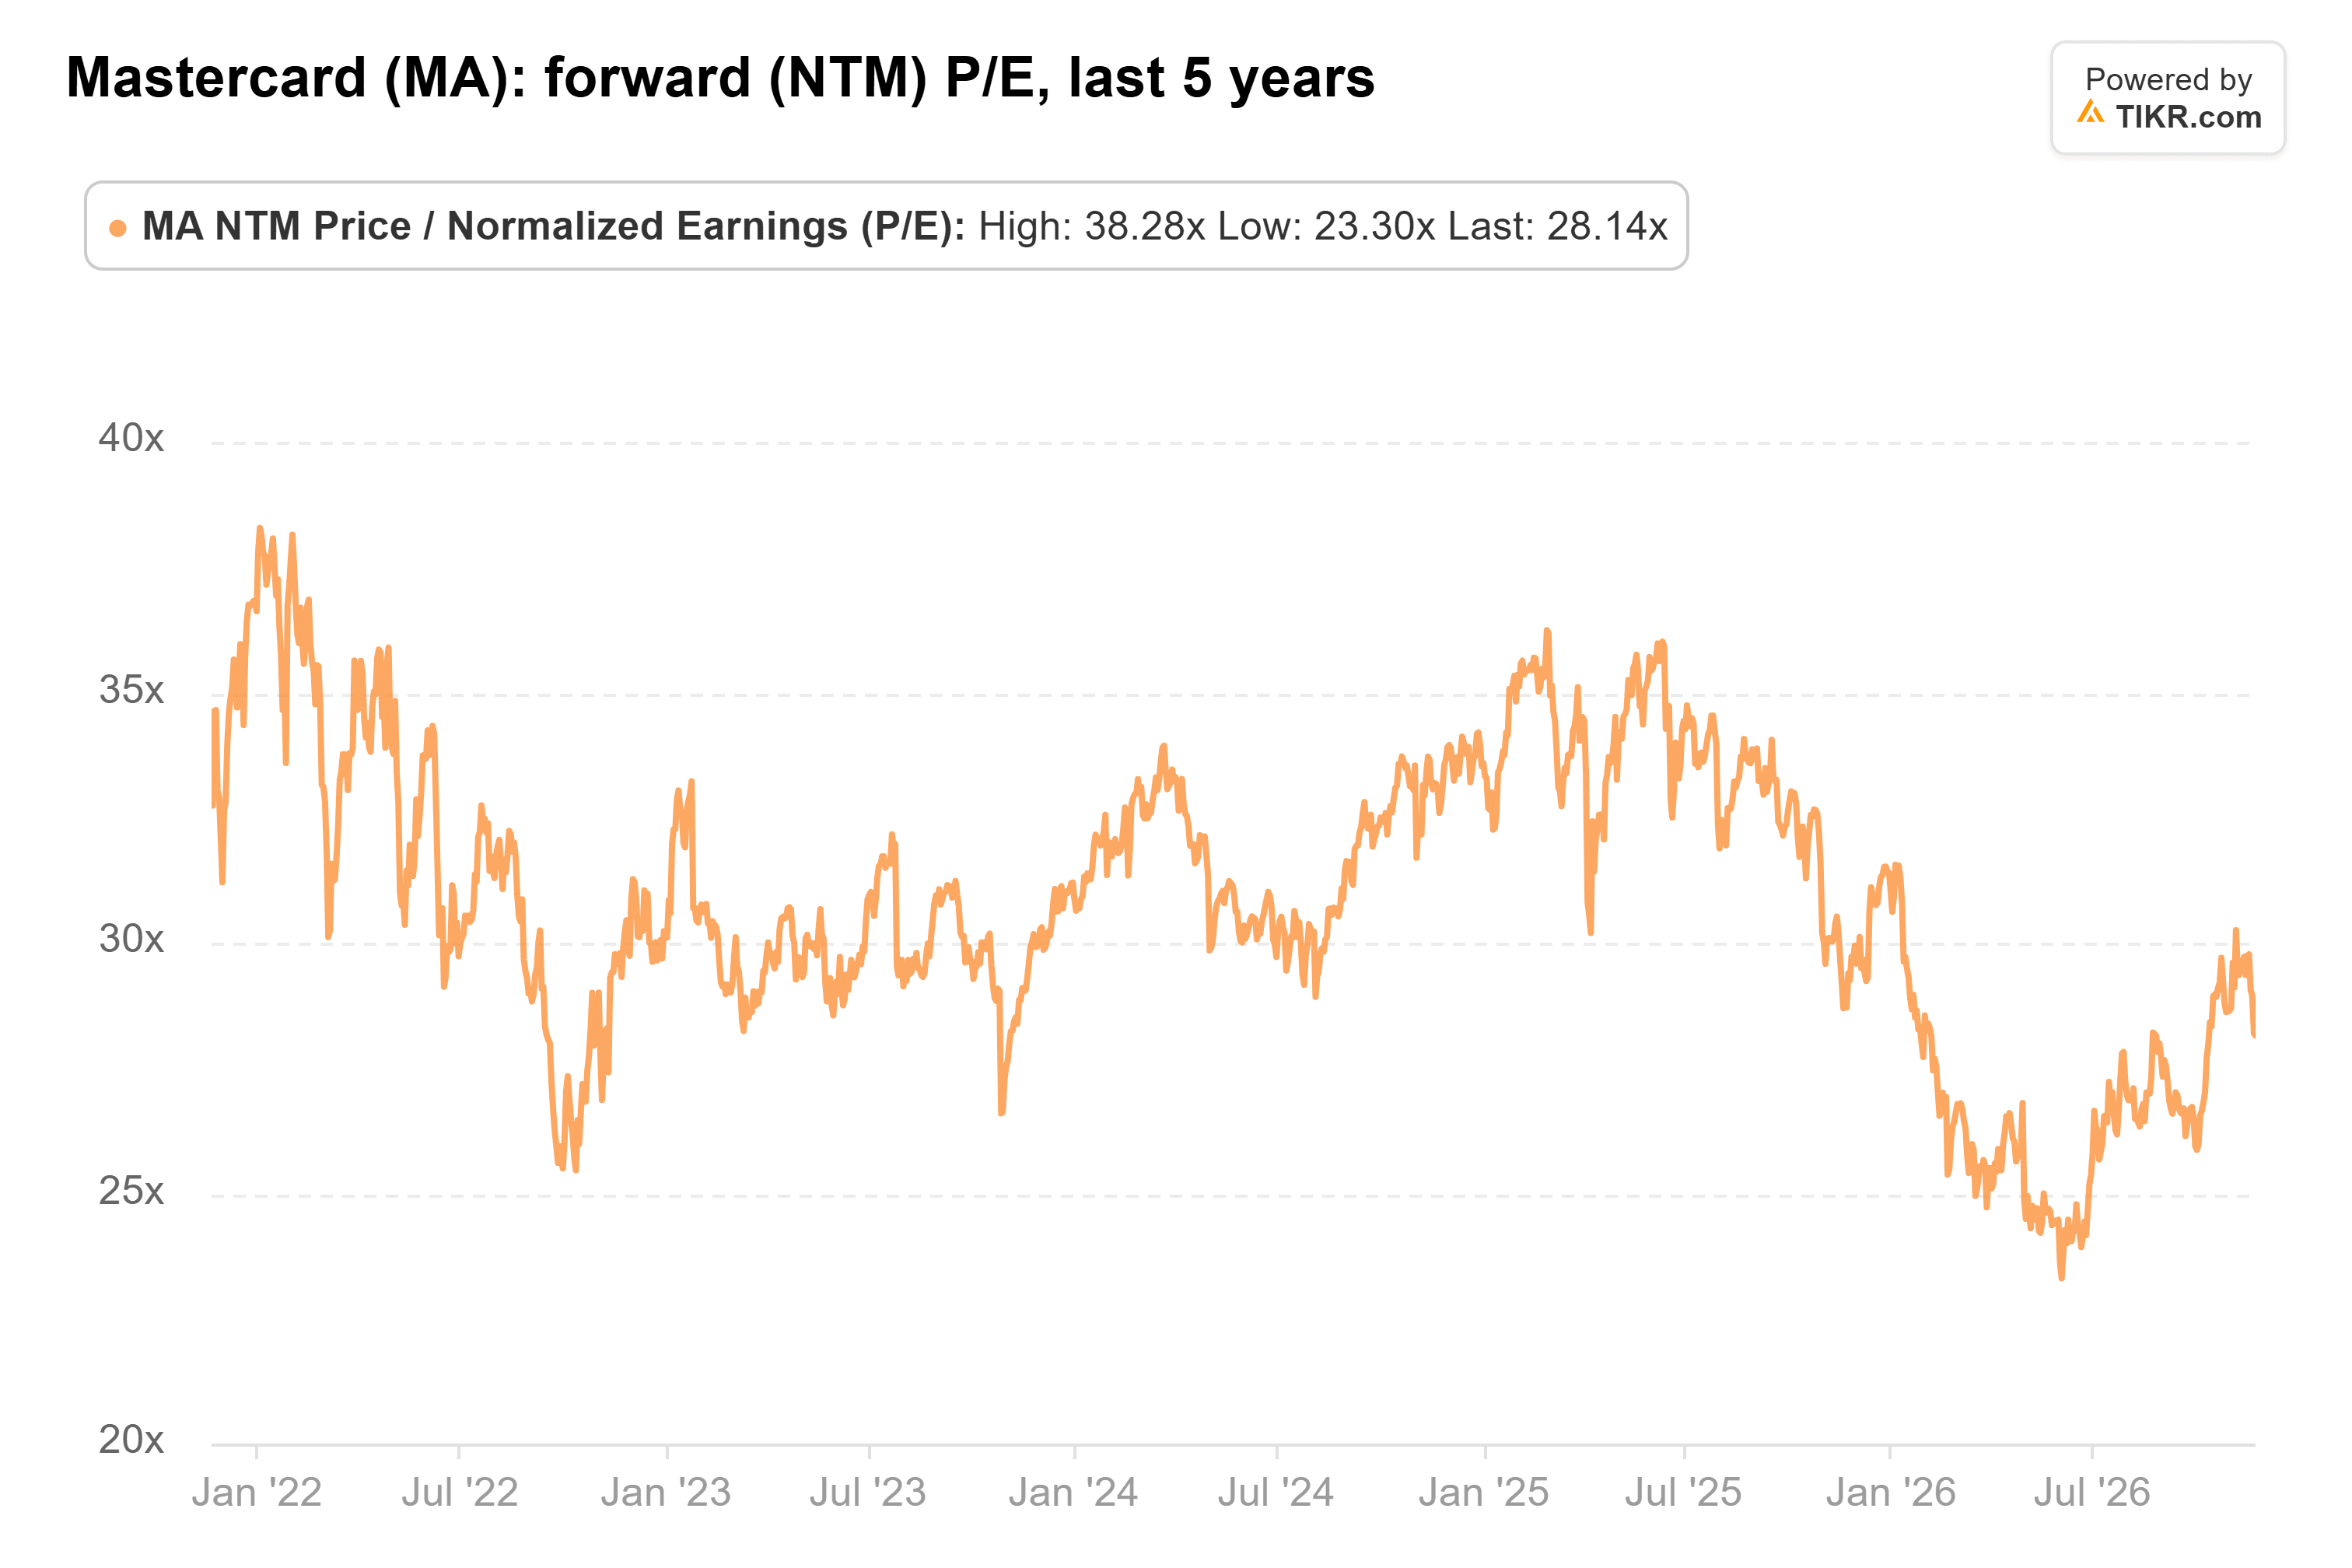
The multiple bottomed at 23x in June, when the stock dipped below $500, so a good chunk of the rebound has already happened. But 28x is still a discount to where investors have usually valued this business.
Analysts’ targets have climbed with the estimates. The consensus target is $721, up from $657 a year ago and 15% above the last close:

A year from now, the market will be pricing 2028’s earnings. On that $26.91 estimate, $721 works out to about 27x by our math, a touch below today’s multiple and under the five-year average. So the target needs no re-rating at all, only for the estimates to hold. (Targets run from $550 to $800.)
The sellers’ best case is the cash
The sellers’ strongest argument on the numbers is what it costs Mastercard to win business. Rebates and incentives took 52.4% of its gross network fees in the second quarter, up from 49.9% a year earlier, per its quarterly filing. Analysts also expect free cash flow to grow only about 3% in 2026, and CFO Ling Hai has warned of a fourth-quarter offset to the third quarter’s strength.
Still, the buyers have the better side of this trade. Mastercard is growing earnings in the mid-teens, trades below its usual multiple, and doesn’t need a higher one to reach the Street’s target. Paying 28x for that is a fair deal for a business this good.
The next test is Mastercard’s fourth-quarter report in late January, which brings the first full-year outlook from Hai as CFO. If it keeps 2027’s $23.16 EPS estimate intact and rebates’ share of gross fees stops climbing past 52.4%, the buyers look right. If the guidance pulls that figure down, the point goes to the sellers, and the next round of 13Fs, due by mid-February, will show who stuck around.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!