Key Takeaways
- Alphabet fell 12% on Oct. 29 after its third-quarter report, its worst day since it went public in 2004.
- Scott Galloway calls AI an existential threat to Google Search, but he still says Alphabet stock looks like a buying opportunity.
- Gains on private stakes have pushed up Alphabet’s reported earnings, so on normalized earnings it trades at 20x forward, below its five-year average of 23x.
- With revenue up 25% and Cloud now earning almost as much on new revenue as Google Services does, the stock looks like a buy, and the next test is the 2027 capex figure due in early February.
At the end of April, Alphabet (GOOG) traded at 33x forward earnings, its richest valuation in five years. Now one of Search’s loudest critics says it’s cheap enough to buy.
In between came the third quarter. Search & other revenue grew 12%, down from 17% in the second quarter. Free cash flow came in at negative $9.1 billion. And the stock fell 12% on Oct. 29, its worst day since it went public in 2004. That capped its worst month ever by market value lost.
Scott Galloway, the NYU Stern professor and co-host of Prof G Markets, isn’t shy about the bear case. On Monday’s episode, he said: “AI is an existential threat to Alphabet because the world’s most profitable largest toll booth in history, Search, it appears like is kind of under attack.”
He also said Microsoft paid for its AI build-out with cash on hand, while Alphabet “appears to be taking out second mortgages for the same renovation.”
Then he set Alphabet’s P/E of 14.6 against the S&P 500’s 19.5 and landed here: “this to me feels like a buying opportunity.”
Quite the endorsement from a guy who just called Search a toll booth under attack.
TIKR tracks 58 analysts on Alphabet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
The real multiple is closer to 20x
Alphabet isn’t quite as cheap as 14.6, though. Gains on its stakes in private companies have padded its reported earnings. In the first half of 2026, those gains came to $135.9 billion, more than its $80.5 billion of operating income. In the second quarter alone, they made up $6.26 of its $9.11 of earnings per share.
Normalized earnings are the better yardstick here. Analysts expect them to climb from $10.81 a share in 2025 to $18.26 by 2028, and they barely changed those estimates after the report:

On those earnings, Alphabet trades at 20x, below its five-year average of 23x:
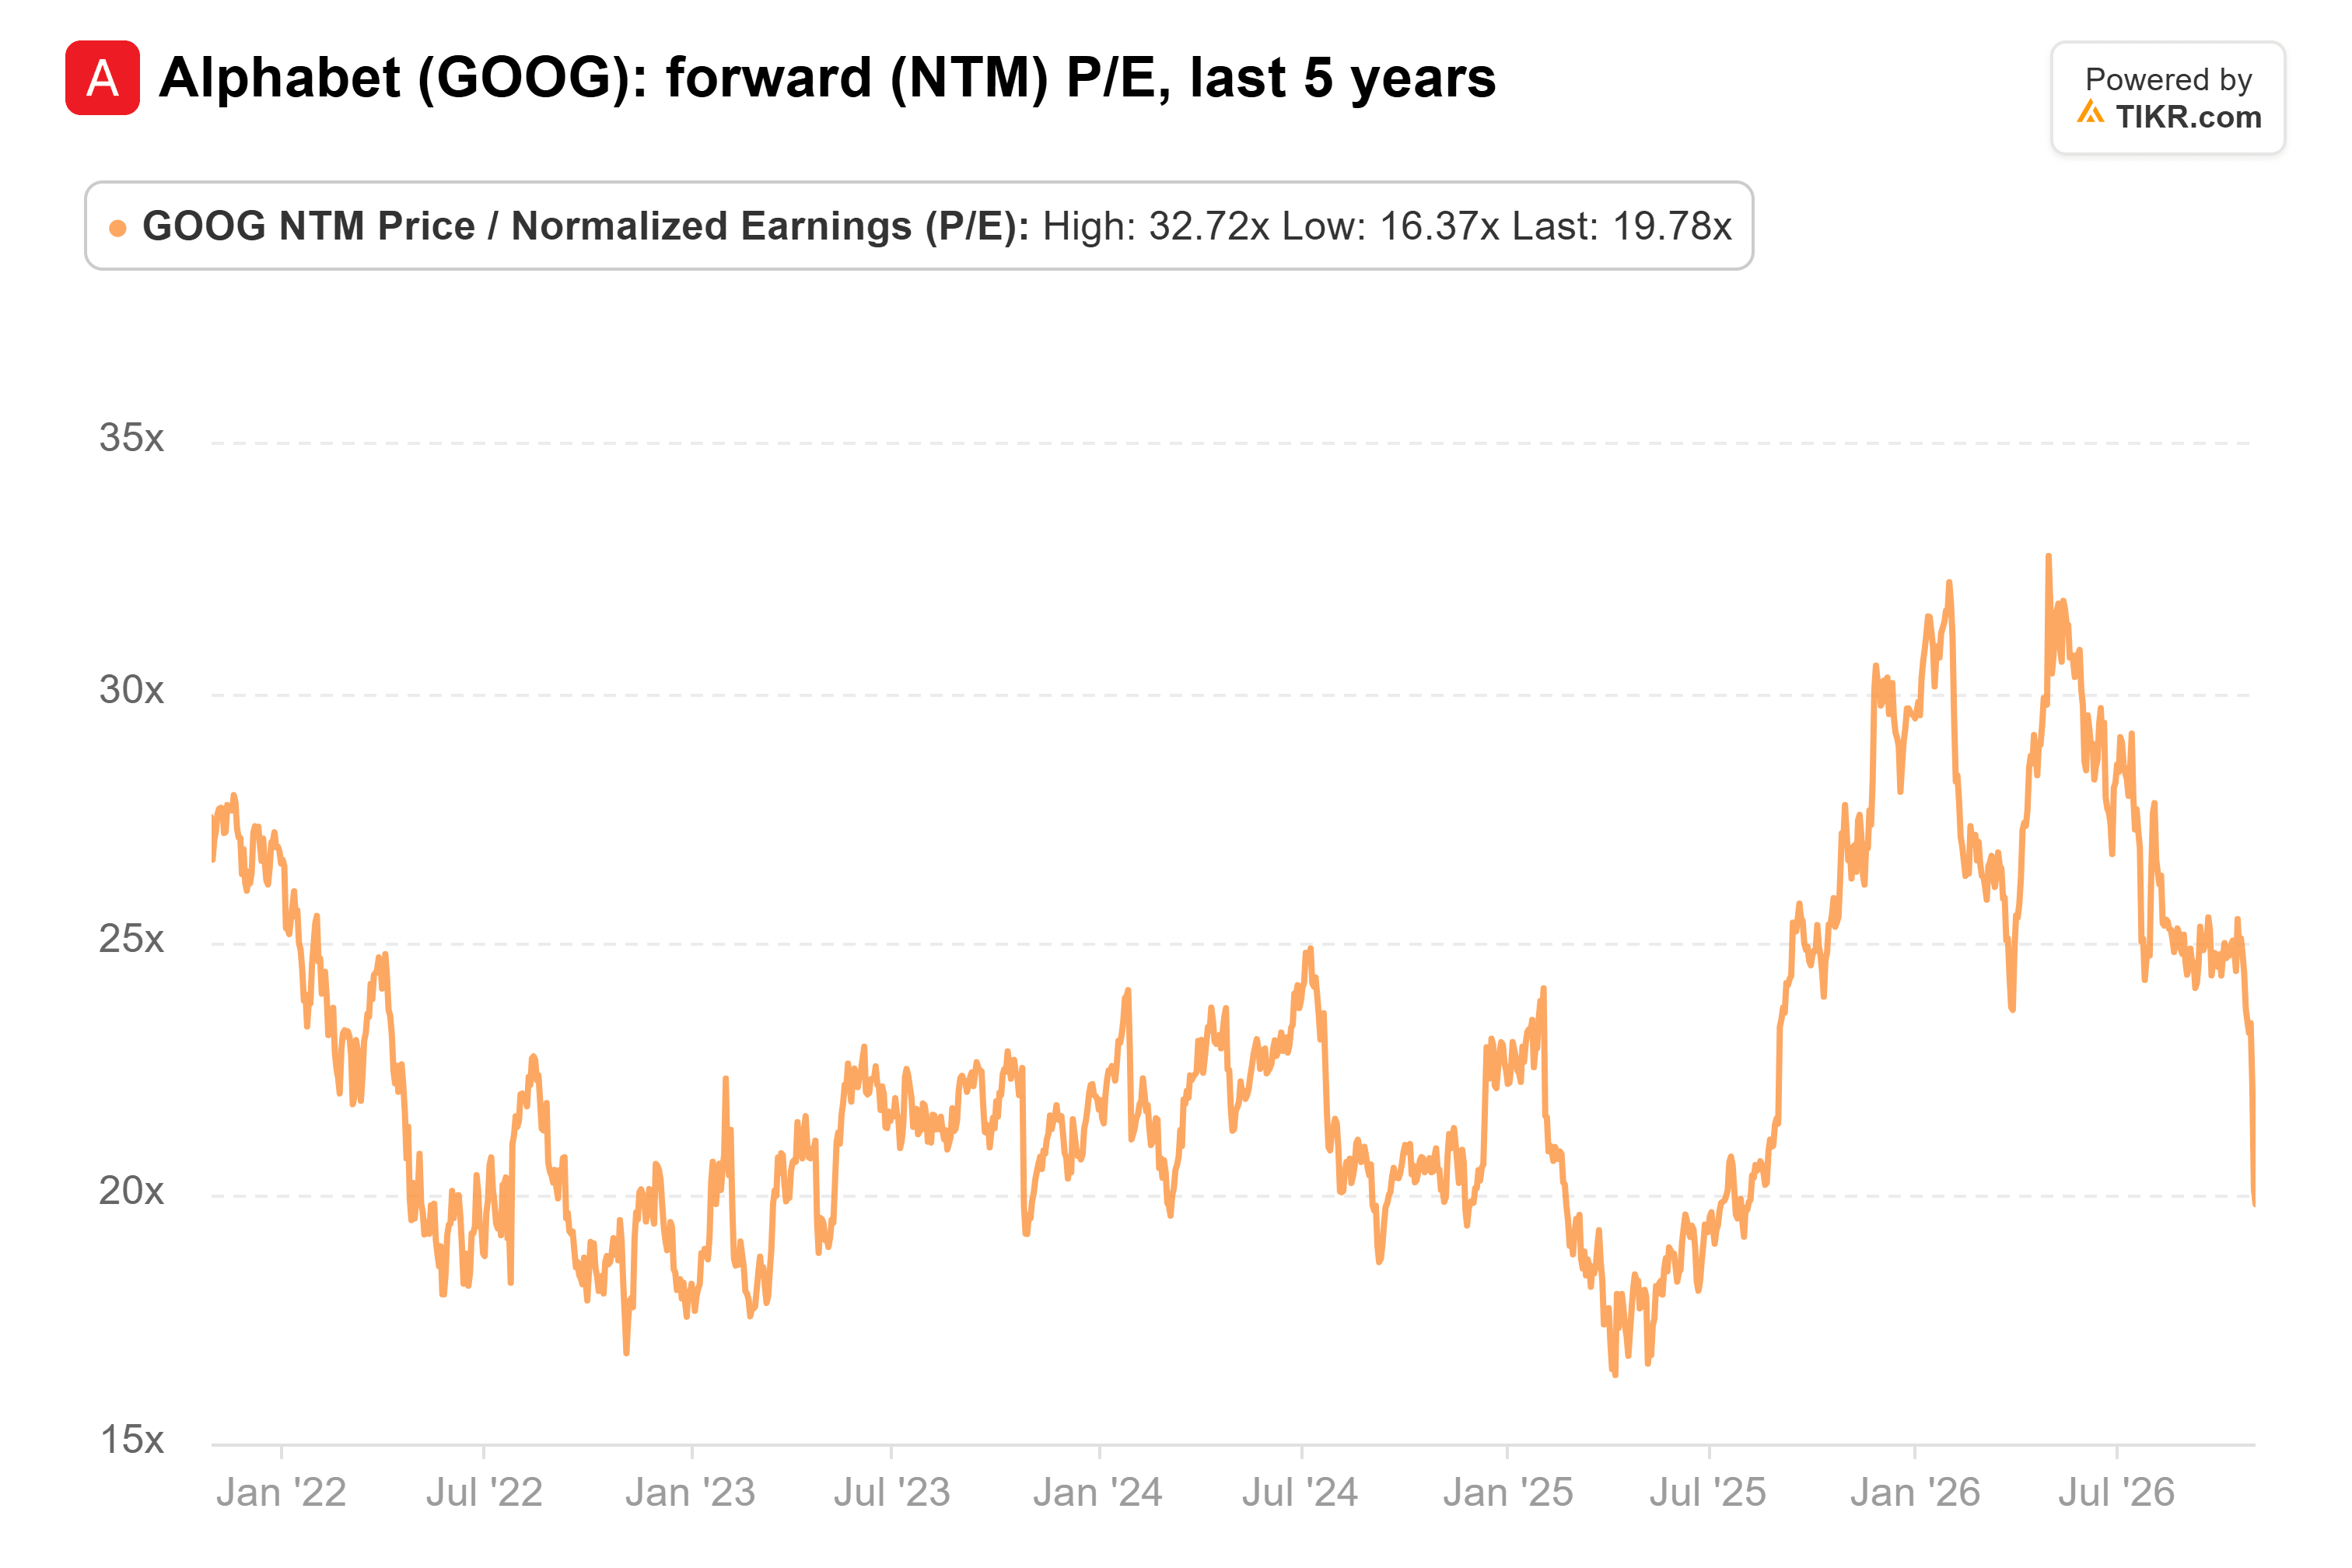
So Alphabet costs more than Galloway’s 14.6, but it’s still cheap by its own standards.
Cloud now earns like Google Services
And the business is still growing fast. Revenue reached $128 billion in the third quarter, up 25% from a year earlier:

More than half of that growth came from Google Cloud, where revenue jumped 103% to $30.7 billion. Cloud’s operating margin rose to 36.2%, from 23.7% a year earlier. Management had warned that renting outside computing capacity, which started this quarter, would weigh on that margin, and it rose anyway.
By the second quarter, a new dollar of Cloud revenue was already adding about as much operating income as a new dollar from Google Services, the segment that holds Search. So even if Search slows, Alphabet has a second business earning like it.
And Search is slowing. Chief Business Officer Philipp Schindler blamed part of the third quarter’s slowdown on lower monetization in AI Mode. That’s the cannibalization Galloway worries about. Alphabet also sold $12.4 billion of new stock and issued $28.7 billion of notes in the quarter. Those are his second mortgages, in practice.
I’m with Galloway
A company growing revenue 25% a year at this size, with a second business that now earns like its first, looks like a buy at 20x forward earnings. I think the market is pricing Search as if it’s already shrinking, when Search & other revenue still grew in the third quarter.
Of course, the spending isn’t done. CFO Anat Ashkenazi expects capex to “increase significantly in 2027,” and the figure is due on the fourth-quarter call, likely in early February. If it outruns Cloud’s $561 billion backlog, I’d take Galloway’s mortgage worry more seriously than his buy call.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!