Key Takeaways
- Walmart beat and raised its outlook again on Nov. 19, but the stock fell anyway at 42x forward earnings.
- CFO John David Rainey expects the next five years to beat the last five.
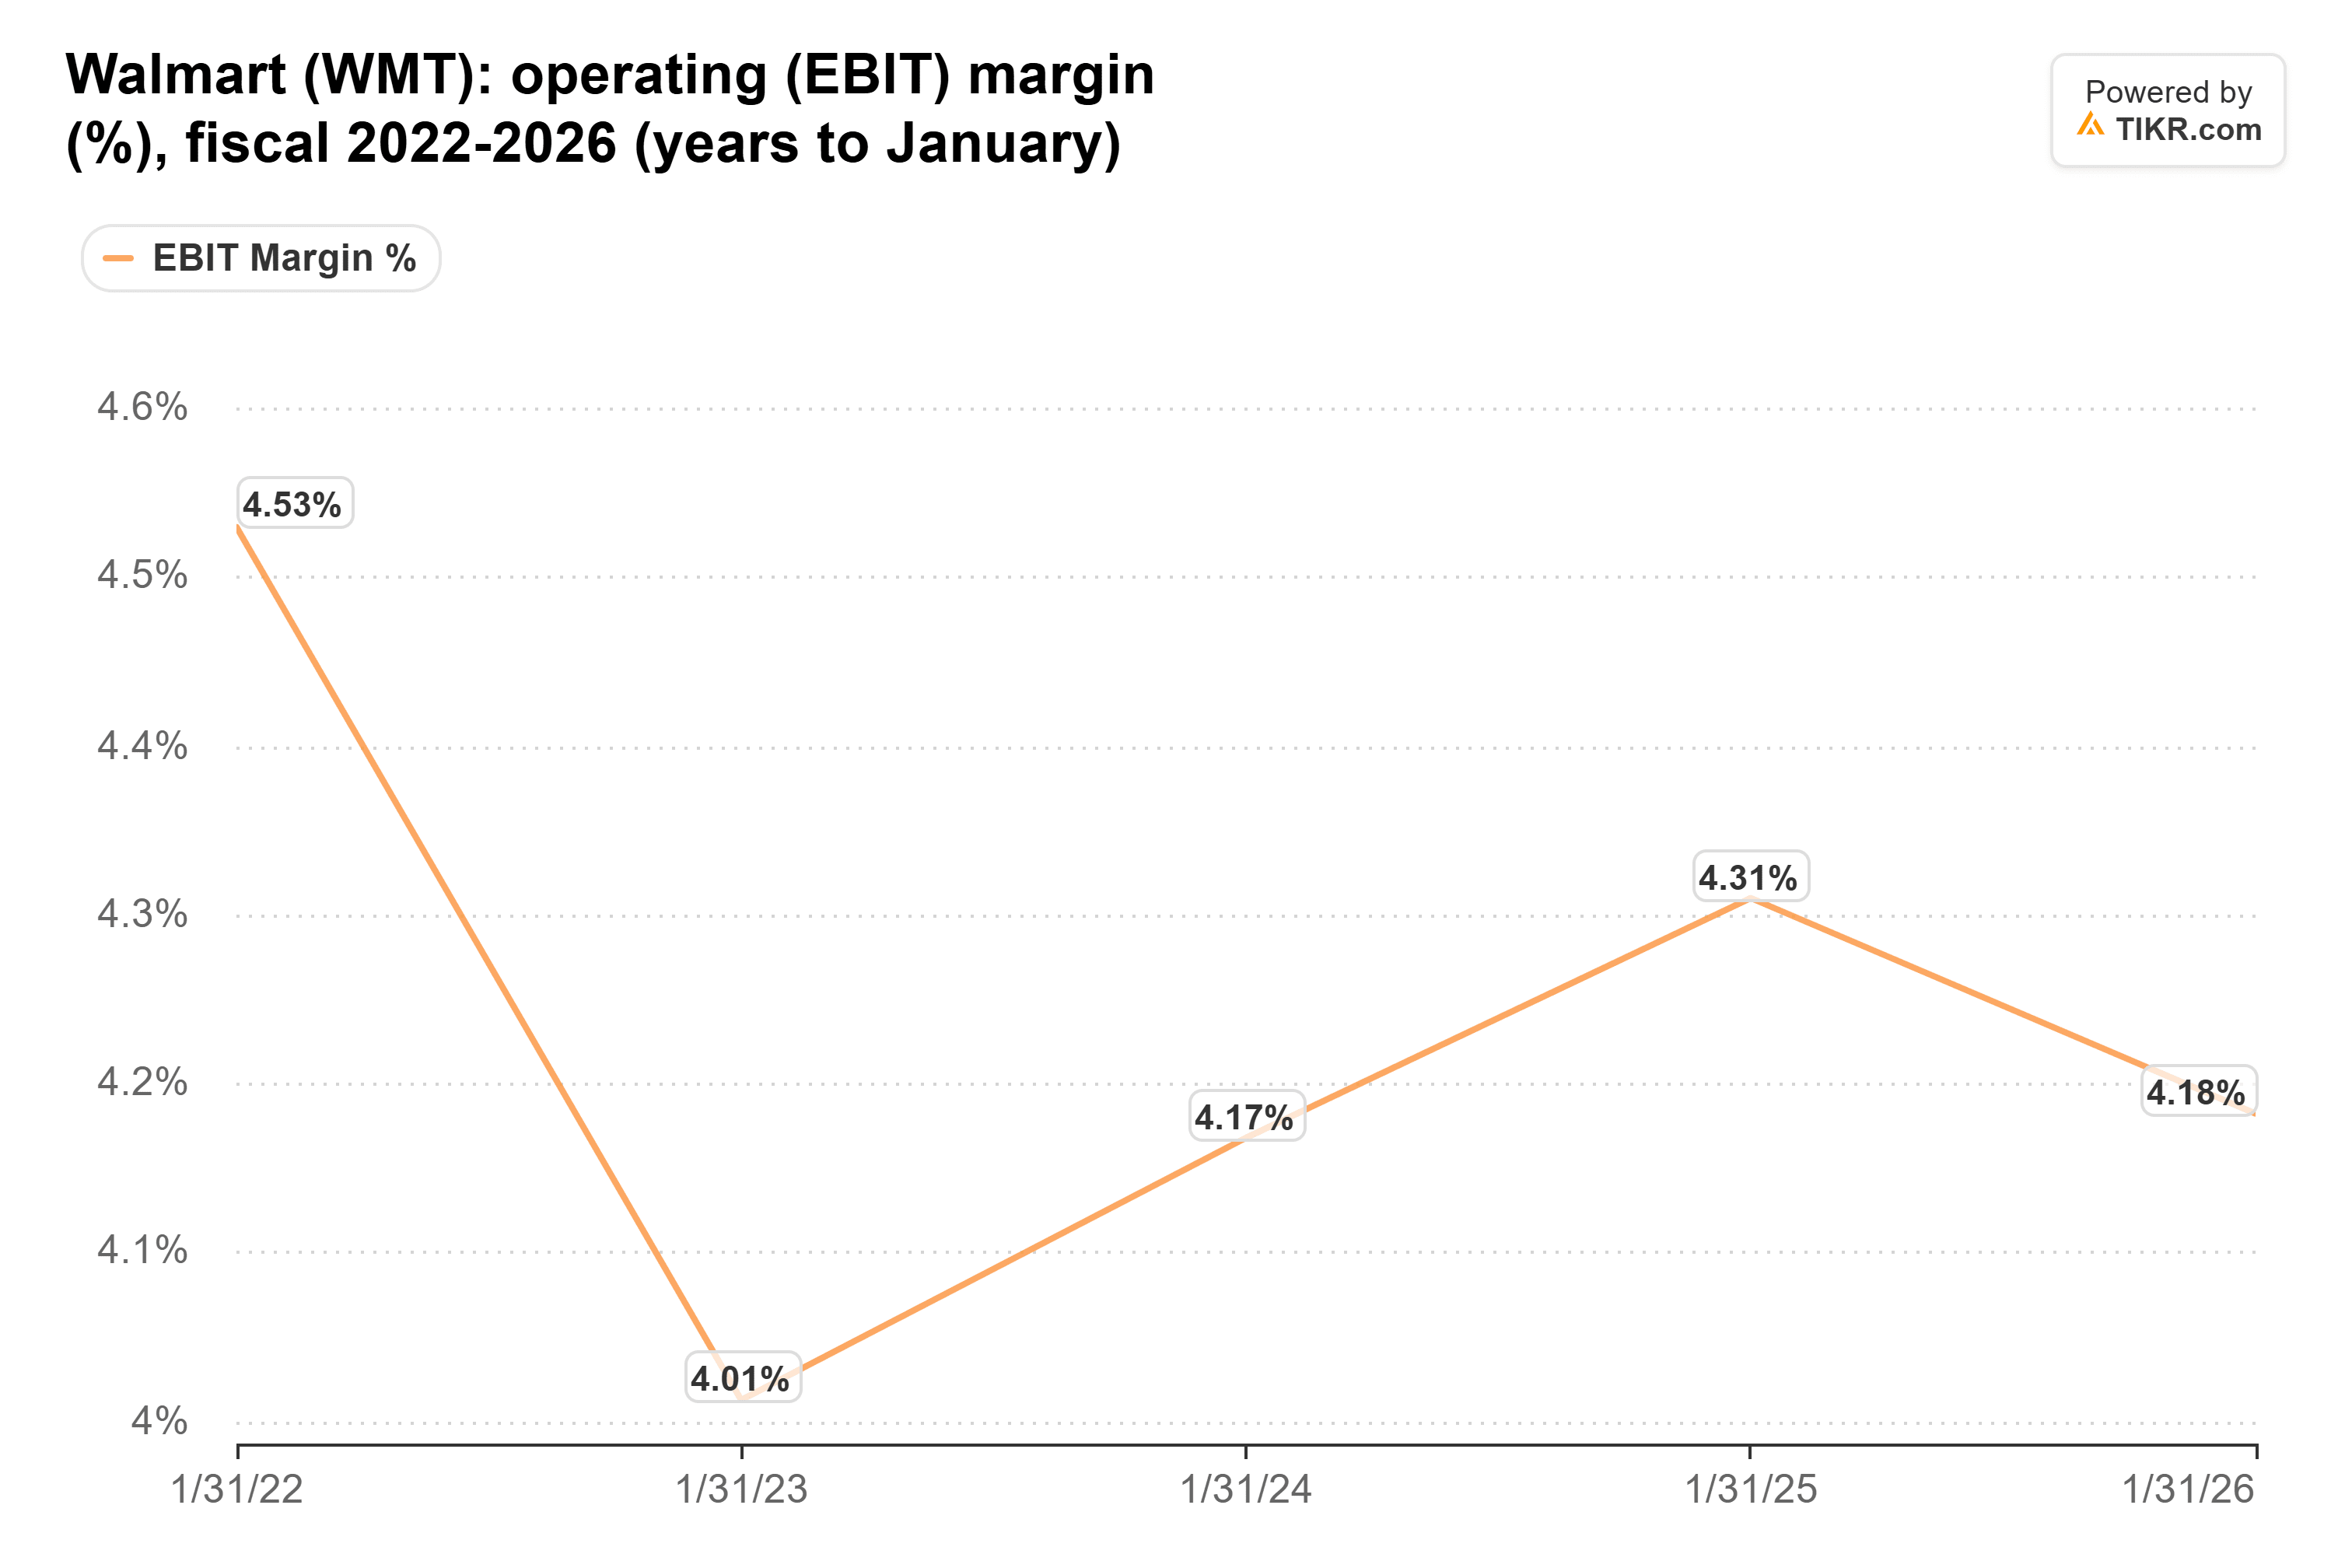
- Its operating margin slipped from 4.5% to 4.2% over five fiscal years, yet analysts expect about 11% EPS growth a year.
- At that multiple, investors are paying for a wider margin.
Walmart (WMT) beat estimates and raised its full-year outlook for the second straight quarter on Nov. 19. The stock fell anyway.
The price helps explain why. At 42x forward earnings, Walmart trades well above Amazon (AMZN) at 25x and Target (TGT) at 17x. Only Costco (COST) trades richer, at about 49x.
On the call, UBS’s Michael Lasser asked whether Walmart could sustain its “algorithm” of 4% sales growth and up to 8% operating income growth next year. CFO John David Rainey said operating income would keep growing faster than sales next year, then went further: “we expect the next five years to look better than the last five years.”
At 42x, it has to.
Analysts Already Expect a Much Better Five Years
Over the last five fiscal years, Walmart’s normalized EPS grew about 5% a year. Analysts expect roughly twice that pace from here, about 11% a year, to $3.62 in the year ending January 2029:
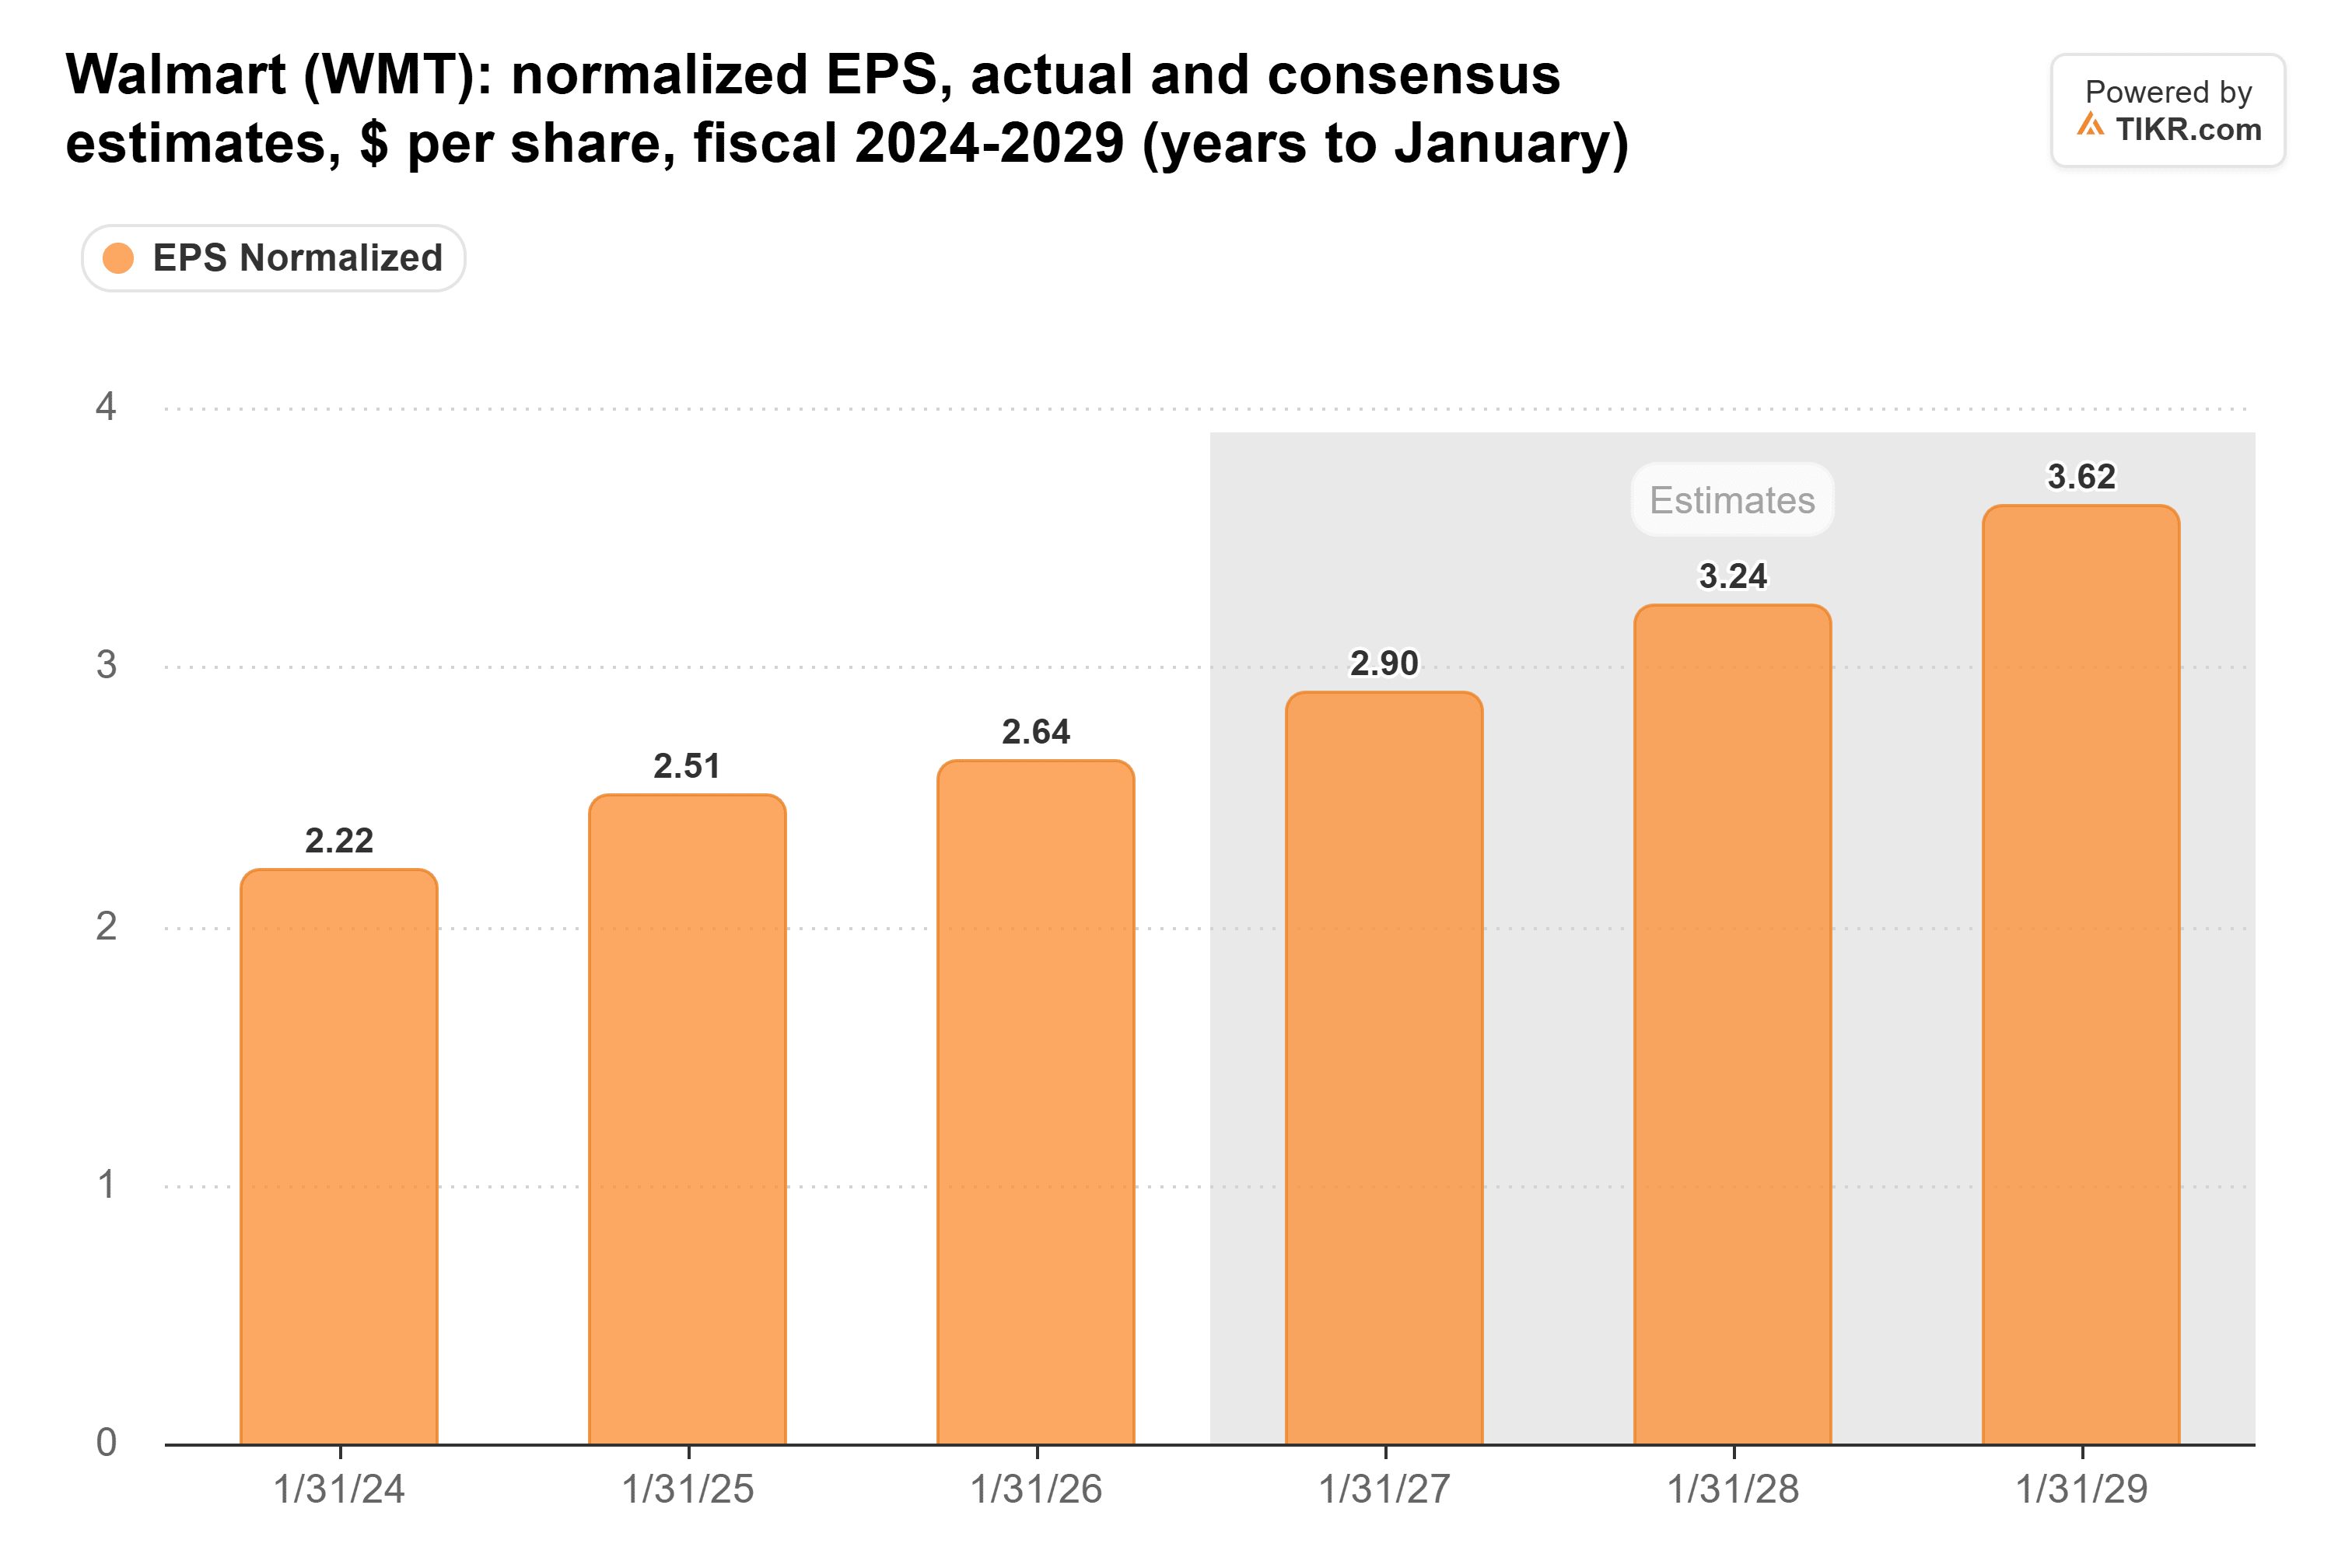
At about 4% sales growth, getting there would take a wider margin, with some help from buybacks. Instead, its operating margin slipped from 4.5% to 4.2% over those five years:
Investors Are Already Paying for Walmart’s Better Five Years
That 42x is below February’s peak of 47x but well above Walmart’s five-year average of 30x:
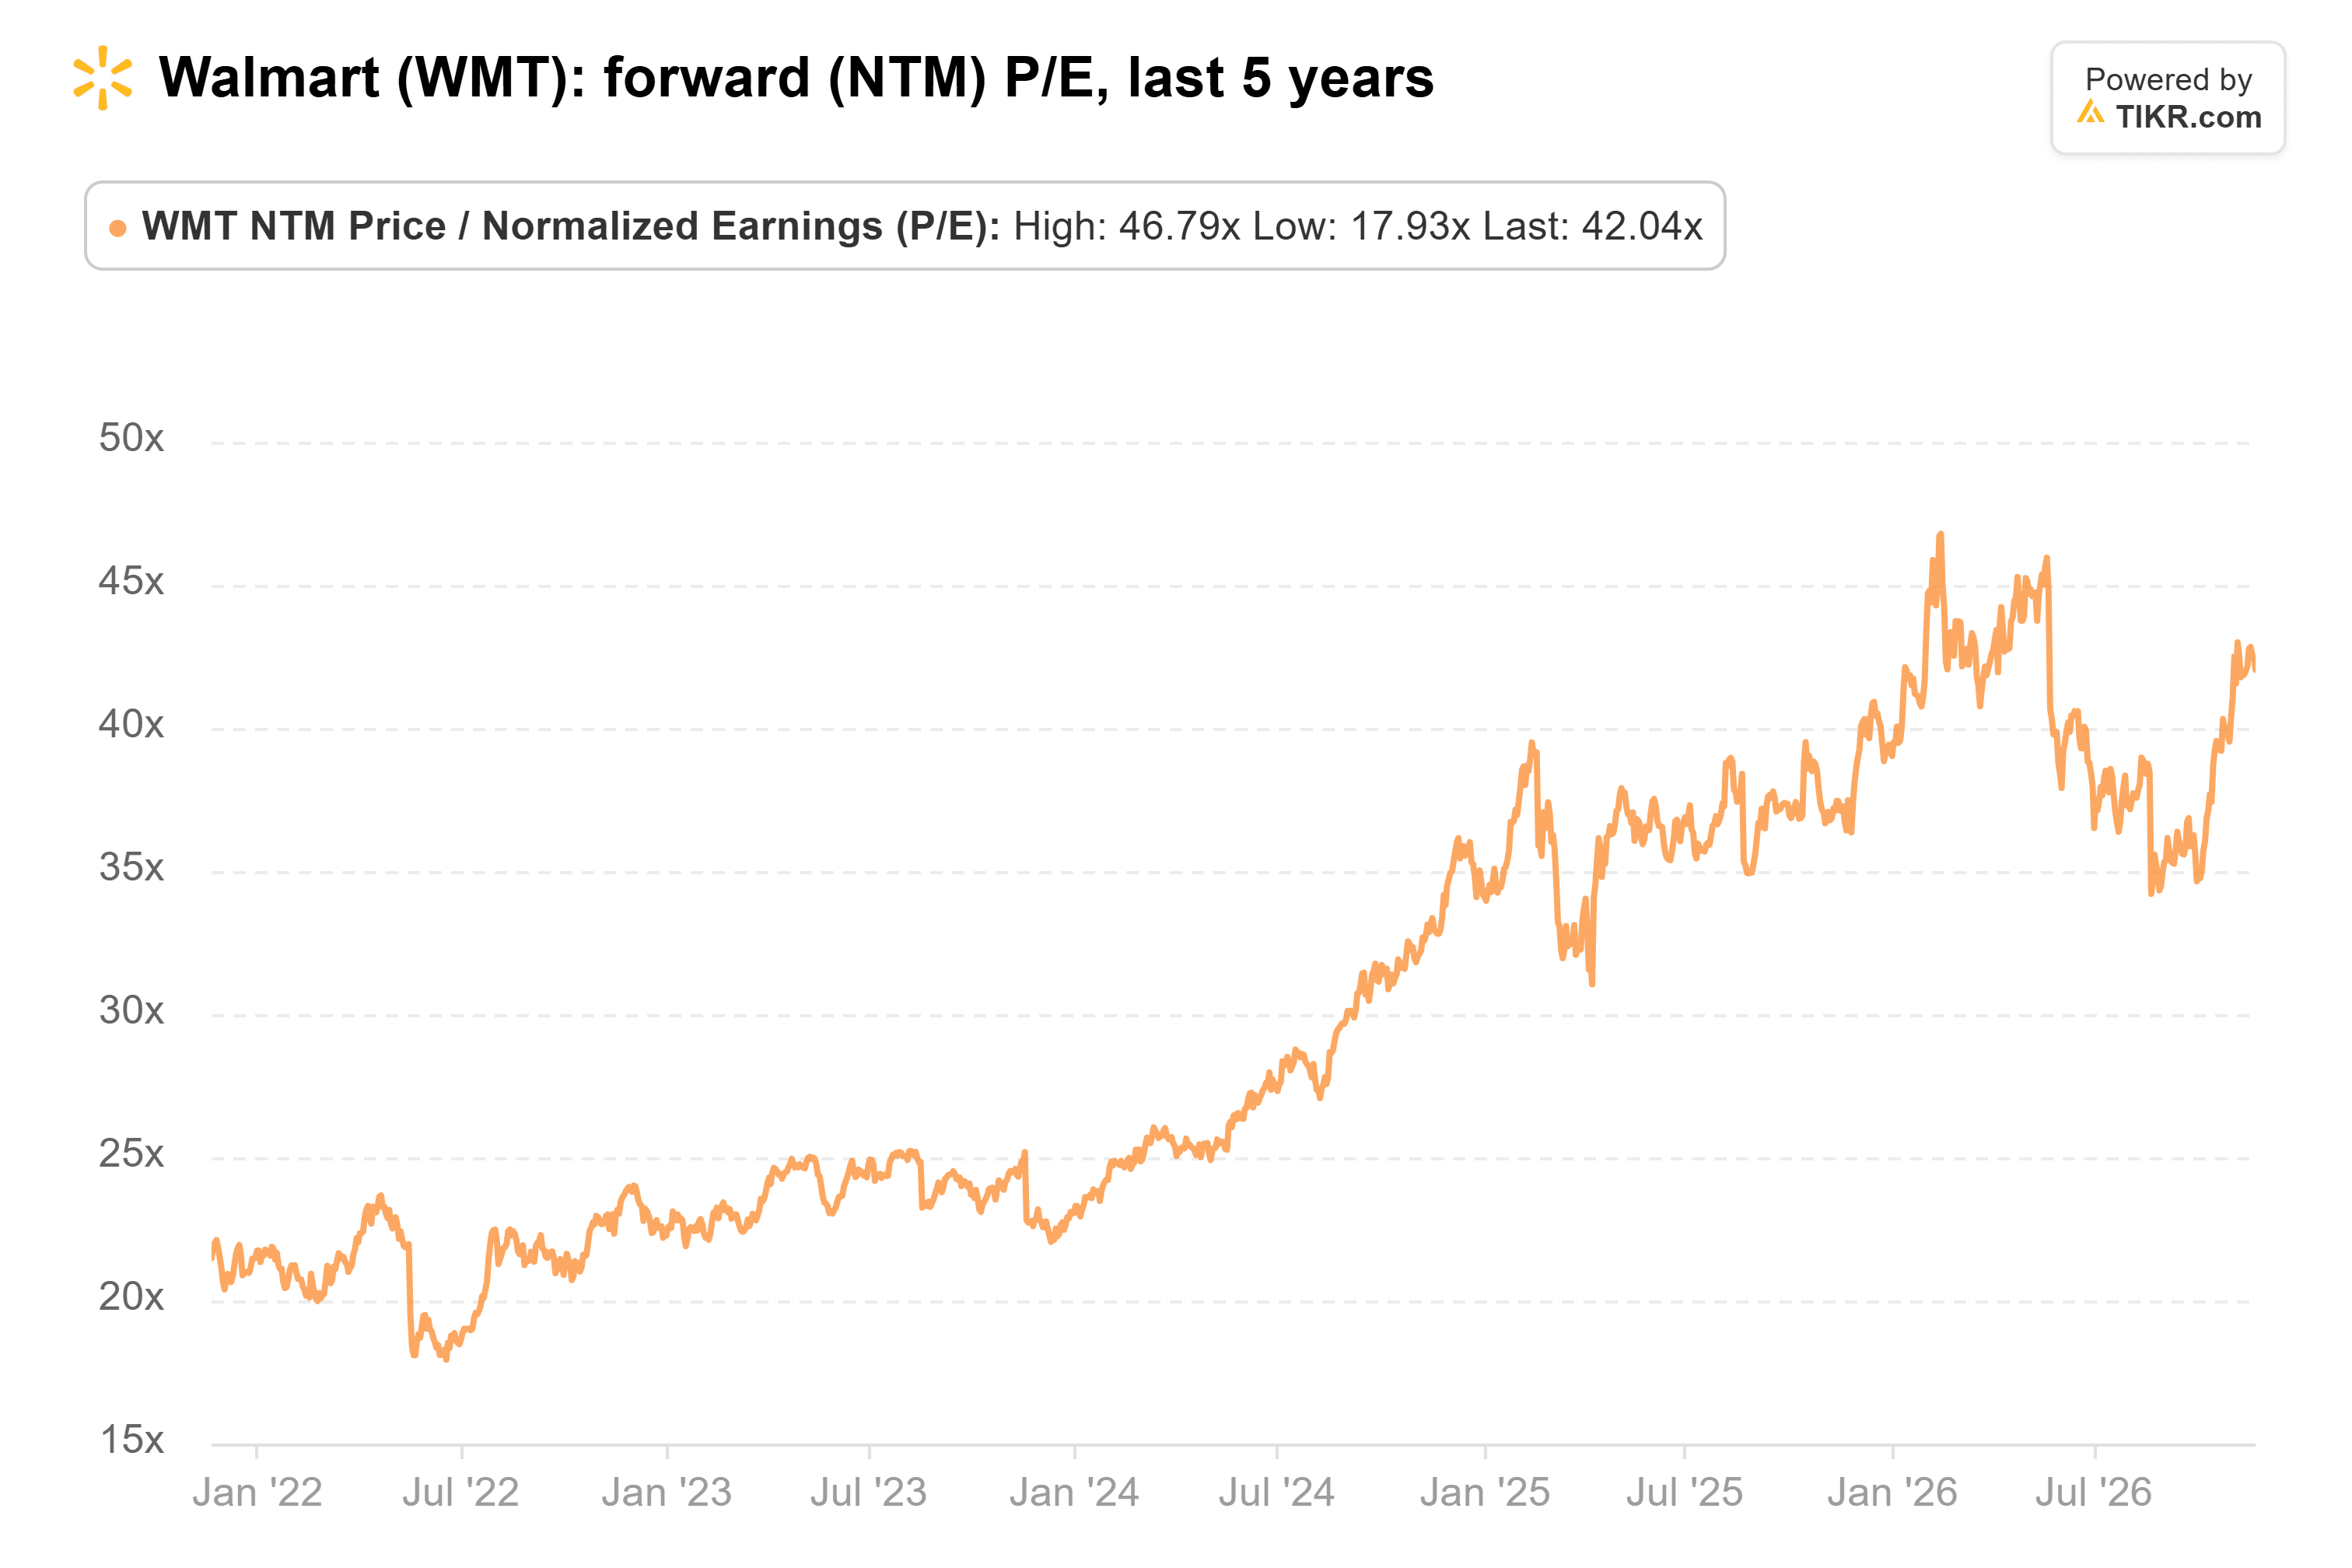
If it drifted back to that average, earnings would need to rise about 40% to hold the share price, or a bit over three years at 11% a year.
E-Commerce Is Close to Paying Its Own Way
Rainey’s case rests on e-commerce, which earned a U.S. incremental margin above 12% in the quarter. He said U.S. e-commerce is “pretty close to breakeven without advertising, which was pretty remarkable.” He expects low double-digit incremental margins from here.
E-commerce is about 25% of Walmart’s business, and Rainey sees that share rising another 10 to 15 percentage points over five to seven years. If it pays its own way, more of each ad dollar and membership fee falls through to profit.
Amazon’s North America segment shows where that can lead: an operating margin of about 7% in 2025, against 5.2% for the Walmart U.S. segment in the year ended January 2026.
TIKR Tracks 44 Analysts on Walmart. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Walmart, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Walmart’s Analyst Ratings
Walmart Keeps Spending the Gains
Rainey said diesel and transportation will add “over $2 billion of incremental costs” this year. Of the new Walmart+ and Sam’s Club Plus bundle, he said: “We’re cannibalizing and refunding fees that members have paid by essentially giving one of those memberships away for free.” In the third quarter, adjusted operating income grew 5.5% in constant currency, only about a point faster than sales.
Better Has to Mean a Wider Margin at Walmart
I think Rainey is right that the next five years will look better. But investors are already paying for a sustained rise in margin, and the last five years went the other way. I’d want a lower price, or proof in the margin, before paying a multiple this close to Costco’s.
February’s outlook for the year to January 2028 is the first test. Operating income guided at about twice the pace of sales, with EPS at or above the $3.24 consensus, would back Rainey’s five-year claim.
So What Is Walmart Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Walmart could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!