Key Takeaways
- PDD Holdings shares jumped 11% after its third-quarter adjusted profit beat estimates on flat revenue, and Jefferies raised its price target to $120, 40% above the stock price.
- Online marketing revenue grew 12% while transaction services revenue fell 12%, and a 17% cut in marketing spending helped lift profit.
- JD.com also cut its marketing spending this quarter, and Alibaba’s customer management revenue fell, so PDD’s ad growth stood out.
- On analysts’ 2028 estimates, $120 is about 8x earnings, so the target still holds up if those estimates slip.
PDD Holdings (PDD) is still 31% below its January high, even after today’s 11% jump on its third-quarter results. Wall Street’s average price target has fallen 23% this year, to $114. But Jefferies’ Thomas Chong raised his target to $120 from $118 and kept his Buy rating, 40% above today’s $86.
PDD wasn’t the only one spending less to win shoppers. Its sales and marketing spending fell 17%, and JD.com (JD) cut its marketing spending too, which lifted its non-GAAP operating margin to 2.4% from 0.1%. Alibaba (BABA) saw its customer management revenue fall 5% (up 1% like-for-like), while PDD’s online marketing revenue grew 12%.
A rough year for Temu’s owner
PDD missed on first-quarter revenue in May. Then the EU’s €3 duty on cheap parcels took effect on July 1, part of Europe’s push for €6 billion from cheap imports, and second-quarter net income fell 12%. And on Nov. 9, Morgan Stanley downgraded the stock to Equal Weight and cut its target to $90 from $129.
Jefferies is betting on the ads
Third-quarter revenue was flat at RMB108.3 billion, short of the roughly RMB116 billion analysts expected. Online marketing revenue grew 12% to RMB59.8 billion, while transaction services revenue fell 12% to RMB48.5 billion. Non-GAAP earnings of RMB21.04 per ADS beat the roughly RMB19 analysts expected. Chong called the earnings beat a surprise and tied the higher target to better ad revenue and profitability.
TIKR tracks 35 analysts on PDD Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PDD Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PDD Holdings’ Analyst Ratings
Does $120 add up?
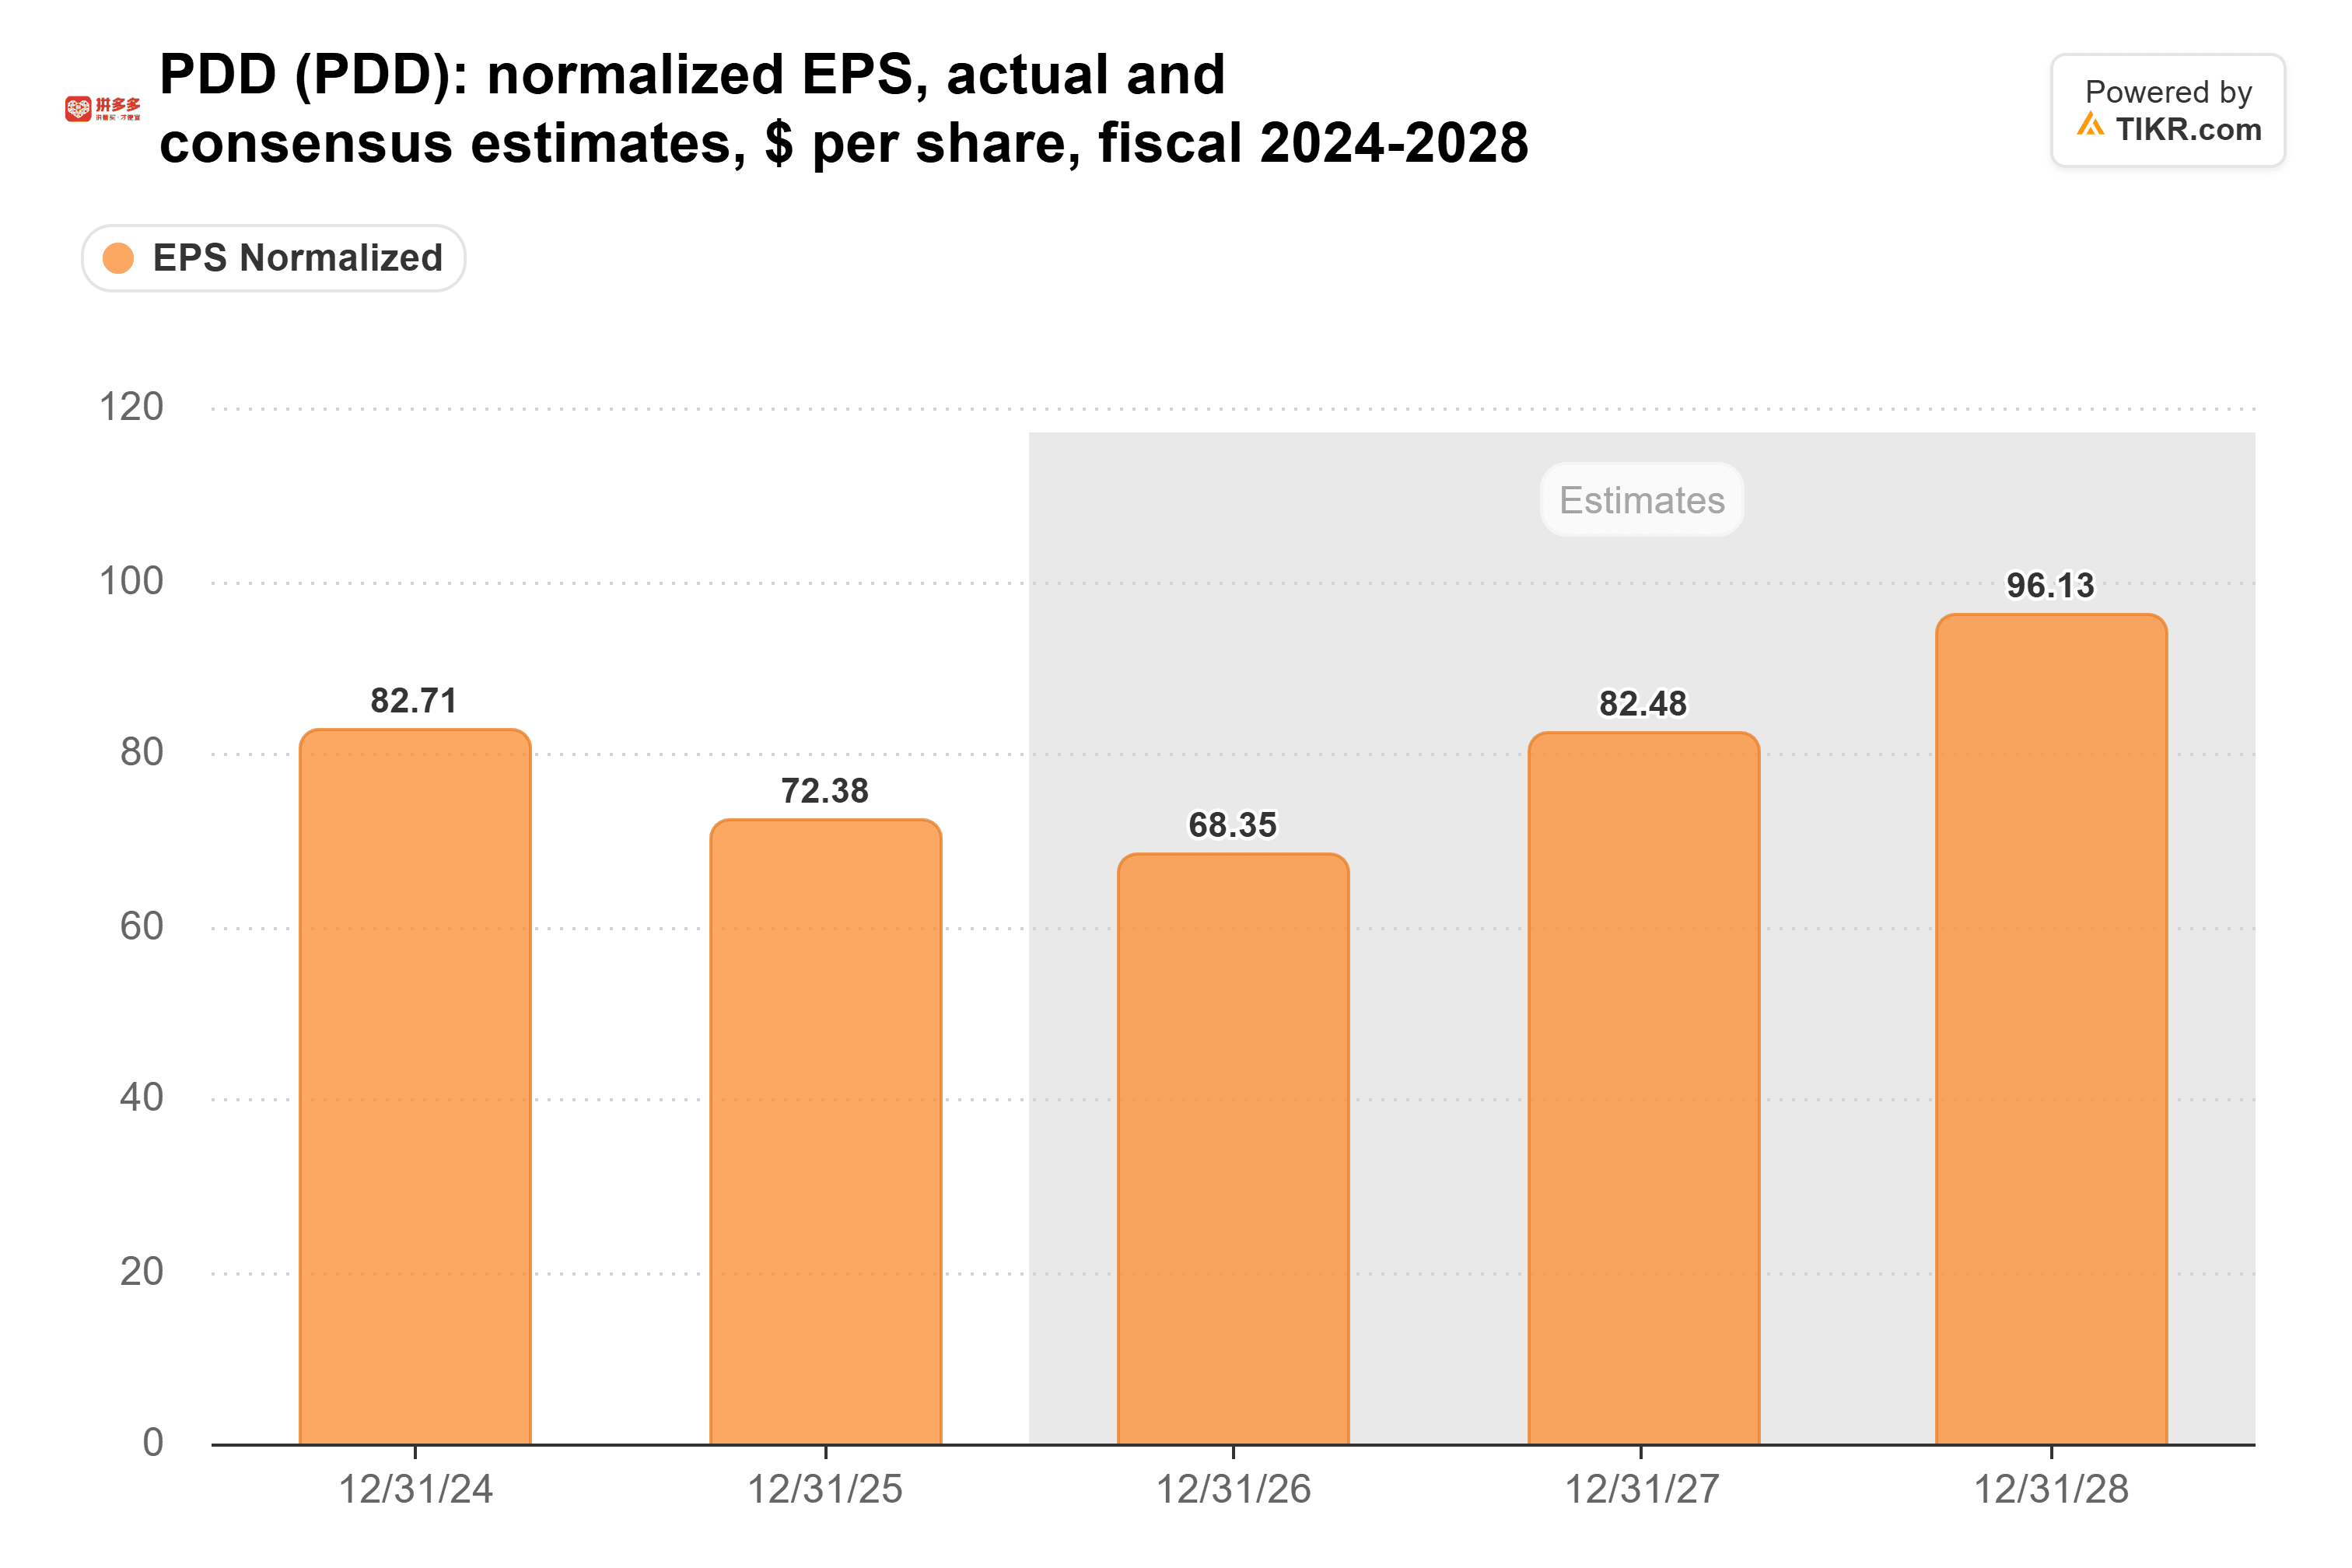
The 35 analysts who cover PDD have targets from $82 to $151. Their earnings estimates barely moved over the past 90 days, and all of them came before today’s report:
The stock trades near its lowest multiple of the past five years:
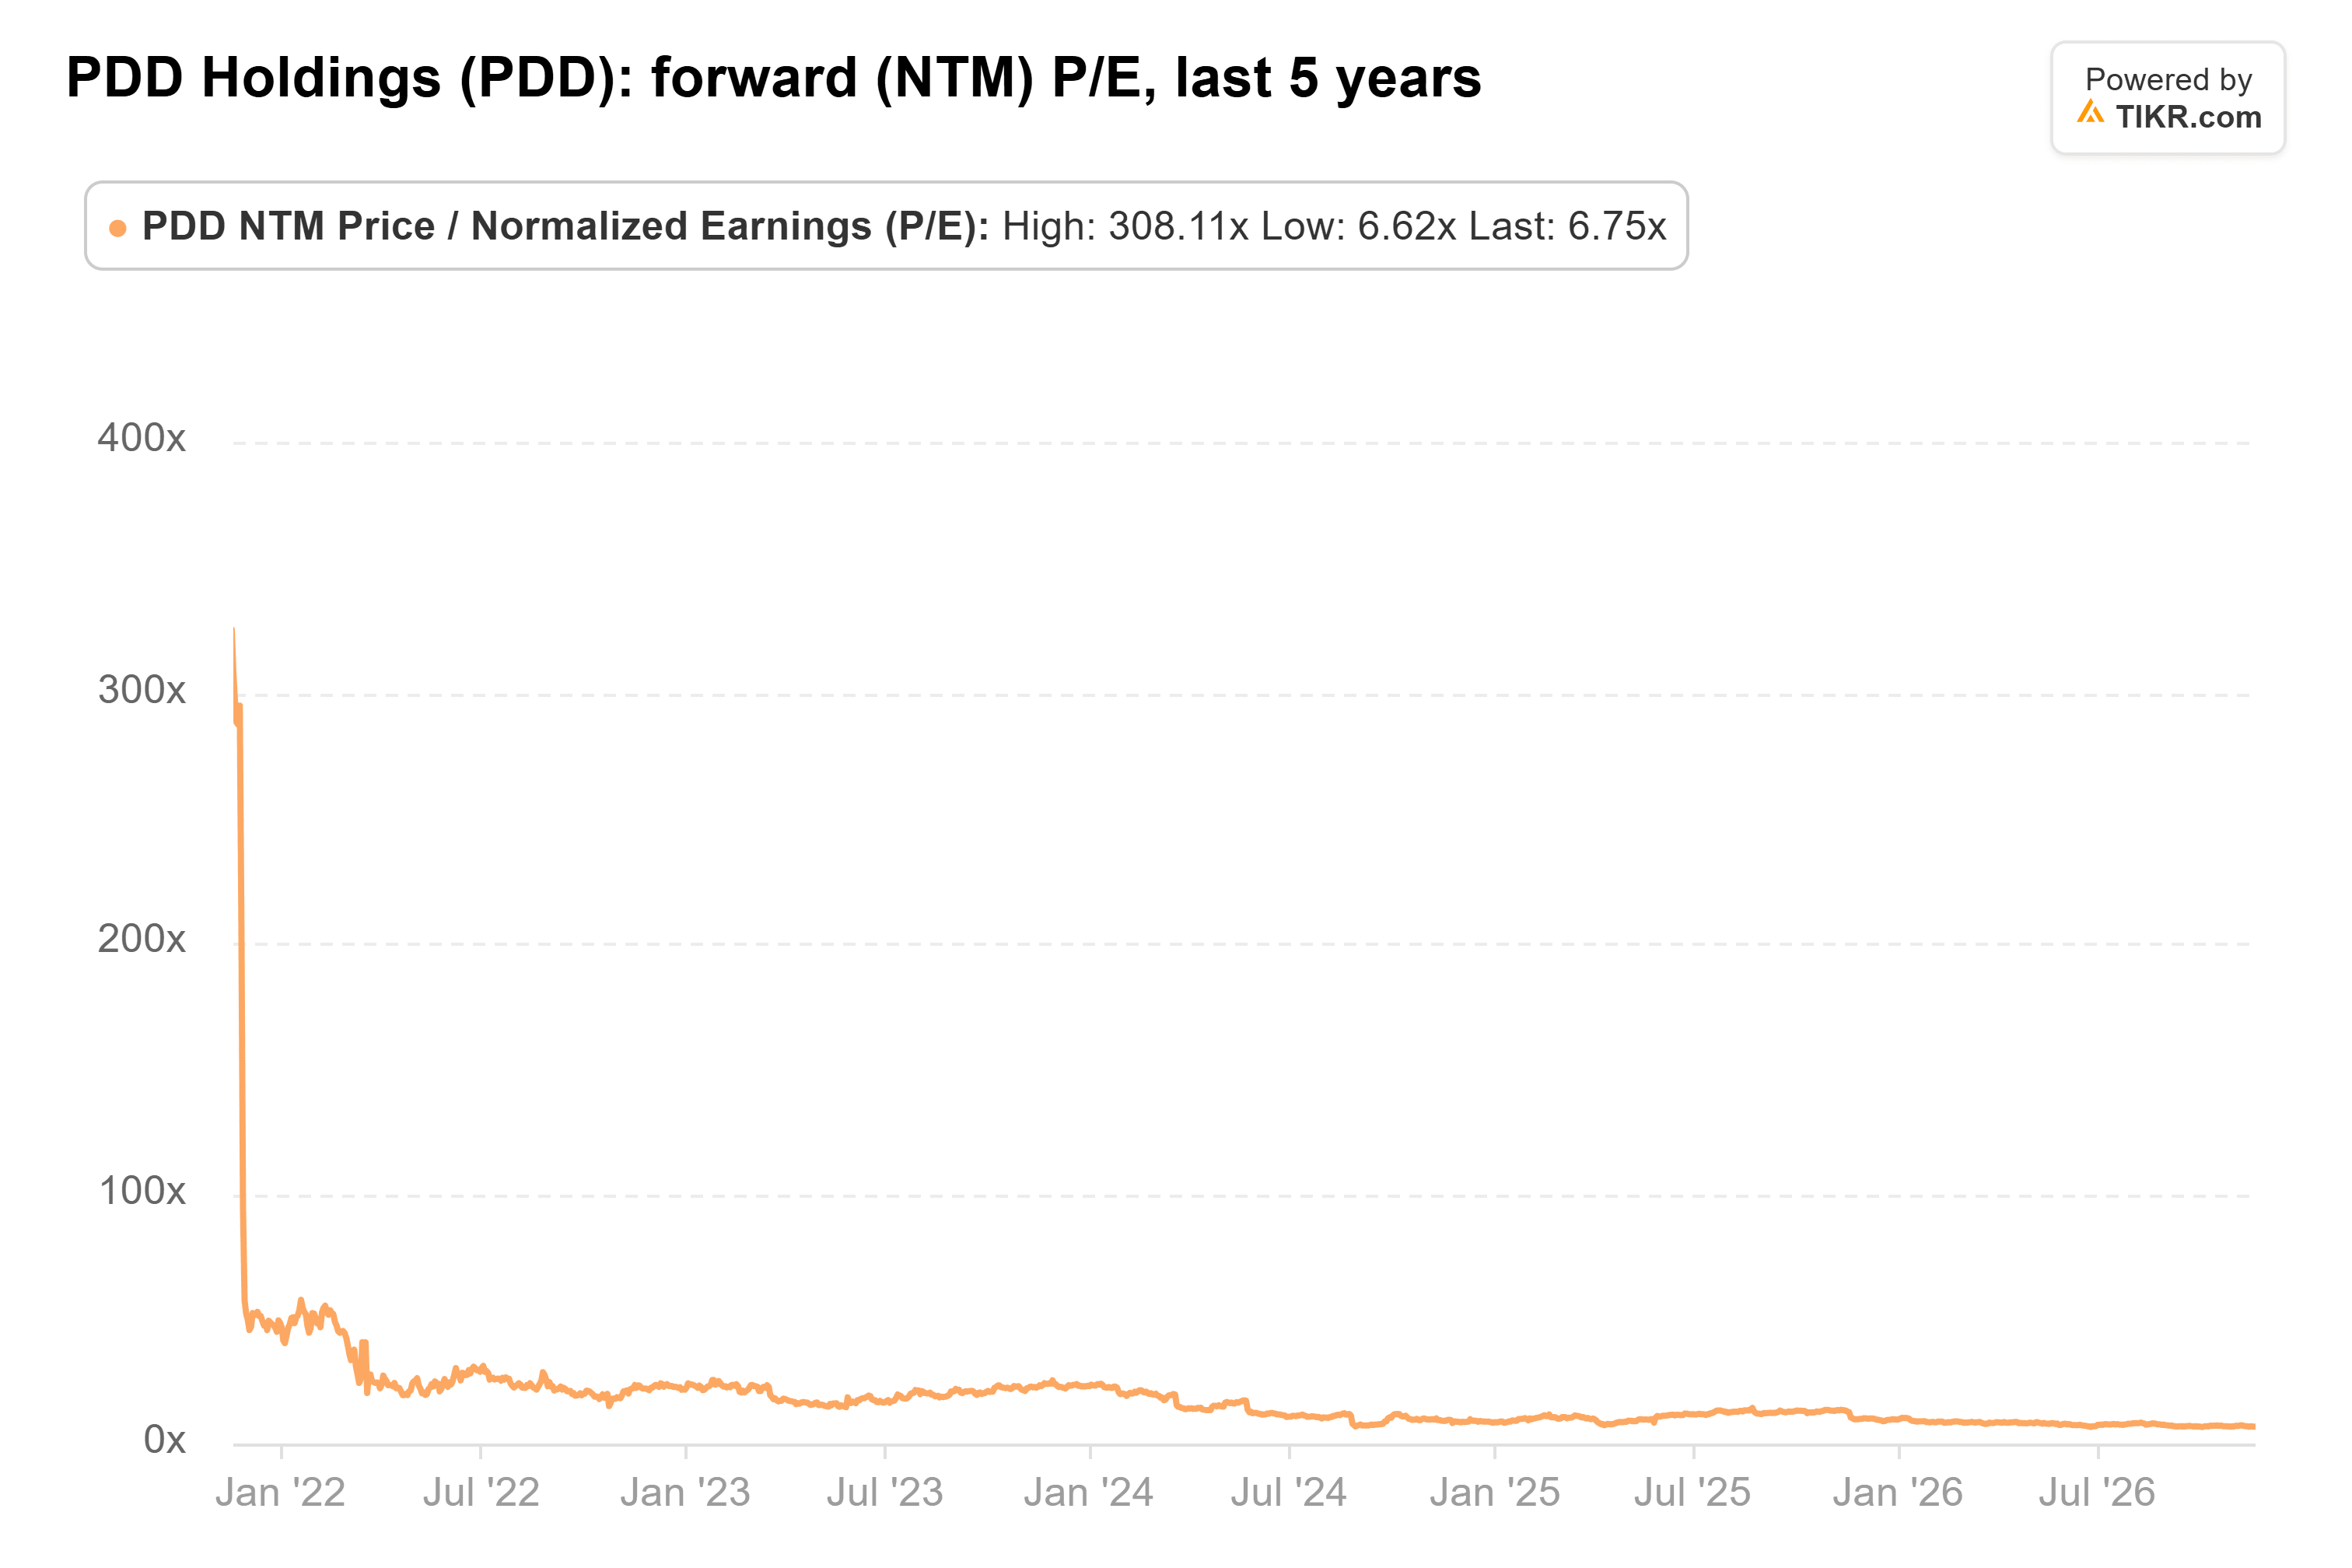
That 6.8x is in line with JD.com’s 6.9x and below Alibaba’s 10.6x. Analysts expect RMB96.13 per ADS for 2028, or about $14.34, so $120 is 8.4x those earnings. To get there, earnings have to grow 25% and the multiple has to rise 12%. And if 2028 earnings came in no higher than the next twelve months’ $11.47, $120 would still be 10.5x, below the stock’s three-year average of about 12x.
The target asks for very little
The risk is that the multiple stays stuck. PDD held RMB455.4 billion ($67.9 billion) of cash and short-term investments on Sept. 30, more than half its market value, and it hasn’t paid a dividend or bought back stock since it listed in 2018.
Still, I’d side with Jefferies: $120 asks for little more than the earnings growth analysts already expect. The next test is fourth-quarter results in March. Analysts’ 2026 revenue estimate from before the report implies about RMB139 billion for the quarter, 12% more than a year earlier, so transaction services revenue has to stop shrinking.
So what is PDD Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PDD Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!