Key Takeaways
- MPLX raised its quarterly distribution 12.5% on Nov. 3, and TC Energy declared a quarterly dividend of C$0.8775 a share on Nov. 5, up from C$0.85 a year earlier.
- MPLX yields 8.6% against TC Energy’s 3.9%, and at each one’s 5-year growth rate, $10,000 in MPLX would pay about $40,000 over 20 years, against about $8,600 for TC Energy.
- TC Energy’s dividend has more room, at 1.96x distributable cash flow in fiscal 2025 against MPLX’s 1.40x, but TC Energy carries more debt, at 6.02x net debt to EBITDA against 4.05x.
- MPLX’s $750 million asset sale is a headwind for 2027 that management hadn’t planned on.
MPLX (MPLX) raised its quarterly distribution 12.5% on Nov. 3. On its third-quarter call, it called the raise “the fifth consecutive year of double-digit increases.” Two days later, TC Energy (TRP) declared a quarterly dividend of C$0.8775 a share, up from C$0.85 a year earlier, and it counts “26 consecutive years of dividend growth.”
Both are building for the same surge in natural gas demand.
So if I can only pick one, which is it?
| Metric | TC Energy (TRP) | MPLX (MPLX) |
|---|---|---|
| Dividend yield | 3.9% | 8.6% |
| Dividend growth, fiscal 2020-2025 | 1.0% a year | 8.2% a year |
| Record (company’s own count) | 26 straight years of dividend growth | 5 straight years of double-digit raises |
| Distributable cash flow coverage, fiscal 2025 | 1.96x | 1.40x |
| Distributable cash flow coverage, fiscal 2026 consensus | 1.86x | 1.28x |
| Net debt / EBITDA (last 12 months) | 6.02x | 4.05x |
| Interest coverage (EBIT / interest, last 12 months) | 2.07x | 4.03x |
Source: TIKR, at today’s prices; TC Energy’s per-share figures in Canadian dollars; records from each company’s third-quarter call.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
TC Energy has room to spare
On Nov. 5, TC Energy raised its 2026 comparable EBITDA outlook to C$11.8 billion to C$12.0 billion and said it expects 5% to 7% growth a year through 2031. It plans to grow the dividend 3% to 5% a year. CFO Sean O’Donnell said on the third-quarter call: “This is an internally funded plan. No equity, no M&A, no capital rotation needed to achieve this plan if we can deliver as expected.”
Distributable cash flow has covered the dividend in every fiscal year since 2016. Coverage ranged from a 1.23x low in fiscal 2024 to 1.96x in fiscal 2025:
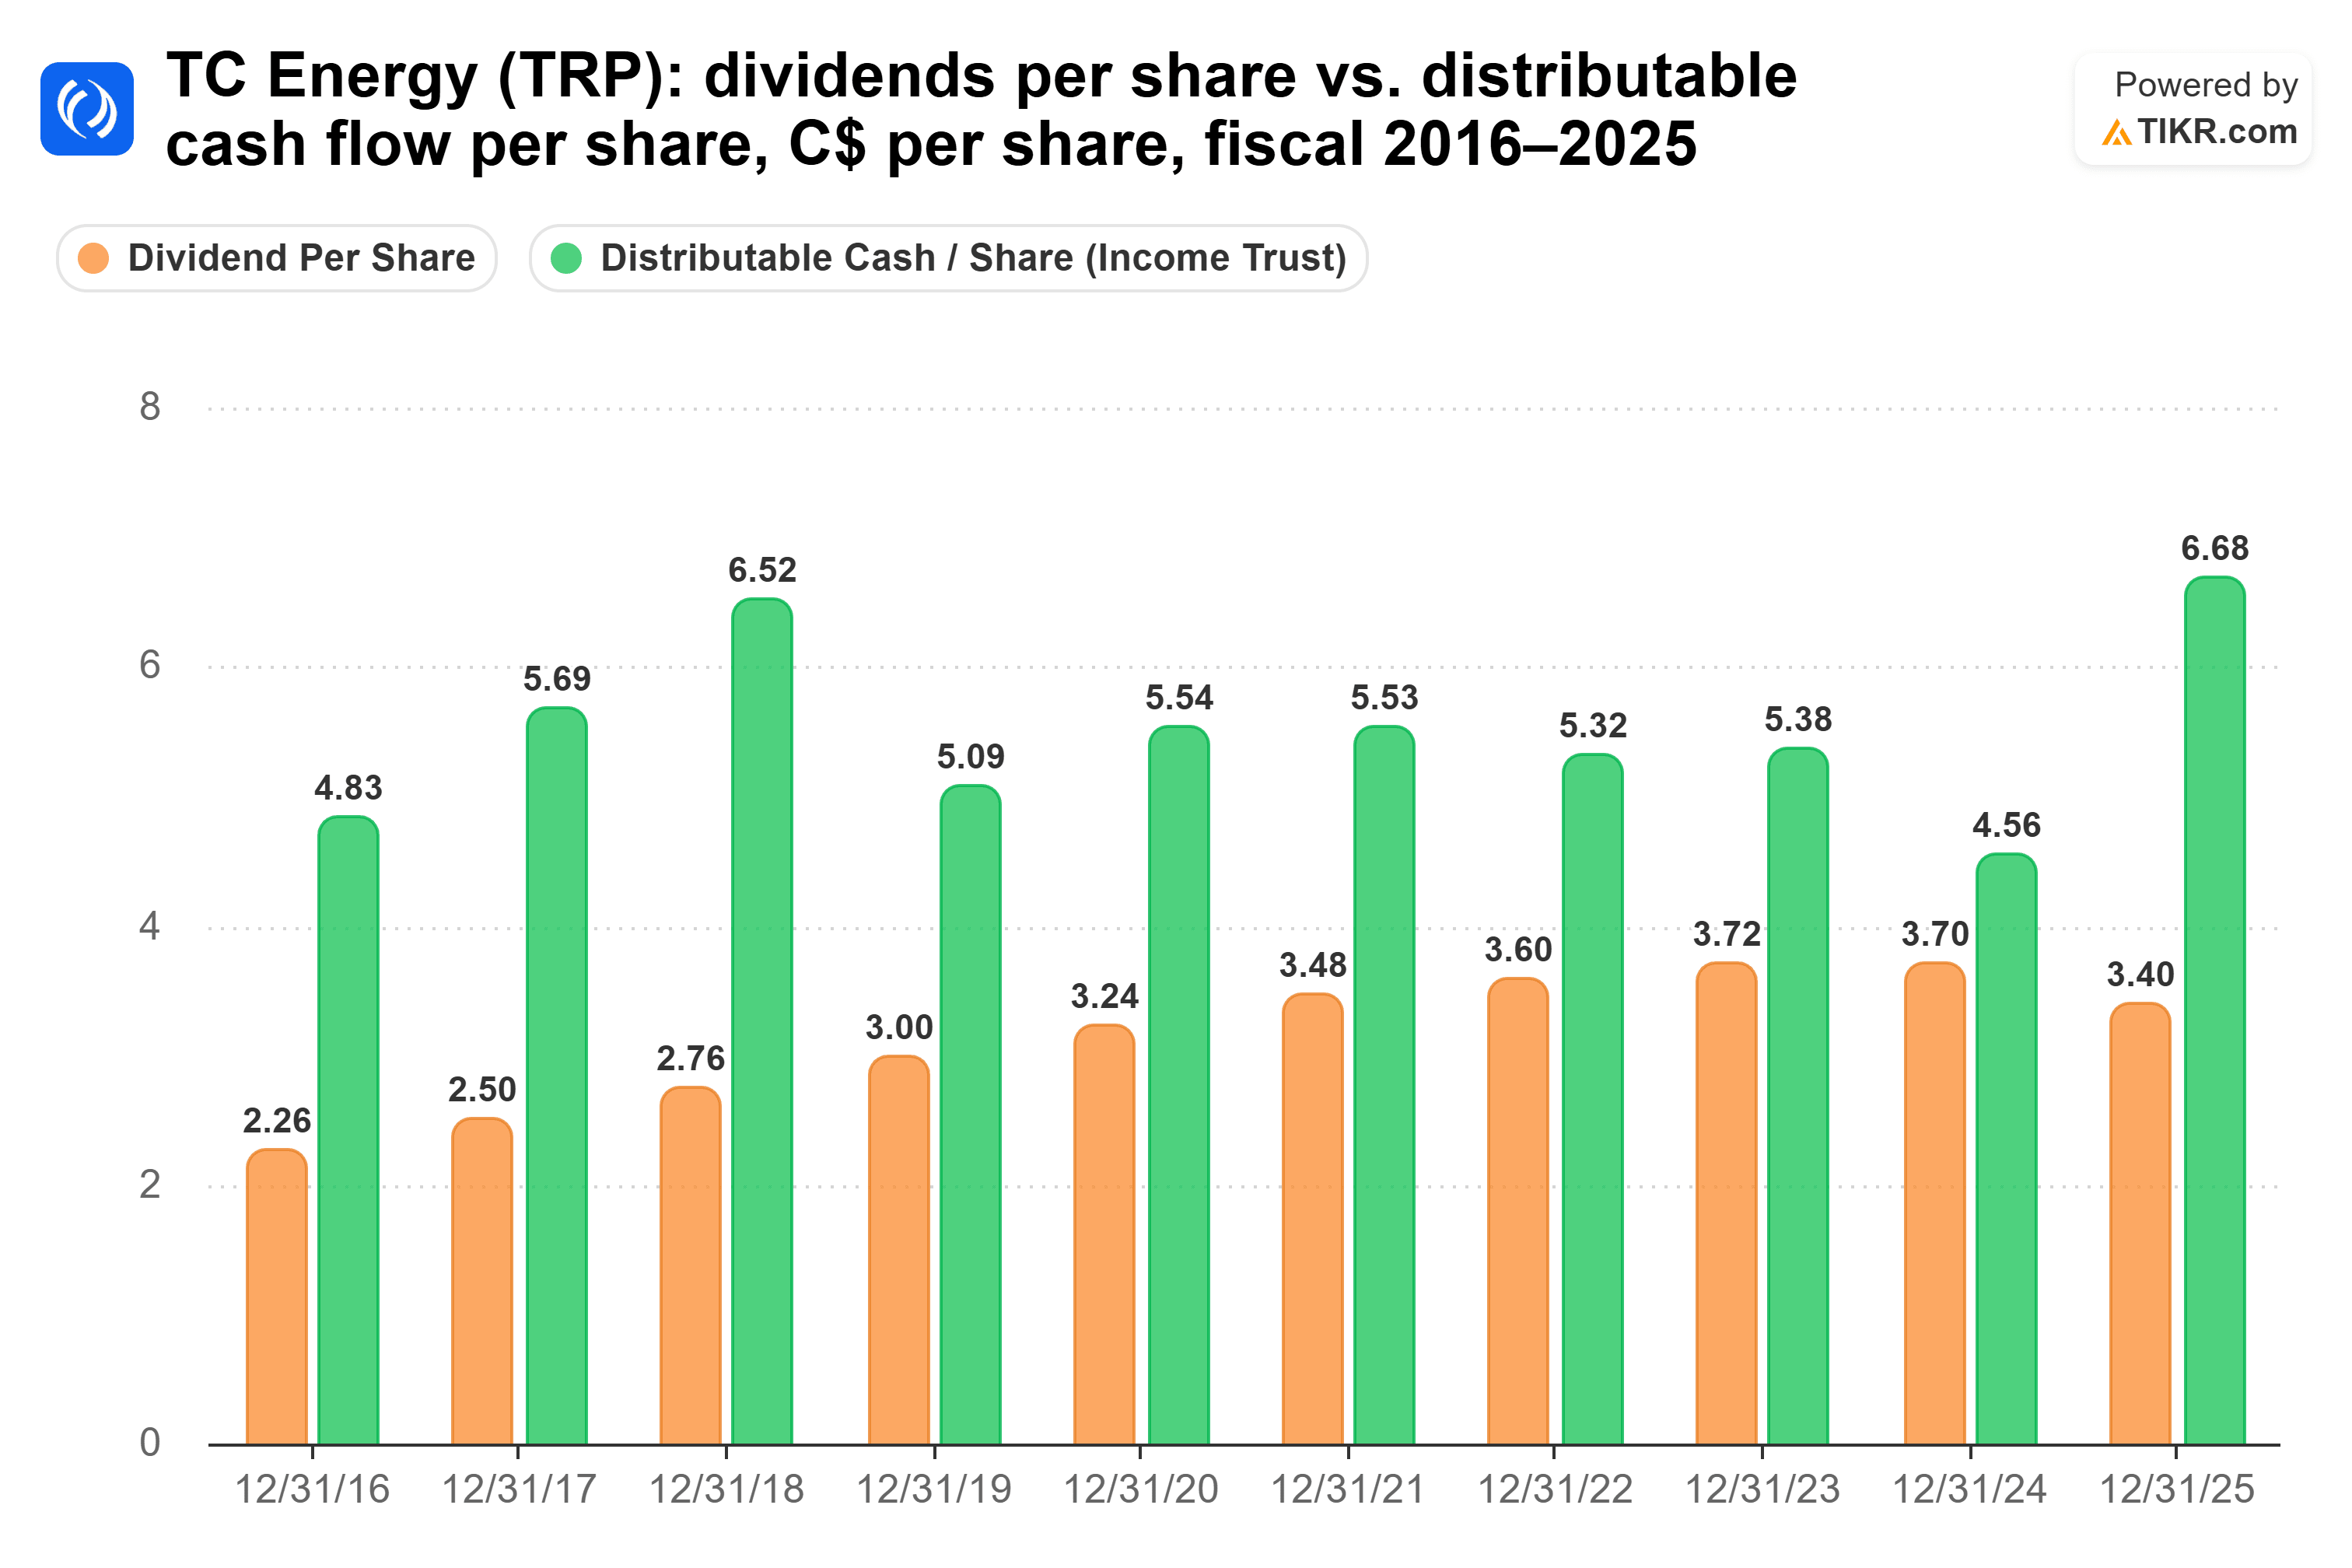
Analysts expect a still-wide 1.86x for fiscal 2026.
The dividend is set in Canadian dollars, so its US-dollar value moves with the currency. Canada also withholds tax on dividends paid to US holders. Its weak spot is debt.
MPLX pays more, with less to spare
MPLX works the same gas boom from the gathering and processing end. In the third quarter, adjusted EBITDA rose 5.3% from a year earlier to $1.86 billion.
Distributable cash flow has covered the distribution in every year on the chart. Coverage ranged between 1.35x in fiscal 2021 and 1.68x in fiscal 2019:
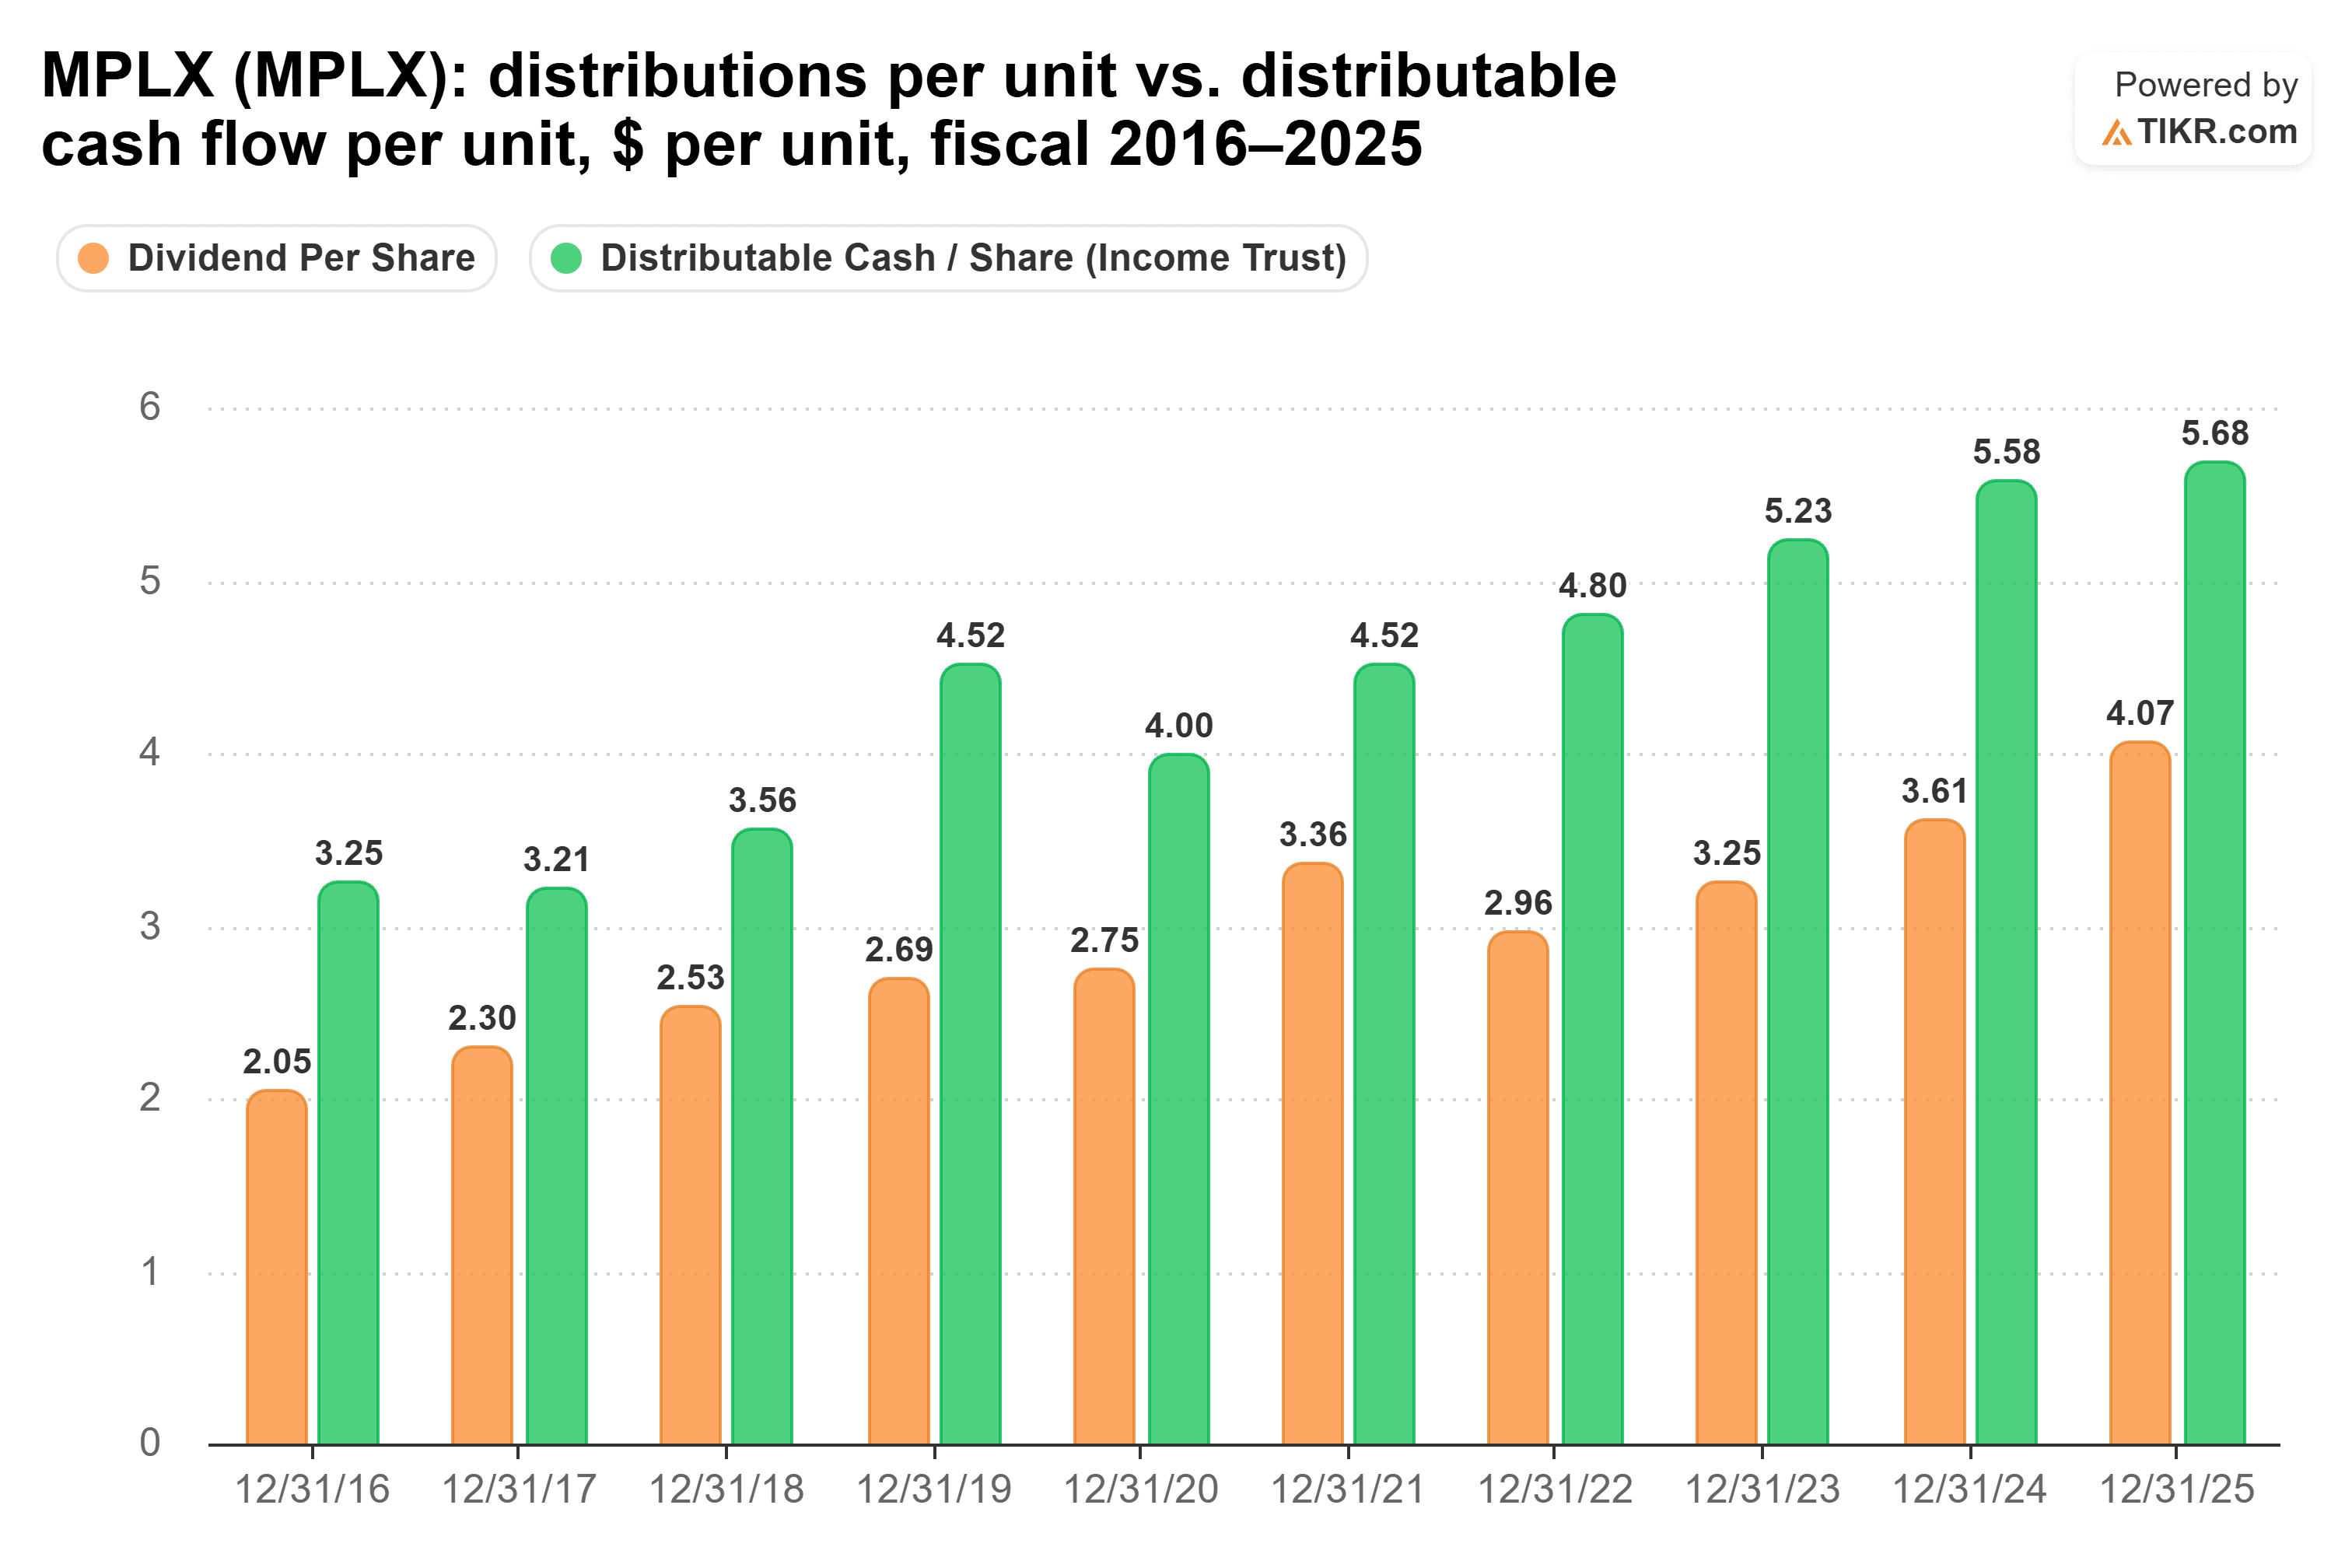
The cushion is thinner than TC Energy’s: 1.40x in fiscal 2025 and 1.28x in analysts’ fiscal 2026 consensus. Management says it’s comfortable at 1.3x and still expects its 2027 raise to outpace distributable cash flow growth, so that cushion won’t get much wider.
On Nov. 3, MPLX also agreed to sell the midstream assets tied to two Marathon Petroleum refineries to CVR Energy for $750 million. CEO Maryann Mannen said on the call that the sale “currently presents a headwind to 2027 that was not initially contemplated when other operational metrics were established.” And as an MLP, MPLX pays distributions on units, with a K-1 at tax time.
So which dividend wins?
If I can only hold one of these for the next 20 years, it’s MPLX.
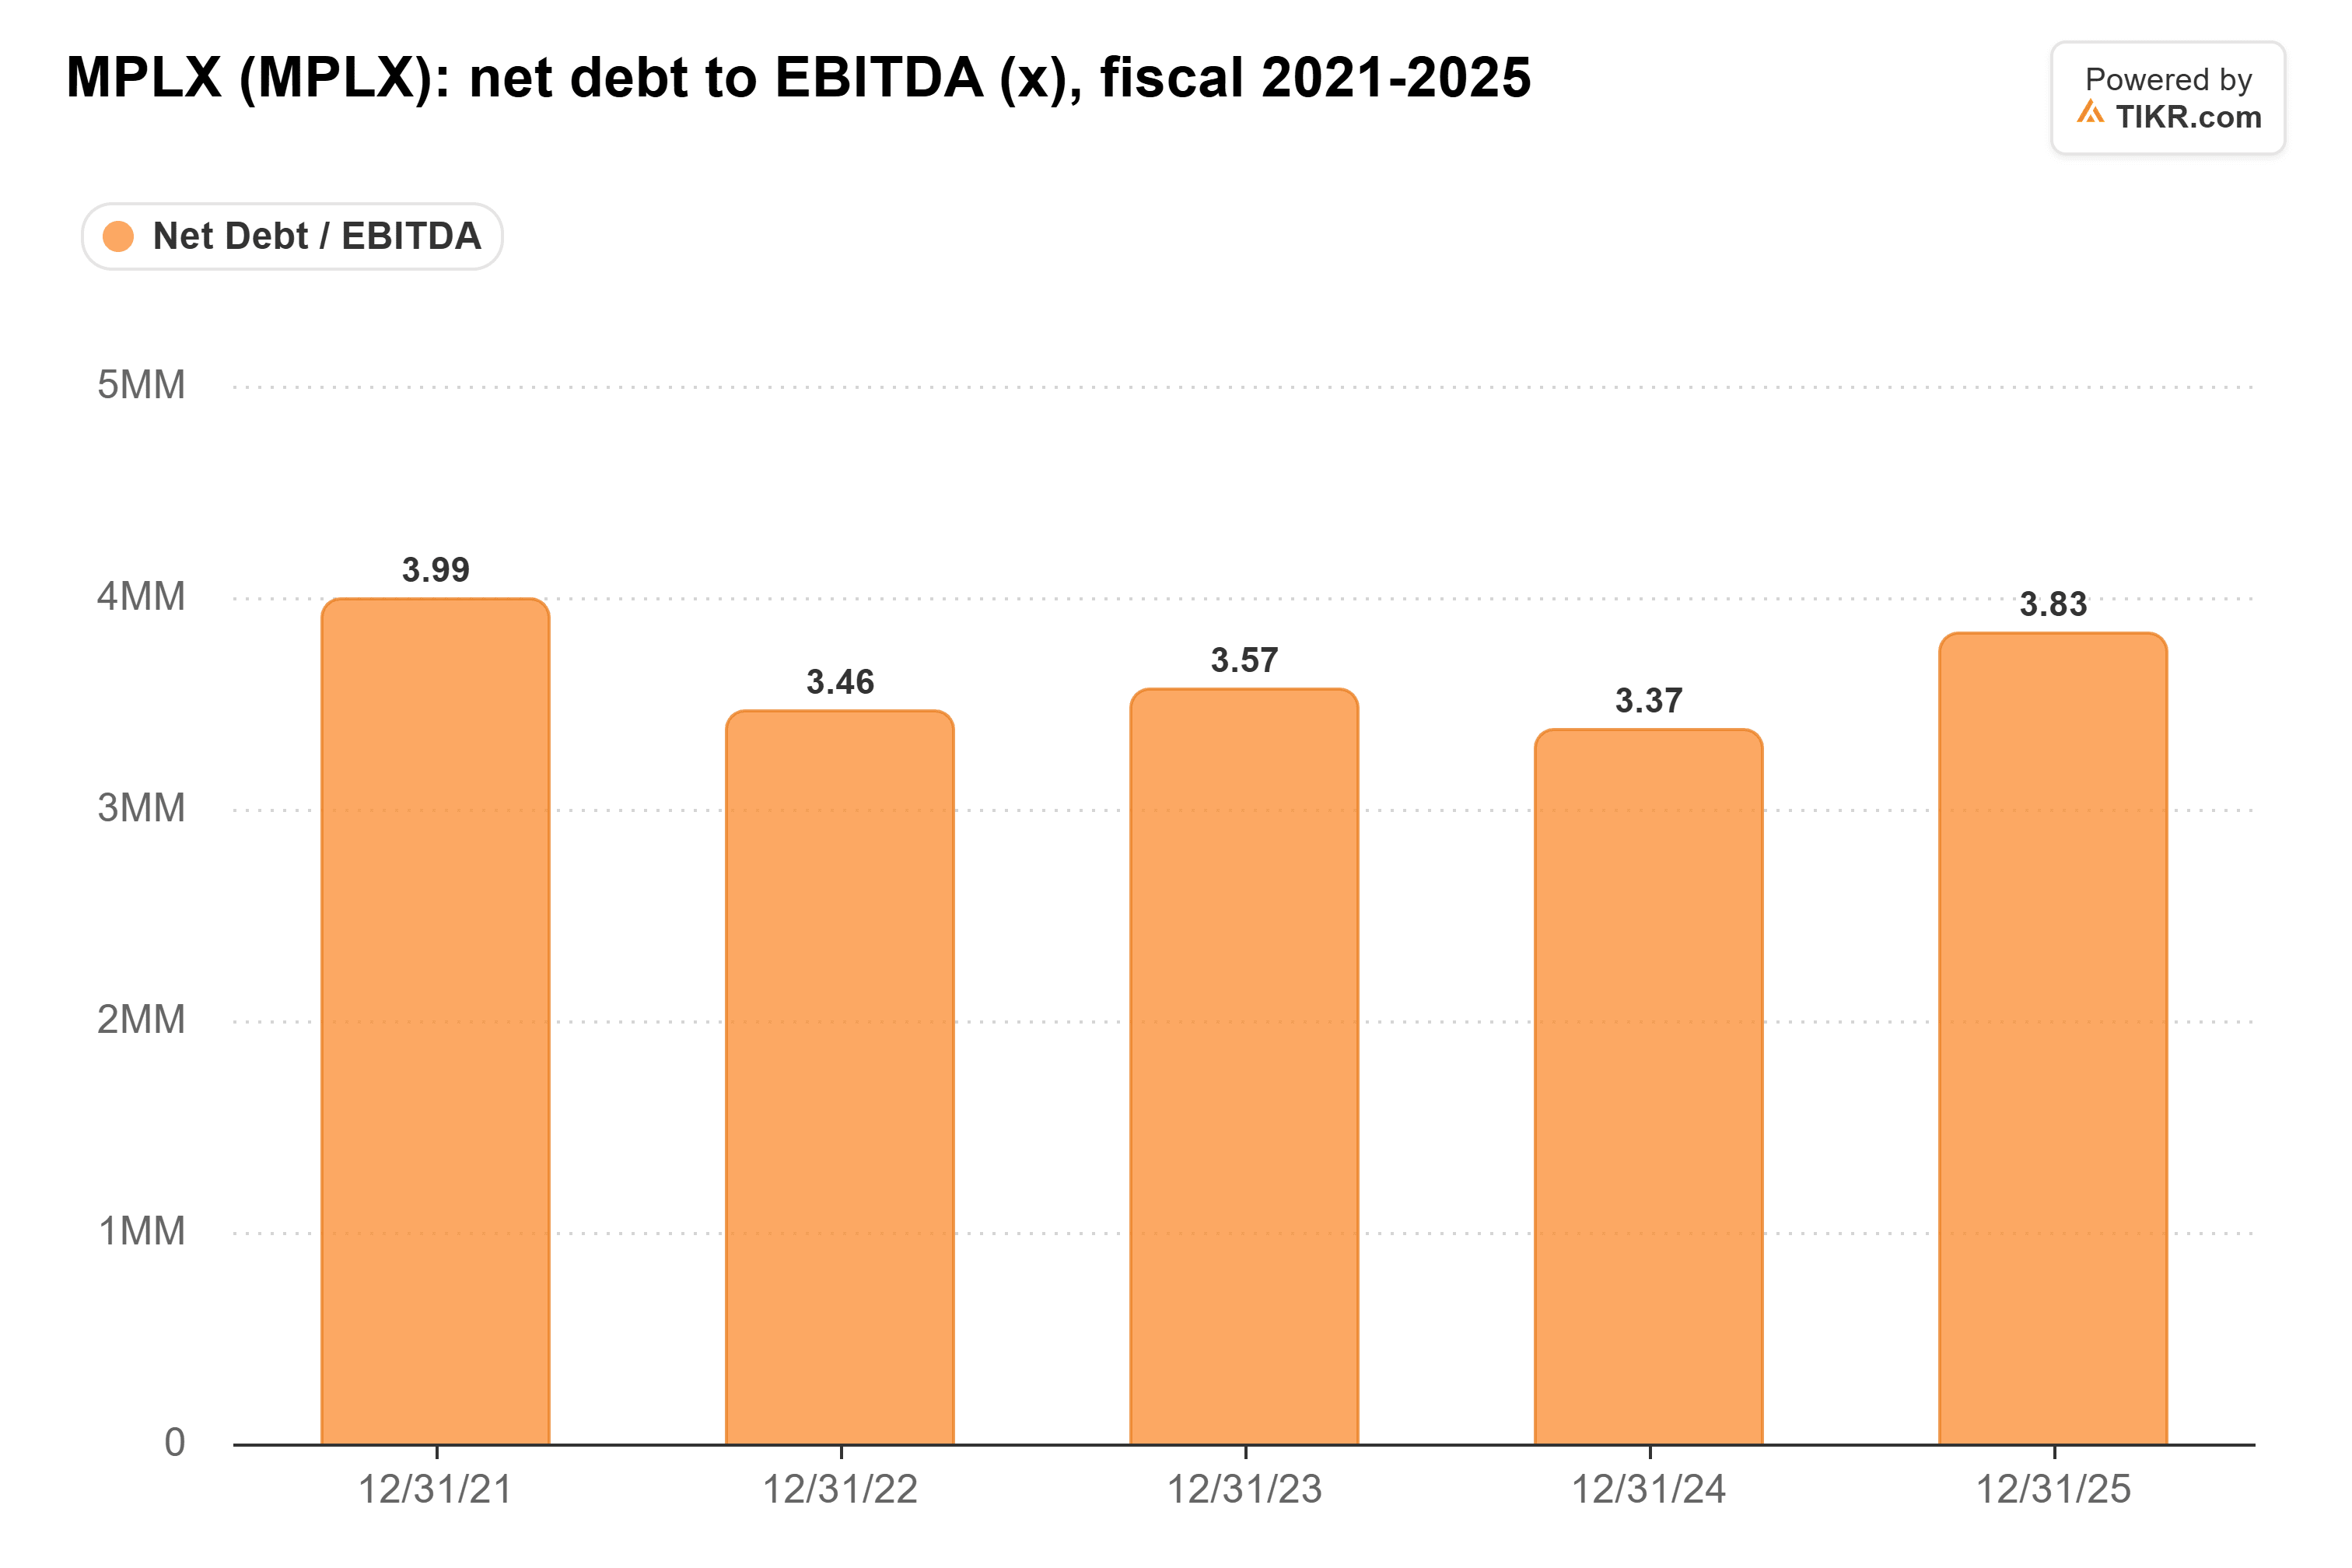
Over two decades, I want a balance sheet that can carry the payout through a bad stretch, and MPLX’s is the stronger one. Its net debt is 4.05x EBITDA, against TC Energy’s 6.02x, and its EBIT covers interest 4.03x, against 2.07x. It has kept its leverage between 3.4x and 4.0x from fiscal 2021 to fiscal 2025, even as it raised its distribution by double digits:
The income gap is enormous, too. At each one’s 5-year growth rate, $10,000 in MPLX pays about $40,000 over 20 years, against about $8,600 from TC Energy, and TC Energy’s income never catches up. I’d expect MPLX’s raises to slow toward its mid-single-digit EBITDA growth with coverage near 1.3x. But a starting check of $860 a year, against $390, leaves plenty of room to slow down and still come out ahead.
That isn’t to say TC Energy’s dividend is in any danger. It’s covered nearly twice over, it rests on a funded plan for 5% to 7% EBITDA growth, and I’m confident management will work hard to keep that 26-year record going. It’s just that, when it comes down to it, I’d rather own the bigger check from the business carrying less debt.
Of course, MPLX has to make up the EBITDA it’s selling, and whether 2027’s EBITDA growth tops this year’s, as management expects, could change the answer.
Forget MPLX: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And MPLX isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!