

Key Takeaways
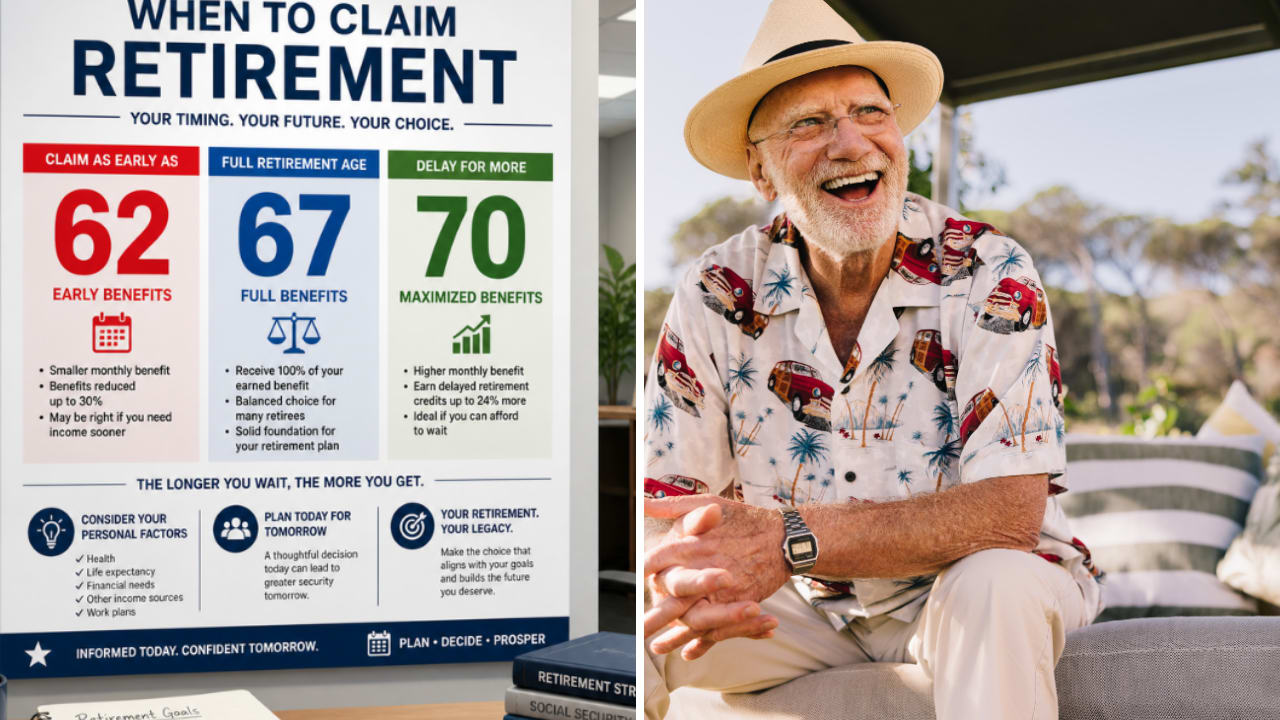
- Next year, the most Social Security pays a worker who retires at 62 is $3,094 a month. At 70, it’s $5,358, which is $2,264 more a month, or $27,168 more a year.
- Those maximum checks go only to workers who earned at least the taxable maximum every year since age 22. The taxable maximum is $184,500 this year and $192,300 next year.
- Waiting means giving up about eight years of checks. At next year’s figures, the bigger check makes that money back just before age 81.
- For a married top earner, waiting also raises the check a surviving spouse would get, because the late worker’s delayed retirement credits carry over to the survivor.
If you’ve been a top earner your whole career, next year’s Social Security figures make a strong case for patience. The most a top earner who retires in January at 62 can collect is $3,094 a month. At 70, it’s $5,358.
That’s $2,264 more every month, or $27,168 more a year. The catch is that waiting costs real money too.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Same career, two very different checks
Let’s say you’ve earned at least the taxable maximum every year since you were 22. That line is $184,500 this year and $192,300 next year. Pay above it doesn’t pay any more Social Security tax, and it doesn’t earn any more benefits.
If you claim in January at 62 and 1 month, the Social Security Administration’s benefit examples put your check at $3,094 a month. If you hold out to 67, the full retirement age for anyone born in 1960 or later, it’s $4,188. If you wait until 70, it’s $5,358, about 73% more than at 62.
Each of those figures is for a worker who retires at that age in January 2027. So the $3,094 goes to someone who is 62 now, and the $5,358 to someone who is 70 now and was born eight years earlier. A 62-year-old who waits until 70 will start collecting in 2035, on their own record, so their dollar figures won’t match 2027’s exactly. Both the cut for claiming early and the credits for waiting are percentages of the full benefit, though. That means a worker with a smaller record faces the same trade-off, just in smaller dollars.
You’d break even just shy of 81
Waiting isn’t free. Between 62 and 1 month and 70, you’d give up 95 checks of $3,094, or about $294,000.
Getting $2,264 more a month, the bigger check takes about 130 months, or nearly 11 years, to make that back. That puts the break-even point just before your 81st birthday. (That leaves out taxes and the cost-of-living raises that lift both checks.) If you live past that, you come out ahead for every month after.
The last stretch of waiting also pays the most. Going from 62 to 67 adds $1,094 a month. Going from 67 to 70 adds $1,170, in three years instead of five.
A bigger check can outlive you
For a married top earner, the bigger check can keep paying after you’re gone. A widow or widower who claims at full retirement age gets 100% of the late spouse’s full retirement benefit, plus the delayed retirement credits the late spouse earned by waiting. Social Security pays only the higher of the survivor’s own benefit and the survivor benefit, so this matters when the survivor’s own check is the smaller one.
The reverse is true too. If you claim at 62, you lock in a smaller survivor check, because a survivor’s benefit is cut when the late worker took a reduced retirement benefit. So the wait to 70 keeps paying off for as long as either of you is alive.
Claim at 62 once the paychecks stop
Waiting doesn’t have to mean 70 exactly. You can claim in any month from 62 on, and the credits for waiting build month by month past full retirement age until 70, so 68 or 69 are options too.
If you claim at 62 and keep working, the earnings test can take most of those early checks anyway. Social Security charges any excess earnings against your whole benefit, starting in January and cutting a dollar of benefits for each dollar of excess until it’s all covered. So a 62-year-old still earning a top salary could go months without a check, possibly the whole year. Those months aren’t gone for good, since the benefit is recalculated at full retirement age to credit them back. Still, it’s a strange way to collect early.
I’d wait, if you can
If you’re a top earner in good health, and especially if you’re married, I’d wait until 70. Breaking even just before 81 isn’t a tall order for a healthy 62-year-old, and the bigger check can keep paying your spouse after you’re gone. But if your health is shaky, or bridging eight years would mean draining savings you’d rather not touch, there’s no shame in taking the smaller check early. Whichever size you lock in, each year’s cost-of-living adjustment raises it by the same percentage, so the gap in dollars keeps growing from there.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!




