Key Takeaways
- Hormel Foods just closed its $1.055 billion Brakebush Brothers purchase with help from a $700 million loan, while Sysco works to close its own Jetro Restaurant Depot deal.
- Hormel yields 5.2% against Sysco’s 2.9%, but its dividend took 82% of free cash flow over the last twelve months, against 48% for Sysco.
- Sysco’s sales rose 2.8% last quarter and it expects 9%-11% adjusted EPS growth this year, while Hormel’s organic net sales fell 2% in its latest quarter.
- Hormel trades at 15x forward earnings, well below its 10-year average of 22x.
On Nov. 16, Hormel Foods (HRL) closed its $1.055 billion purchase of chicken maker Brakebush Brothers. On Nov. 13, it borrowed $700 million under a new term loan to help pay for it.
Sysco (SYY) is working on a deal of its own: it expects to close its purchase of Jetro Restaurant Depot by the end of its fiscal third quarter. Both are buying growth while paying a dividend, from very different starting points.
If I could only hold one of those dividends for the next 20 years, which would it be?
| Metric | Hormel Foods (HRL) | Sysco (SYY) |
|---|---|---|
| Dividend yield | 5.2% | 2.9% |
| Annual dividend | $1.17 a share | $2.20 a share |
| Dividend growth, 5 years | 4.5% a year (fiscal 2020-2025) | 3.6% a year (fiscal 2021-2026) |
| Record, in its own words | 392 consecutive quarterly payouts | 57 years of dividend increases |
| Cash dividend payout ratio, TTM | 82% (to July 26, 2026) | 48% (to Sept. 26, 2026) |
| Net debt/EBITDA | 1.2x | 2.5x |
| Interest coverage | 12.6x | 4.4x |
Source: TIKR; records from each company’s earnings calls. Yields at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Hormel’s dividend has outgrown its cash flow
In its fiscal third quarter, which ended July 26, 2026, Hormel’s organic net sales fell 2%. Retail volume dropped on exits it chose and on a pressured consumer. Foodservice grew organic sales for a 12th straight quarter, though, and that’s where Brakebush lands, with about $1.2 billion of net sales over its last 12 months. Management also raised its fiscal 2026 adjusted EPS guidance to $1.45-$1.51, or 6%-10% growth.
The dividend took a stretched 82% of free cash flow over the twelve months to July 26, 2026. Over the past decade, the dividend has grown much faster than the cash behind it:
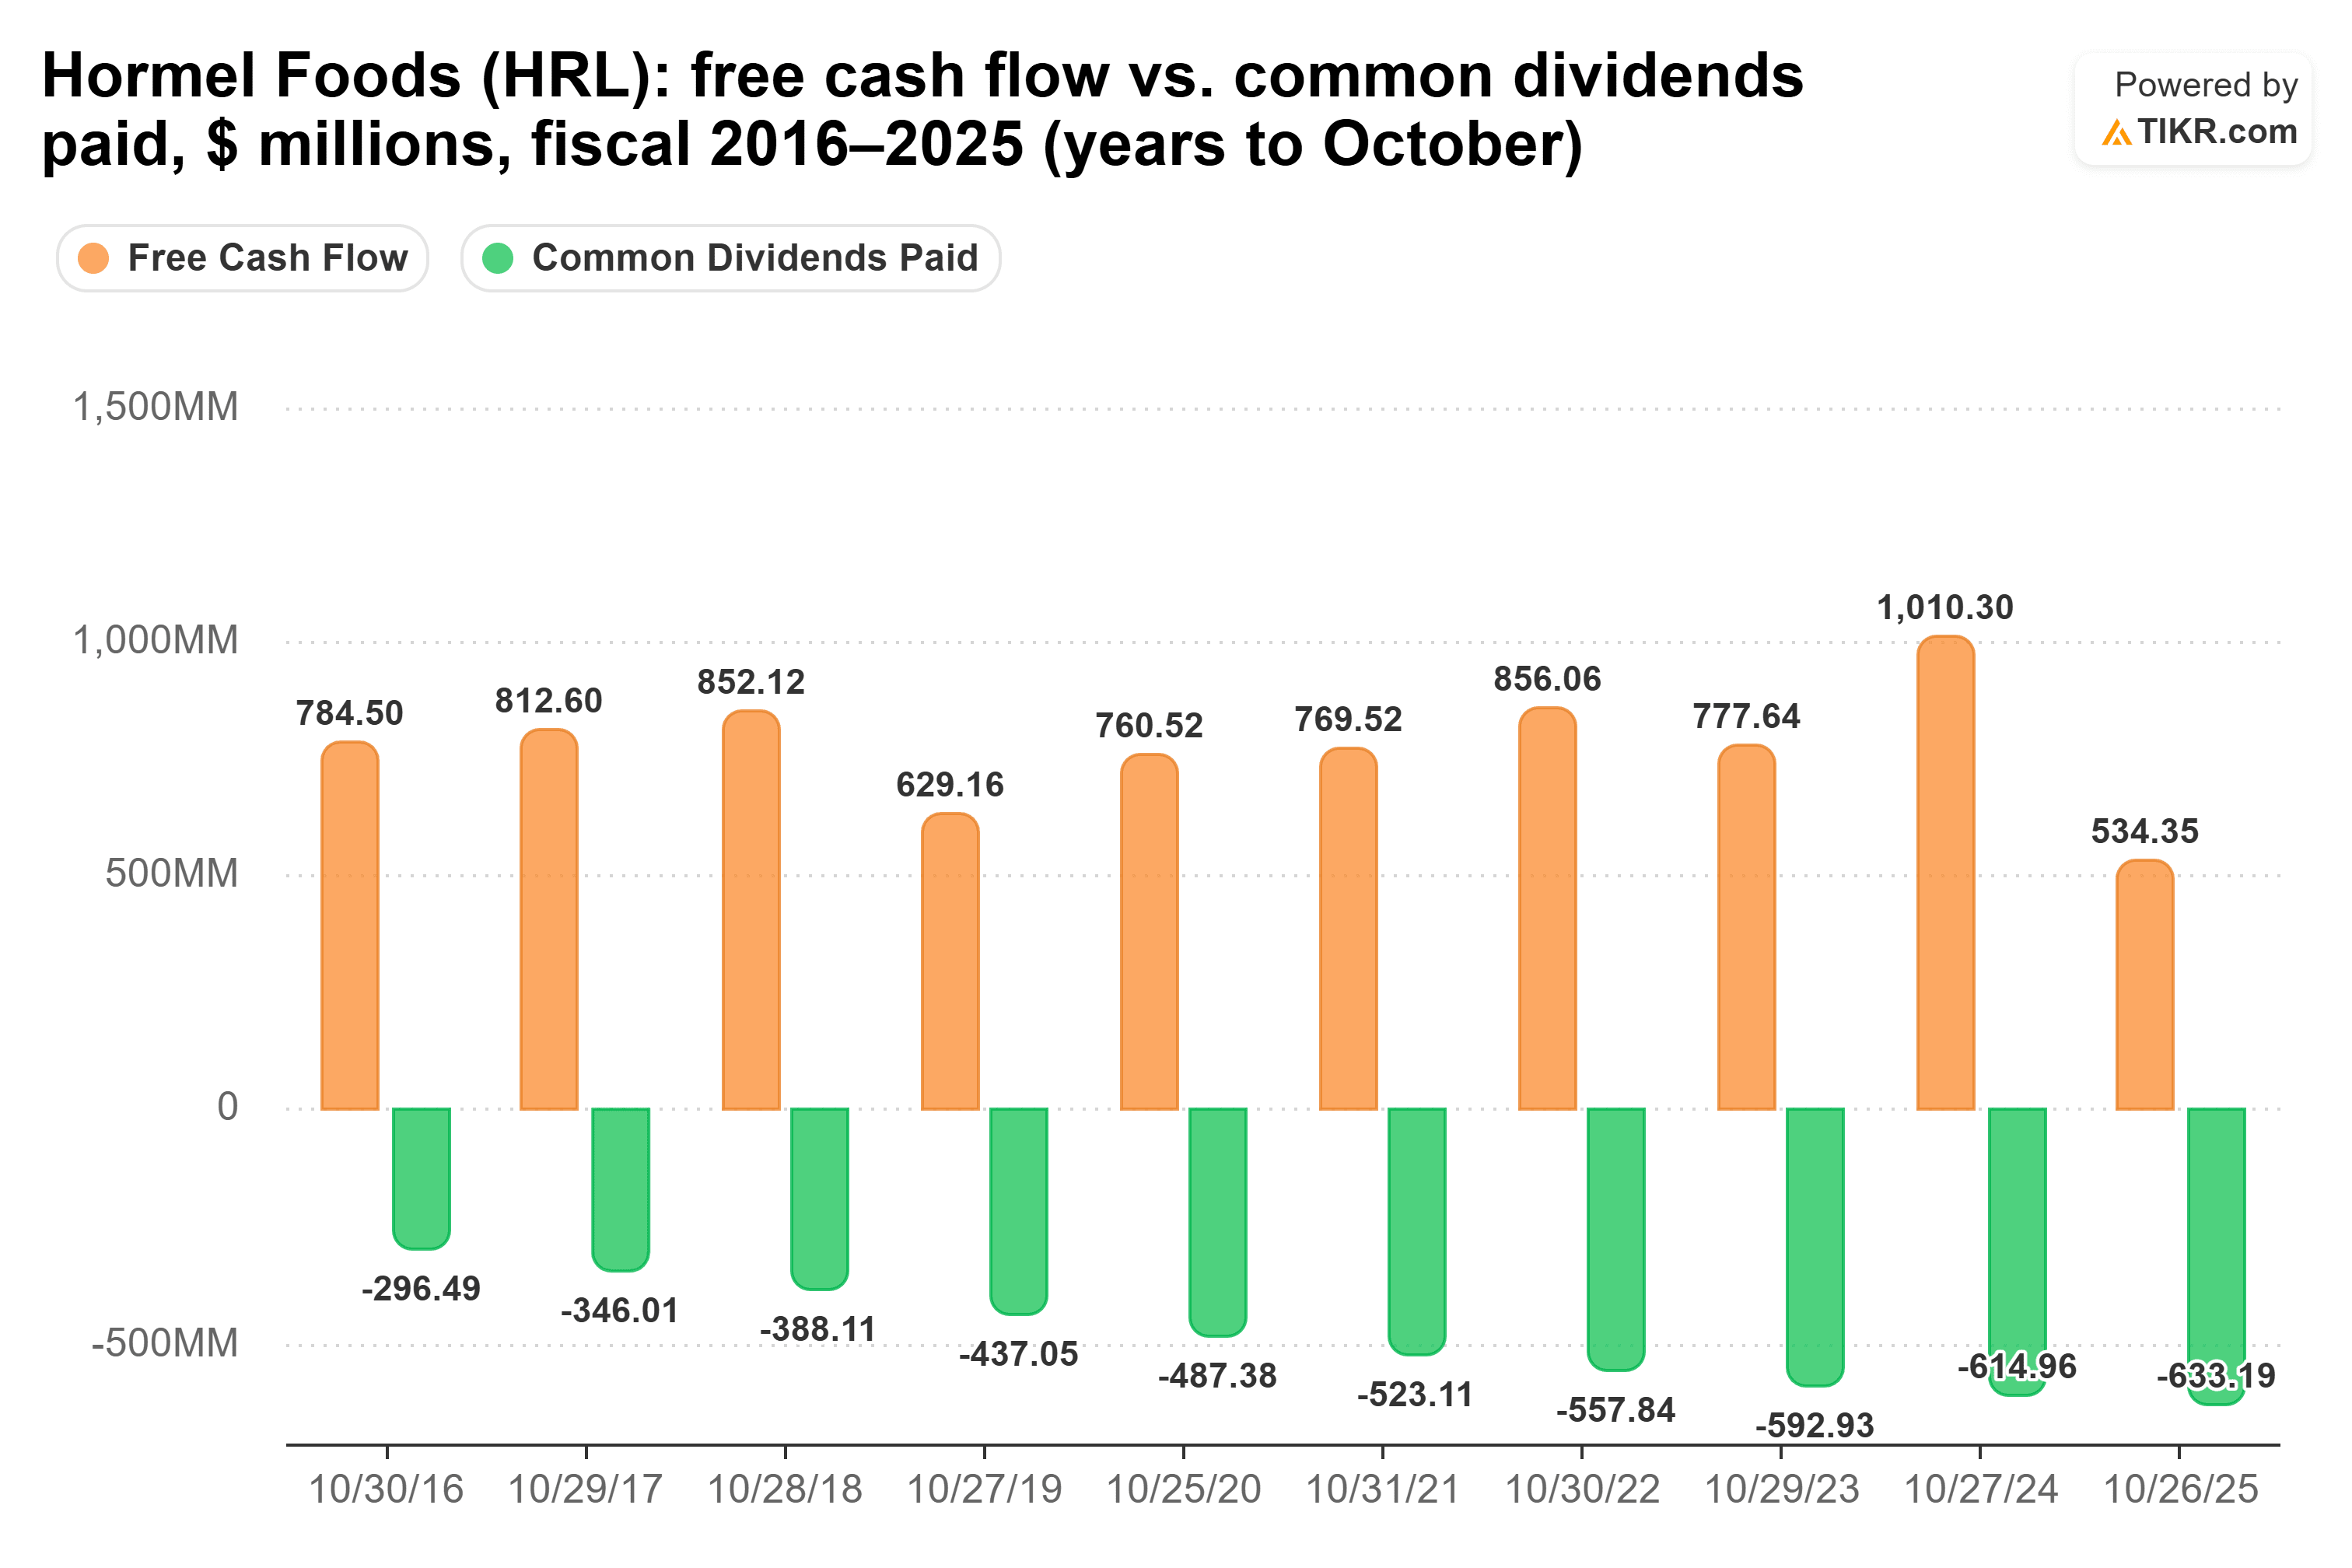
Dividends paid more than doubled, from $296 million in fiscal 2016 to $633 million in fiscal 2025. Free cash flow ranged from $629 million to $1.01 billion before it fell to $534 million in fiscal 2025, the first year on the chart it didn’t cover the dividend.
John Ghingo, who became CEO on Oct. 26, said on the third-quarter call: “Certainly, the dividend continues to be very important to us.” The new debt is what I’d watch. Hormel’s net debt was a light 1.2x EBITDA over the last twelve months, and that was before the $700 million loan.
Sysco has cash to spare
Sysco offers the opposite trade: a smaller check with far more cash behind it. In its fiscal first quarter, the 13 weeks ended Sept. 26, 2026, sales rose 2.8% to $21.7 billion, and adjusted EPS rose 3.5% to $1.19. Management stood by its call for 9%-11% adjusted EPS growth this fiscal year.
Its dividend took a well-covered 48% of free cash flow over the twelve months to Sept. 26, 2026. Free cash flow topped dividends in every year on the chart:
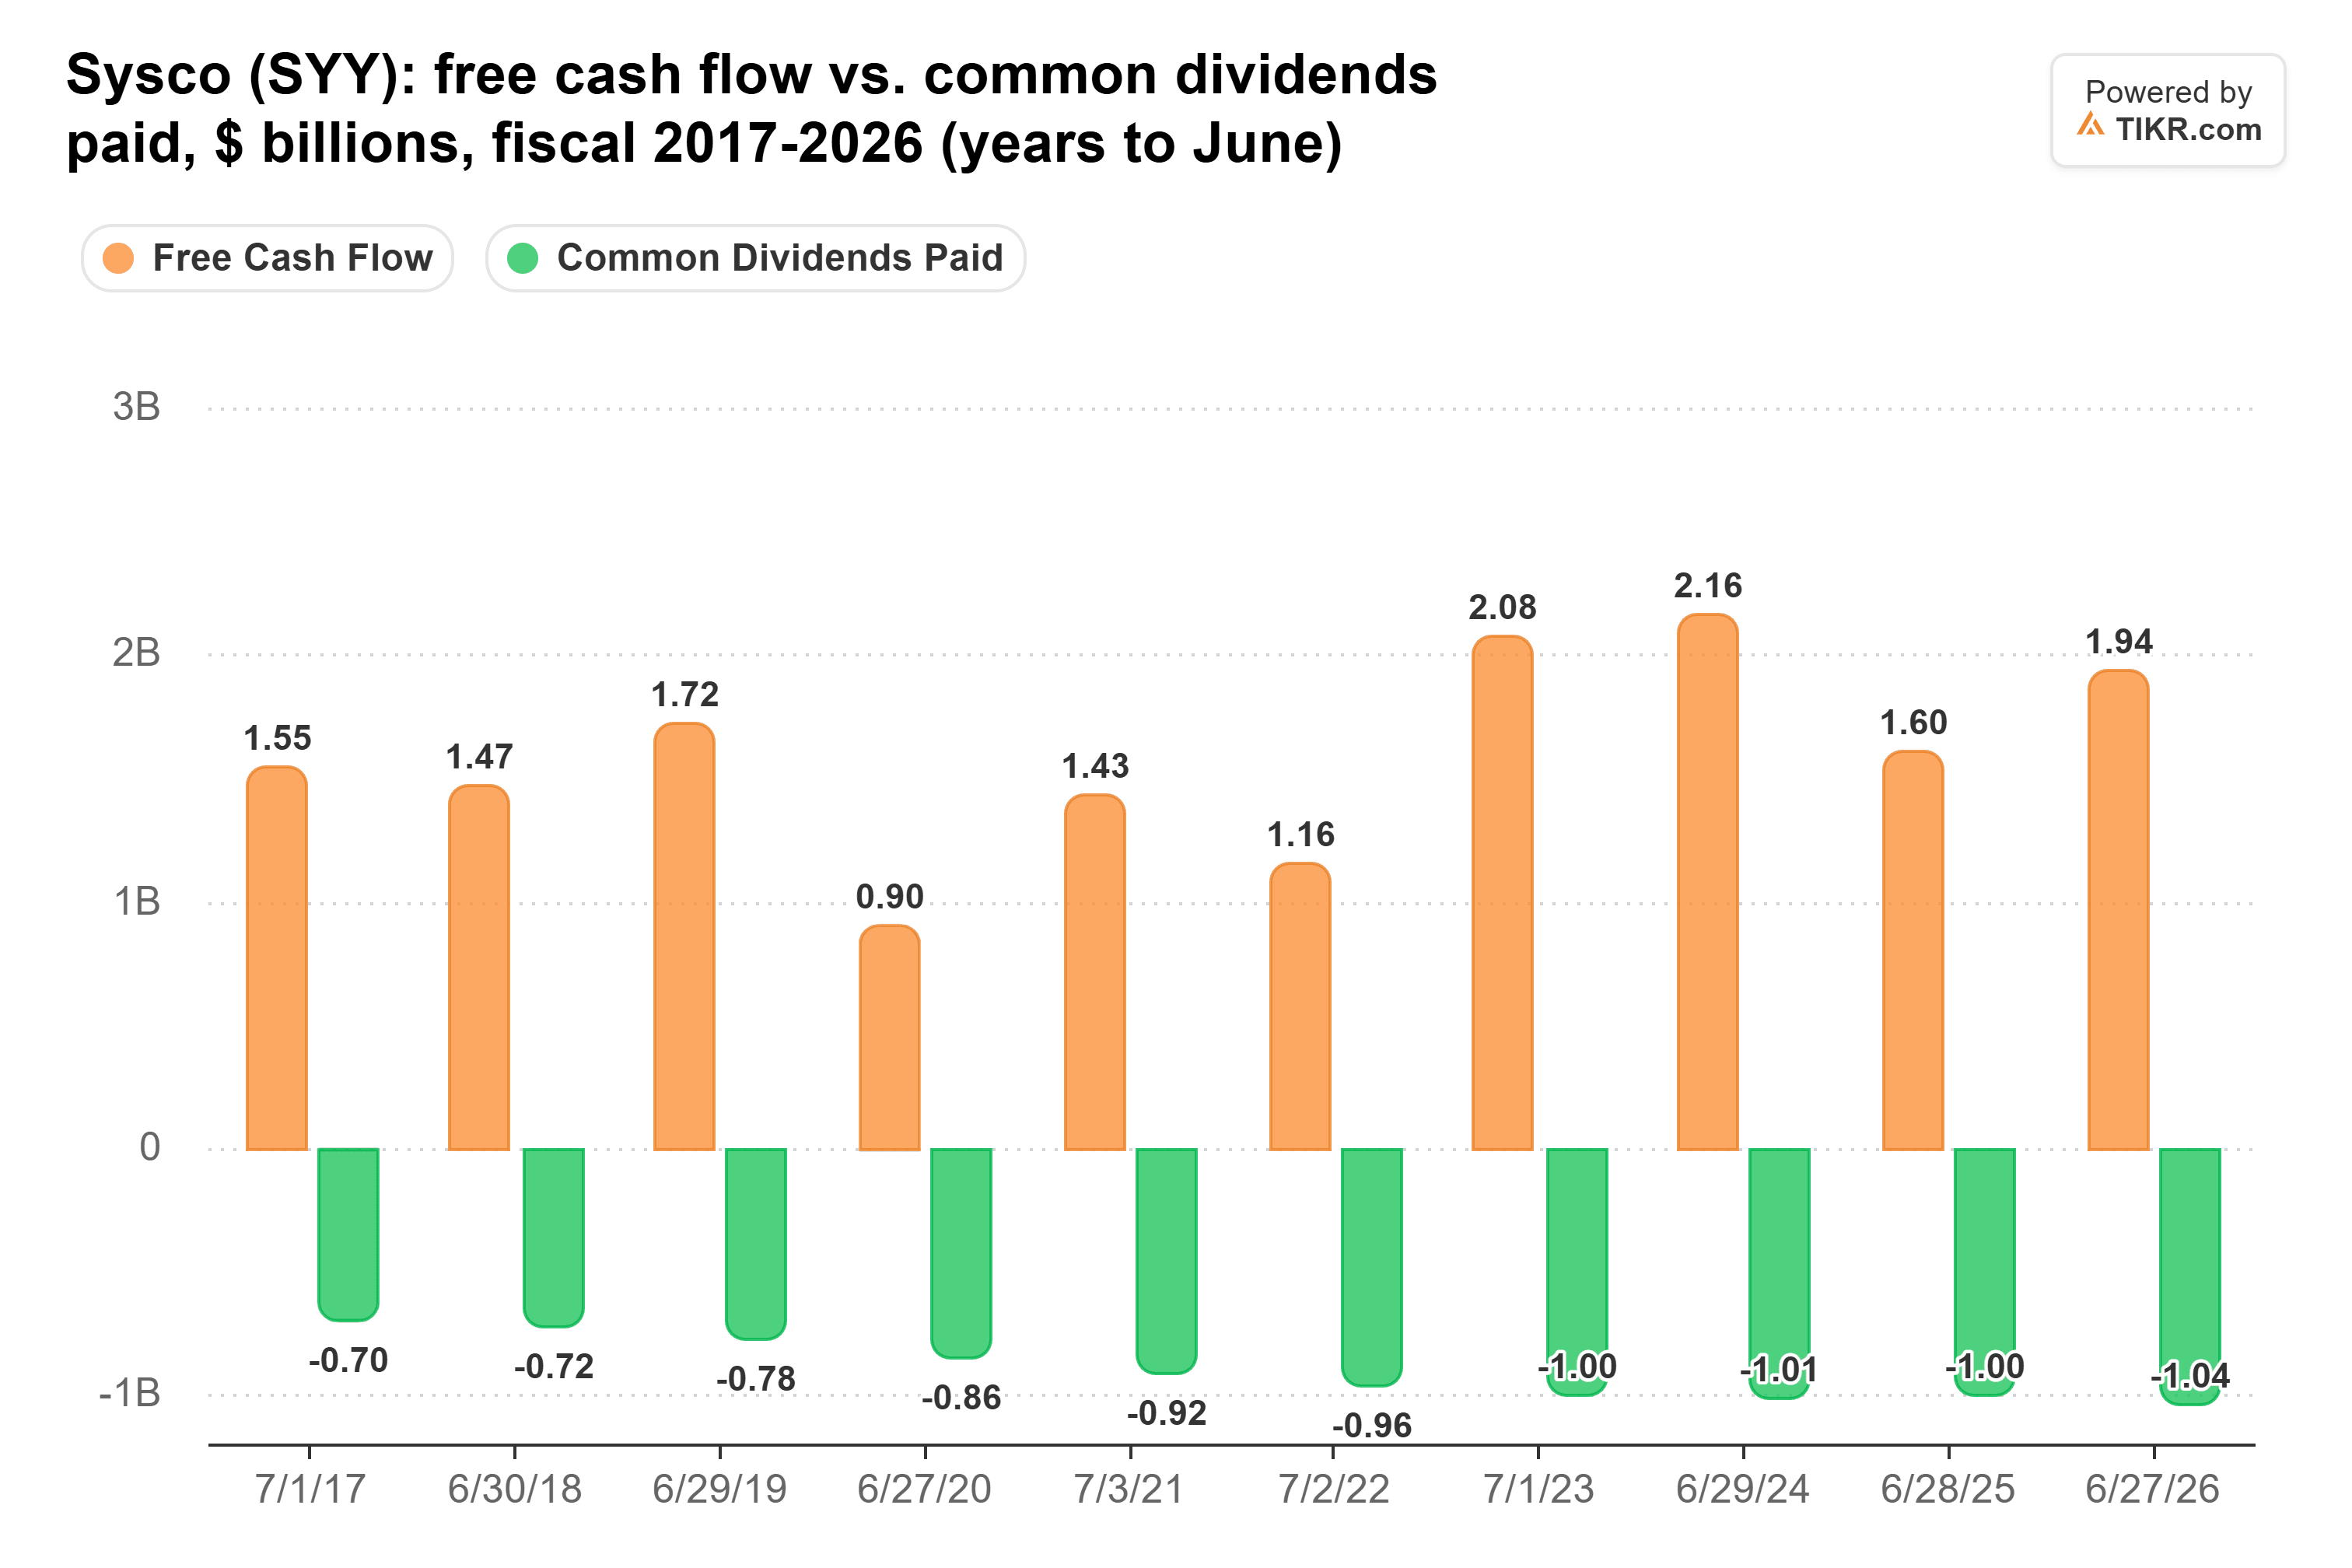
The tightest year was fiscal 2022, when the dividend took 83% of free cash flow. But its latest raise, in April, was about 2%, so the check grows slowly. Its balance sheet is also heavier, with net debt at 2.5x EBITDA and EBIT covering interest 4.4x, and Jetro Restaurant Depot is still to close.
So which dividend wins?
If I can only pick one dividend stock for the next 20 years, I’m picking Hormel. The income gap is too big to give up. At its 5-year growth rate, $10,000 in Hormel pays about $16,346 over the 20 years, against about $8,269 for Sysco at its own rate.
Even if Hormel never raised its dividend again, that $10,000 would pay $10,400 over the 20 years. That’s still more than Sysco’s growing check. So what I need from Hormel is a dividend that holds, and I’m not paying up for one. Hormel trades well below where the market has valued it over the past decade:
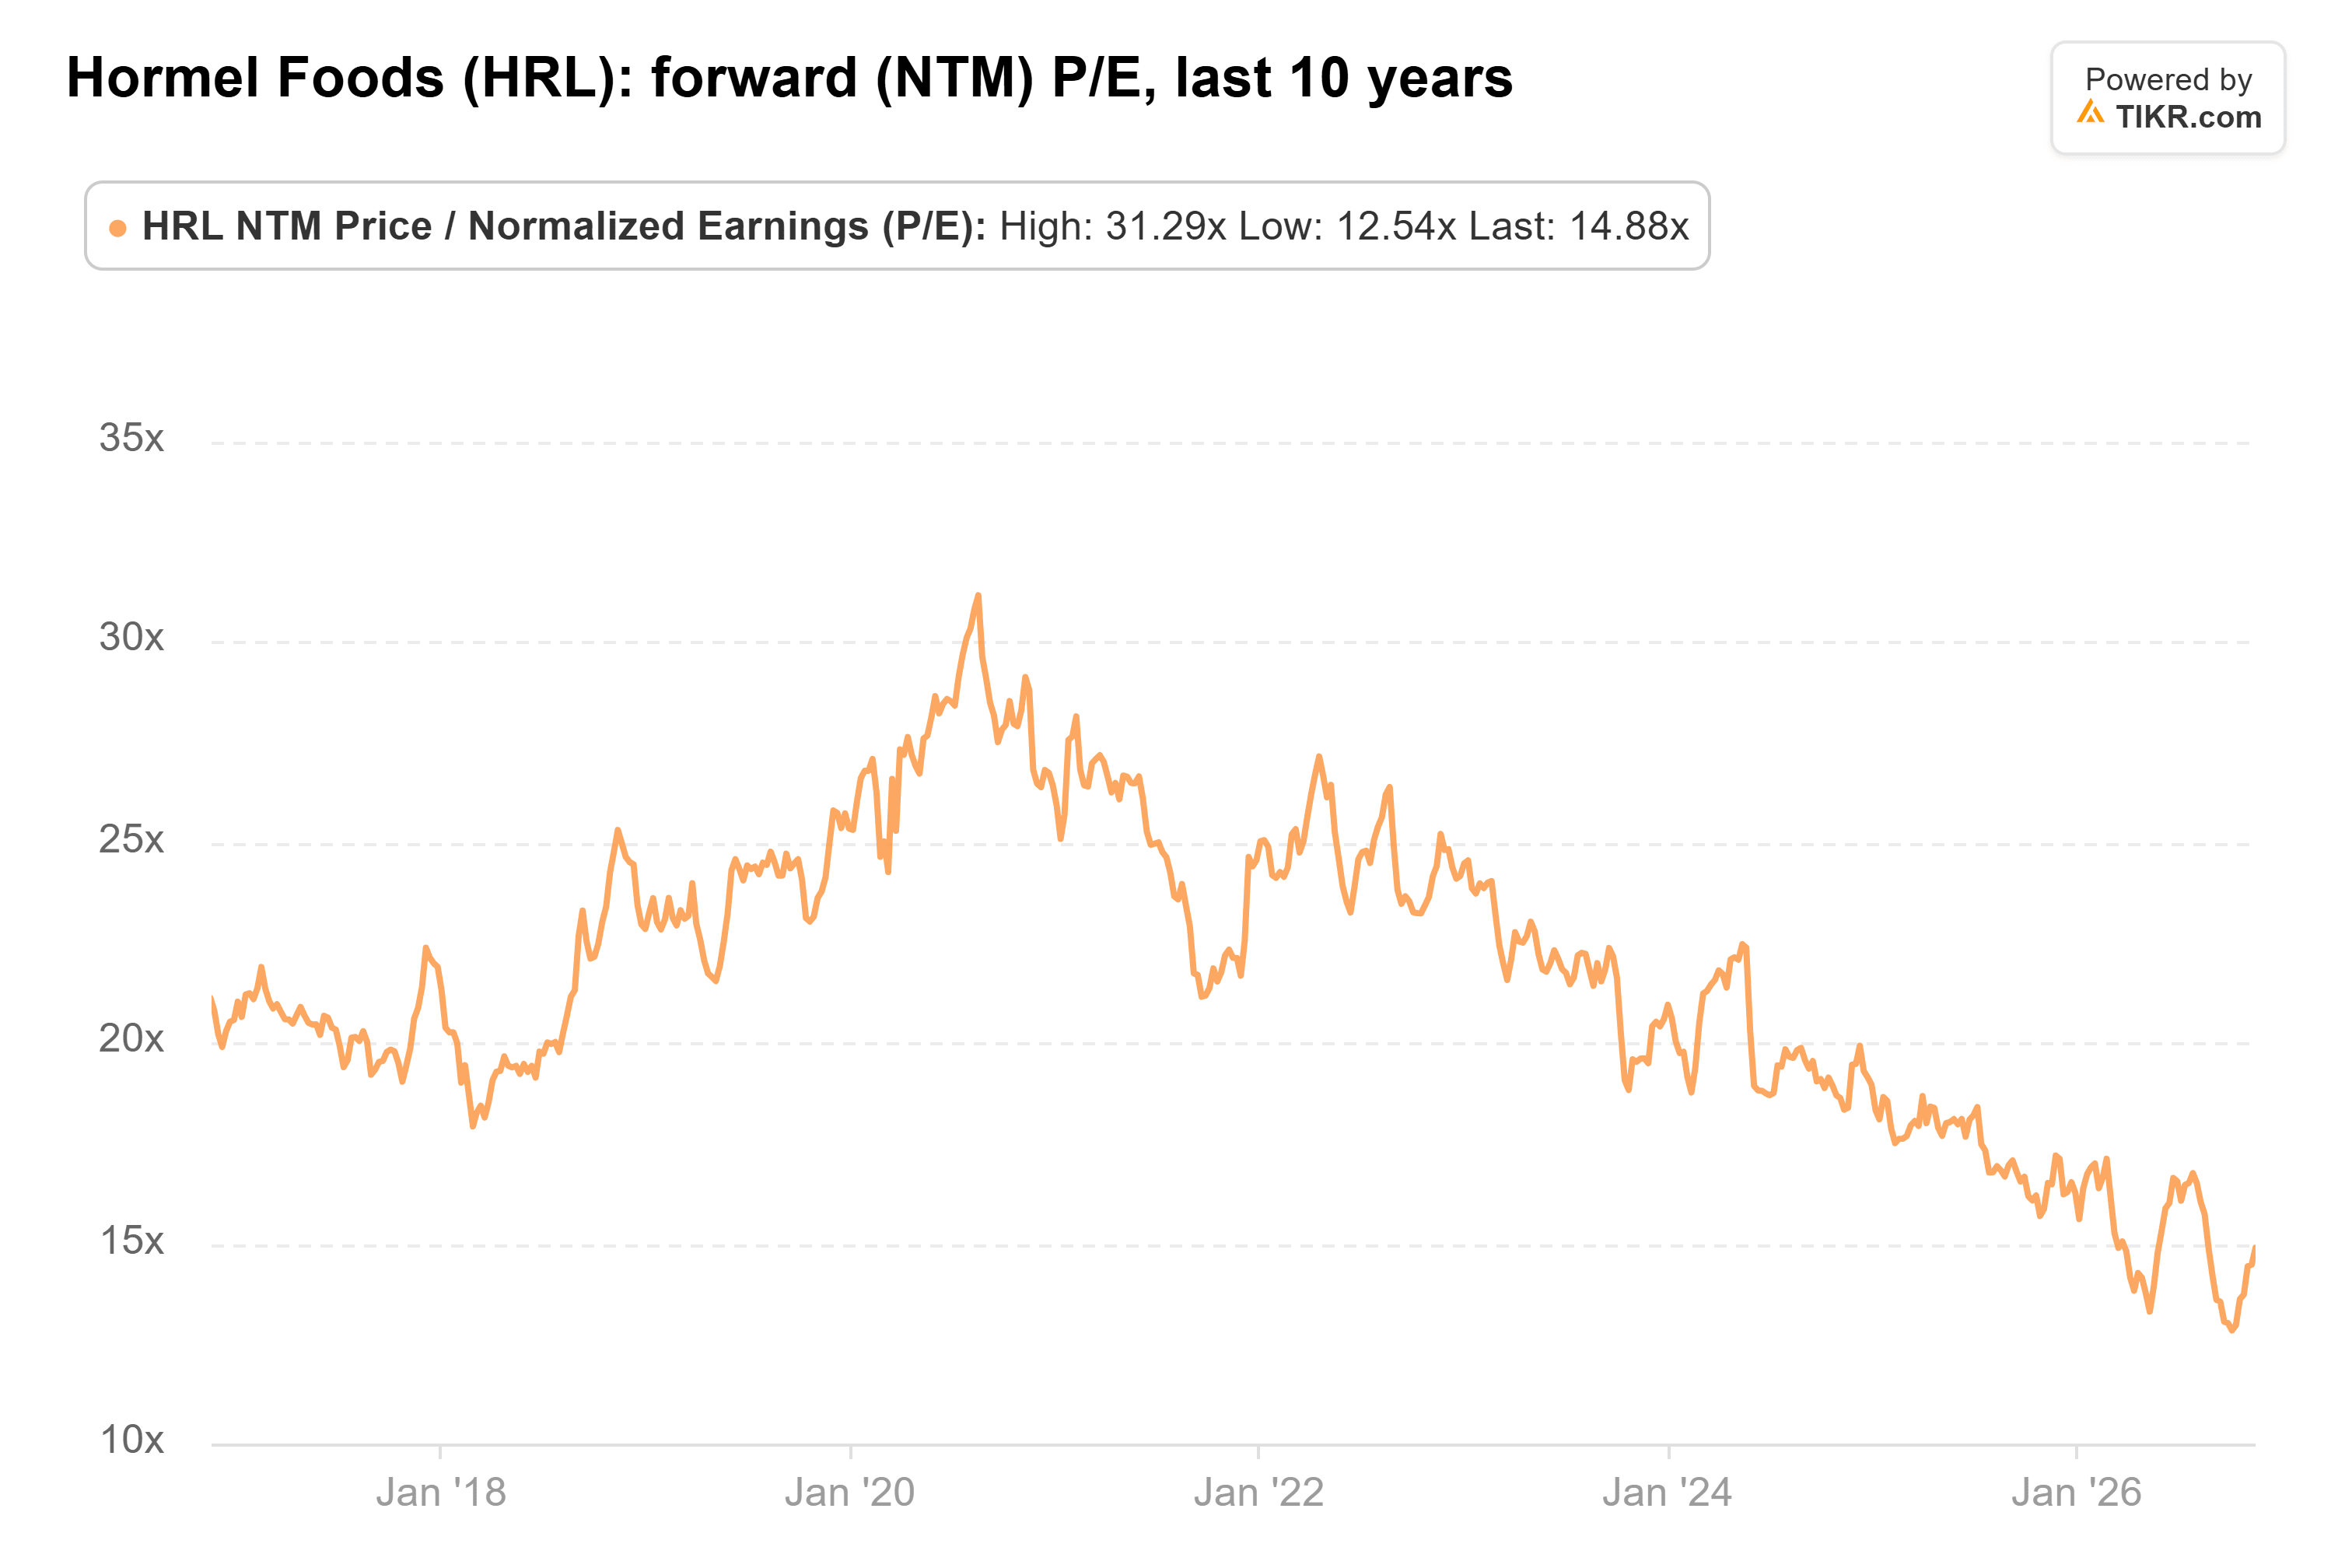
Its 15x forward earnings compares with a 10-year average of 22x and a high of 31x in August 2020.
This isn’t to say Sysco’s dividend is in any doubt. It’s well covered, the business is growing, and that record of raises is one I’m confident management will work hard to keep. It’s just that over 20 years, Hormel’s 5.2% yield gives me a lot more room for error.
Of course, Hormel’s fourth-quarter call on Dec. 3 will show how the new debt fits. If free cash flow stays near fiscal 2025’s $534 million, I’d revisit this.
Forget Hormel Foods: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Hormel Foods isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!