Key Takeaways
- Franklin Templeton yields 3.8%, against 2.6% for Procter & Gamble, though P&G raised its dividend faster from fiscal 2021 to fiscal 2026.
- P&G’s dividend took a well-covered 67% of its free cash flow over the 12 months to Sept. 30, 2026, against 85% for Franklin Templeton.
- Franklin Templeton’s business is improving, with record long-term net inflows of $84.1 billion in fiscal 2026, while P&G kept its outlook despite higher commodity costs.
- What to watch: Franklin Templeton’s next raise, after a 3.1% increase last December, and whether P&G’s earnings hold up against rising costs.
Procter & Gamble (PG) kept its full-year outlook on Oct. 22, even after raising its estimate of what commodity costs will take out of earnings this fiscal year. It still expects to pay over $10 billion in dividends.
Two weeks later, Franklin Templeton (BEN) reported a year of record inflows. Its stock yields 3.8%, well above P&G’s 2.6%.
So if only one of them gets my dividend dollars for the next 10 years, which should it be?
| Metric | Procter & Gamble (PG) | Franklin Templeton (BEN) |
|---|---|---|
| Dividend yield | 2.6% | 3.8% |
| Dividend growth, fiscal 2021-2026 | 5.6% a year | 3.3% a year |
| Dividend raises, by the company’s count | 70 years in a row | Every year since 1981 |
| Cash dividend payout ratio, TTM to Sept. 30, 2026 | 67% | 85% |
| Net debt/EBITDA | 0.93x | 0.28x |
| Forward P/E | 24x | 11x |
Source: TIKR and company releases, at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
P&G pays its dividend with room to spare
P&G’s fiscal first quarter, the three months to Sept. 30, 2026, was a strong start. Organic sales rose 4.0%, with growth in all 10 product categories and all six regions. Health Care volume fell 2.9% after two weak cold and cough seasons. Core EPS rose 1% to $2.00, ahead of the $1.89 analysts expected, and the stock jumped 6% that day.
The dividend is well covered, taking 67% of free cash flow over the 12 months to Sept. 30, 2026. Free cash flow has stayed well above dividends paid for a decade:
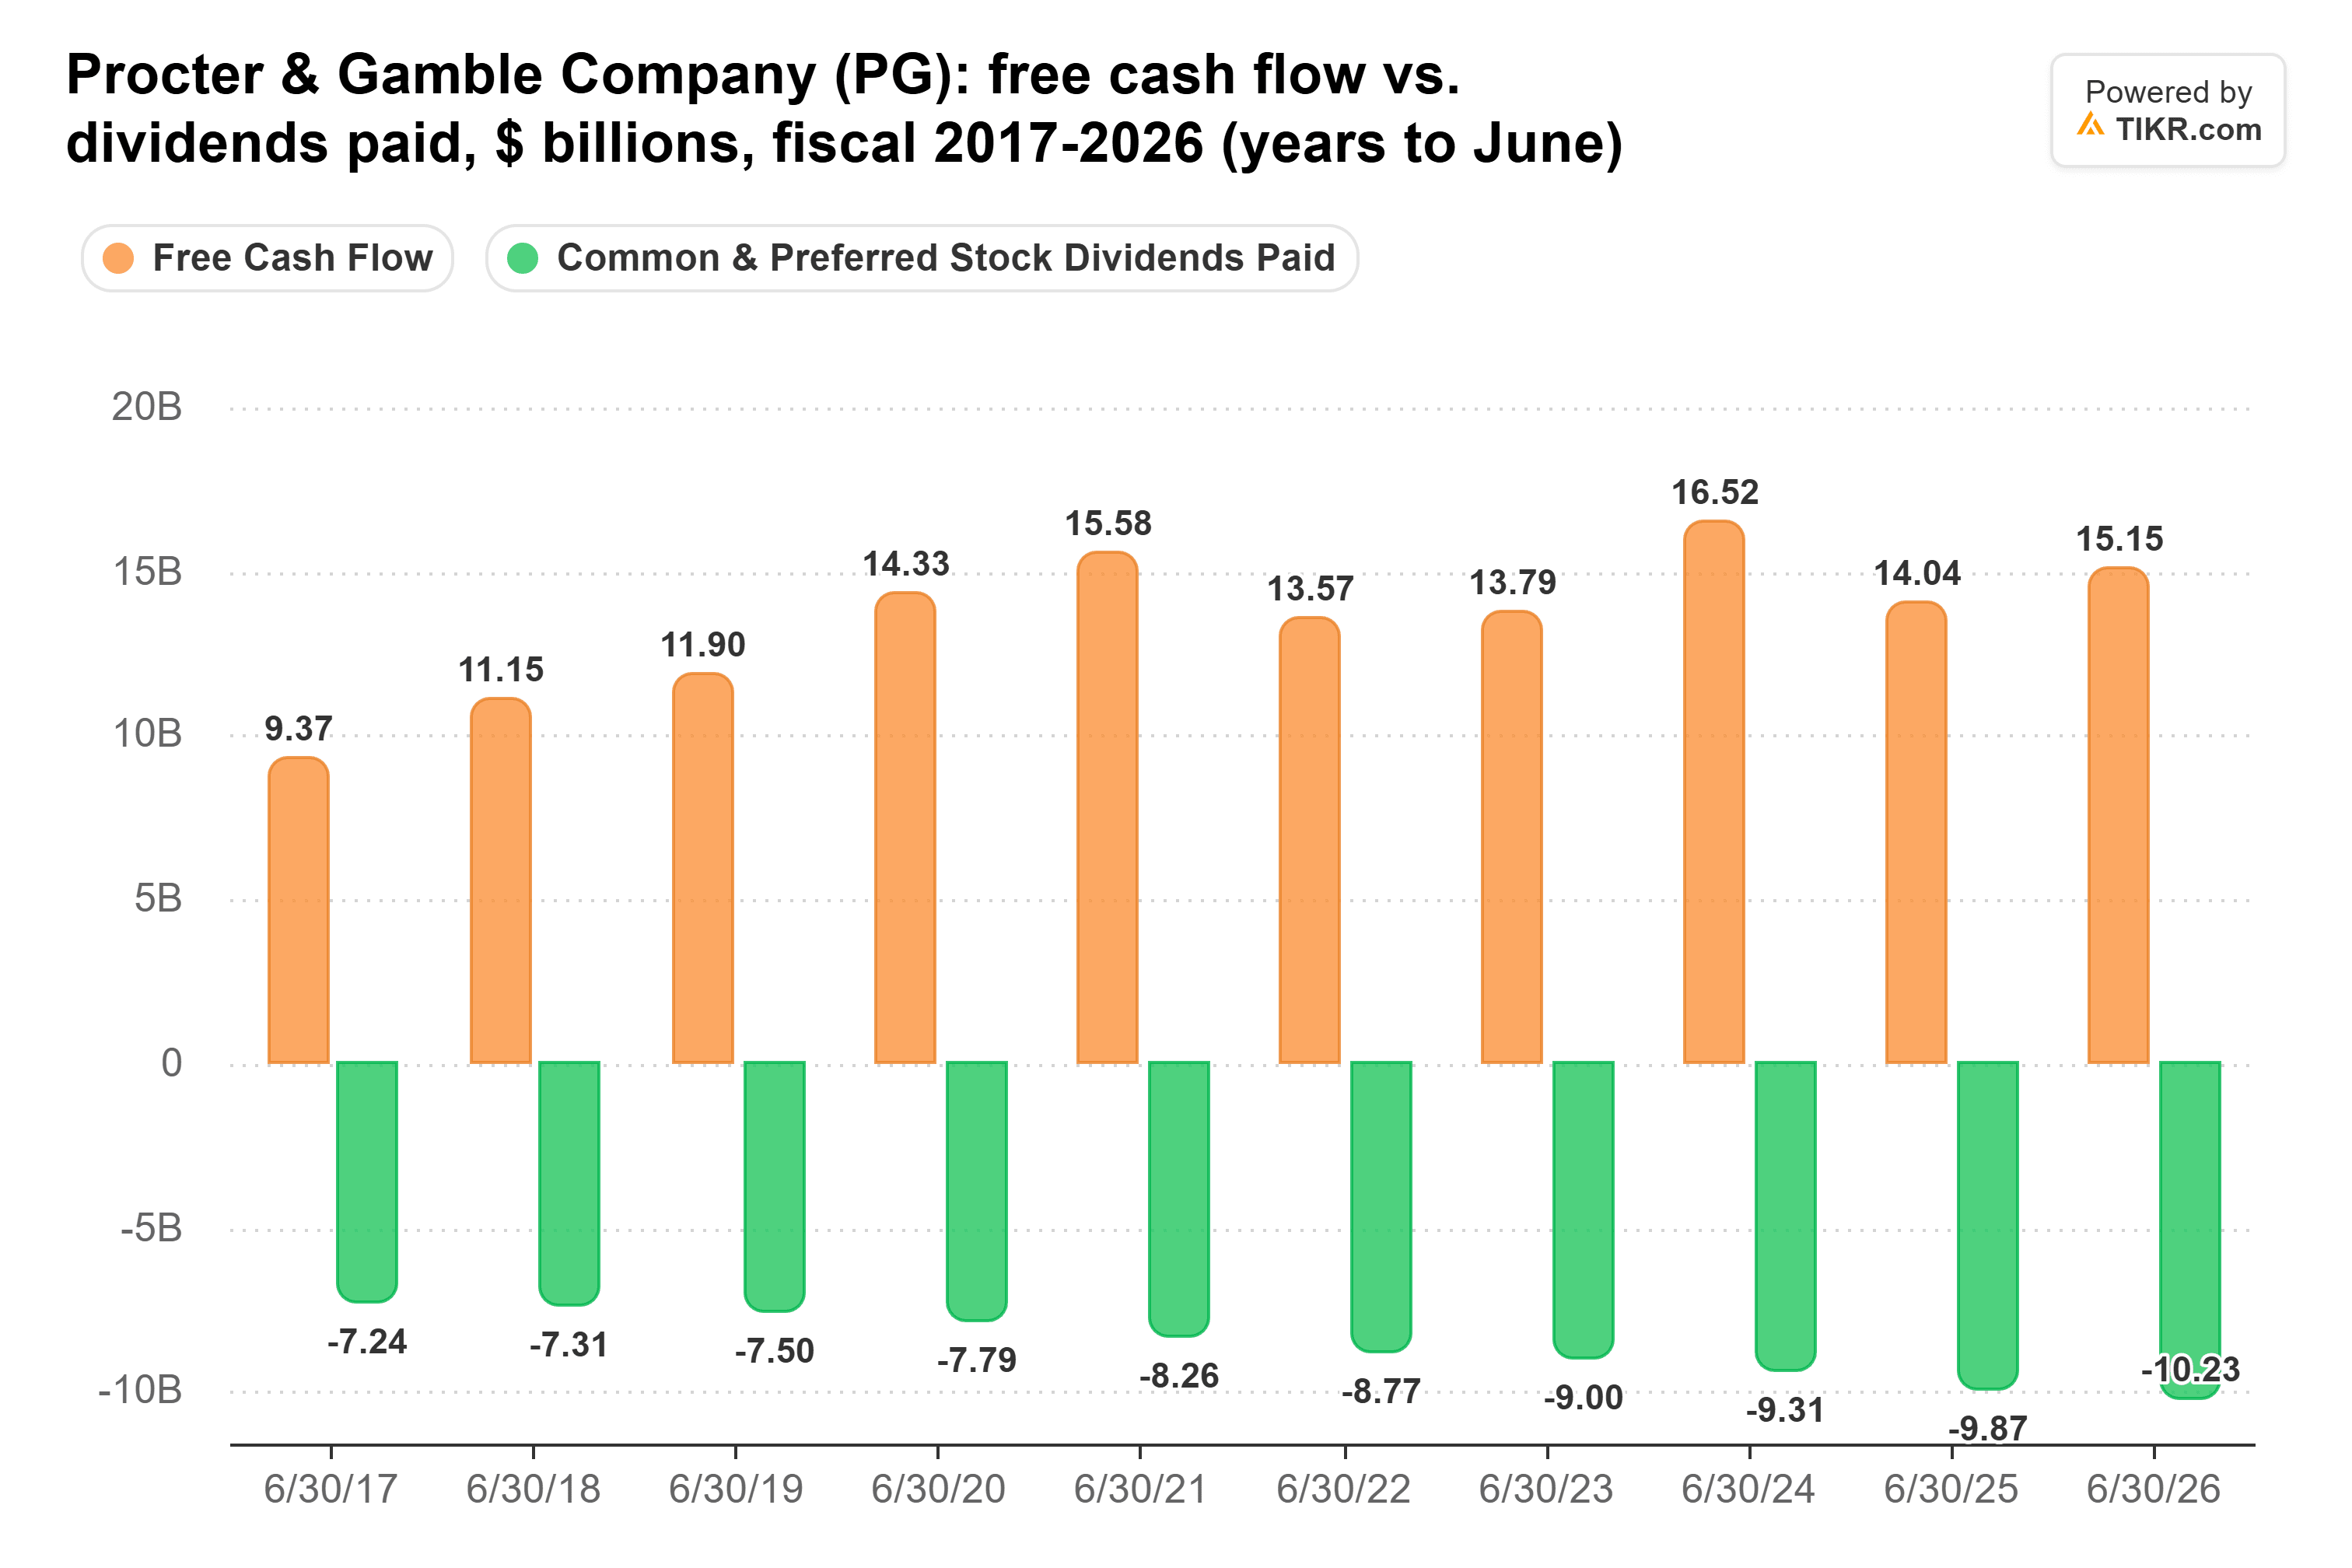
It rose from $9.37 billion in fiscal 2017 to $15.2 billion in fiscal 2026, which ended in June, while dividends went from $7.24 billion to $10.2 billion. P&G says it has raised its dividend for 70 consecutive years, and it declared its regular $1.0885 quarterly payment on Oct. 13.
The risk is slower earnings. P&G now expects commodity costs to take $0.79 a share out of fiscal 2027 earnings. It guides core EPS growth of in-line to 3%, below the 5.6% a year its dividend grew from fiscal 2021 to fiscal 2026.
Franklin pays more and covers it with less
Franklin pays a bigger check than P&G, and its business is picking up. In fiscal 2026, which ended Sept. 30, it pulled in a record $84.1 billion of long-term net inflows, after $97.4 billion of net outflows in fiscal 2025. Adjusted diluted EPS rose to $3.07 from $2.22. Management expects its adjusted operating margin to reach about 30% in fiscal 2027, up from 28.0%. Fixed income is the weak spot, with $11.7 billion of net outflows at Western Asset Management for the year.
The cash behind the dividend hasn’t kept up:
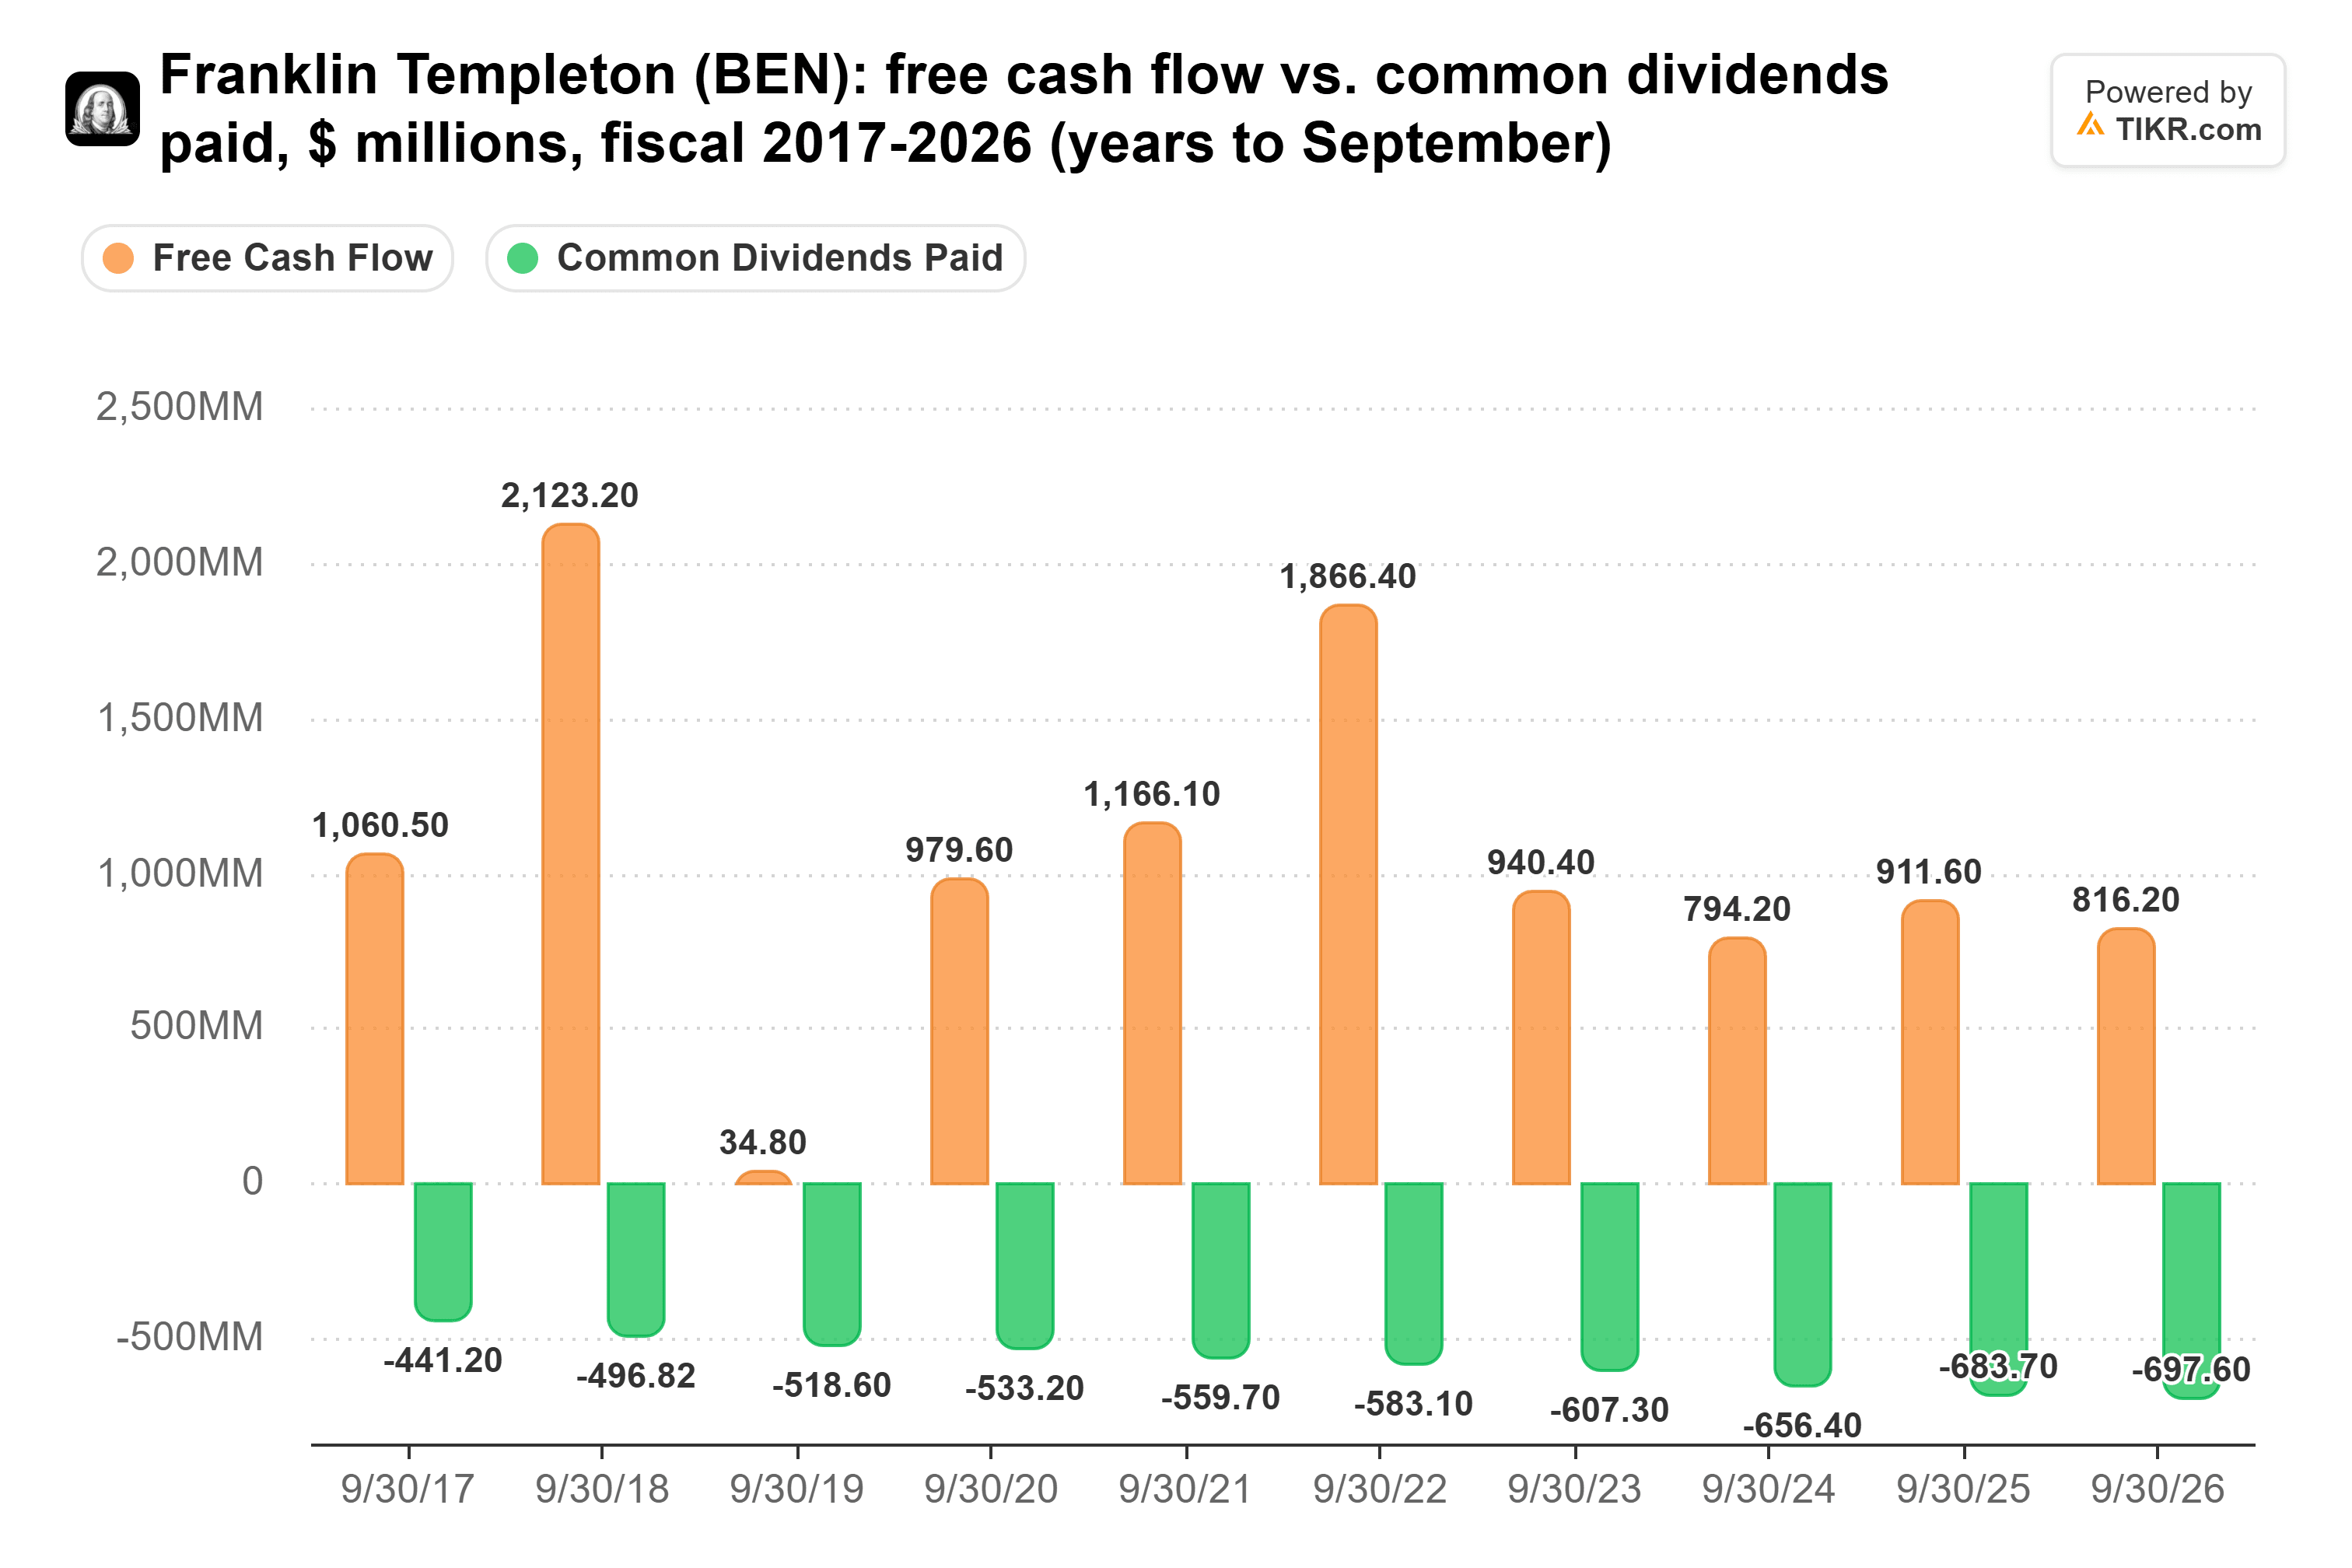
Free cash flow fell from $1.87 billion in fiscal 2022 to $816 million in fiscal 2026, while dividends paid rose from $583 million to $698 million. That’s a thin 85% cash dividend payout ratio over the 12 months to Sept. 30, 2026.
Franklin says it has raised its dividend every year since 1981, and management said on its July call that keeping it rising is always a high priority. With 85% of free cash flow already paid out, Franklin needs the business to keep improving to make good on that. The raises are small, at least. The last one, on Dec. 17, 2025, took the quarterly dividend from $0.32 to $0.33, up 3.1%.
So which dividend wins?
Franklin Templeton gets my dividend dollars for the next 10 years.
It comes down to the size of the check. $10,000 in Franklin pays $380 a year today, against $260 in P&G. At each company’s 5-year rate of raises, Franklin pays about $4,425 over the decade and P&G pays about $3,367, so Franklin pays about $1,058 more. By year 10, Franklin’s check would be about $511, a 5.1% yield on the $10,000. P&G’s income wouldn’t pass it until around 2044.
Franklin needs only 3.3% raises a year to get there. If its inflows keep coming and its margin reaches 30%, it should be able to afford those raises and rebuild some room in its payout ratio.
P&G’s dividend is the safer one. It leaves a third of its free cash flow to spare after paying the dividend, and it has 70 years of raises behind it. Investors pay a little more than usual for that safety:
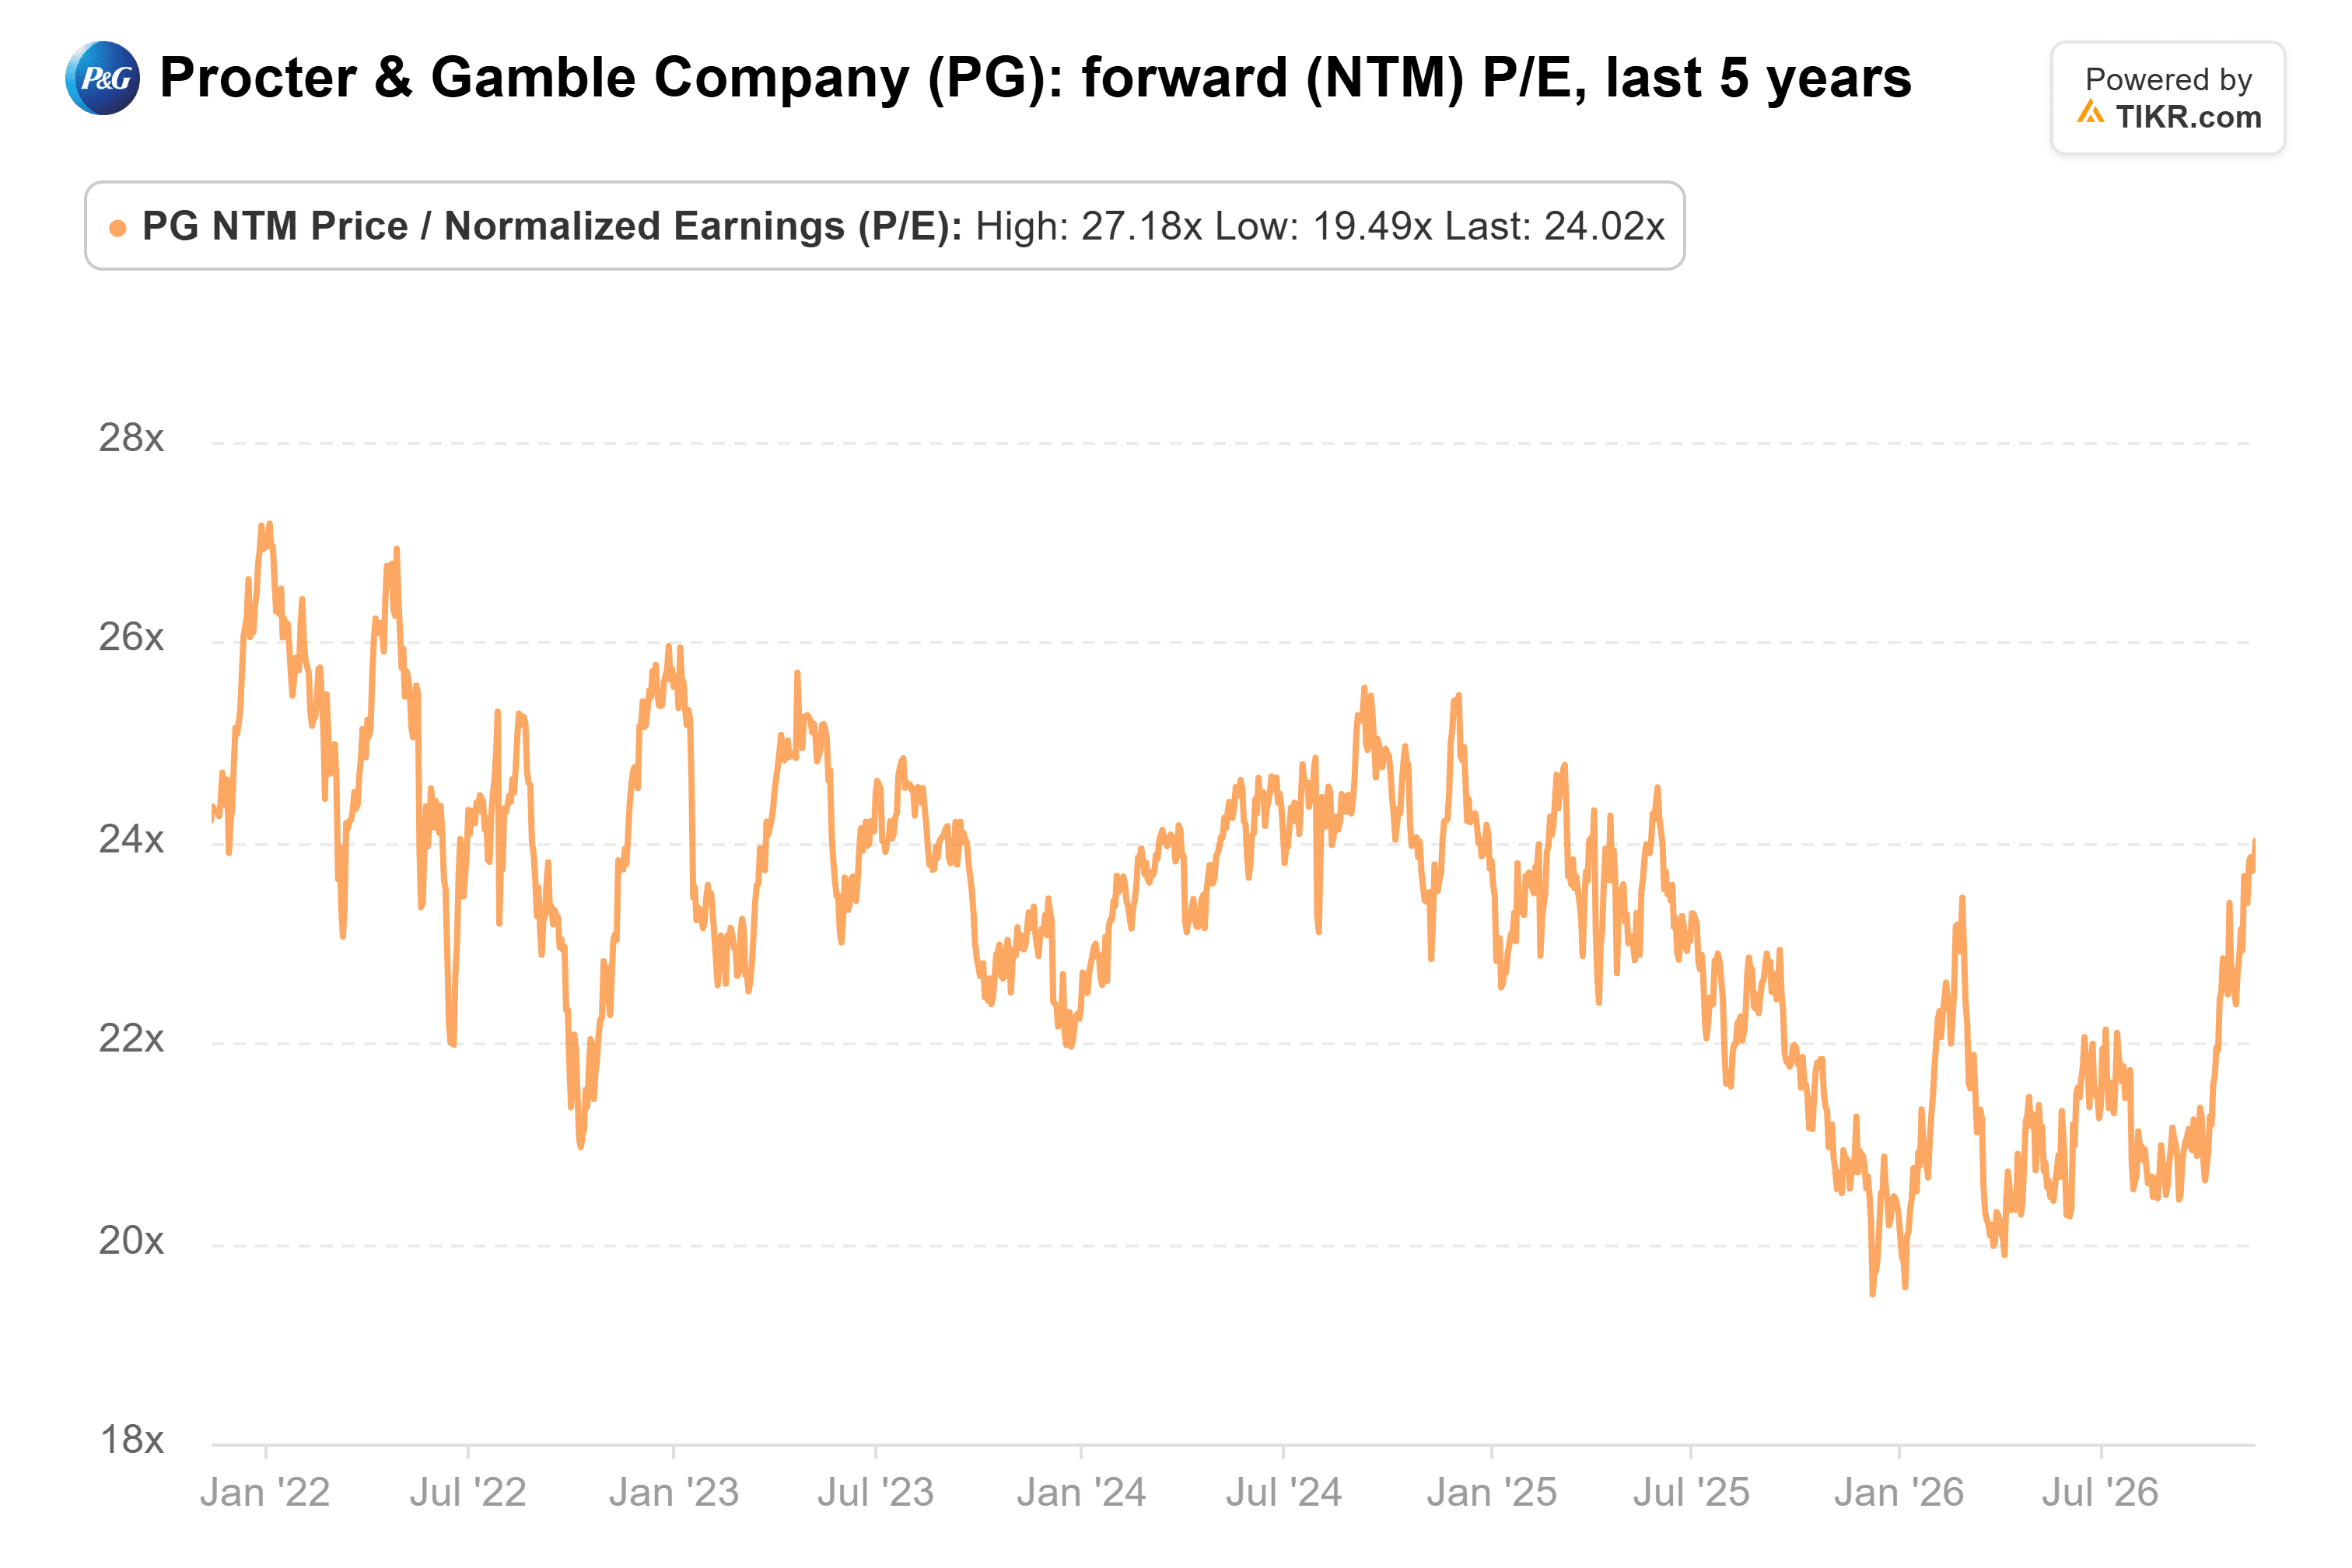
P&G trades at 24x forward earnings, against a five-year average of 23.3x, while Franklin trades at 11x. Over 10 years, though, I’d leave too much income on the table with P&G, a company guiding to core EPS growth of no more than 3% this fiscal year.
Franklin announced last year’s raise in December, so the next check-in is weeks away. Another raise would keep it on track. If its free cash flow keeps falling, though, I’d be rethinking P&G.
Forget Franklin Templeton: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Franklin Templeton isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!