Key Takeaways
- A fund that manages $2.9 billion opened a new Microsoft stake worth $135 million in the third quarter, making it the largest holding in its latest 13F.
- It also added 26% to its Aramark shares and 46% to its Sherwin-Williams shares, its second- and third-largest positions.
- Analysts’ average targets sit 31% above Microsoft’s price and 25% above Aramark’s, but only 10% above Sherwin-Williams’, where targets have slipped over the past year.
- Microsoft is the one the numbers back best, though its shrinking free cash flow is the risk to watch.
Microsoft (MSFT) wasn’t in Mane Global Capital Management’s 13F at the end of June. By Sept. 30, it was the fund’s biggest holding.
That’s the standout move in the firm’s 13F for the quarter ended Sept. 30, filed Nov. 16. Mane manages $2.94 billion in all, and its 13F lists $1.84 billion of US stocks across 60 positions. It also added to its next two largest holdings, Aramark (ARMK) and Sherwin-Williams (SHW).
Microsoft goes straight to No. 1
Mane held 263,799 Microsoft shares at Sept. 30, worth $135 million, or 7.3% of its 13F stocks. The stock is down 6% since then.
Analysts haven’t backed off. Their average target dipped to $556 in late July and has since climbed to $636, its high for the past year:
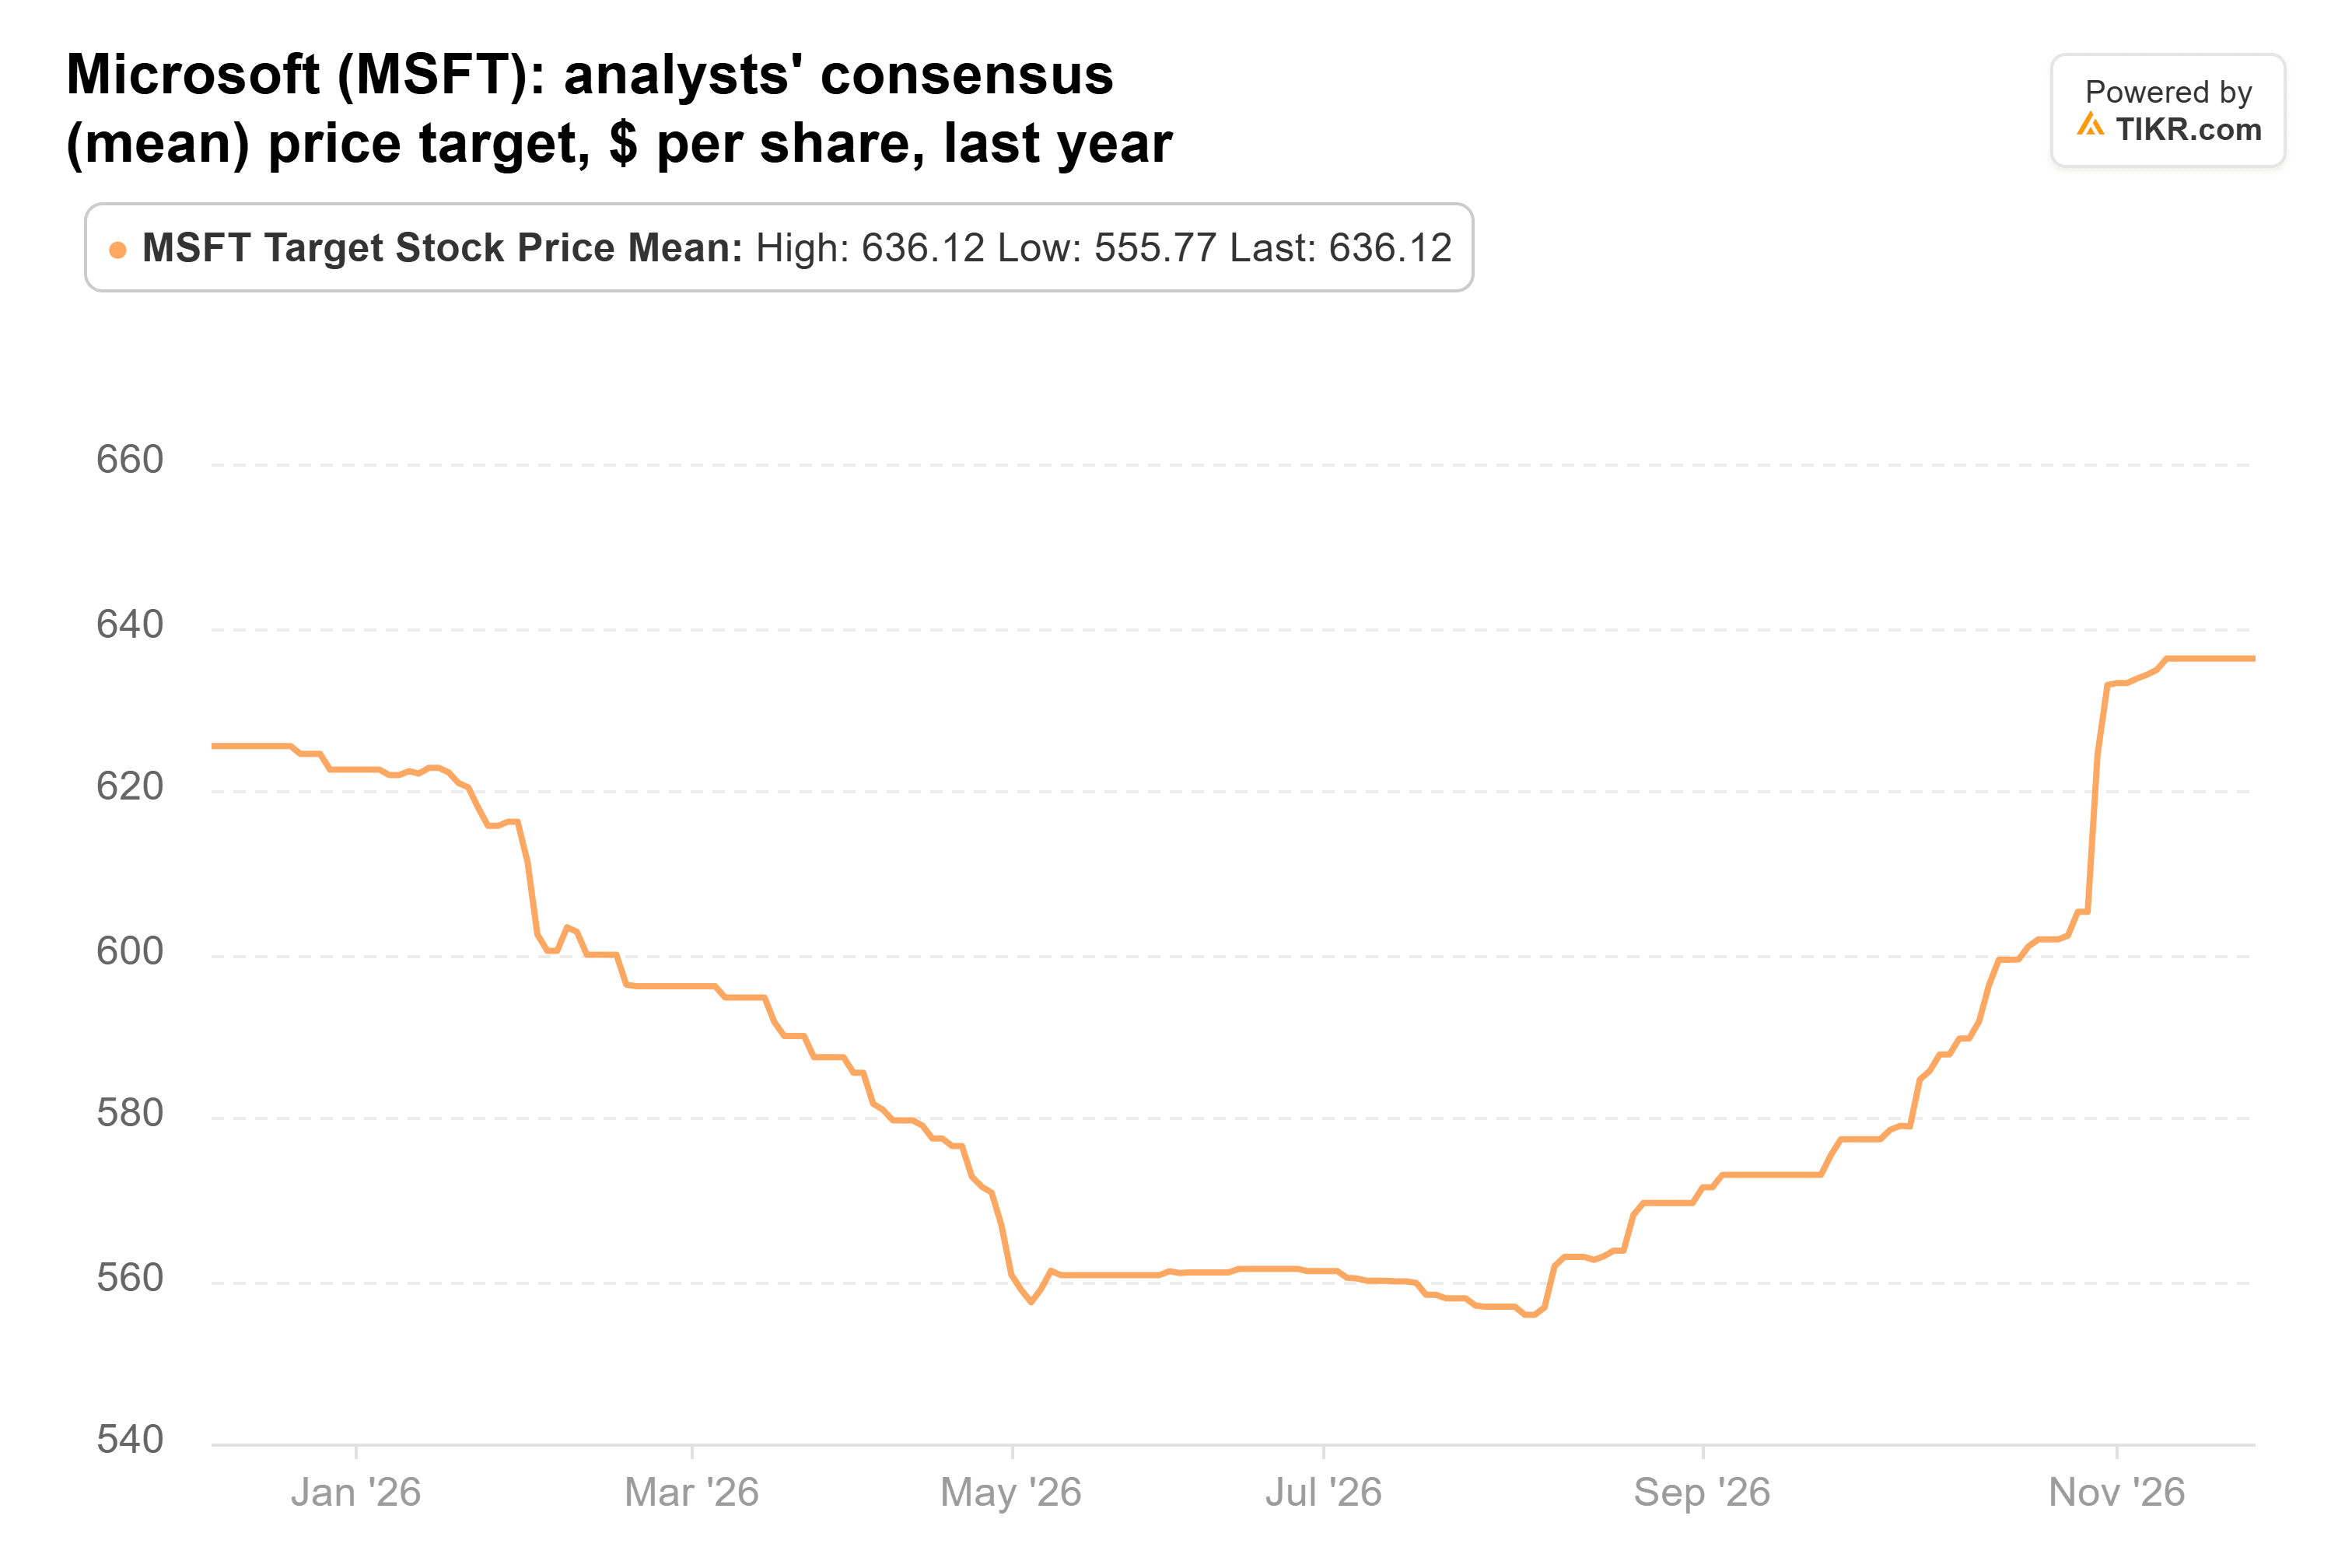
That’s 31% above where the stock trades now. At about 23x forward earnings, Microsoft also trades below its five-year average of 29x. Analysts expect adjusted EPS to grow 14% to $19.76 in fiscal 2027, which ends next June.
TIKR tracks 58 analysts on Microsoft. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Microsoft, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Microsoft’s Analyst Ratings
Aramark has an AI kicker
Mane held 1.32 million Aramark shares at Sept. 30, worth $71 million. That’s 26% more shares than at the end of June, and 3.9% of its 13F stocks. Shares have barely moved since then, up 0.5%.
The business has real momentum. In the fourth quarter of fiscal 2026, which ended Oct. 2, organic revenue grew 12%. About 2 points of that came from a calendar shift. Adjusted EPS rose 25% in constant currency to $0.71, even after $0.07 of extra incentive pay. Aramark also booked a record $1.9 billion of gross new business for the year.
Then there’s Aramark Nexus, which Aramark launched in May to serve hyperscale AI data centers. CEO John Zillmer said at the time that its new multi-year client, a top global hyperscaler, “is expected to become the largest in our portfolio.”
Analysts have chased the story. Their average target is up 51% in a year, from $44.60 to $67.34:
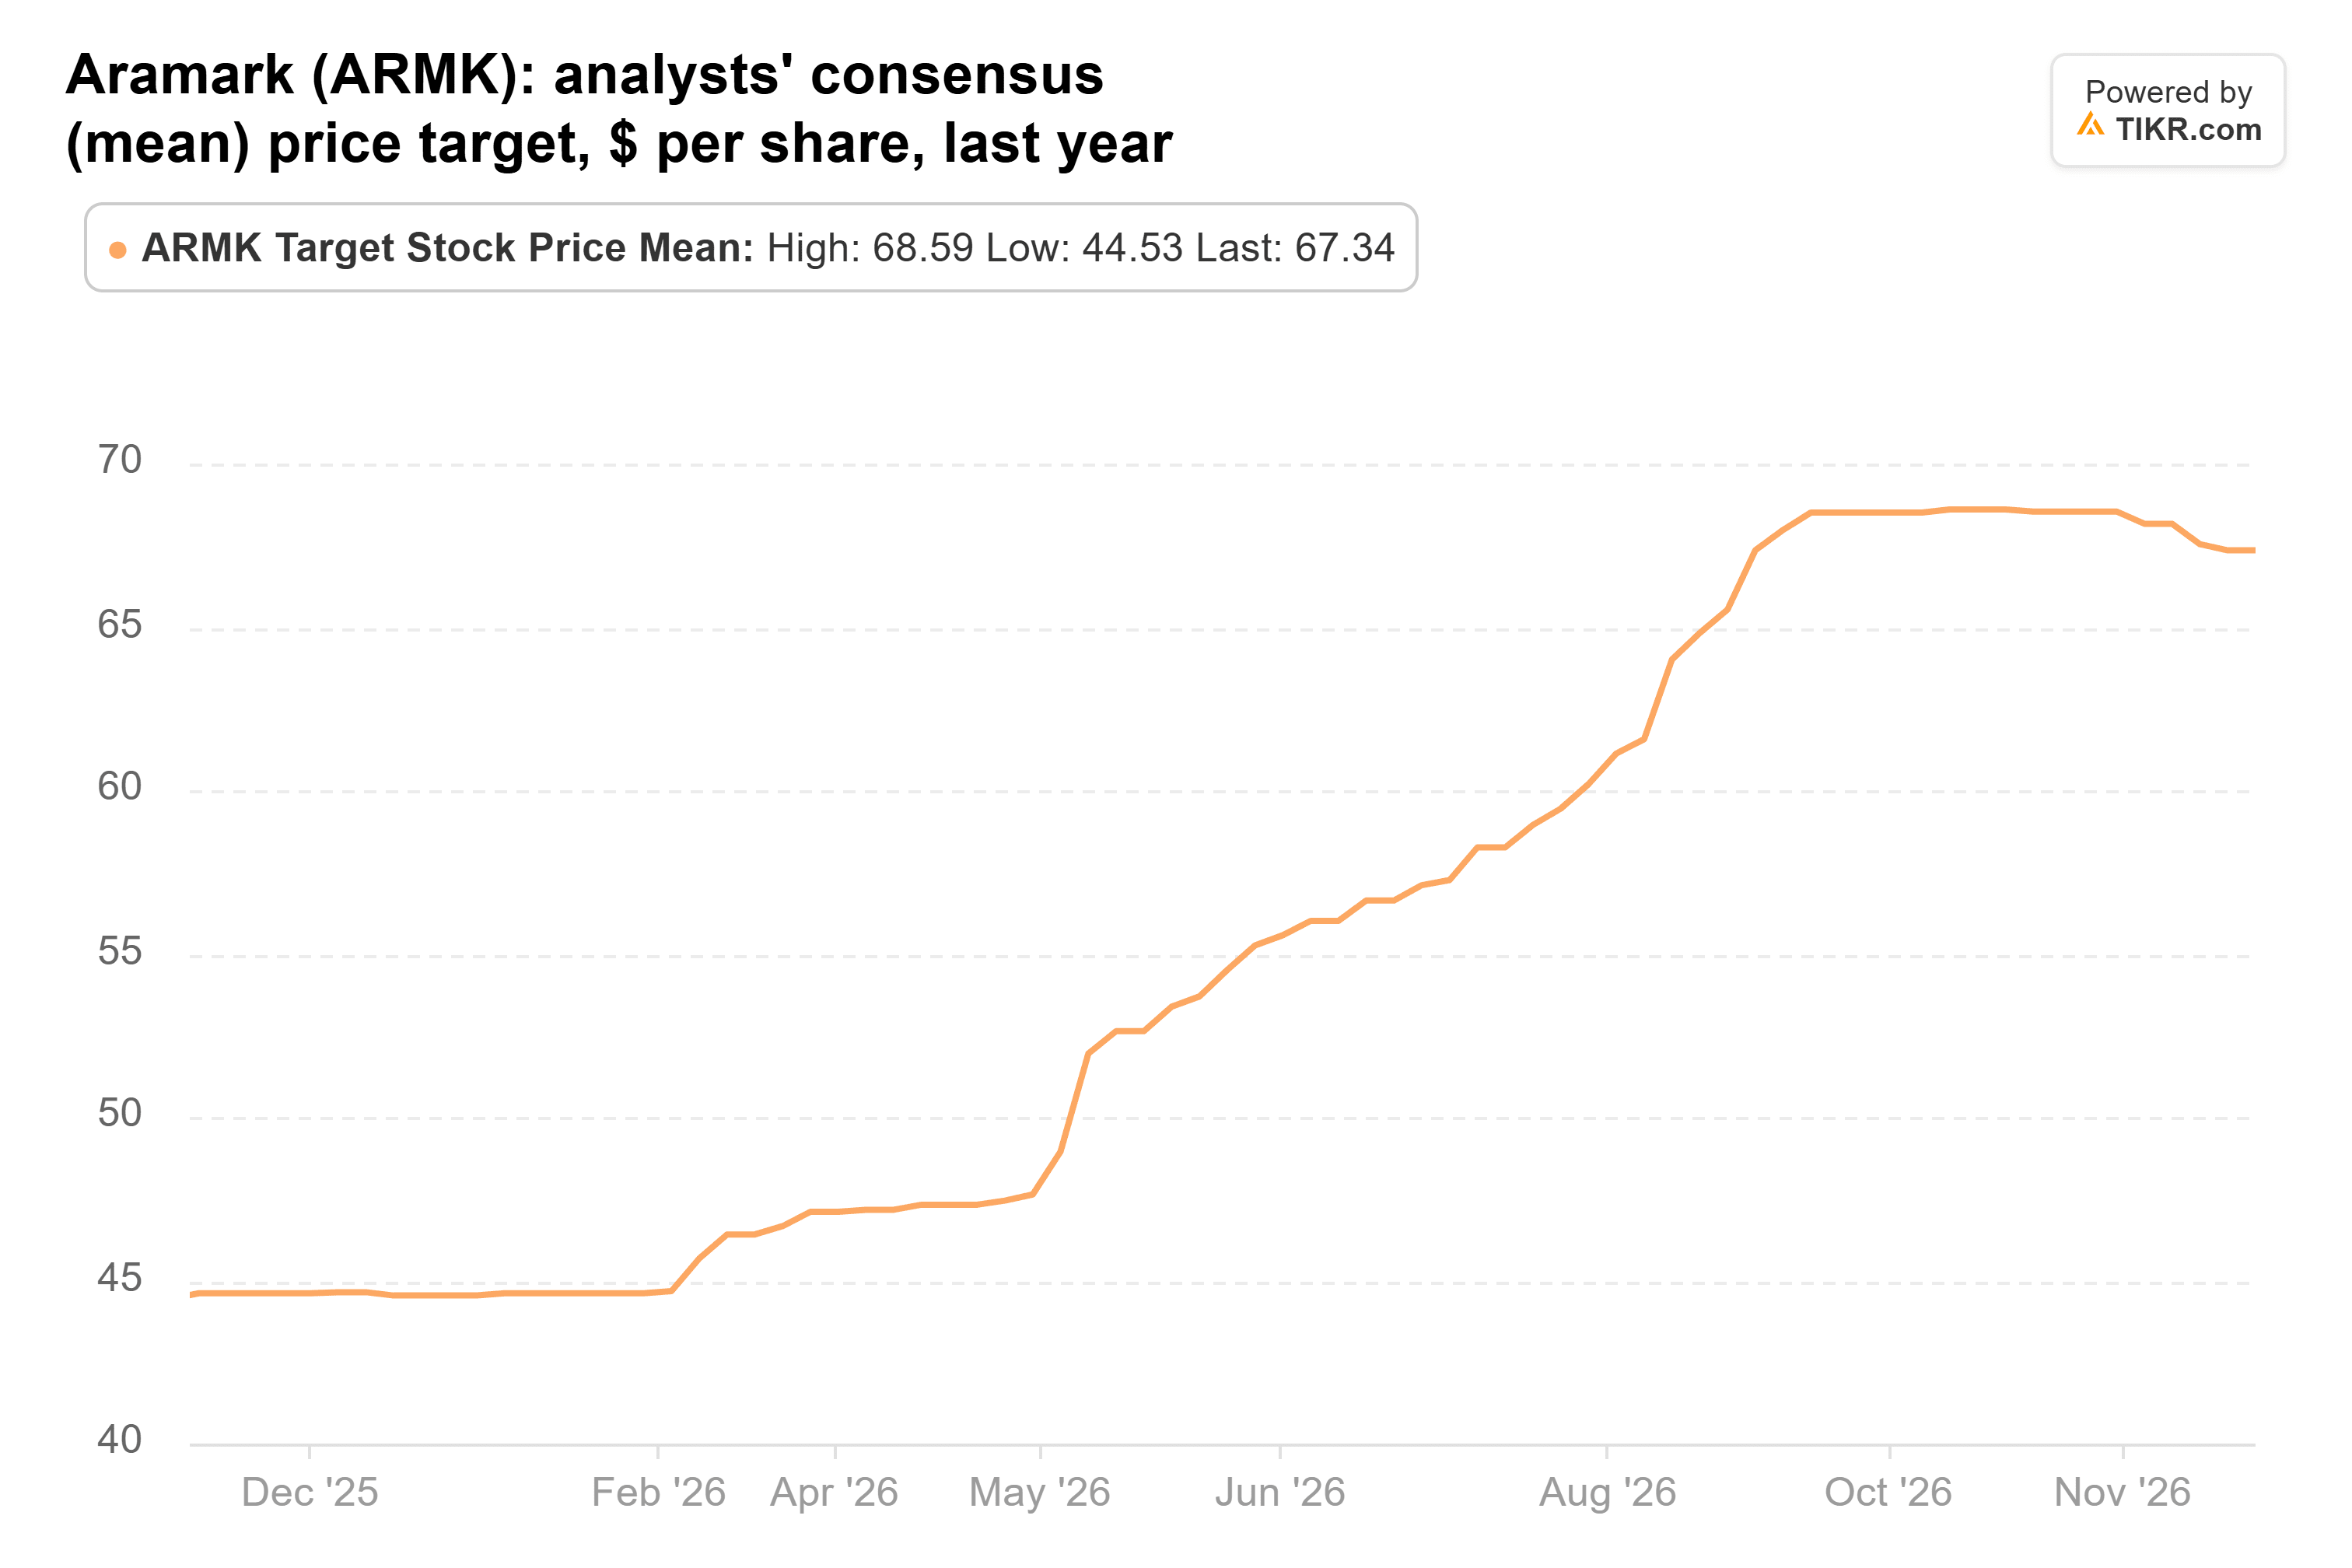
That still leaves 25% upside, with the stock at about 20x forward earnings.
Sherwin-Williams is the harder sell
Mane added 46% to its Sherwin-Williams stake in the third quarter. That left it with 216,733 shares worth $70 million at Sept. 30, or 3.8% of its 13F stocks, and the stock has gained 5% since then.
Sales are growing faster than profits. Third-quarter net sales rose 7.9% to $6.86 billion, helped by price increases and the October 2025 purchase of Suvinil. But gross margin fell to 47.8% from 49.2%. Management blamed higher raw material and supply chain costs, Suvinil’s lower margins and faster growth in its lower-margin segments.
Adjusted EPS rose just 1.1%, to $3.63, and management now guides full-year adjusted EPS to $11.85-$12.15. An 8% price increase took effect Sept. 1, so only one month of it shows up in the third quarter. The fourth quarter will show more of it.
Analysts have trimmed their expectations. Their average target slipped from $385.81 a year ago to $373.83:

That’s just 10% above the stock, which trades at about 26x forward earnings, the highest multiple of the three.
Microsoft is the one to follow
Microsoft has the most upside of the three. Analysts also expect its adjusted EPS to rise another 20% in fiscal 2028, to $23.70. Frankly, that’s a lot of growth for a stock at 23x forward earnings.
The risk is cash. Analysts have cut their fiscal 2027 free cash flow estimate three times, to $32.0 billion, as capital spending climbs. Microsoft also added $7.4 billion of finance leases in the September quarter, and free cash flow doesn’t count them.
Aramark is a close second, with record new business and a data center client that management expects to become its biggest. Sherwin-Williams needs its price increases to win back margin before 10% upside looks like enough.
Microsoft’s December-quarter report, due in late January, is the next test. It made $18.6 billion of free cash flow in the September quarter. To reach the $32.0 billion estimate, it needs about $13.4 billion more from the next three quarters combined. Mane’s next 13F, due in mid-February, will show whether it’s still holding the stock.
So what is Microsoft stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Microsoft could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!