Key Takeaways
- Wesco CFO Neel Dev bought $503,528 of stock in the open market on Nov. 5, and its HR chief Anthony Marino bought $99,903 more the next day.
- The two bought at about 25% below the stock’s October high, a week after Wesco posted a record quarter and raised its 2026 outlook.
- Analysts expect earnings per share to grow about 19% a year in 2027 and 2028, and their consensus target is up 71% over the past year.
- The numbers back the buy, though both purchases came with matching stock options. Wesco’s 2027 outlook in February is what to watch next.
Wesco International (WCC) just got a vote of confidence from the executive who walks investors through its numbers. CFO Indraneel “Neel” Dev bought 1,725 shares in the open market on Nov. 5 at an average of $291.90 a share, or $503,528 in all, according to the Form 4 he filed on Nov. 9.
He wasn’t the only one buying. Chief Human Resources Officer Anthony S. Marino bought 341 shares the next day at an average of $292.97, or $99,903. Both bought with the stock about 25% below its Oct. 6 intraday high of $388.64. At its Nov. 9 close of $316.47, it’s still 19% off that high, but up 24% over the past year.
The business gave no reason to sell
On Oct. 29, Wesco reported a record third quarter. Net sales rose 17% to $7.2 billion, data center sales jumped about 55% to $1.8 billion, and adjusted EPS climbed 47% to $5.77. Backlog was up about 80%, and CEO John Engel said “our backlog growth is being fueled by multi-year customer commitments.”
Management raised its 2026 outlook again, to adjusted EPS of $18 to $18.50. The stock fell anyway, dropping about 19% over Nov. 4 and Nov. 5 from its $351.61 close on Nov. 3. The first day’s slide came amid a sector-wide selloff, with no news from Wesco. Dev bought on the second day.
TIKR tracks 11 analysts on Wesco International. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Wesco International, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Wesco International’s Analyst Ratings
Dev put real money in
Dev’s purchase grew his stake 10%, to 18,621 shares. Marino spent less, but his buy grew his stake by a third, to 1,363 shares. Plenty of investors track insider buying for exactly this kind of signal.
These buys came with a sweetener, though. Under the terms Wesco disclosed when it hired Dev in February, he gets a matching stock option for each share he buys in his first year, up to twice his $800,000 base salary. Both executives’ filings report option grants equal to the shares they bought, vesting over three years.
That makes the bet more attractive, but the cash is still at risk: both paid market prices for their shares.
And Dev knows exactly what’s behind the guidance. On Wesco’s third-quarter call, he said nothing structural was behind a sequential dip in fourth-quarter margins, and he put it down to one fewer business day and the holidays.
$291.90 looks like a fair price
Analysts expect Wesco’s earnings to keep climbing well past this year:
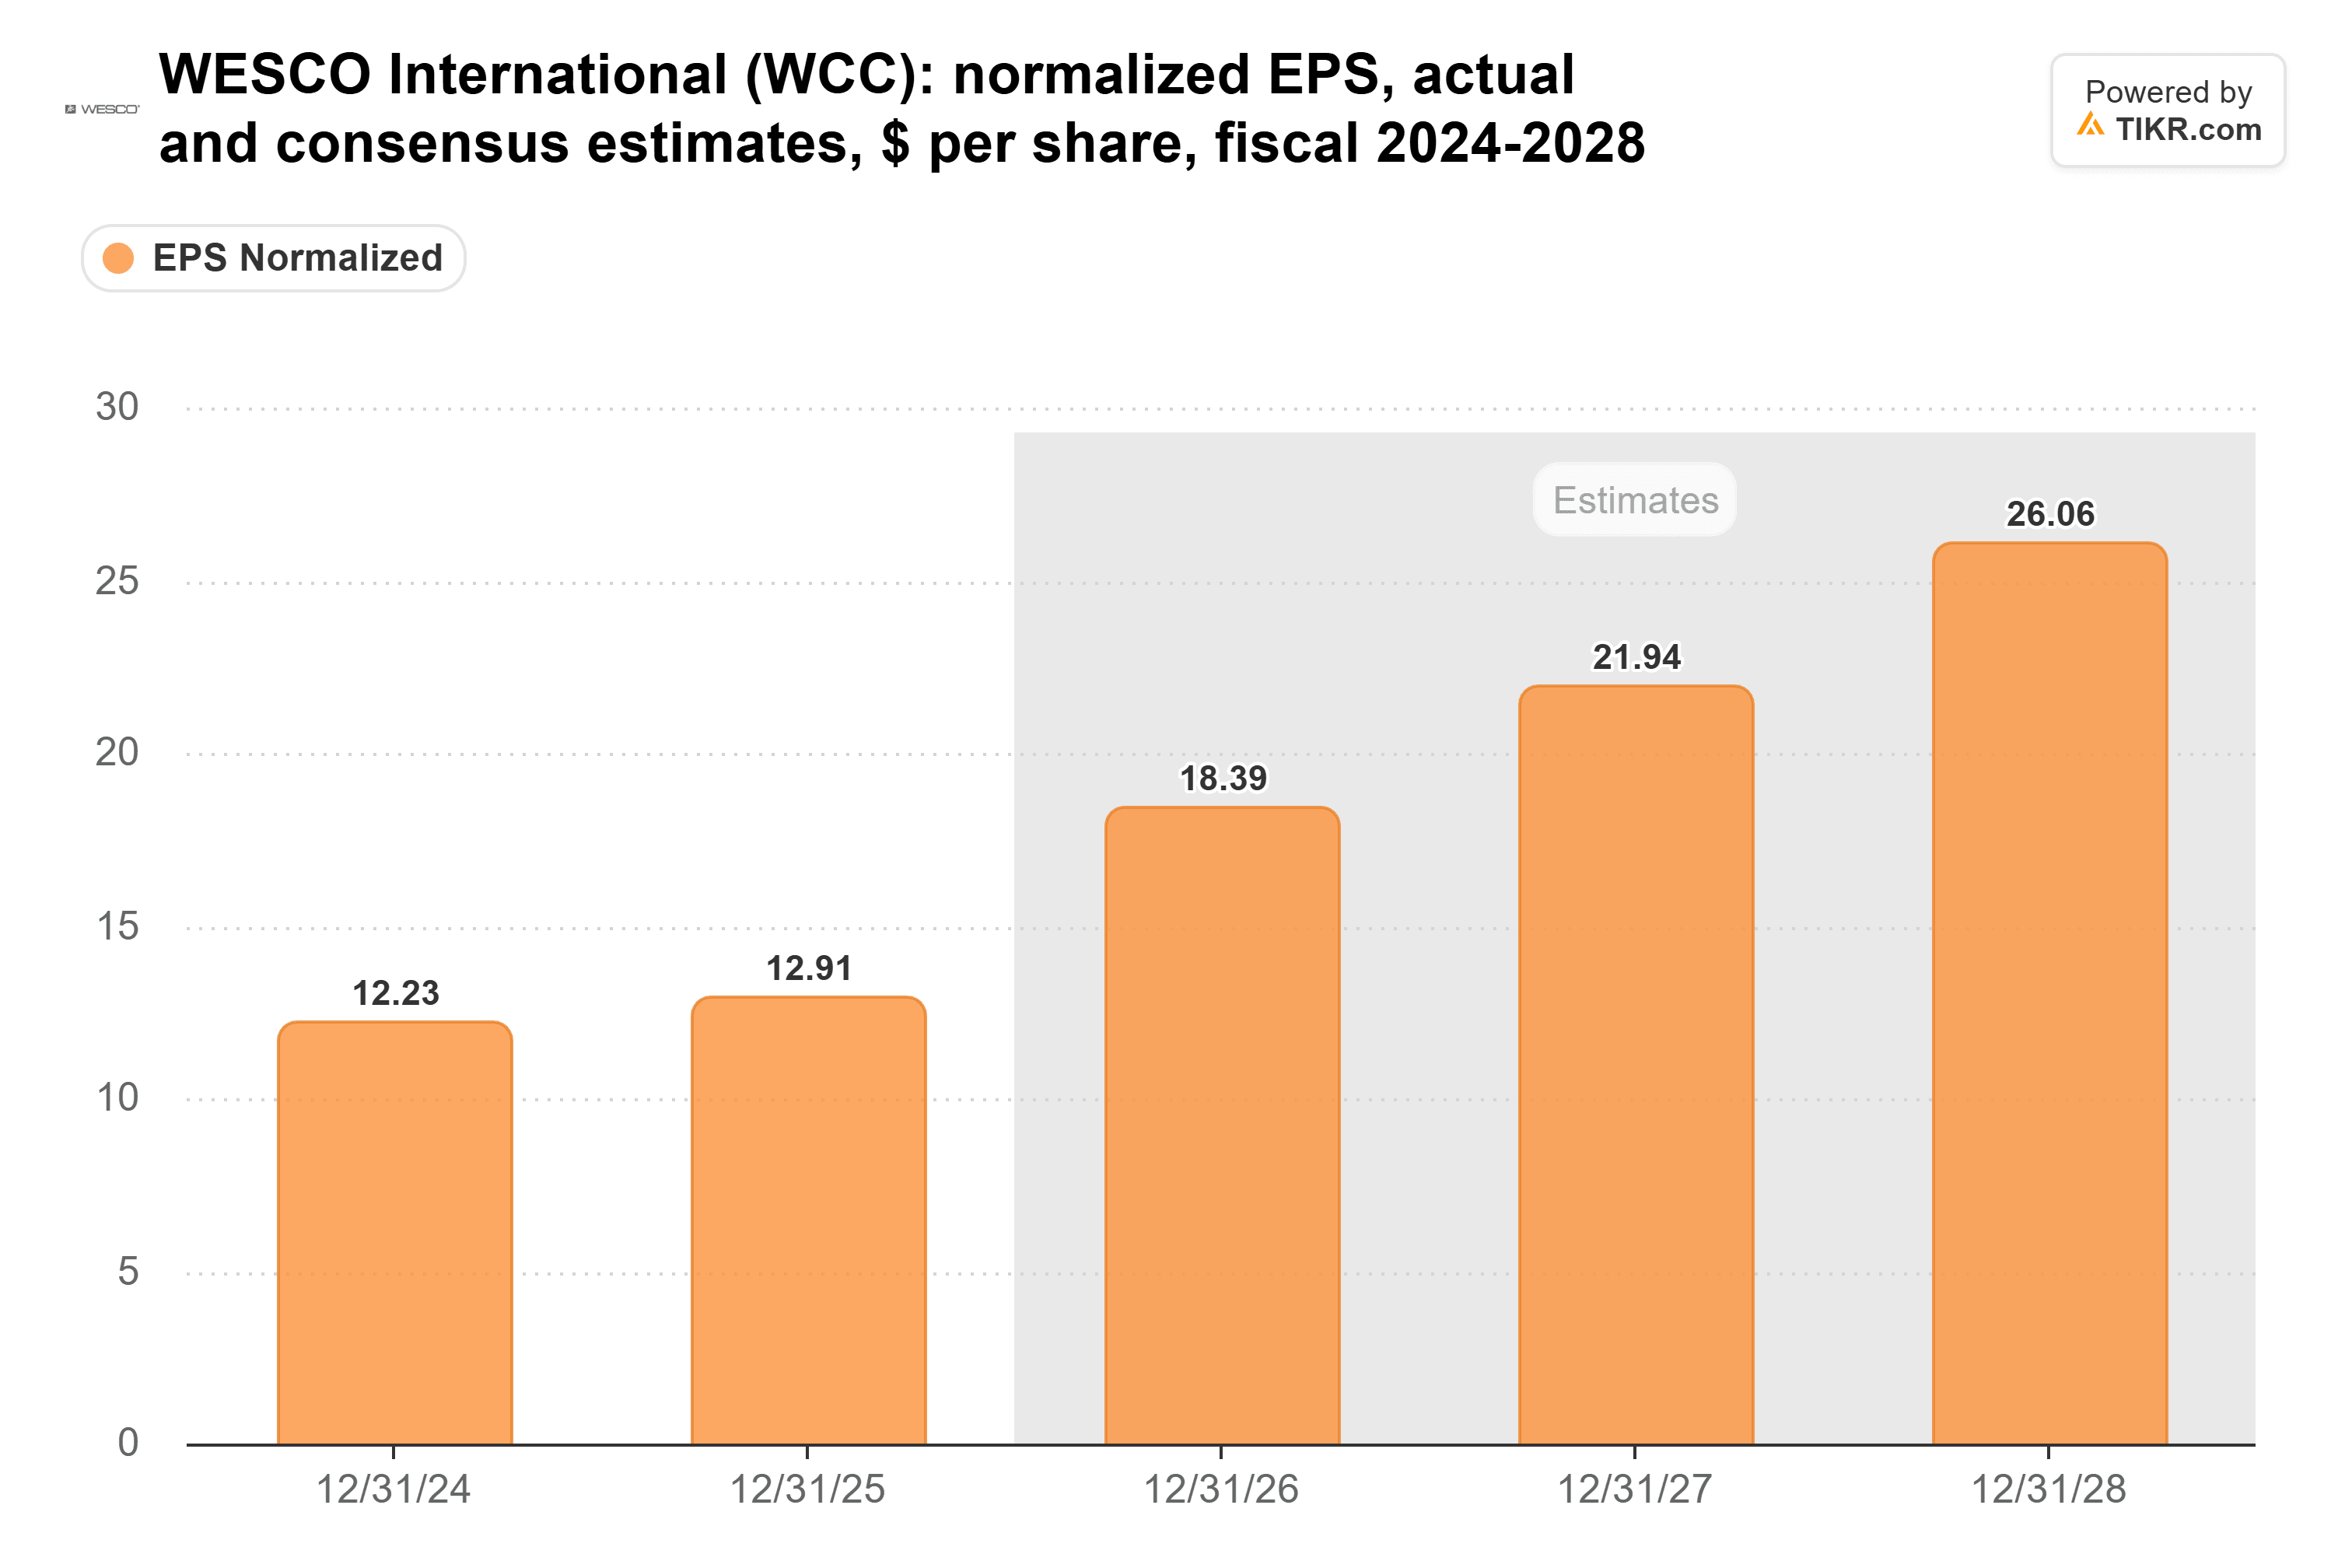
Consensus normalized EPS for 2026 is $18.39, inside management’s range and up 42% from $12.91 in 2025. Analysts then expect $21.94 in 2027 and $26.06 in 2028, roughly 19% growth a year. Getting there takes wider margins, since Engel sketched sales growth of mid- to high single digits for next year. He said the company’s digital overhaul should deliver “at least 100 basis points” of EBITDA margin expansion.
That growth comes at a multiple above the stock’s usual one:
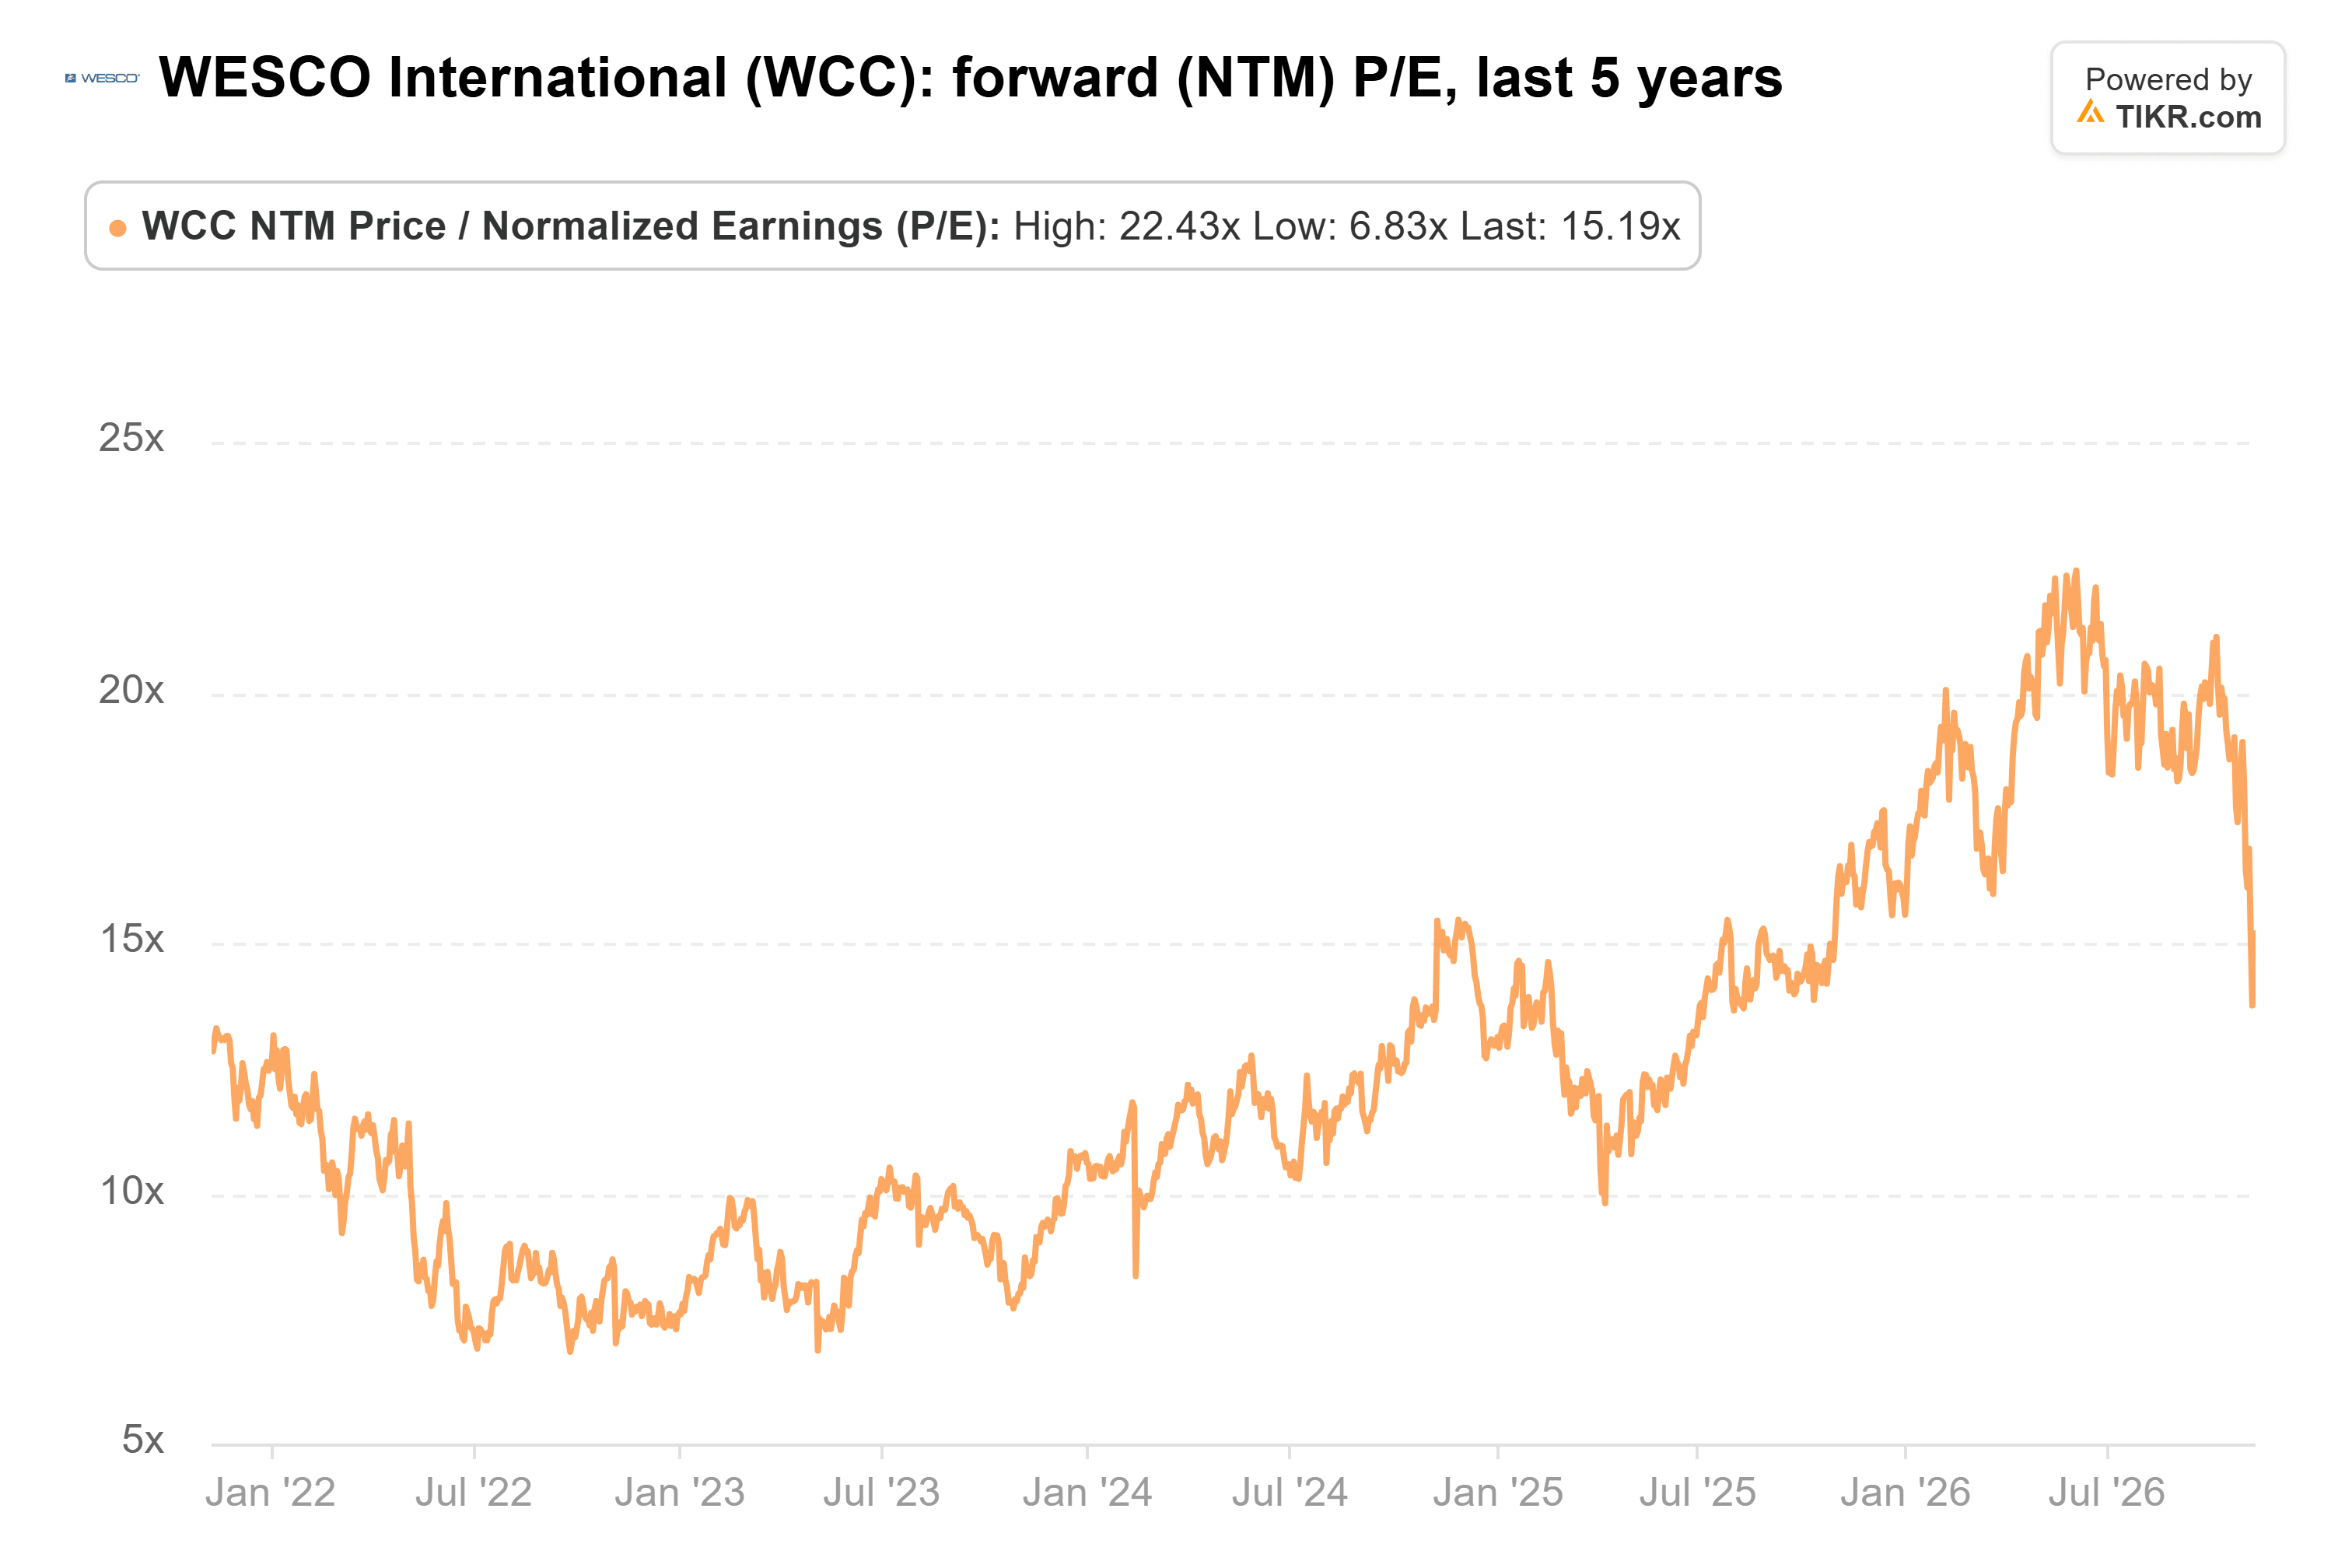
At that $316.47 close, Wesco traded at 15x forward earnings, against a five-year average of 12x and a peak of 22x on June 3. Dev paid about 14x, a modest premium for that kind of growth.
Wall Street’s targets have climbed all year:
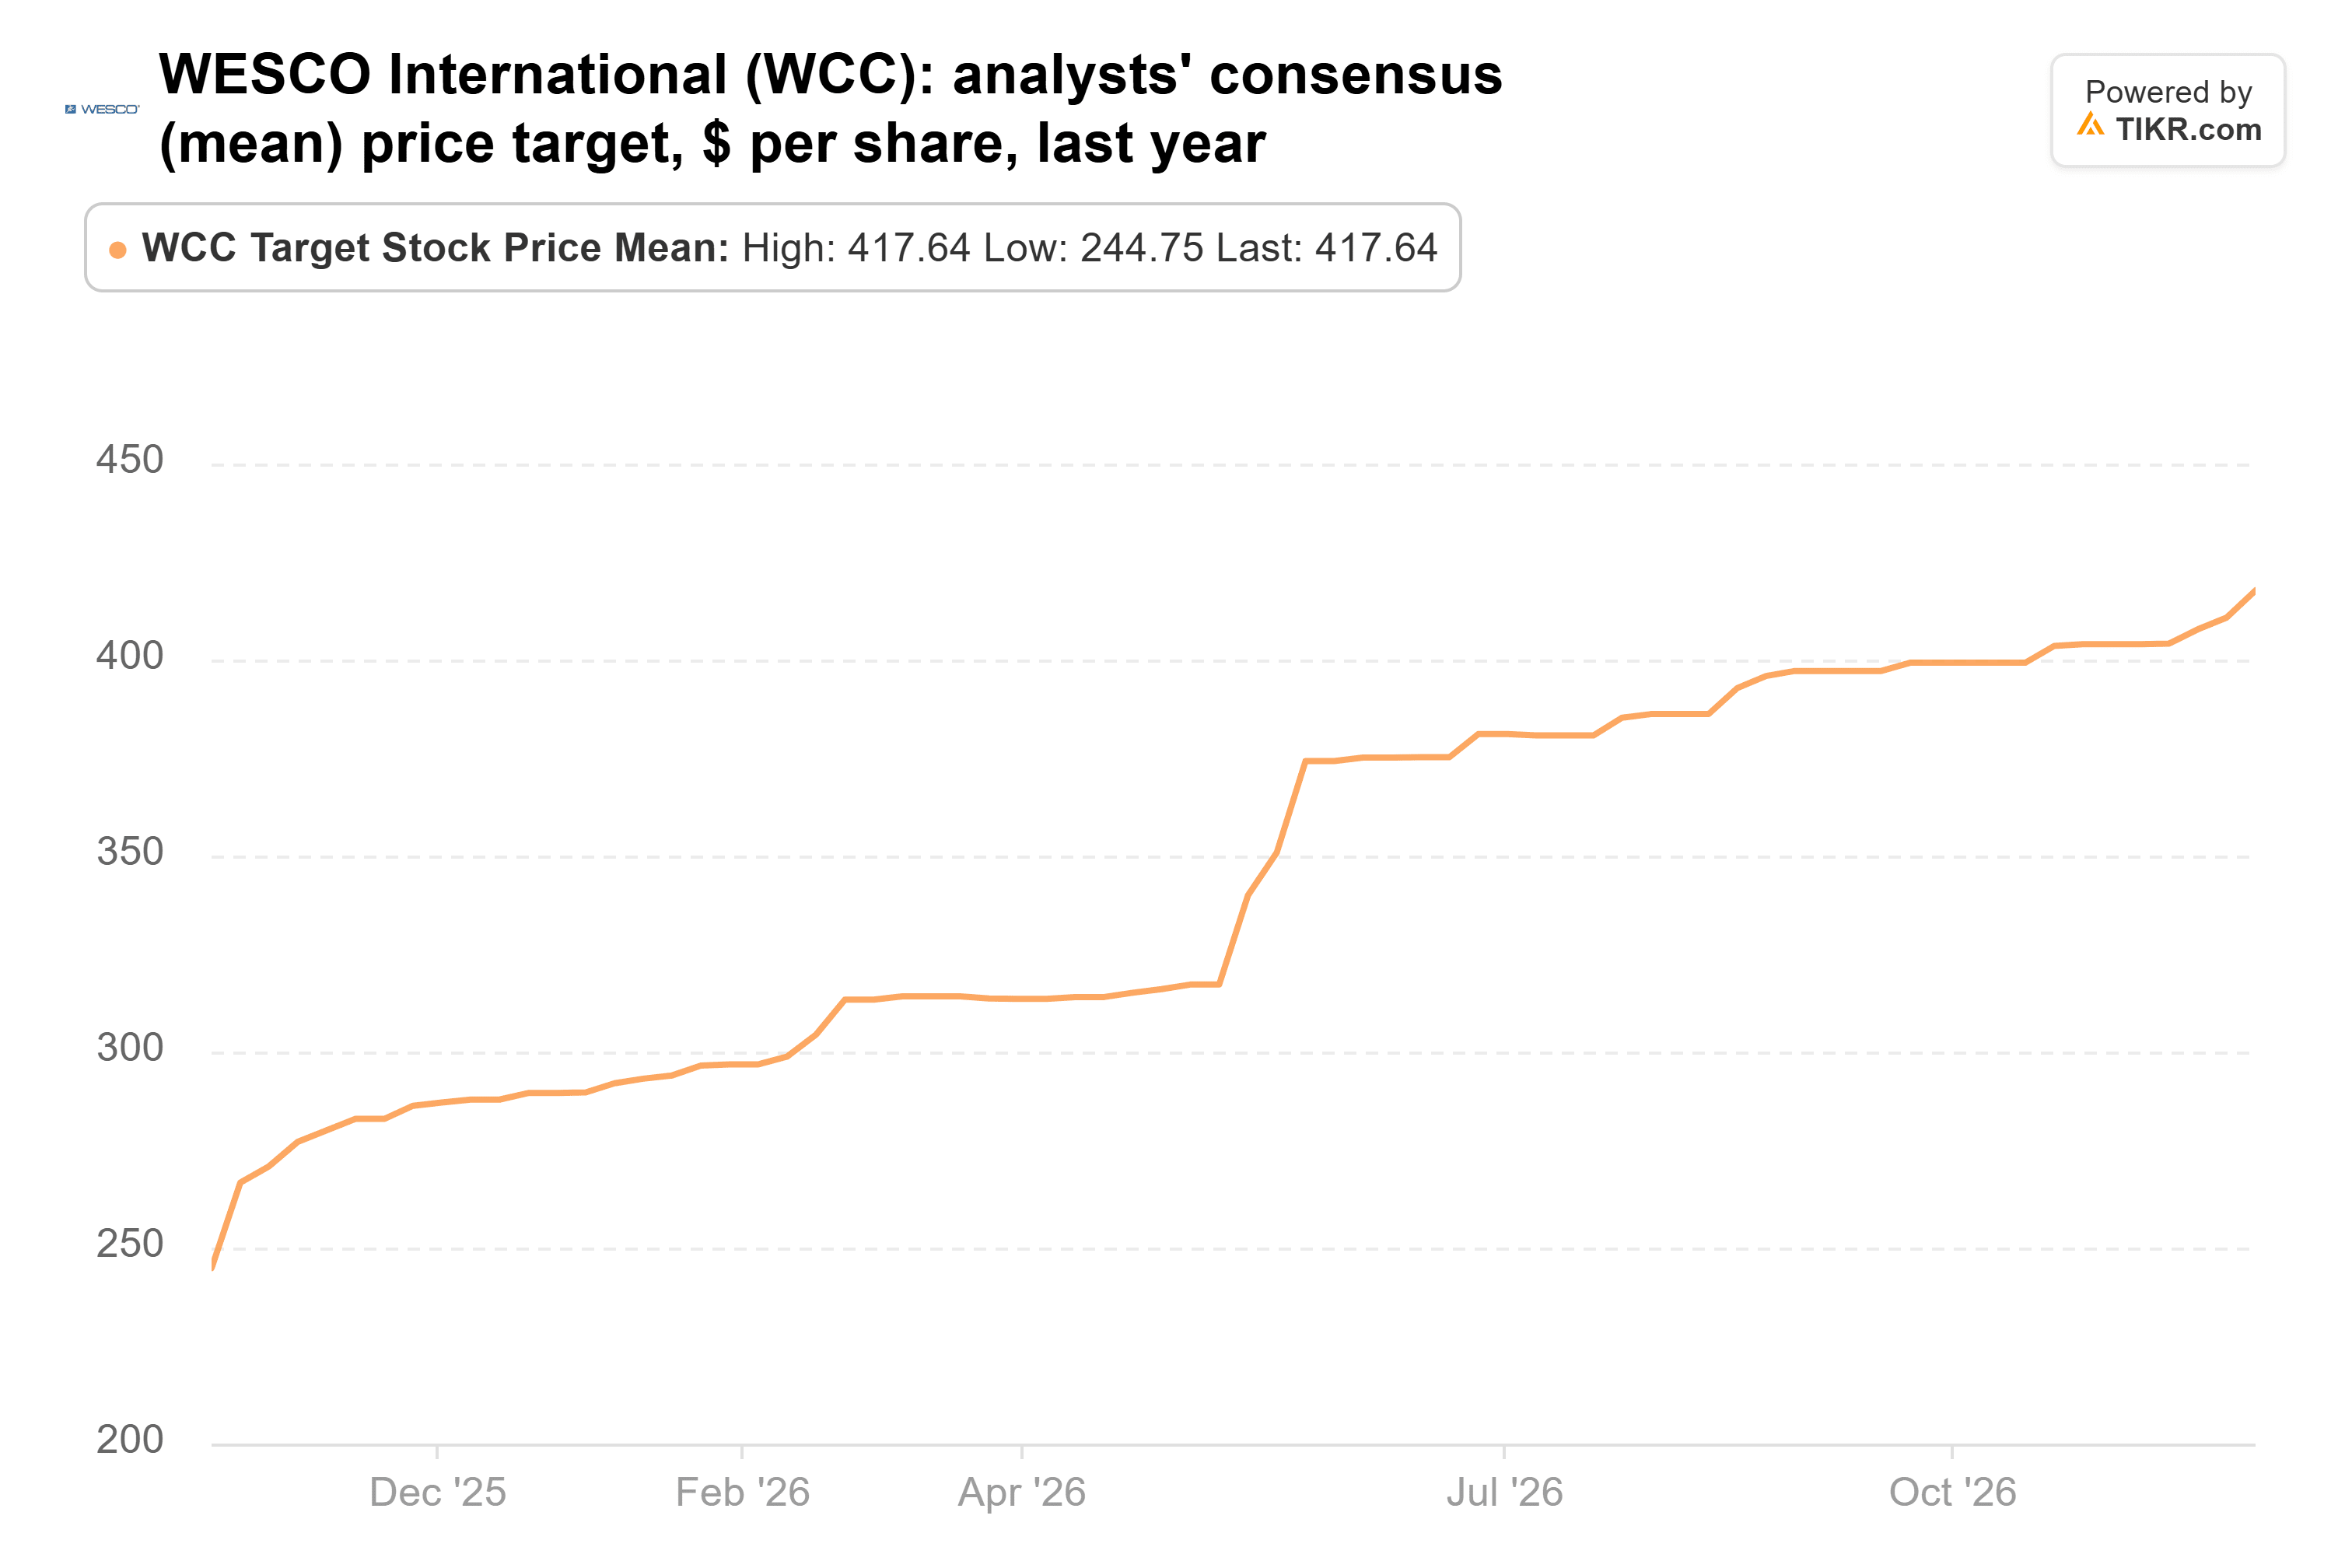
The consensus target rose from $244.75 a year ago to $417.64 by Oct. 30, 32% above the Nov. 9 close. The lowest target, $283, is only 3% below what Dev paid.
The Math Sides With the CFO
The main risk is that Wesco leans on one hot market. Data centers are now about 23% of sales, and a pause in that building boom would hit Wesco’s fastest-growing business.
Still, the numbers back Dev. He paid a fair multiple for a company whose estimates and targets are still rising. Two executives’ buys are only a signal, though. At its Nov. 10 data center event, Wesco showed data centers growing from about 10% of sales in 2023 to more than 20% now, which sharpens that concentration risk. The real test is the 2027 outlook it’ll give with fourth-quarter results in February.
So what is Wesco stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Wesco could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!