Key Takeaways
- Former Stability AI CEO Emad Mostaque predicted that Tesla will sell more robots than cars within two years and that 10 million Optimus robots would bring in $400 billion of revenue.
- At 202x forward earnings, Tesla’s valuation only makes sense if Optimus becomes a much bigger business than cars.
- Mostaque’s math works out to $40,000 per robot, but analysts expect Tesla’s total revenue to reach just $142 billion in fiscal 2028.
- Optimus production is planned to start in 2027, and Tesla has already cut the memory in its AI5 chip to get enough volume for the robot.
Tesla (TSLA) has a valuation problem:
Its stock trades at 202x forward earnings, and selling cars won’t get it there.
Emad Mostaque, the former CEO of Stability AI, thinks he knows what will. On this week’s episode of the Moonshots podcast with Peter Diamandis, he gave the bull case in four sentences:
“Tesla sells 1.6 million cars a year. Within two years, it’ll be selling more robots. It makes 100 billion a year. At 10 million, that’s 400 billion of revenue.”
Then, for good measure: “That’s likely.”
Fellow panelist Salim Ismail, founder of OpenExO, added that Musk himself is betting the company on it: “Elon said 80% of Tesla’s future revenues he expects to come from the robots from Optimus.”
Why it has to be robots
Mostaque is answering the question the stock faces right now. Gary Black of the Future Fund, one of Tesla’s best-known bulls, just called the stock “rich by any standard” even after its latest delivery beat, as TIKR covered here.
TIKR’s numbers agree. At 202x next-twelve-months earnings, Tesla trades at nearly double its five-year average of 107x…
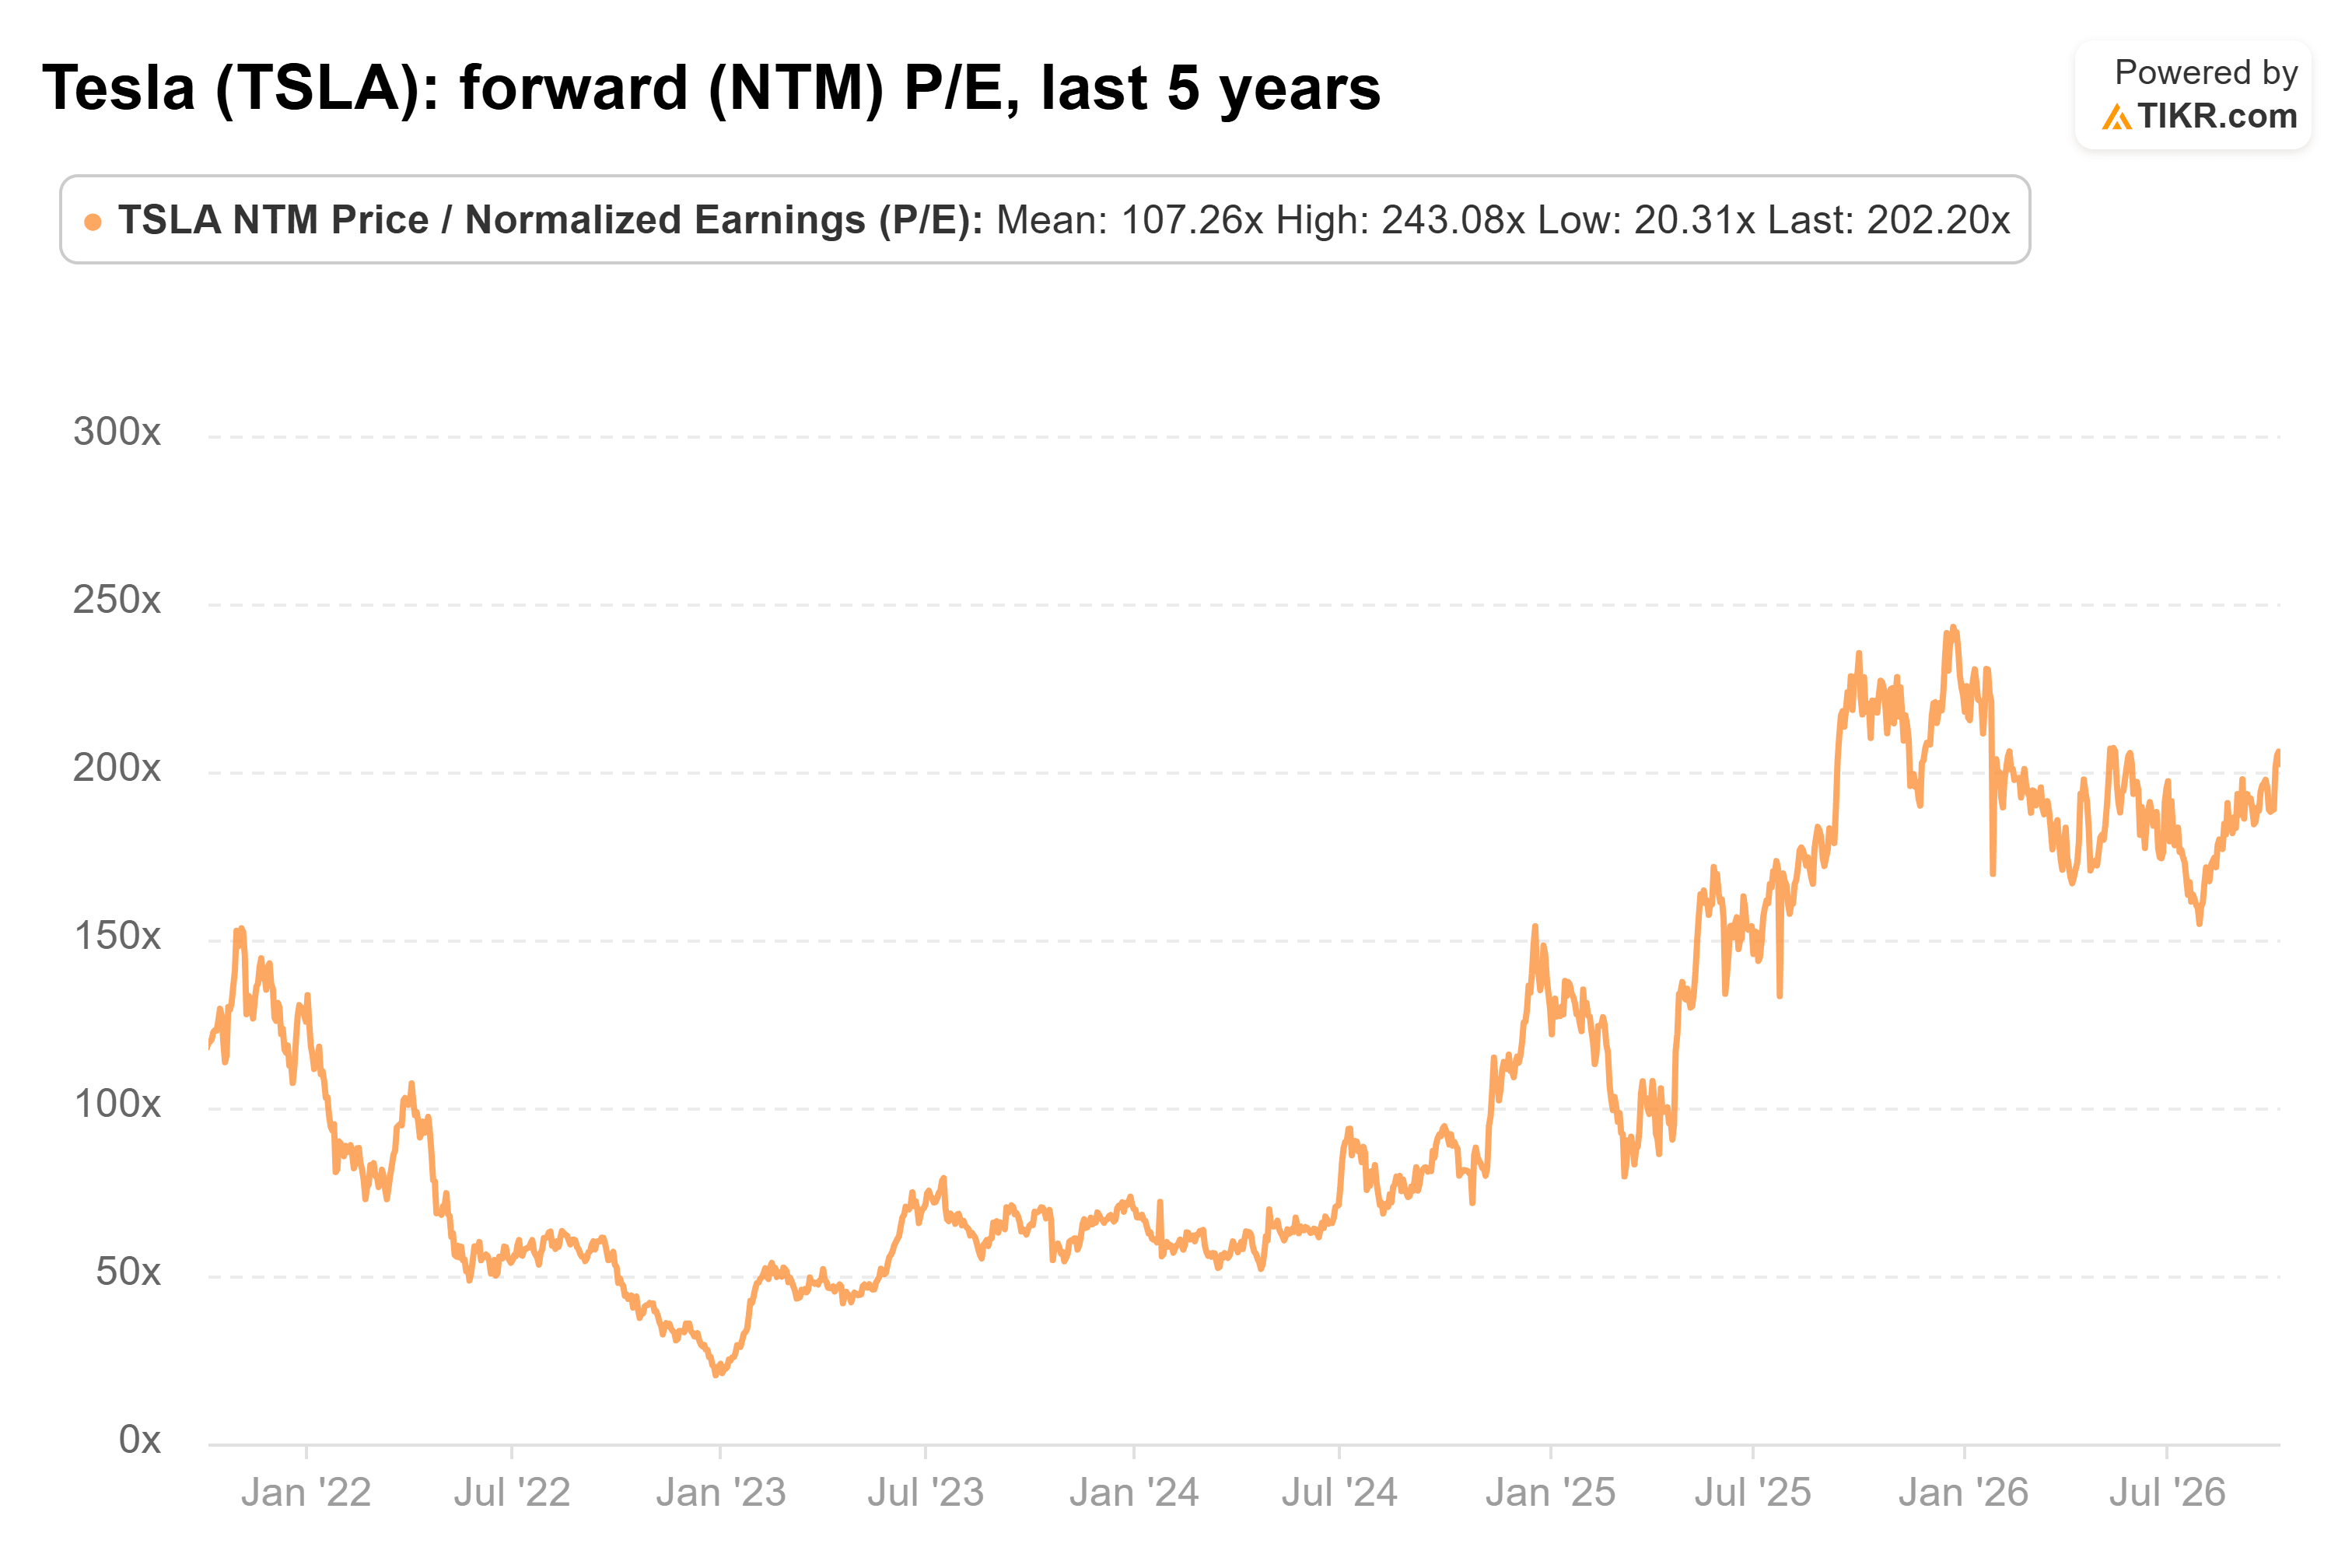
(It was even higher last December, peaking at 243x.)
The car business isn’t growing into that multiple, either. Tesla’s operating margin has fallen every year since fiscal 2022, from 16.8% that year to 4.6% in fiscal 2025:
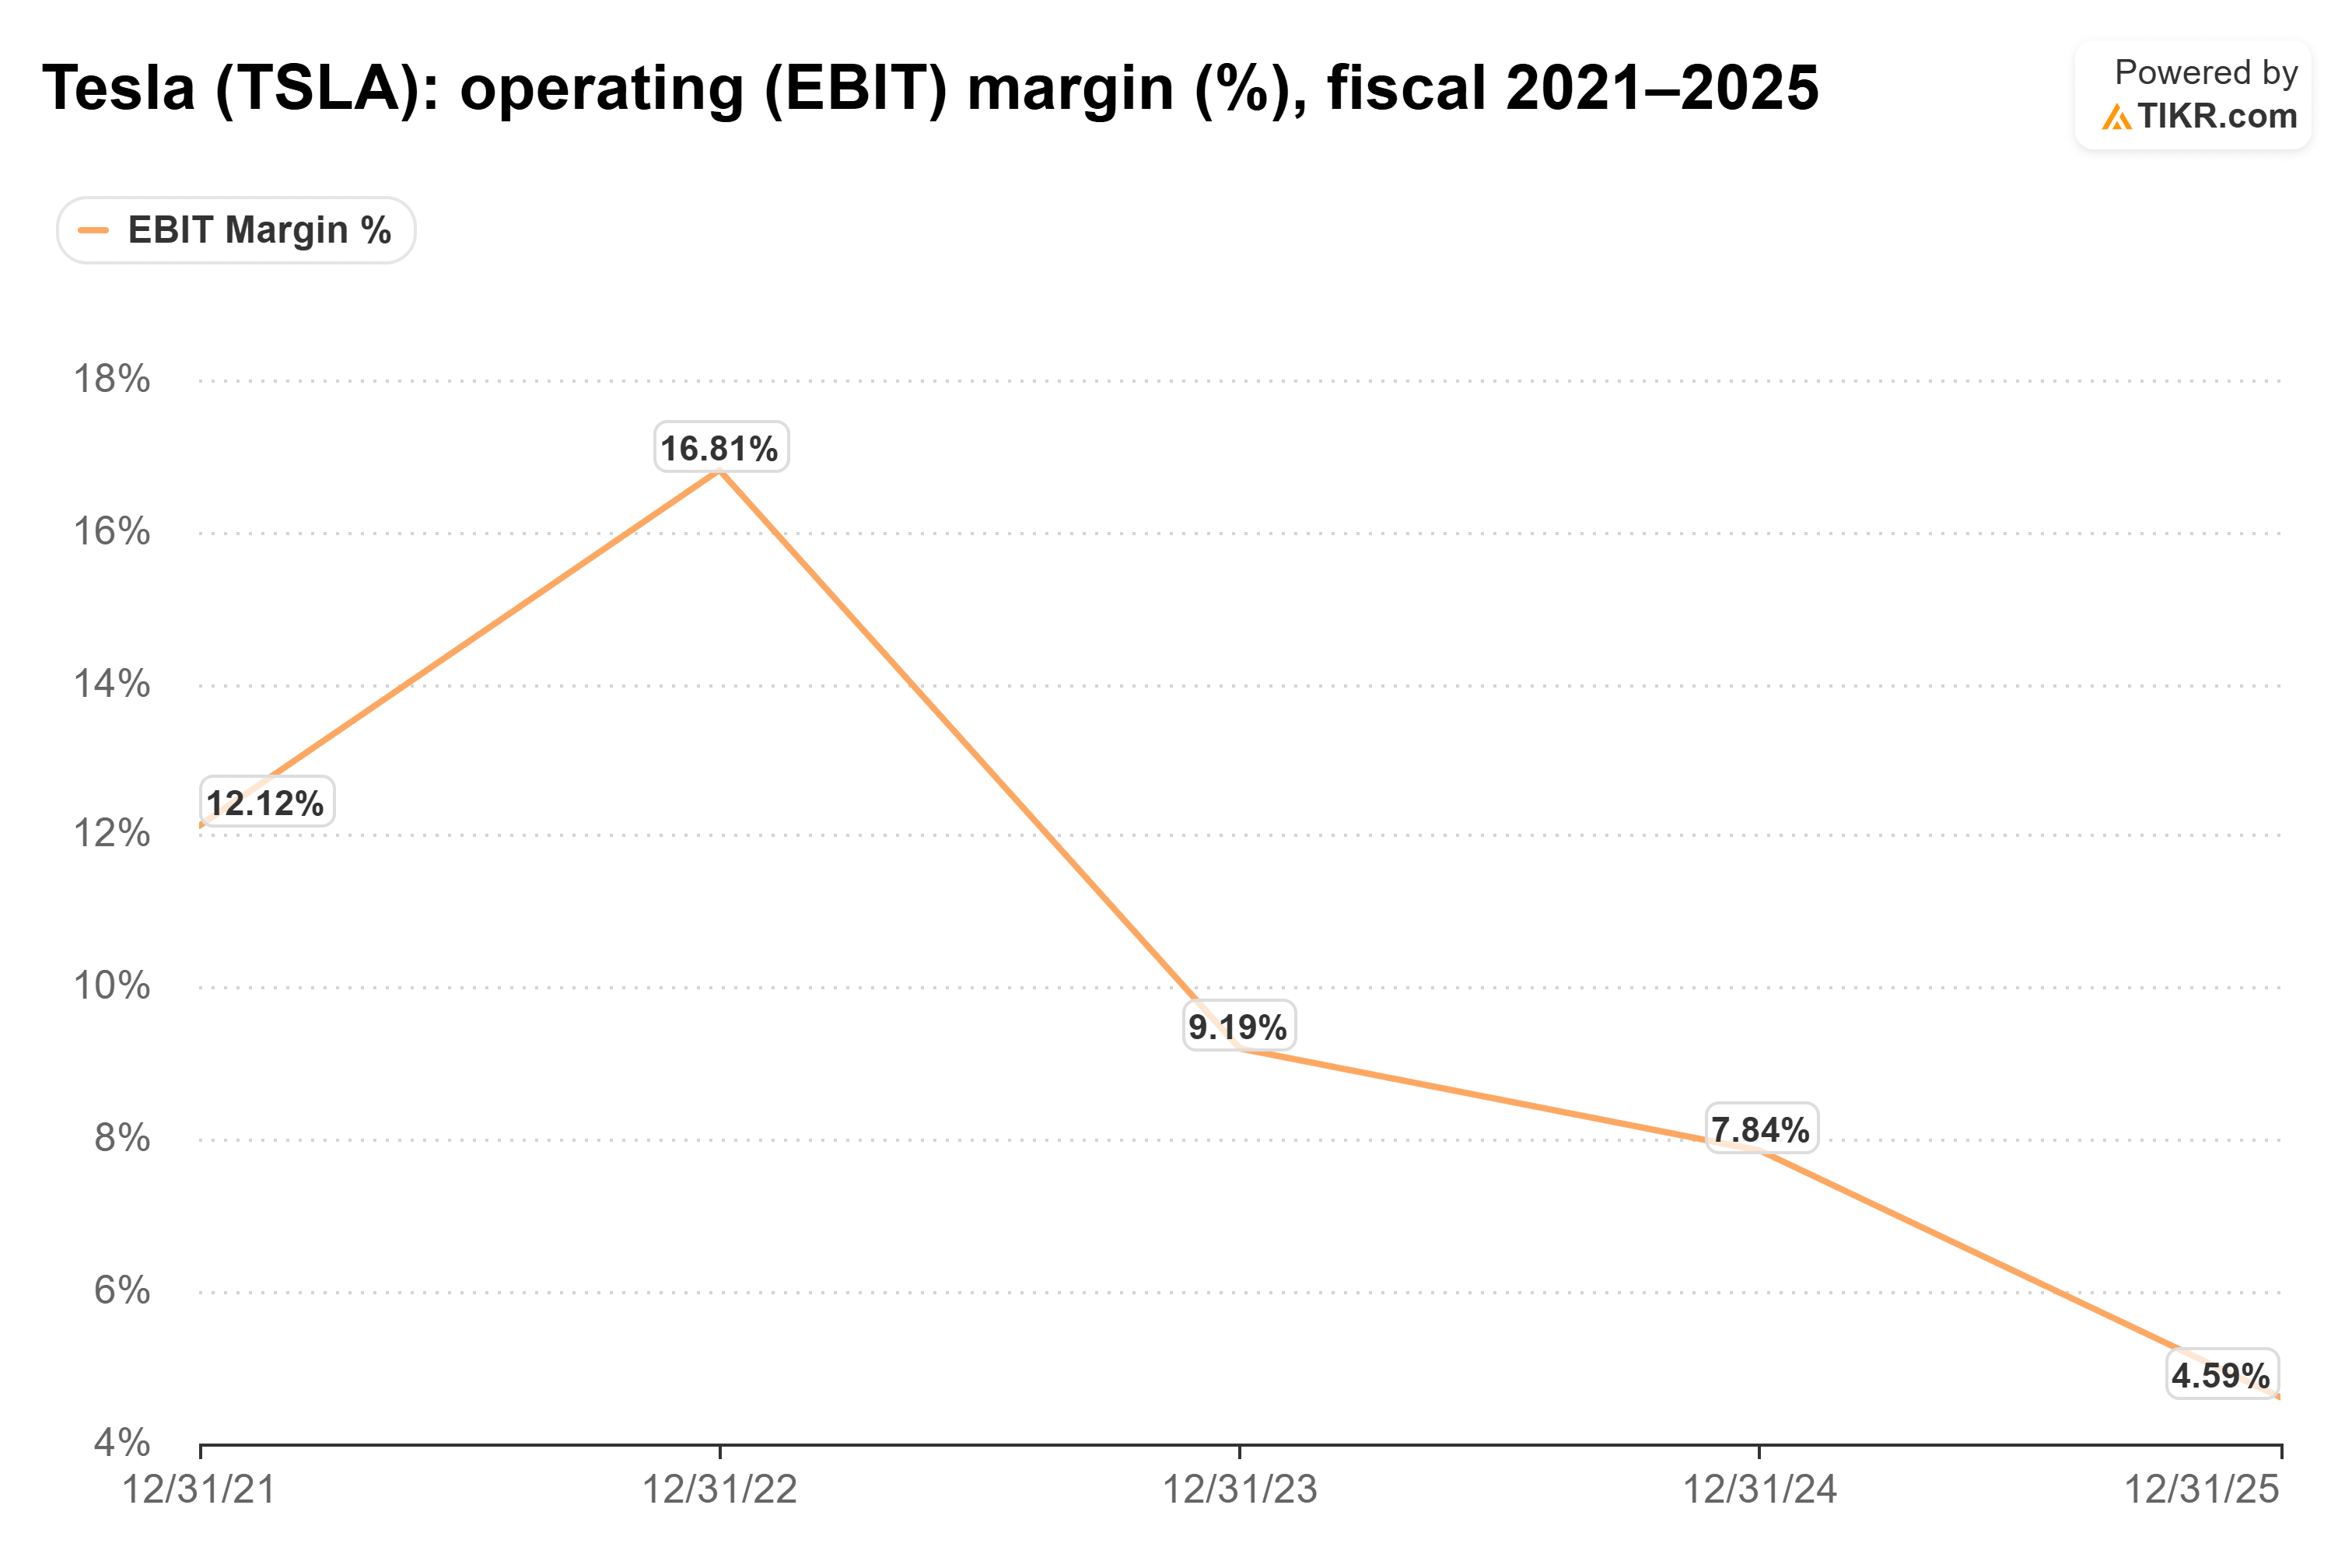
So for the multiple to make sense, something else has to carry the earnings. For the bulls, that something is Optimus.
Let’s check Mostaque’s math
Divide $400 billion by 10 million robots to get $40,000 per robot, the price his math assumes.
The 10 million figure rests on Tesla’s own plans. As Jordi Hays noted on TBPN, the new Optimus factory at Giga Texas will have a “targeted capacity of 10,000,000 Optimus per year,” with initial production planned to begin in 2027.
For scale, $400 billion is roughly four times Tesla’s entire revenue today, and analysts aren’t modeling anything close to it…

Consensus calls for $142 billion in fiscal 2028, about 50% above fiscal 2025’s $94.8 billion.
Now test the two-year call. If Tesla sells more robots than its 1.6 million cars by 2028, at $40,000 each, that’s $64 billion of robot revenue. Wall Street’s 2028 estimate adds just $47 billion to fiscal 2025’s revenue, robots and cars together.
So either analysts are deeply skeptical of Optimus’s ramp, or Mostaque’s clock is running fast. I’d bet on the second.
Here’s the catch: memory
Optimus has no production revenue yet. Before Tesla can sell millions of robots, it needs millions of the chips that run them.
Musk gave a hint of how hard that will be in a post on X about the memory in Tesla’s next AI chips:
“This was the only way to get enough volume for Optimus production and greatly reduces cost.”
He’s since nudged AI5 back up to 96GB, and he expects the cut to have “a negligible effect on Optimus performance.”
It’s encouraging that Tesla is engineering for scale this early. Still, redesigning a chip around memory volume before the first production robot ships suggests that supply could cap output long before 10 million units.
So will robots outsell cars by 2028?
I don’t think so, even though Mostaque is right that Optimus is the business that has to justify Tesla’s valuation, and a factory built for 10 million robots a year shows Tesla takes it seriously. Going from first production in 2027 to more than 1.6 million robots a year within two years would be one of the fastest ramps in manufacturing history, and memory is already a constraint.
At 202x forward earnings, today’s buyers are paying for much of that ramp before it happens.
Of course, initial production at Giga Texas is planned for 2027, and how many robots that first year actually produces will tell us far more than any forecast.
So what is Tesla stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Tesla could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!