


Key Takeaways
- SpaceX agreed on Oct. 8 to buy Grain Management’s 800 MHz spectrum for a reported $8 billion, and Verizon, AT&T and T-Mobile US each fell more than 10% the next day.
- LightShed Partners analyst Walter Piecyk says Verizon has nothing left to set it apart, and the numbers back him up.
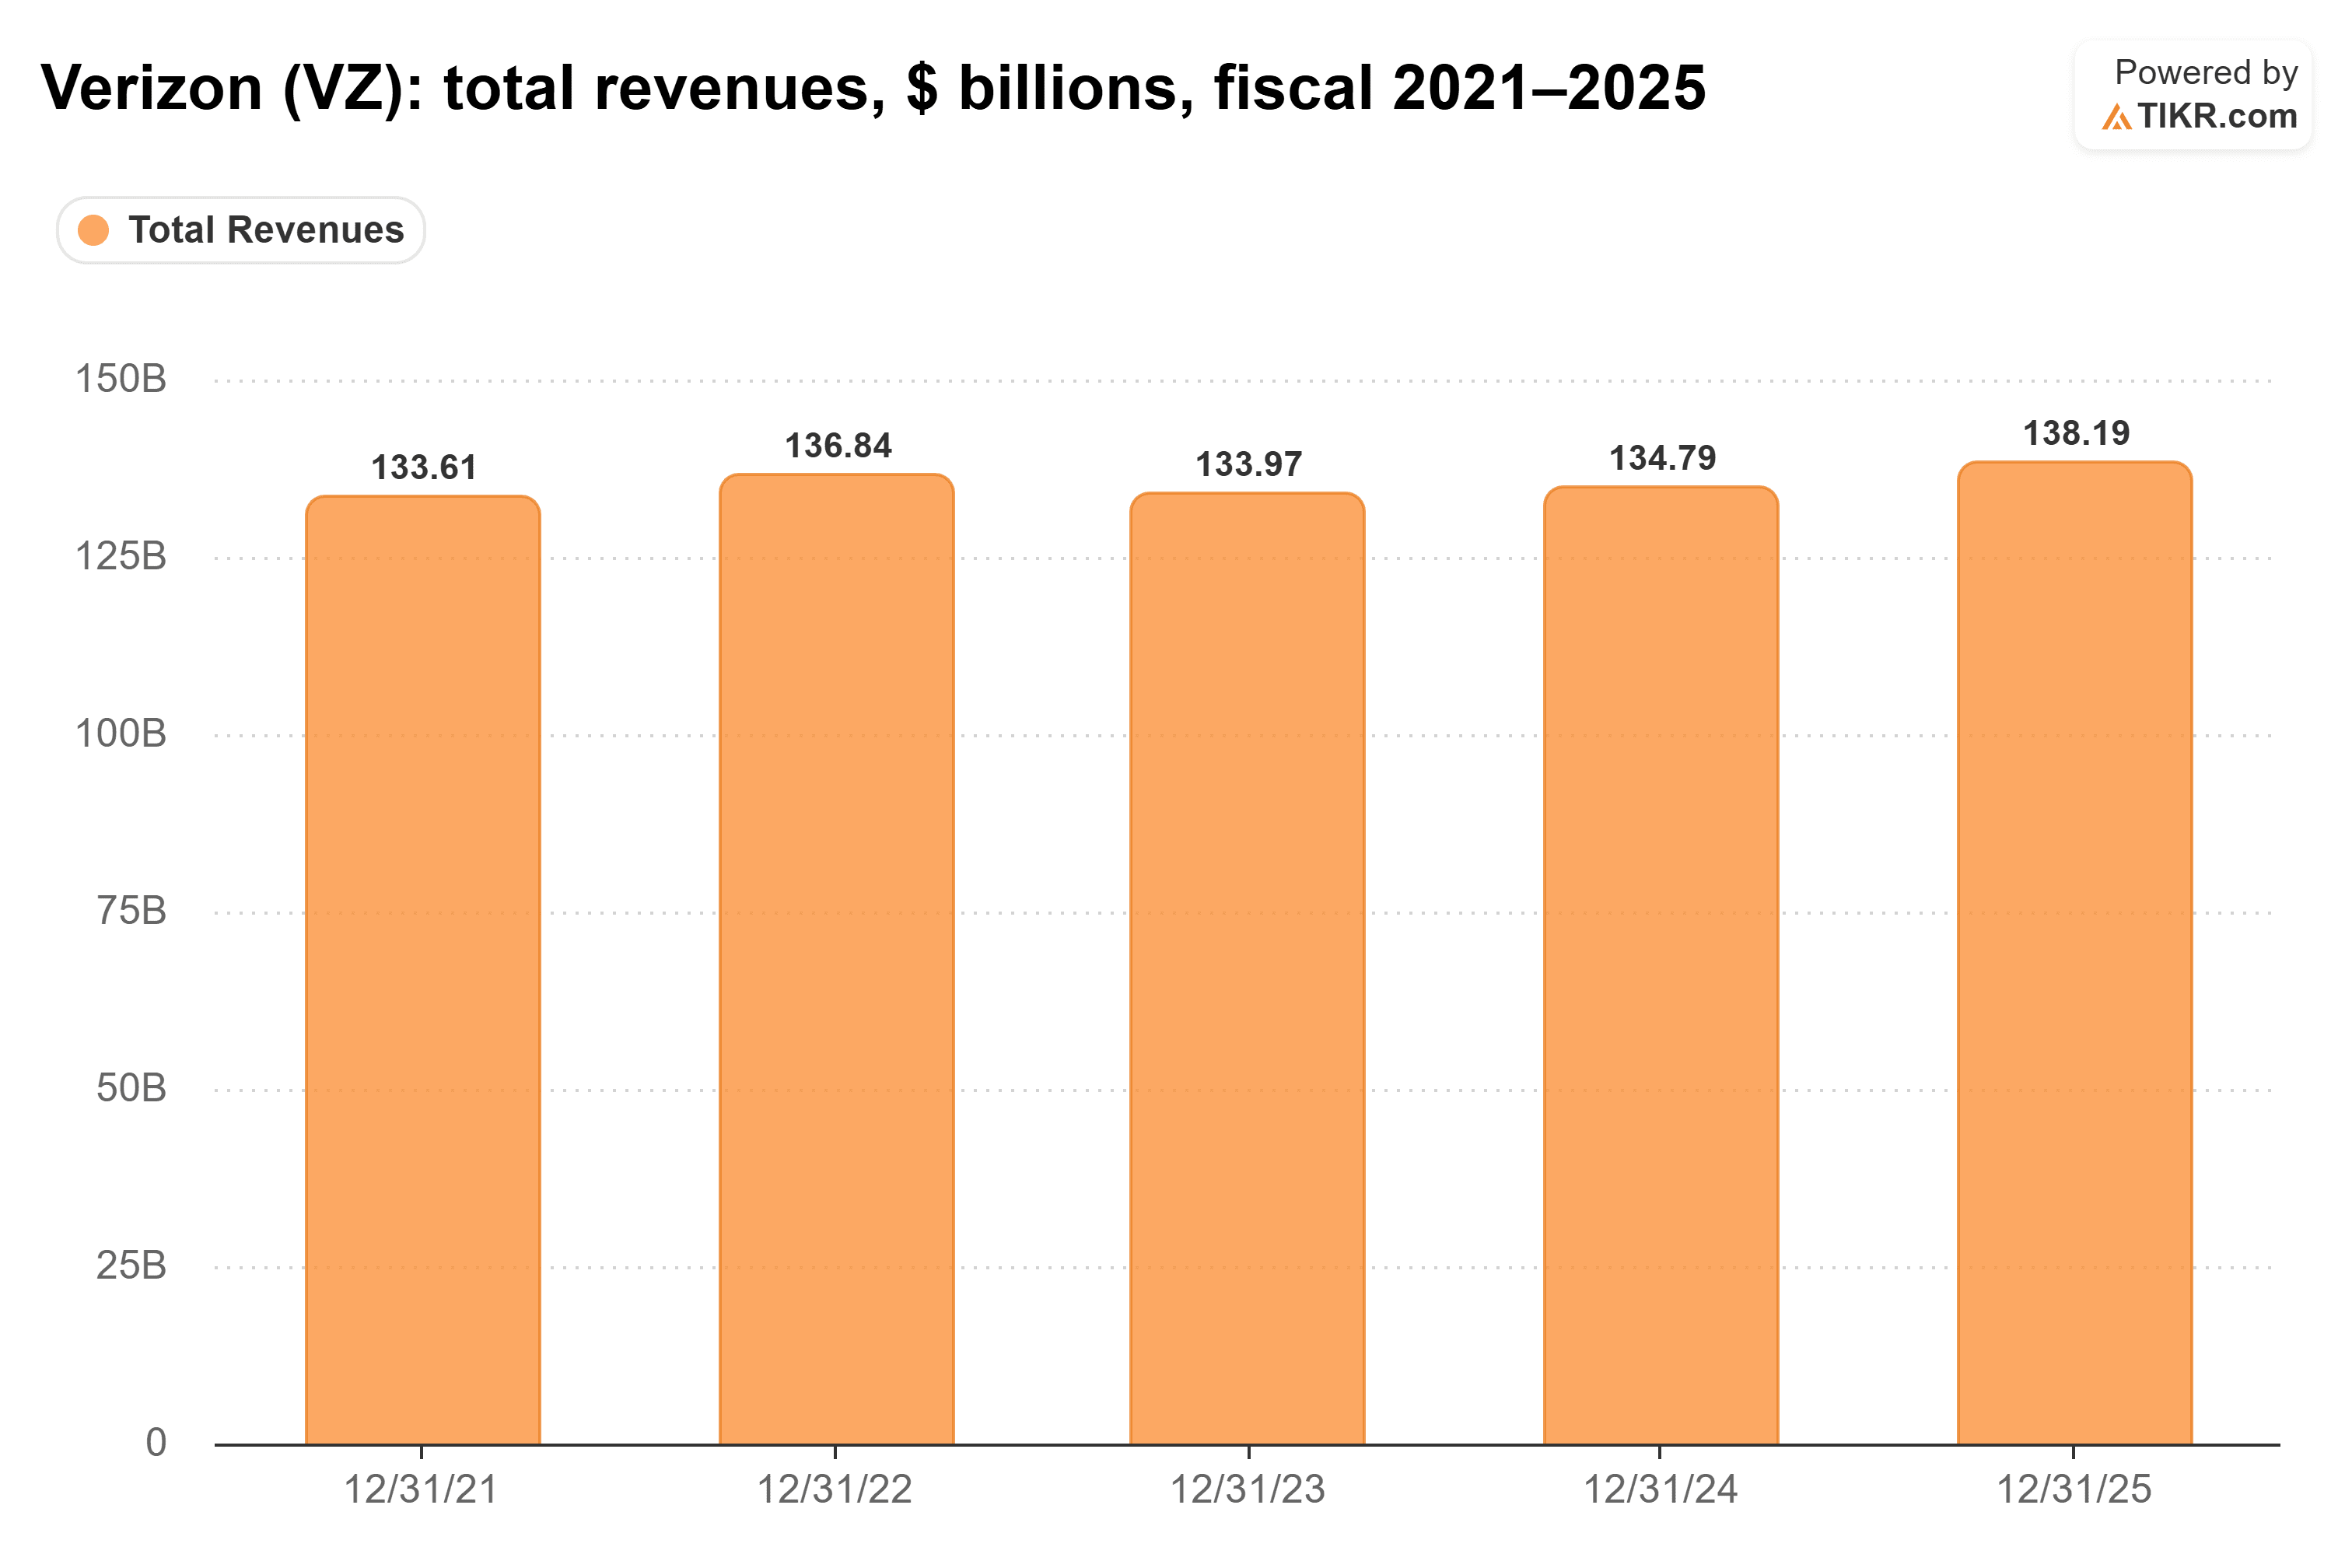
- Verizon’s revenue grew only from $134 billion in fiscal 2021 to $138 billion in fiscal 2025, while its total debt reached $185 billion.
- SpaceX expects upgraded Starlink Mobile service by the end of 2027, and Verizon reports third-quarter results on Oct. 26.
SpaceX (SPCX) is coming for the wireless carriers, and one longtime telecom analyst thinks he knows which one is in the most trouble: Verizon (VZ).
On Oct. 8, SpaceX agreed to buy Grain Management’s nationwide 800 MHz spectrum for Starlink Mobile. The Wall Street Journal valued the deal at around $8 billion. Verizon, AT&T (T), and T-Mobile US (TMUS) each fell more than 10% the next day.
On the latest episode of Decoder, host Nilay Patel asked LightShed Partners analyst Walter Piecyk why Verizon has the most to lose. His answer:
“What is Verizon’s differentiation in the market right now? They have none.”
Ouch.
A 60% margin on a commodity
Piecyk starts with the network, which used to be Verizon’s whole pitch. For years it sold itself as the best network, and he says T-Mobile has taken that title. When Patel asked whether it’s gone for good, Piecyk didn’t hedge: “I think that’s completely gone.”
That leaves an industry earning big margins on what he sees as the same product everywhere:
“The networks are effectively commoditized. These networks are basically the same, right? And they’re getting 60% margins.”
Verizon’s own EBITDA margin sits below Piecyk’s 60%, but look at how little it moves: between 35% and 36% every year from fiscal 2022 to fiscal 2025. A margin that steady, on a product Piecyk calls a commodity, is exactly what draws a new entrant in…

Layoffs under Verizon’s new CEO can prop that margin up for now, and Piecyk gives them that much. The cuts “may appease investors to make the EBITDA look good for the next couple of quarters, but at some point you have to show and have a strategy for some type of revenue growth.”
Where’s the growth?
That’s the bigger problem. Piecyk laid out how SpaceX bulls could build their case from here: Starlink Mobile wins its first 5 million or 10 million customers, and then “Verizon is going to be so desperate for any type of revenue because their revenue declined. They’re just going to hand them a wholesale deal and then they’ll start selling spectrum.”
He has a point about the revenue. Verizon went from $134 billion in fiscal 2021 to $138 billion in fiscal 2025, about 3% growth over four years, or less than 1% a year…
Verizon also has little room to buy its way out. Its total debt reached $185 billion at the end of fiscal 2025, up from $172 billion a year earlier and the highest in five years…

Piecyk says the carriers are “already pretty levered.” Even so, he thinks passing on Grain’s airwaves was a mistake: “maybe Verizon or AT&T should have bought this 800 spectrum for whatever it was, let’s call it $8 billion. They’re probably losing more in enterprise value over the concerns of what’s happening with SpaceX than it would have cost them just to buy it.”
That’s the line I keep coming back to. Verizon’s drop of more than 10% on Oct. 9 erased well over $8 billion of market value on its own, more than Grain’s spectrum reportedly cost.
Starlink Mobile’s upgrade is targeted for late 2027
To be fair, SpaceX won’t be taking Verizon’s customers tomorrow. Piecyk describes a typical telco build as another $10 billion to $15 billion of capex on top of the spectrum, and he said “you’re not taking 50% share overnight.” The Grain purchase still needs FCC approval. On SpaceX’s August earnings call, President Gwynne Shotwell said the company expected to begin providing upgraded Starlink Mobile service using next-generation satellites and EchoStar spectrum by the end of 2027.
So Verizon’s margins can probably hold for a while yet. The stock, though, has already been marked down for a threat that’s years away. And with revenue this flat, Verizon has every reason to cut a wholesale deal with SpaceX long before Starlink Mobile reaches scale.
Verizon is the carrier in the crosshairs
I think Piecyk is right about Verizon. AT&T shows the difference: he credits it with building a fiber network to bundle with wireless, which brings in “very high value, very low churn customers.” Verizon has flat revenue, its heaviest debt in five years, and margins SpaceX would love to take a bite out of.
Verizon is moving the same way. It closed the Frontier acquisition on Jan. 20, 2026, taking its combined footprint to about 30 million fiber passings, and Piecyk thinks more fiber is the right call. The test comes on Oct. 26, when Verizon reports third-quarter results. Revenue is the number I’ll be watching, since it’s the one thing Piecyk says the layoffs can’t fix.
So what is Verizon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Verizon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


