Key Takeaways
- Super Micro fell 11.3% on Nov. 12 after Bloomberg reported a Justice Department probe into whether its servers were smuggled into China.
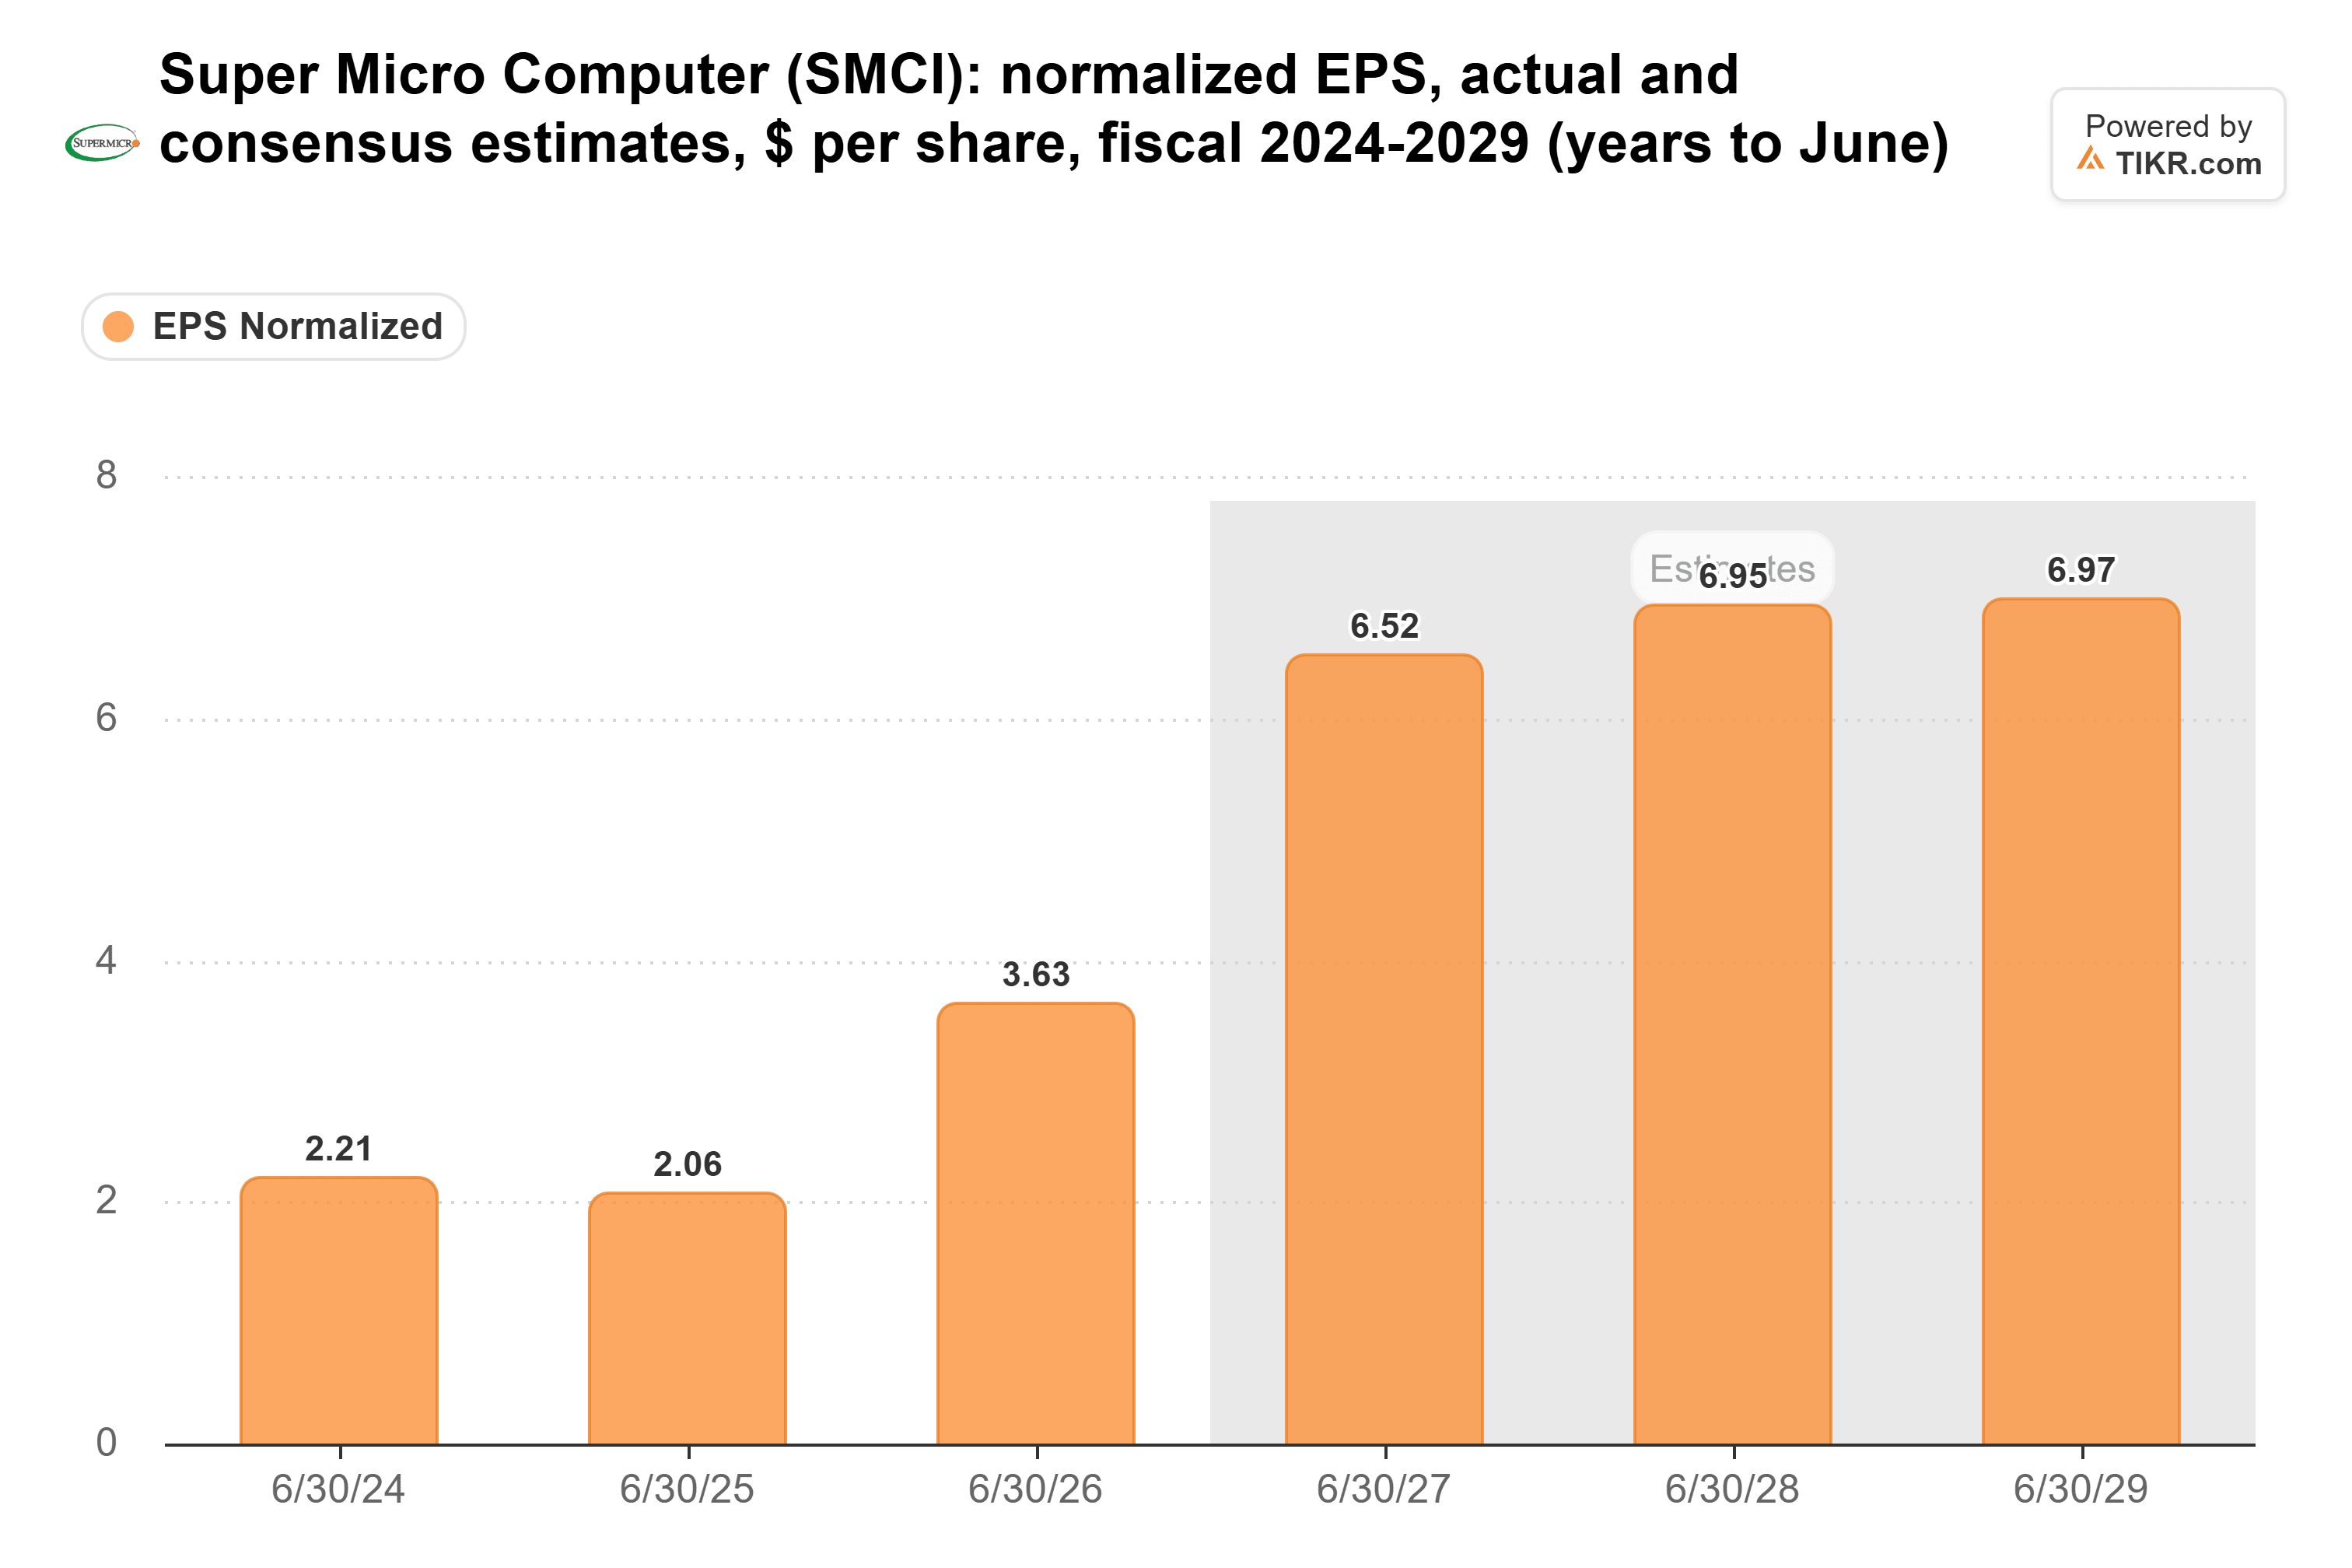
- The stock trades at 4.3x forward earnings, its lowest in five years, even though analysts expect normalized EPS to jump from $3.63 in fiscal 2026 to $6.52 in fiscal 2027.
- Book value is a weak floor: $4.2 billion of Super Micro’s roughly $16 billion of equity is preferred stock, inventory alone nearly matches the total, and free cash flow was negative $476 million in the September quarter.
- The stock looks too cheap for the earnings analysts expect, and the December-quarter report, expected in early February, is the first test of whether that profit turns into cash.
Shares of Super Micro Computer (SMCI) fell 11.3% on Nov. 12, closing at $26.99, after Bloomberg reported that federal prosecutors are looking into whether its servers were smuggled into China. They edged down again on Nov. 13, to $26.87, as Nvidia and other tech stocks slipped.
That leaves the stock so cheap that one investor on the r/ValueInvesting subreddit thinks the market has lost the plot. The poster’s case is that Super Micro had $16 billion of book equity at the end of last quarter, with no goodwill padding it, and should earn $7 billion over the next year. Yet it trades at a $19 billion market value.
“Seems the market is pricing it goes bankrupt next quarter,” the poster wrote.
The earnings math backs that up, at least.
TIKR tracks 18 analysts on Super Micro Computer. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Super Micro Computer, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Super Micro Computer’s Analyst Ratings
On earnings, it’s a bargain
The poster’s estimate starts from $80 billion of revenue at a 12% gross margin. That sits inside the $72 billion to $82 billion of fiscal 2027 revenue Super Micro now guides to. It’s also close to the 12.7% gross margin the company reported for the September quarter.
Analysts come in lower on the bottom line. Even so, they expect normalized EPS to rise about 80%, from $3.63 in fiscal 2026 to $6.52 in fiscal 2027, the year to June:
Even on those numbers, the stock trades at 4.3x forward earnings. That’s its lowest in five years and far below its 14.6x average over that stretch:
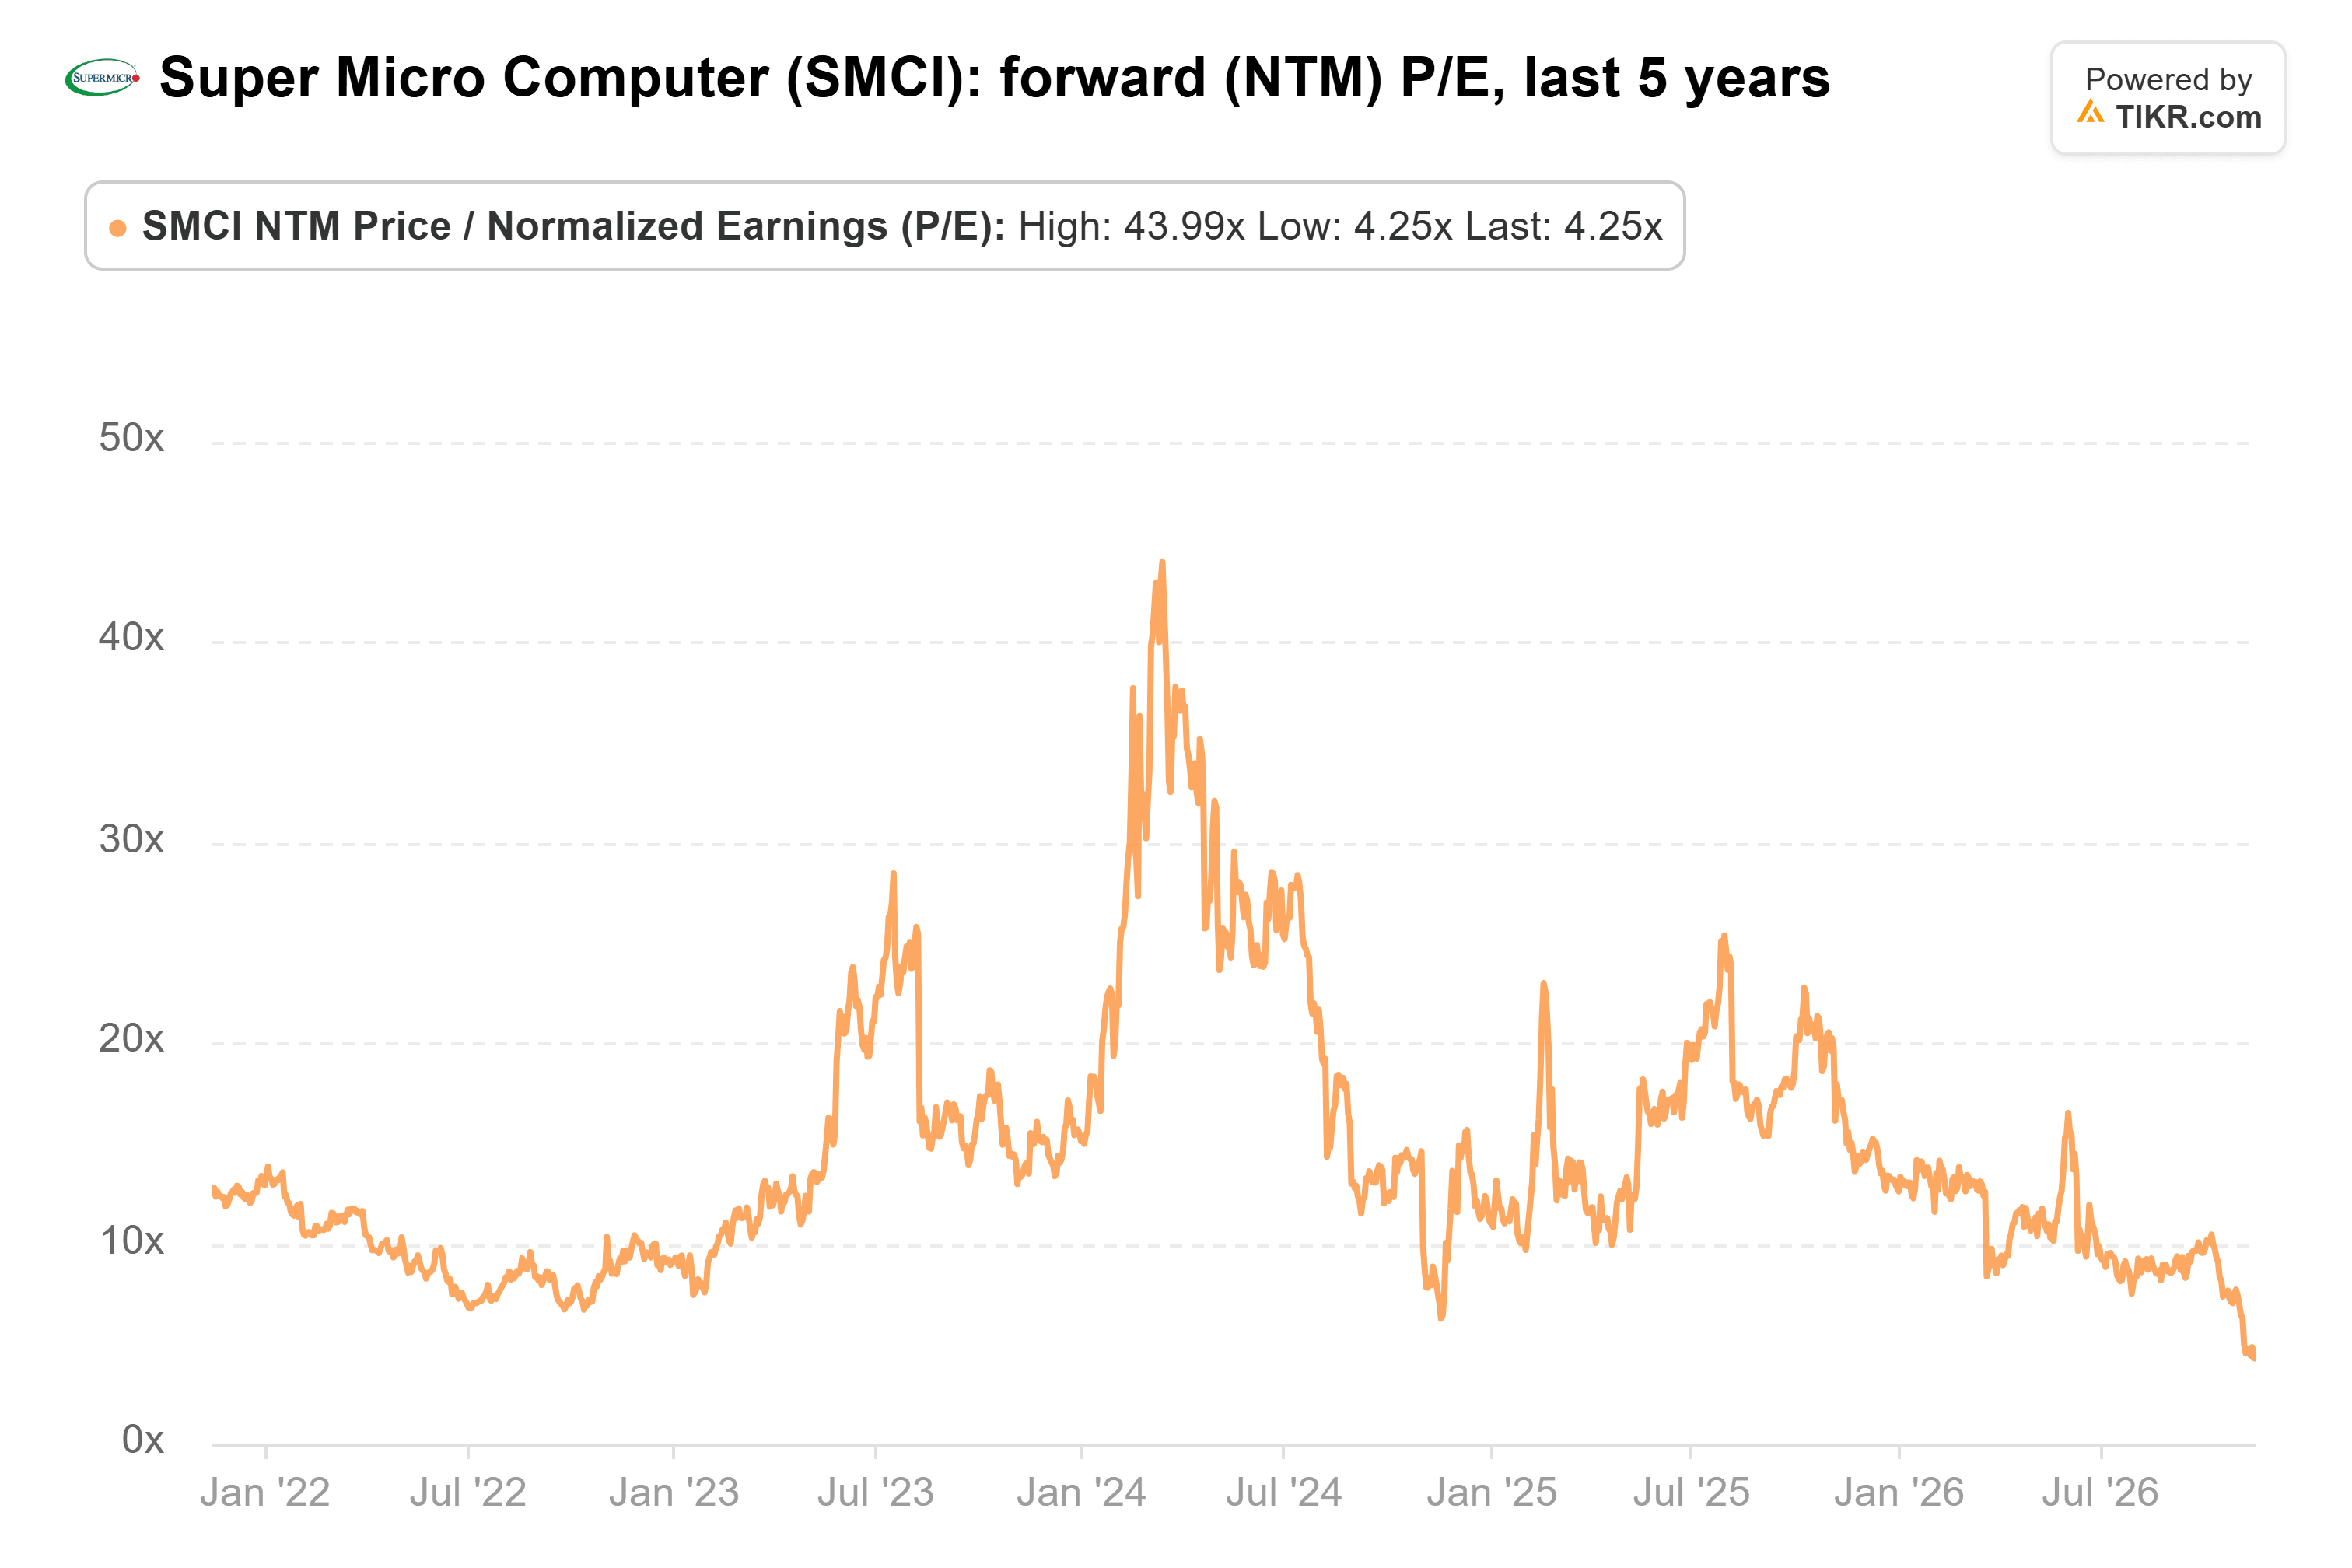
Investors paying 4.3x for rising estimates either doubt the profits will last, or doubt they’ll ever show up as cash.
Book value is a shaky floor
The $16 billion holds up. Super Micro had $16.1 billion of stockholders’ equity at Sept. 30, after it earned $1.6 billion in the September quarter. But $4.2 billion of that is the mandatory convertible preferred stock it sold in June, which turns into common shares by June 2029.
That puts common shareholders’ own book closer to $12 billion. Even at the poster’s $19 billion, the stock trades at about 1.6 times that: cheap, but not at book.
The assets behind it are also far from cash. Inventory alone was $15.1 billion at Sept. 30, up from $12.9 billion at June 30 and nearly equal to all of the company’s equity. As another investor replying to the post put it, “Book value is only a floor if the assets turn into cash near their carrying value.”
Others in the replies put Super Micro’s cash cycle at about three months, and the company’s latest figure backs that up: 97 days in the September quarter, down from 149 days in June. Customer prepayments drove most of that improvement. Even so, free cash flow was negative in five of the last eight quarters, including a $6.7 billion outflow in the March quarter and negative $476 million in the September quarter:
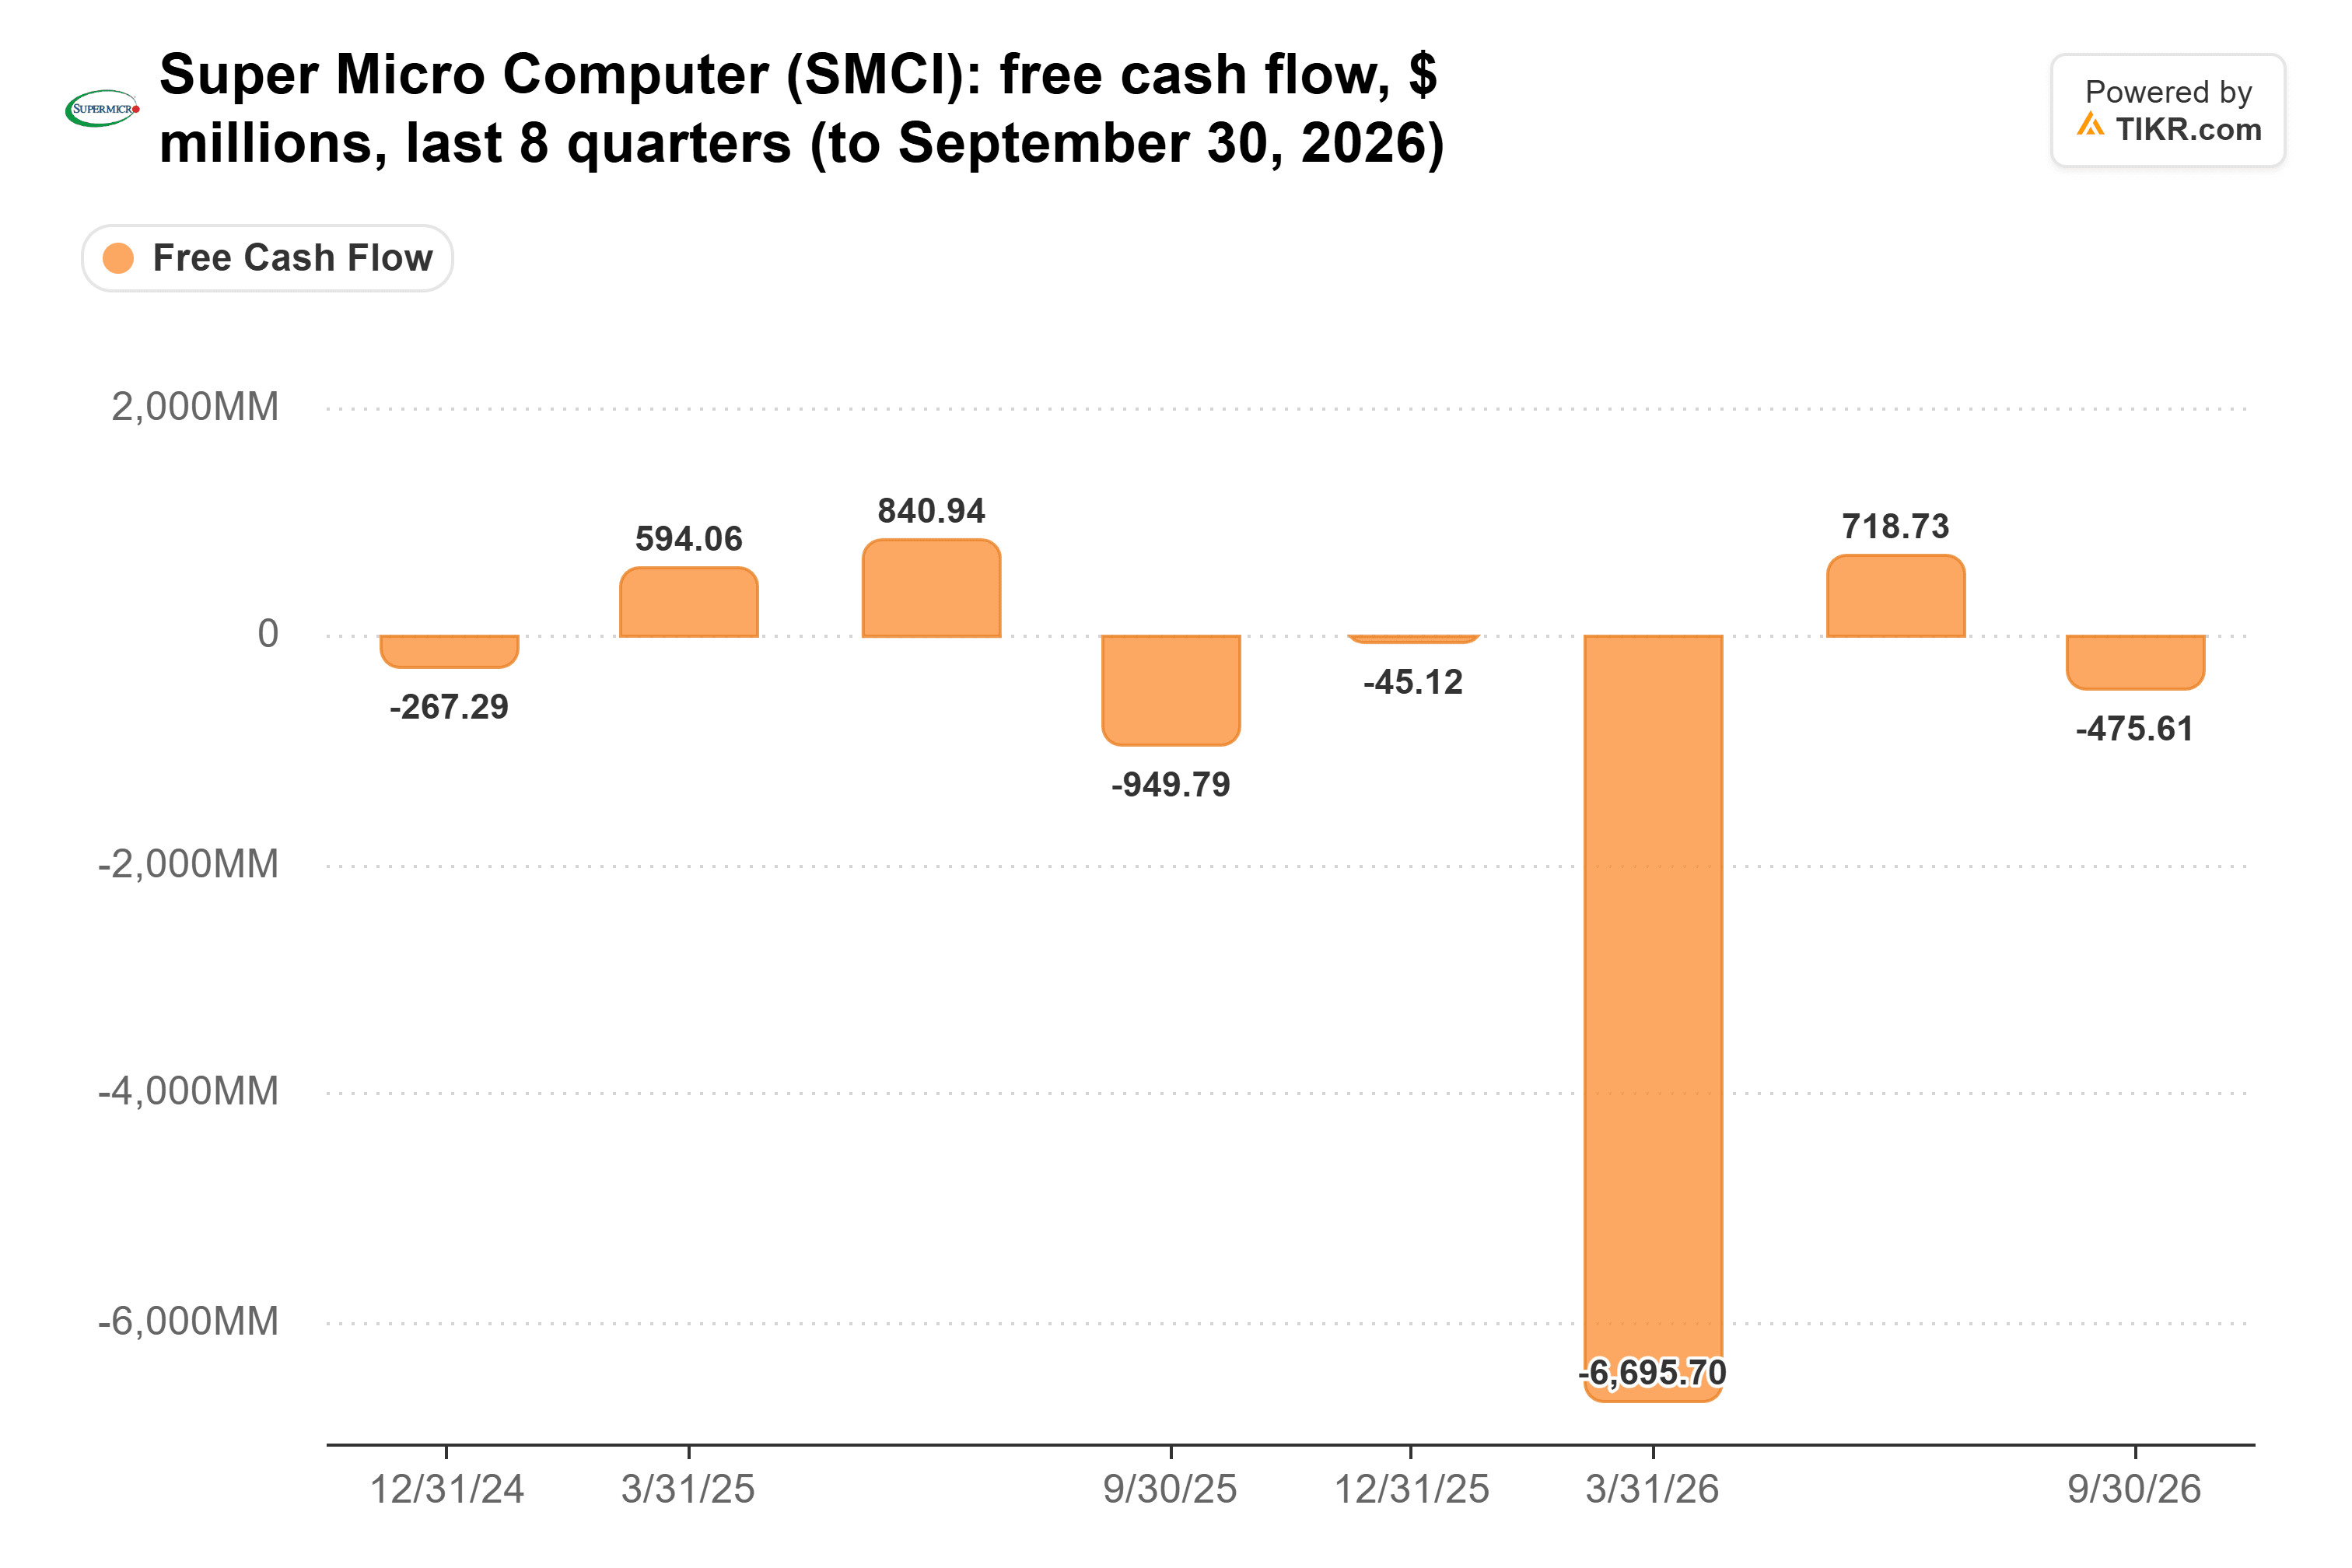
Part of September’s outflow came from paying suppliers early, which management said used roughly $3 billion. Super Micro filled earlier gaps with outside money, raising $5.6 billion of new common and preferred stock in June.
Prosecutors add a second discount
Then there’s the probe that knocked the stock down. The US Attorney’s Office in Manhattan is reportedly examining whether entities tied to Alice Huang, a former top executive at Singapore-based Megaspeed International, helped smuggle Super Micro servers into China. Super Micro said it “has been responsive to inquiries and has fully cooperated” with US and Taiwanese officials, and that Megaspeed “is not, and has never been, a Supermicro customer.”
Singapore authorities, who are investigating Megaspeed separately, have said Super Micro’s cooperation there was limited. The company itself hasn’t been charged, and probes like this can end without any charges.
This is also the second export case hanging over the stock. Co-founder Wally Liaw goes on trial in March 2027 over alleged server diversion to China, though a board investigation found no evidence that current senior management knew about it. If prosecutors charge Super Micro itself, today’s discount could look small.
Cheap enough to take the risk
The poster has a point: Super Micro is cheap. At 4.3x forward earnings, investors are pricing in far more trouble than the probe has shown so far, while analysts keep raising their estimates. But the real floor under this stock is the cash Super Micro collects, and it hasn’t proved it can collect it yet.
Analysts expect $4.0 billion of free cash flow in fiscal 2027. After the September quarter’s outflow, the next three quarters would need to bring in about $4.5 billion between them. The December-quarter report, expected in early February, is the first real test, though a move by prosecutors before then could matter more than any quarter.
So what is Super Micro stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Super Micro could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!