Key Takeaways
- Claiming Social Security at 62 instead of 67 cuts the check 30% for life for anyone born in 1960 or later.
- A couple due $2,600 and $3,300 a month at 67 would give up $1,770 a month, or $21,240 a year, by claiming at 62.
- Waiting until 67 means going without $4,130 a month in early checks for five years each, and replacing those checks takes $247,800 set aside.
- Waiting pays off for anyone who lives past about 79, and if only the bigger check waits, the amount needed drops to $138,600.
If you’re retiring before 62, you’ll spend a few years with no Social Security at all. And when 62 finally arrives, the check on offer is a lot smaller than the one you’d get by holding out until 67.
A caller described exactly that problem this week on Jill on Money with Jill Schlesinger. Her husband works for a school district, and she said: “He’s planning to retire at age 59. And his pension would be $2,900 a month at that point.” She plans to leave full-time work the same year, at 60. At 67, Social Security would pay him $2,600 a month and her $3,300, or $5,900 together.
His pension plus a $900-a-month annuity of hers that starts at 60 gives them $3,800 a month. They spend around $8,000 a month now, not counting home projects. So she asked Schlesinger, “can we stash enough money to fund that gap?” Schlesinger’s reply: “we need a couple hundred grand in there and you’re going to have to be willing to spend it, by the way.”
Claiming at 62 costs 30%, for good
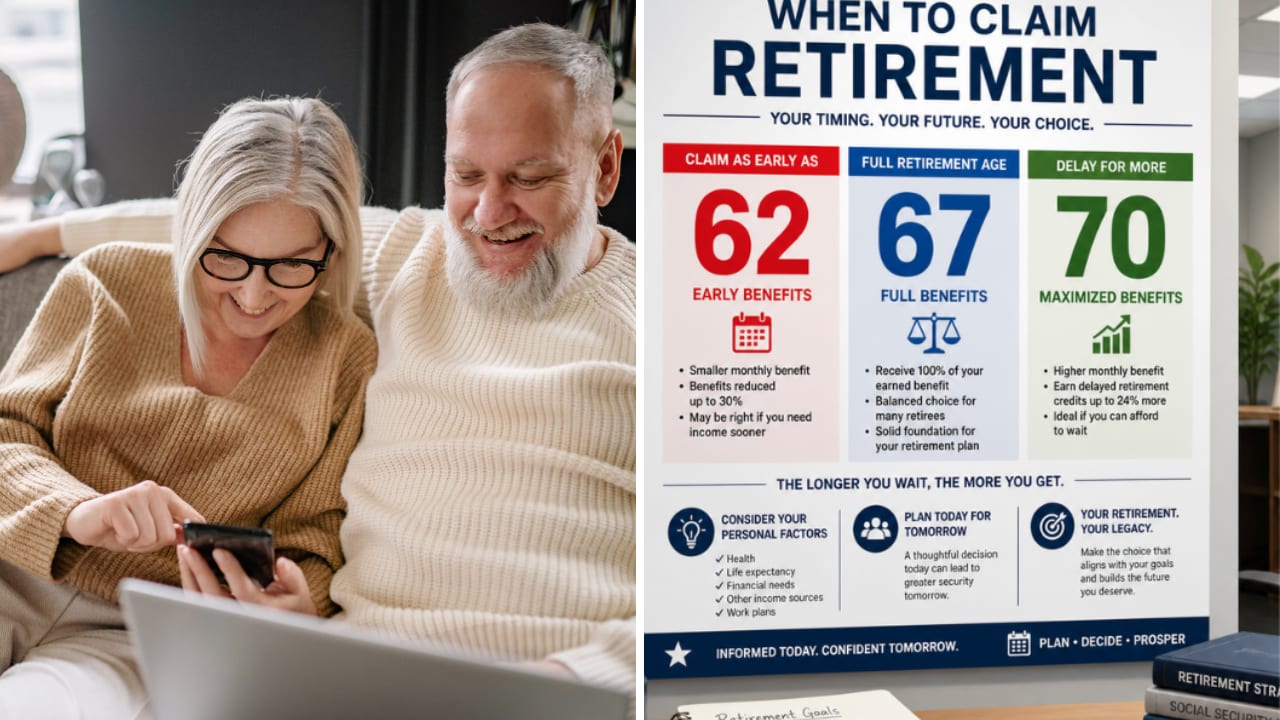
For anyone born in 1960 or later, full retirement age is 67, though you can start Social Security as early as 62. But claiming at 62 cuts the benefit 30% for life. In SSA’s own example, a $1,000 benefit becomes $700. This couple is in their early 50s, so the rule applies to both of them.
His school-district pension won’t shrink his own Social Security check. The Social Security Fairness Act, signed Jan. 5, 2025, ended the Windfall Elimination Provision, which used to cut benefits for people with pensions from jobs Social Security didn’t cover.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
What waiting until 67 costs them
Claimed at 62, his $2,600 would become $1,820 and her $3,300 would become $2,310. Together that’s $4,130 a month, which is $1,770 less than the $5,900 they’d get at 67. Over a year, they’d collect $21,240 less, for life.
Waiting means going without that $4,130 a month for five years each, from 62 to 67. Sixty months of $4,130 comes to $247,800: $109,200 to replace his early checks and $138,600 for hers. That’s what they’d need set aside to live as well from 62 to 67 as if they’d claimed early, and still collect the full $5,900 after that.
In return, they collect $21,240 a year more from 67 on. At that pace, it takes nearly 12 years to make up the $247,800. So each of them comes out ahead by waiting if they live past about 79.
Their own gap is smaller
The $247,800 replaces every dollar of the early checks, but this couple has other money coming in. Schlesinger added $2,000 a month from part-time work, which the caller said they could easily earn. With the $3,800 from the pension and annuity, that makes $5,800 a month. Say they keep spending $8,000 a month. That leaves a $2,200 monthly gap, or about $185,000 over the seven years from her retirement at 60 to her 67th birthday.
That’s close to Schlesinger’s couple hundred grand, and it also covers the years before either of them can claim at all. From 67 on, the squeeze is over: Social Security and his pension alone pay $8,800 a month before taxes.
Letting only the bigger check wait
A couple doesn’t have to claim at the same age. If he claimed at 62 and she waited until 67, they’d only need to replace her early checks, which comes to $138,600. The cost is $780 a month off his check for life, or $9,360 a year. If he keeps working part time after claiming, Social Security’s earnings test can also hold back some of his checks once his pay passes a yearly limit.
Her check is the one worth protecting. When one of them dies, the survivor is paid no more than the bigger of their two benefits, and the bigger one is hers. If she shrinks it by claiming early, the survivor ends up with less, whichever of them that turns out to be.
I’d wait, and they may already have the money
If I were in their shoes, I’d let her check wait until 67 at the very least. Breaking even just before 79 is a bet I’d take, and her bigger check is the one that protects whoever is left.
They may also have more money to bridge the gap than it sounds. She has $325,000 in a traditional 401(k), and since she’ll be 60 when she retires, she’s past 59½, the age the 10% early-withdrawal tax stops applying. (Income tax still applies.)
Before they settle on a number, though, they should check their estimates. SSA’s statements work out the benefit at 67 assuming you keep earning your current pay until you claim. Stopping full-time work at 59 and 60 could bring the $2,600 and $3,300 in lower, and every figure above would drop with them.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!