Key Takeaways
- Chipotle rose 12% this week after third-quarter comparable sales grew 2.1%, ahead of the 1.4% analysts expected, with transactions up 0.8%.
- Restaurant-level margin fell 120 basis points to 23.3% on higher labor and marketing costs, and EPS slipped to $0.27 from $0.29.
- Starbucks ended takeover speculation on October 12 by saying it is “not buying Chipotle,” so this rally rests on the business alone.
- Chipotle guided fourth-quarter comps to about 2% with a 3% to 4% exit rate as Smoked Brisket returns on November 5.
Chipotle finally put out a quarter about customers instead of costs. Mostly.
Chipotle Mexican Grill (CMG) rose 12% this week to close Friday at $32 after its October 28 report. Comparable sales grew 2.1% against the 1.4% analysts expected, and transactions rose for the third straight quarter.
The rally follows a deal fantasy that fizzled. On October 8, the Financial Times reported that Starbucks (SBUX), run by former Chipotle CEO Brian Niccol, had explored a takeover. Chipotle stock jumped more than 7% while Starbucks slipped. Four days later, Starbucks said it was “not buying Chipotle,” and Chipotle fell about 3% that morning.
So this week’s move has to stand on the numbers. Some hold up better than others.
Traffic is back, barely
Third-quarter revenue rose 9.6% to $3.29 billion, driven mostly by 84 new company restaurants.
- Comps of 2.1% came from a 1.3% higher average check and 0.8% more transactions.
- Digital sales rose to 38.8% of food and beverage revenue, from 36.7%.
- Chipotle entered Mexico, Saudi Arabia and South Korea, bringing it to 11 countries.
A year ago, comps grew just 0.3% and transactions fell 0.8%. This quarter also absorbed a July slump tied to U.S. food safety worries, though trends recovered by the end of August.
eMarketer analyst Rachel Wolff said the momentum “reflects the company’s success in winning over younger customers” through promotions and rewards. Rewards members drove a record 33% of sales.
Here’s how quarterly revenue has built over two years…
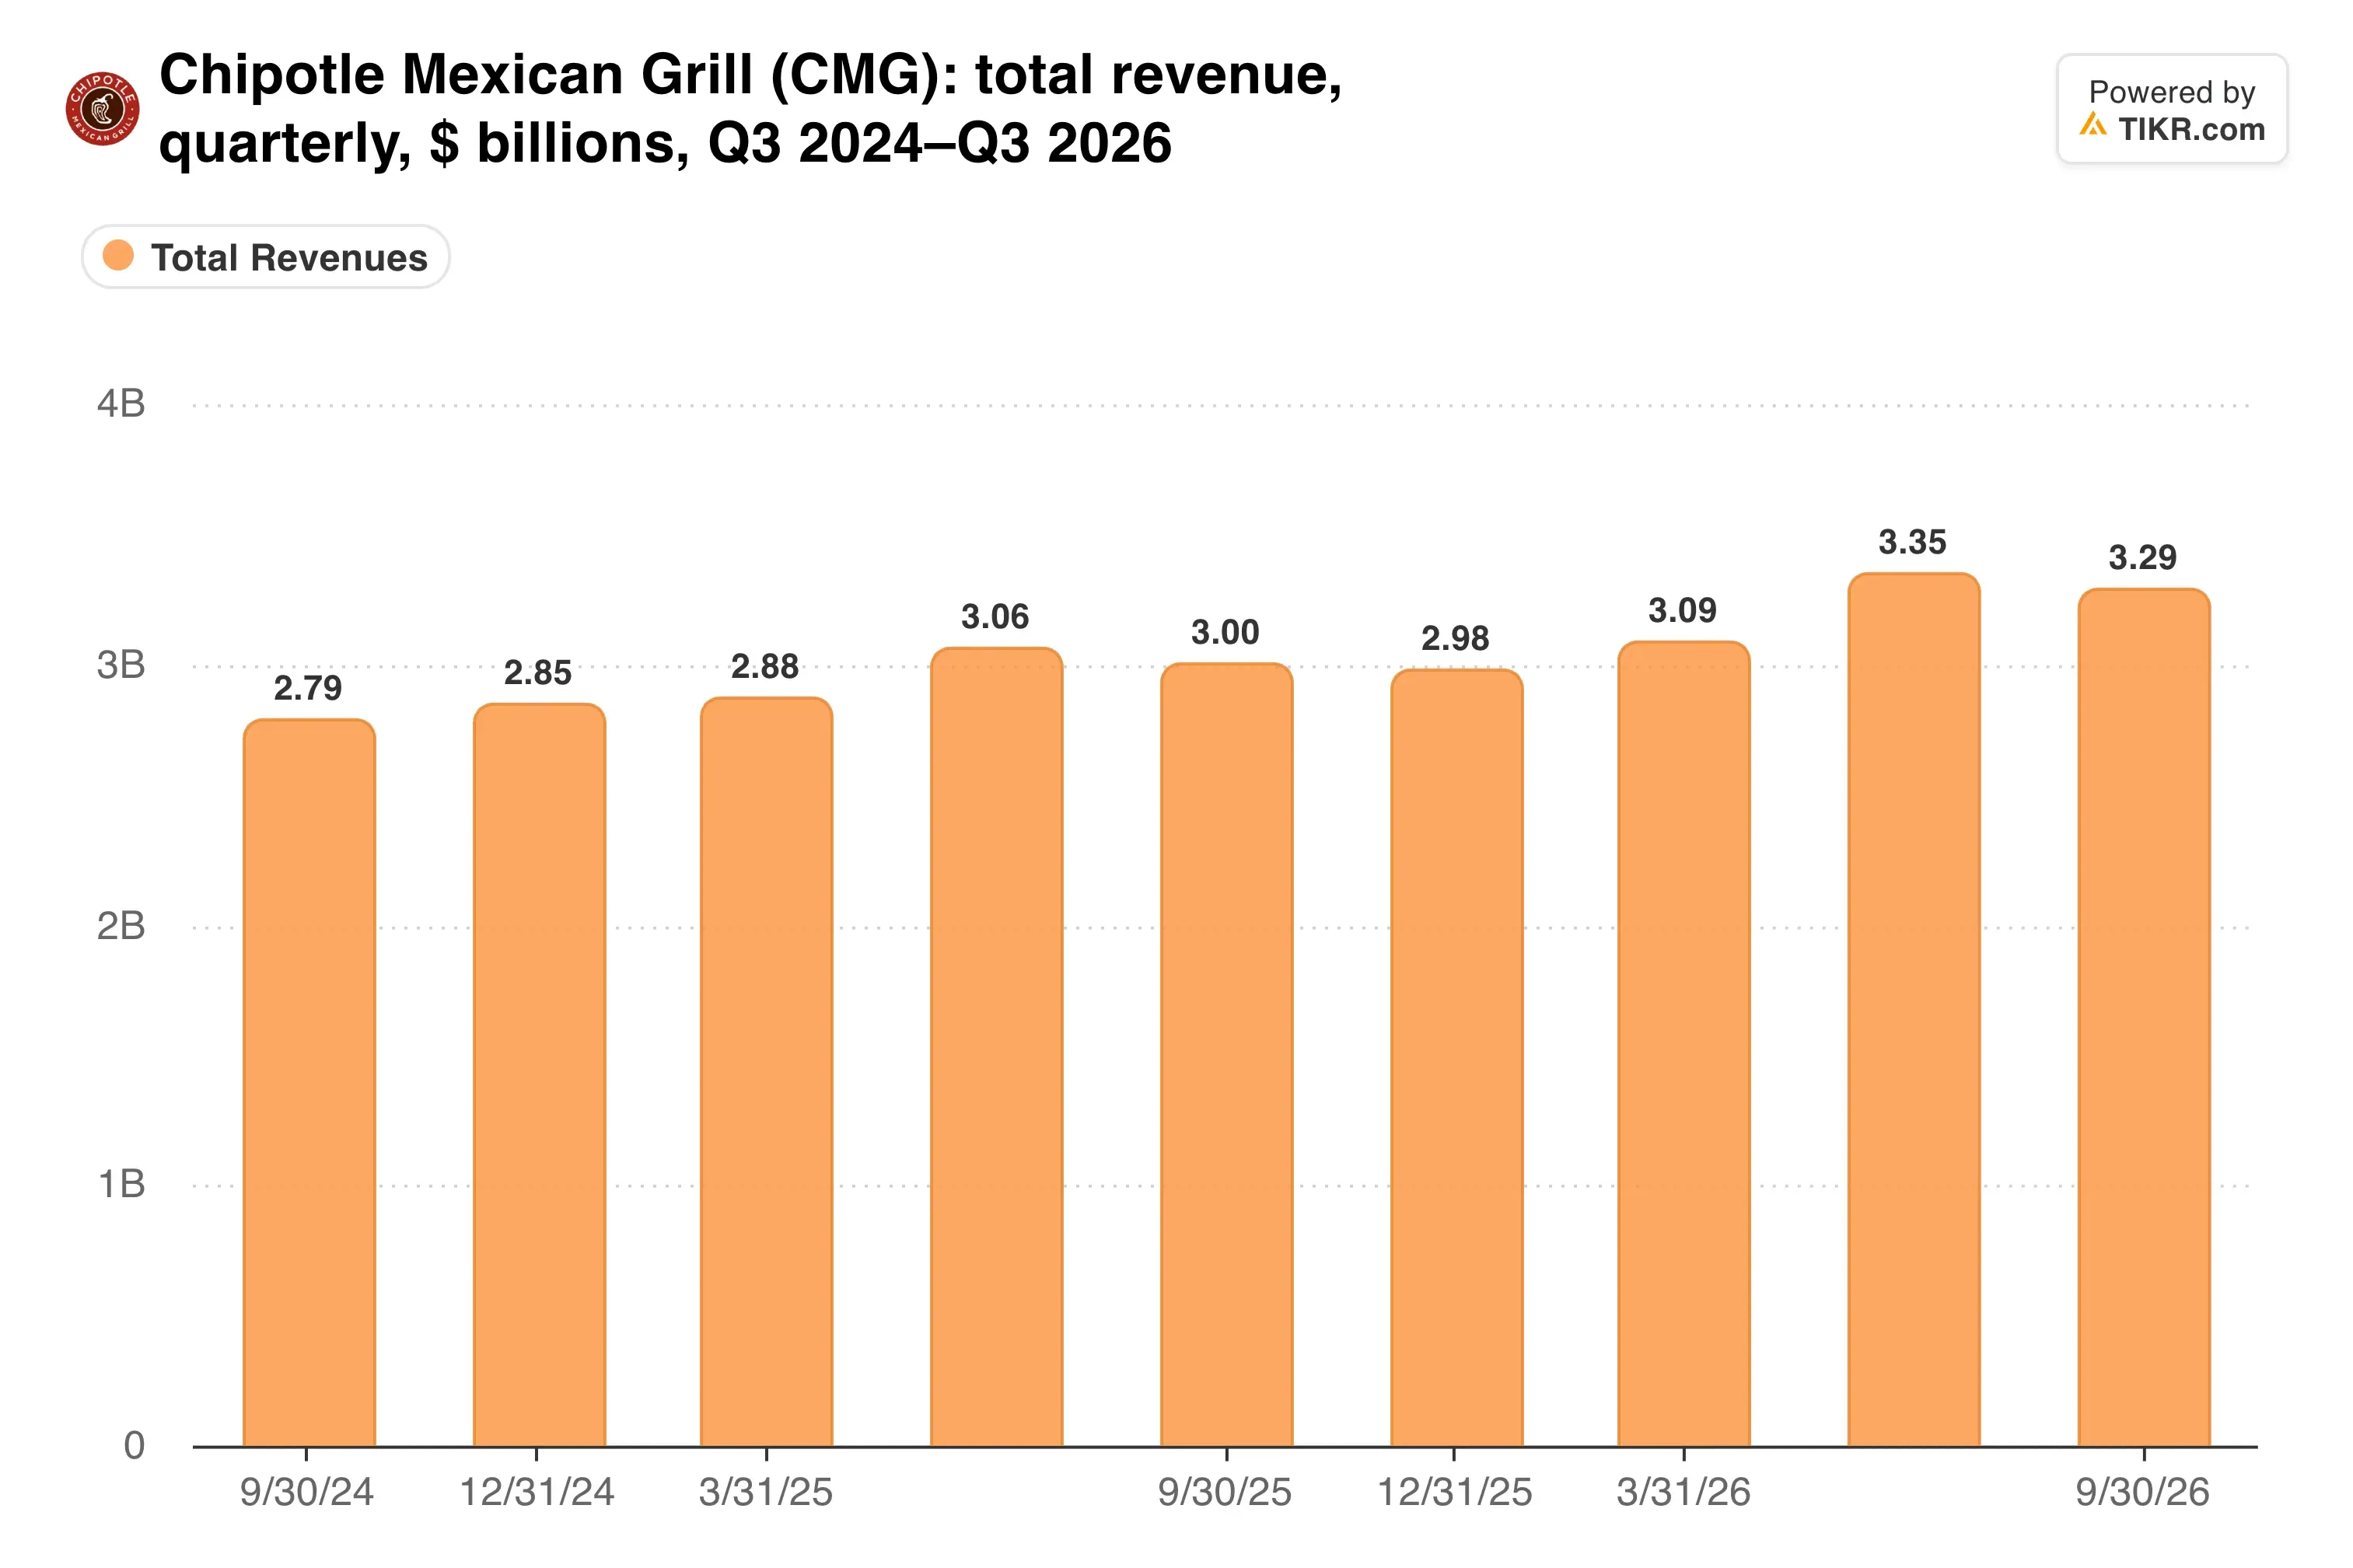
New restaurants are doing most of the work, which is why one point of traffic matters so much.
Paying for the traffic
The cost side moved the wrong way. Labor rose to 25.7% of revenue from 25.2%, and G&A jumped to $185.2 million from $146.7 million. Food, beverage and packaging improved to 29.5% from 30.0%, but that wasn’t enough to offset the rest.
Restaurant-level margin fell 120 basis points to 23.3%. Operating margin slid to 13.7% from 15.9%, and diluted EPS dropped 6.9% to $0.27.
Management is spending on throughput. Its high-efficiency equipment package is in more than 1,700 restaurants, and a cook-to-needs system goes national in early 2027 alongside catering.
Now look at where operating margin has gone.
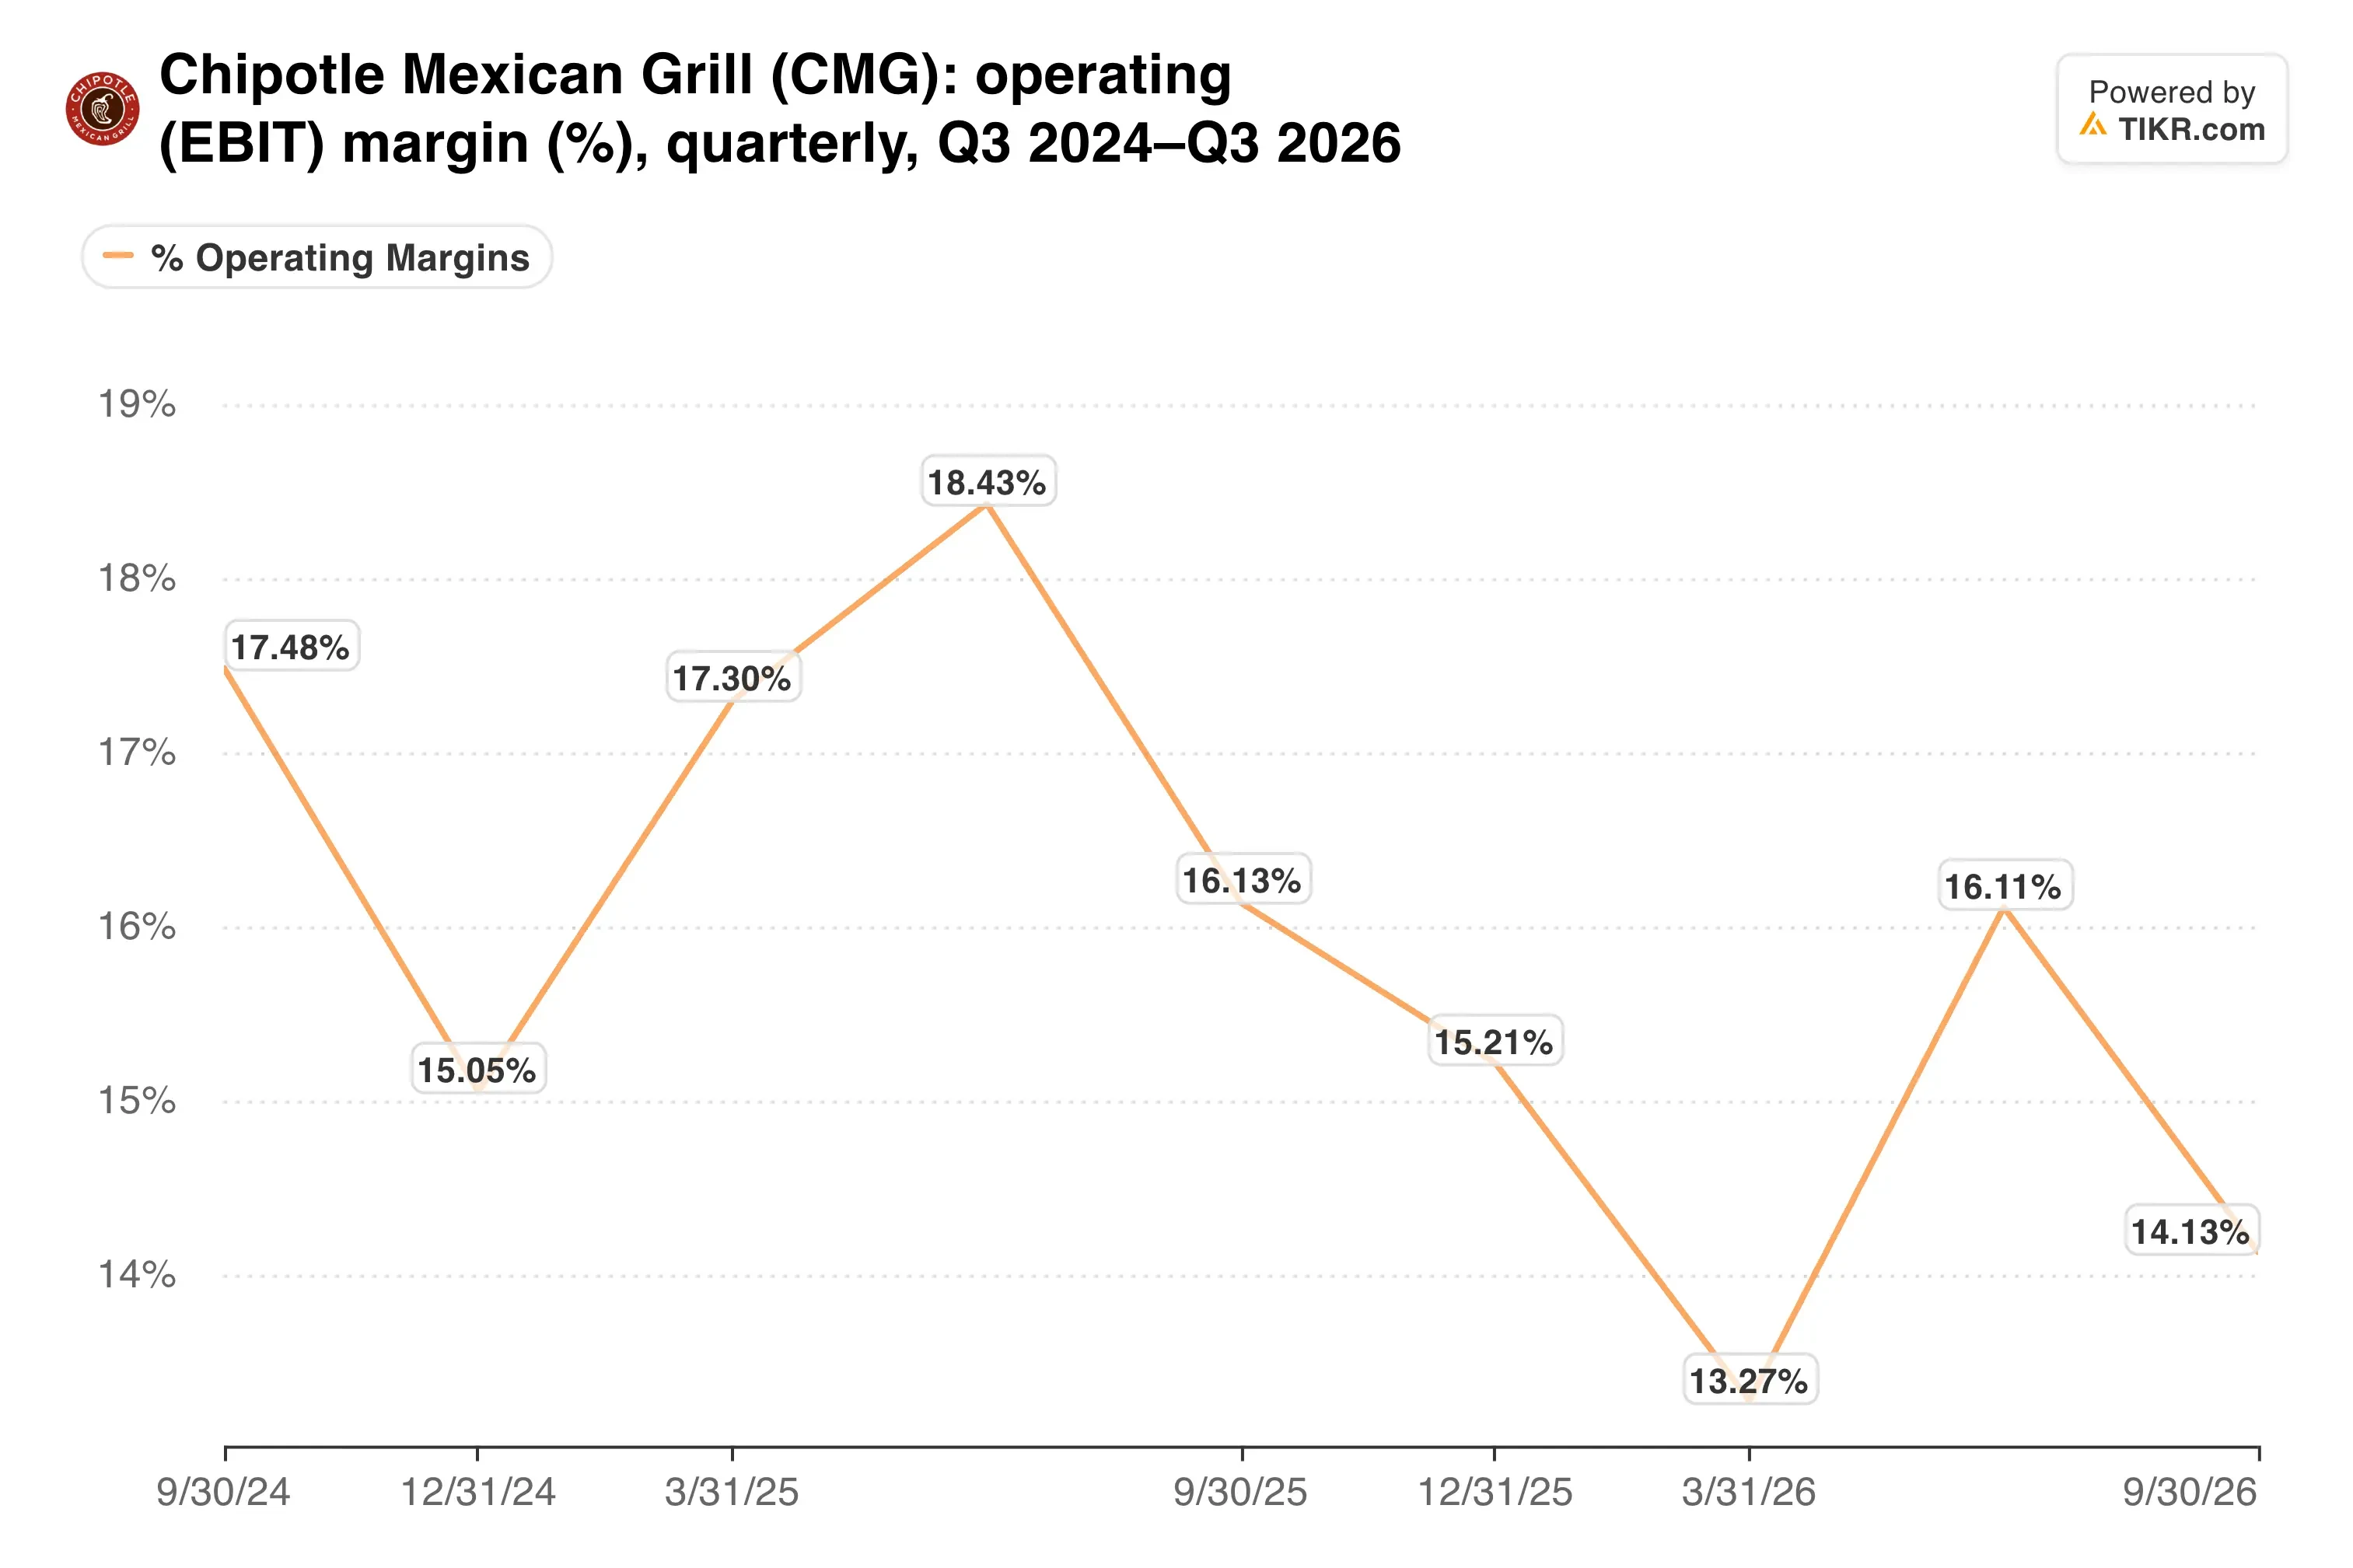
Chipotle expects a restaurant margin baseline in the mid-24% range for 2027, but only if pricing covers inflation and transactions grow at least 1%.
TIKR tracks 35 analysts on Chipotle Mexican Grill. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Chipotle Mexican Grill, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Chipotle Mexican Grill’s Analyst Ratings
Brisket carries the fourth quarter
Guidance calls for fourth-quarter comps of about 2%, exiting the year at 3% to 4%. Smoked Brisket returns to U.S. and Canadian menus on November 5, and it lifted transactions about 4% when it last ran in 2024.
Chipotle reaffirmed 350 to 370 openings this year. For 2027, it plans 340 to 360 company restaurants in the U.S. and Canada plus 15 to 25 international partner sites.
Two years ago, investors paid a steep premium for this growth. Today?
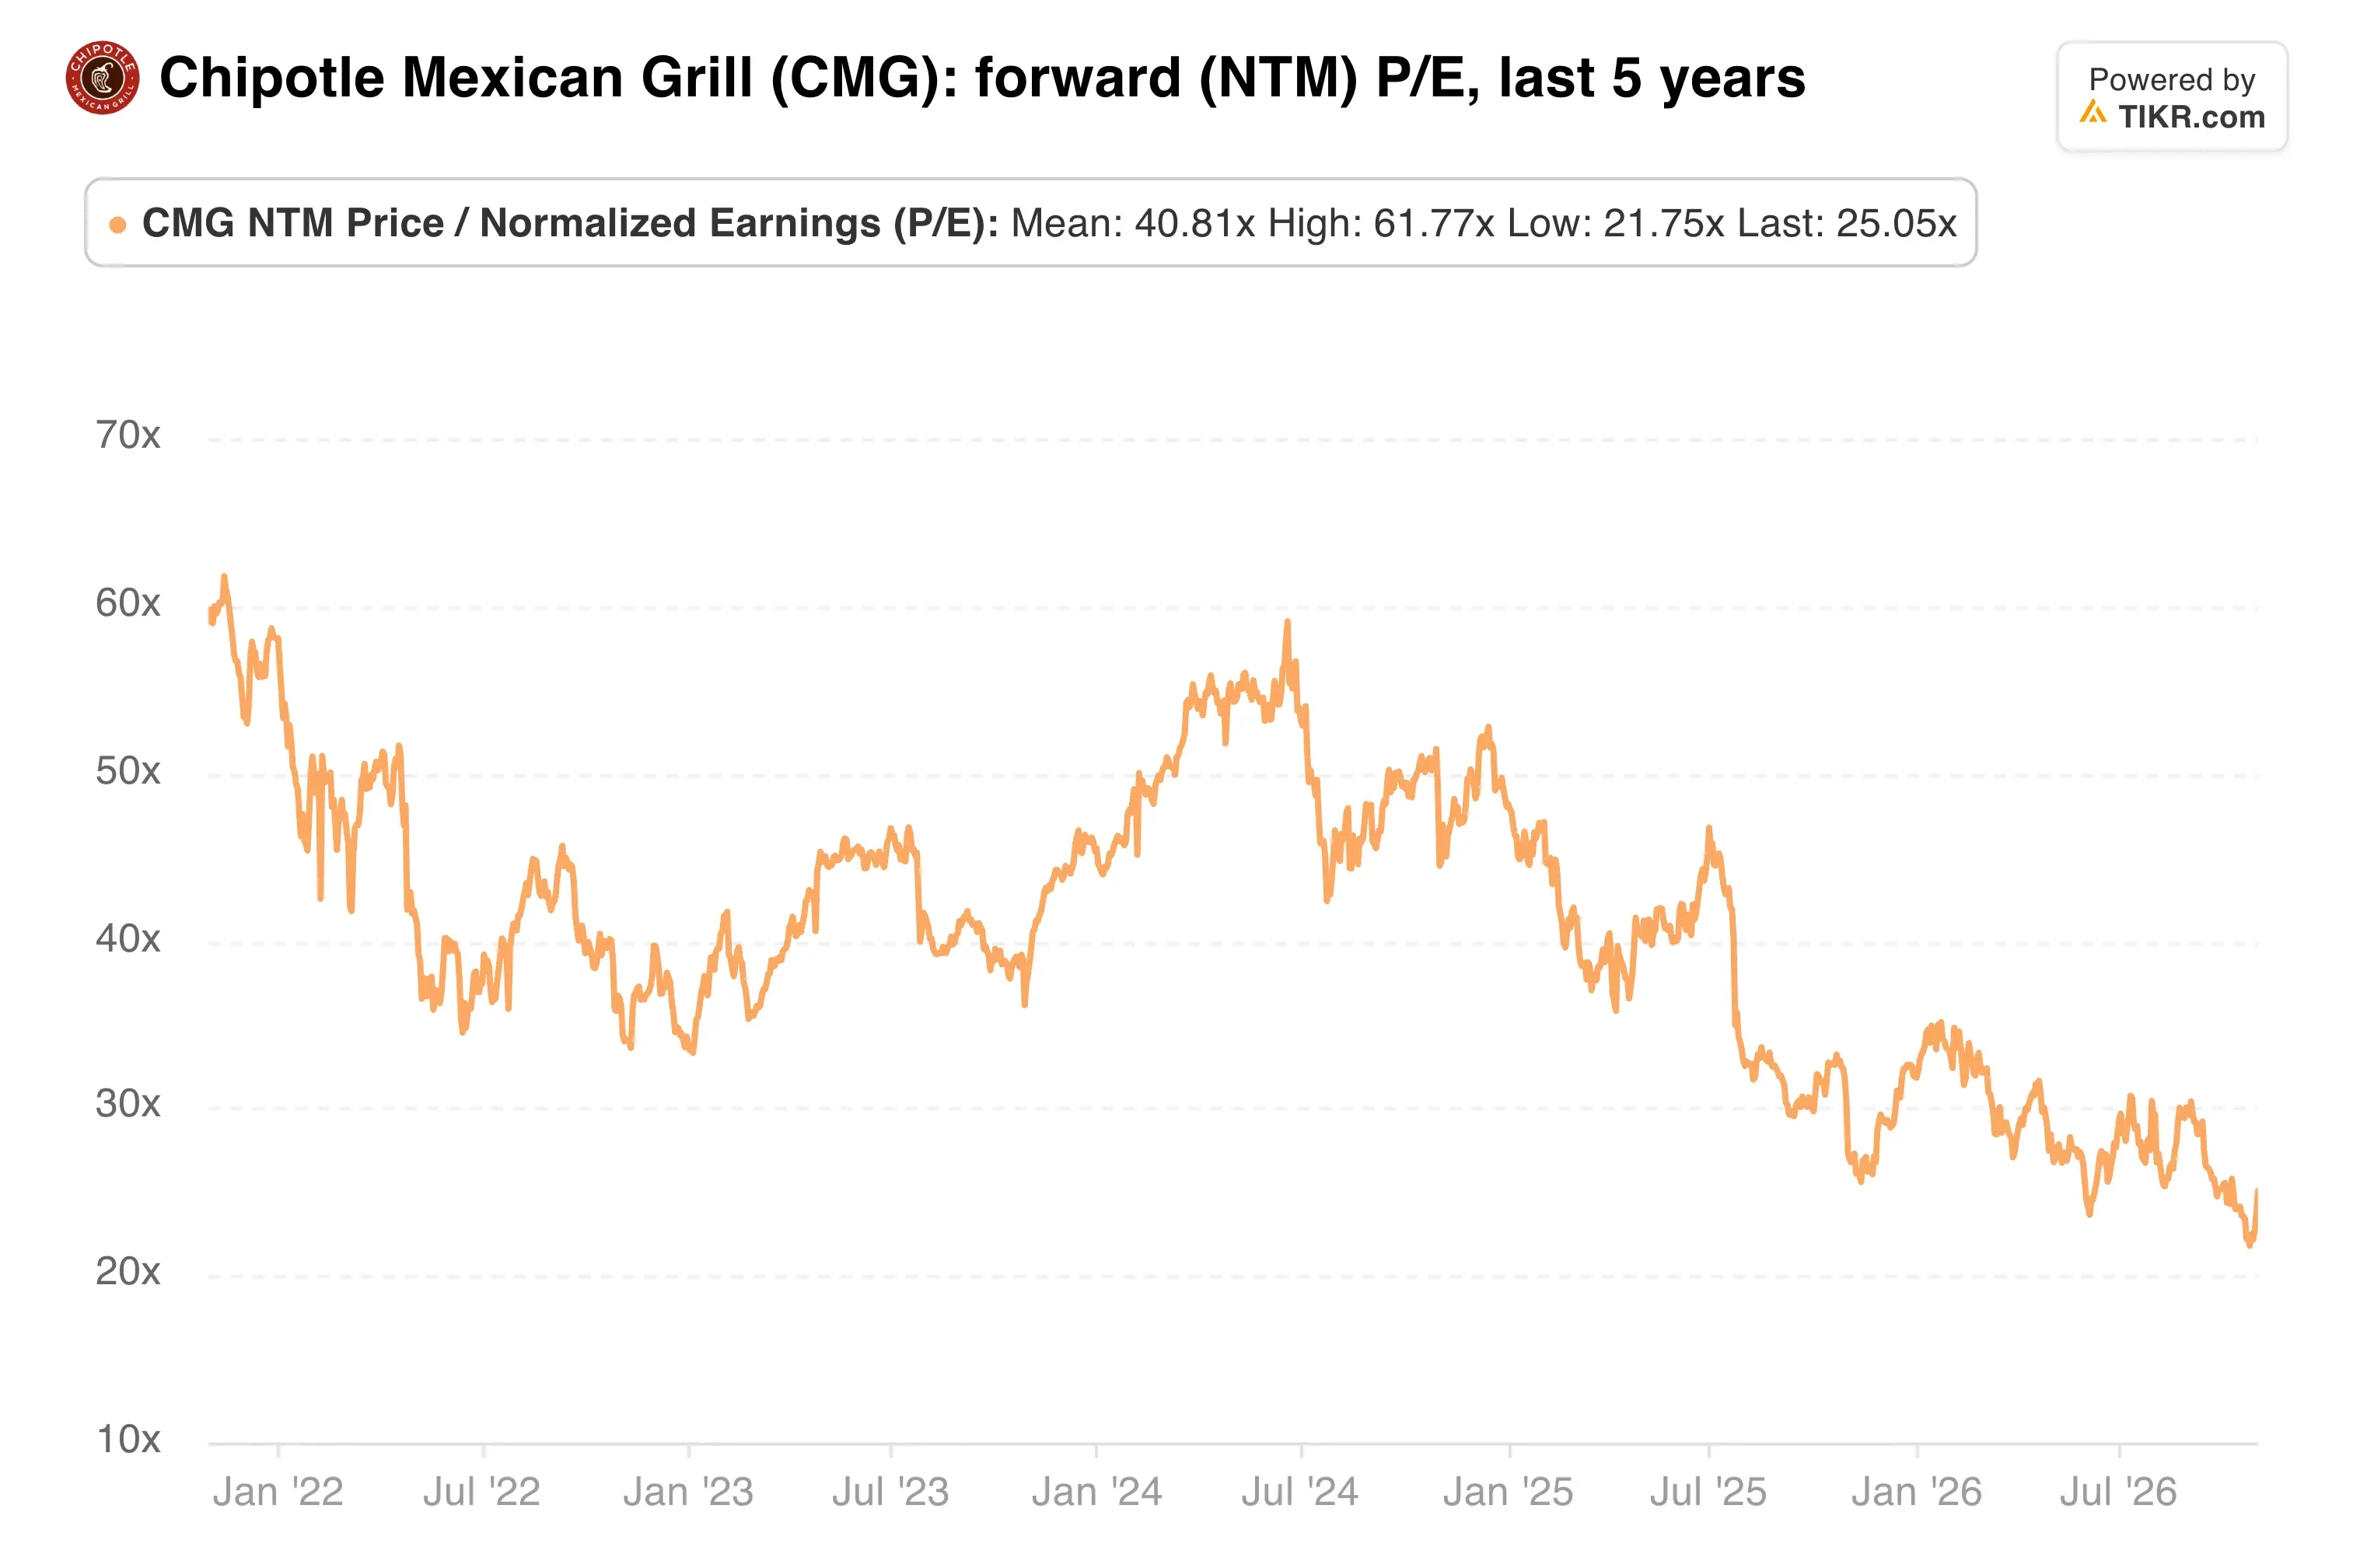
At 25.1x forward earnings, the $40.57 average target implies 27% upside. TD Cowen downgraded the stock on October 21 with a Street-low target, so the bear case still has a voice.
My take: Three straight quarters of positive traffic is the right signal, and the multiple is reasonable. Still, Chipotle is buying that traffic with margin, and a brisket-led exit rate has to prove it can last after the promotion ends. I’d own it here, but in a modest position.
The first checkpoint arrives Thursday, when brisket returns. The early February report will show whether the 3% to 4% exit rate held and whether margin stopped sliding.
So what is Chipotle Mexican Grill stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Chipotle Mexican Grill could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!