Key Stats for Spotify Stock
- Current Price: $529.14
- Target Price (Mid): ~$1,040
- Street Target: ~$594
- Potential Total Return: ~97%
- Annualized IRR: ~17% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Spotify (SPOT) said on October 7 that it will take audiobooks from 22 markets to more than 180 by the end of 2026. On October 8, it renewed its licensing deal with Joe Rogan.
Shares rose about 5% intraday on October 7, though coverage split on why. TipRanks tied the move to a Bank of America note in which Jessica Reif Ehrlich reaffirmed a Buy and a $685 target, well above the Street mean of around $594. Other coverage pointed to the audiobook news. That week, Piper Sandler initiated coverage at Neutral with a $540 target.
The stock closed at $529.14 on October 9, up 8.6% from its September 30 close but 8.9% below where it started 2026. Spotify’s investor relations materials set October 22, before the market opens, for third-quarter results.
Twelve Hours in Brazil, Add-On Only in Africa
New markets do not get the same deal. Eligible Premium subscribers in markets such as Brazil, Italy, Mexico, and Poland get 12 hours of audiobooks a month. That is below the roughly 15 hours co-CEO Gustav Söderström described Premium including. Across Africa, Asia, and Argentina, the paid Audiobooks+ add-on is the main way in.
The tiers fit how Söderström framed the business at the Goldman Sachs Communacopia + Technology Conference on September 9. Listening hours carry a cost, so Spotify controls how much Premium includes and sells to heavy users more. As he put it, “the margin is a managed outcome.”
He also relayed co-CEO Alex Norström’s line that maturing markets let Spotify keep “using the West to fund the East,” where much of its growth now comes from.
Demand is building: Audiobooks+ has more than one million subscribers, and monthly audiobook listeners grew nearly 40% over the past year. Management’s August 4 guide, set before any new market launched, already had a third-quarter gross margin at 32.9%. That is below the second quarter’s 33.4%.
See historical and forward estimates for Spotify stock (It’s free!) >>>
Rogan Stays as Spotify Pays Podcasters From Premium
The renewal keeps Spotify’s licensing and ad-sales rights on the No. 1 U.S. podcast by reach in the second quarter of 2026, according to Edison Research, though the show stays on other platforms. Spotify did not disclose terms. The Wall Street Journal reported they resemble the prior deal, which carried an estimated $250 million earnout.
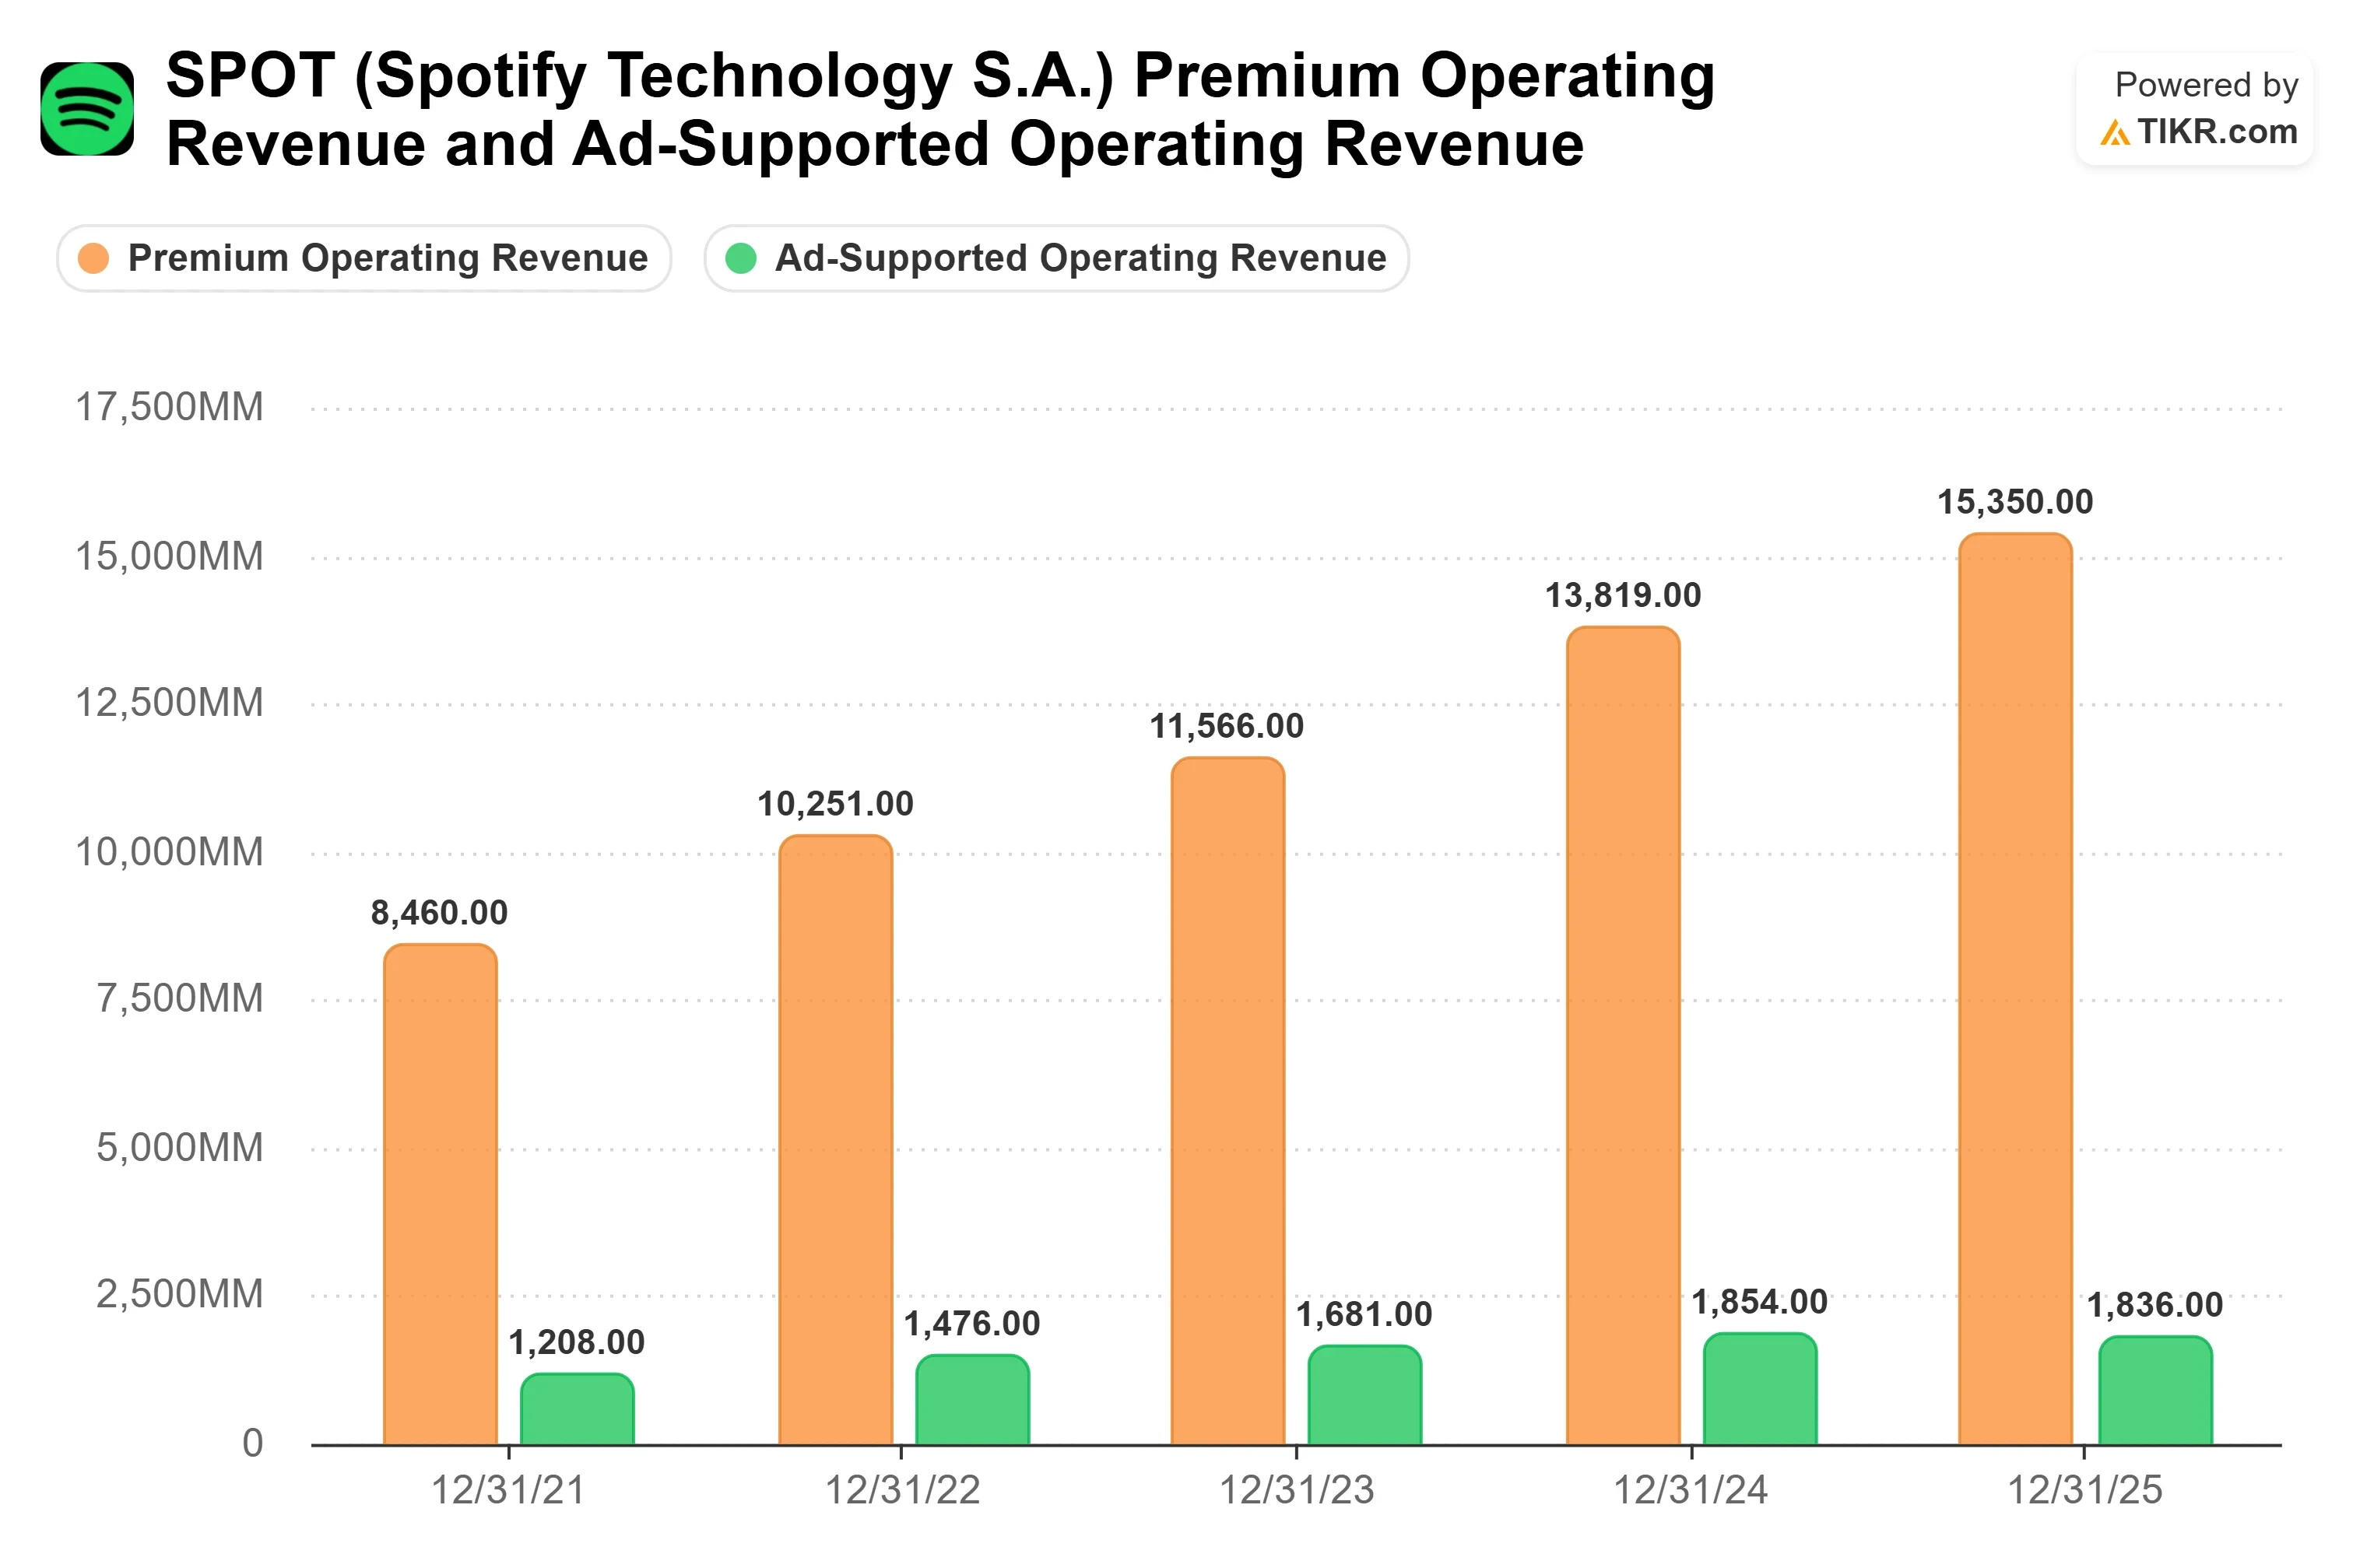
Ads remain the slower line: Ad-Supported revenue rose 1% year over year to €446 million in the second quarter, while Premium grew 15%. Söderström’s podcast plan leans on Premium. The Spotify Partner Program removed Spotify’s own ads from podcasts for Premium listeners and pays creators from the Premium pool, which he said brought creators to upload video.
“I think video has grown 50% year-over-year on Spotify,” he said, adding that only Spotify and YouTube compete seriously in video podcasts. Rogan’s show has more than 18 million followers on Spotify and over 21 million on YouTube.
See how Spotify performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $529.14
- Target Price (Mid): ~$1,040
- Potential Total Return: ~97%
- Annualized IRR: ~17% / year

See analysts’ growth forecasts and price targets for Spotify stock (It’s free!) >>>
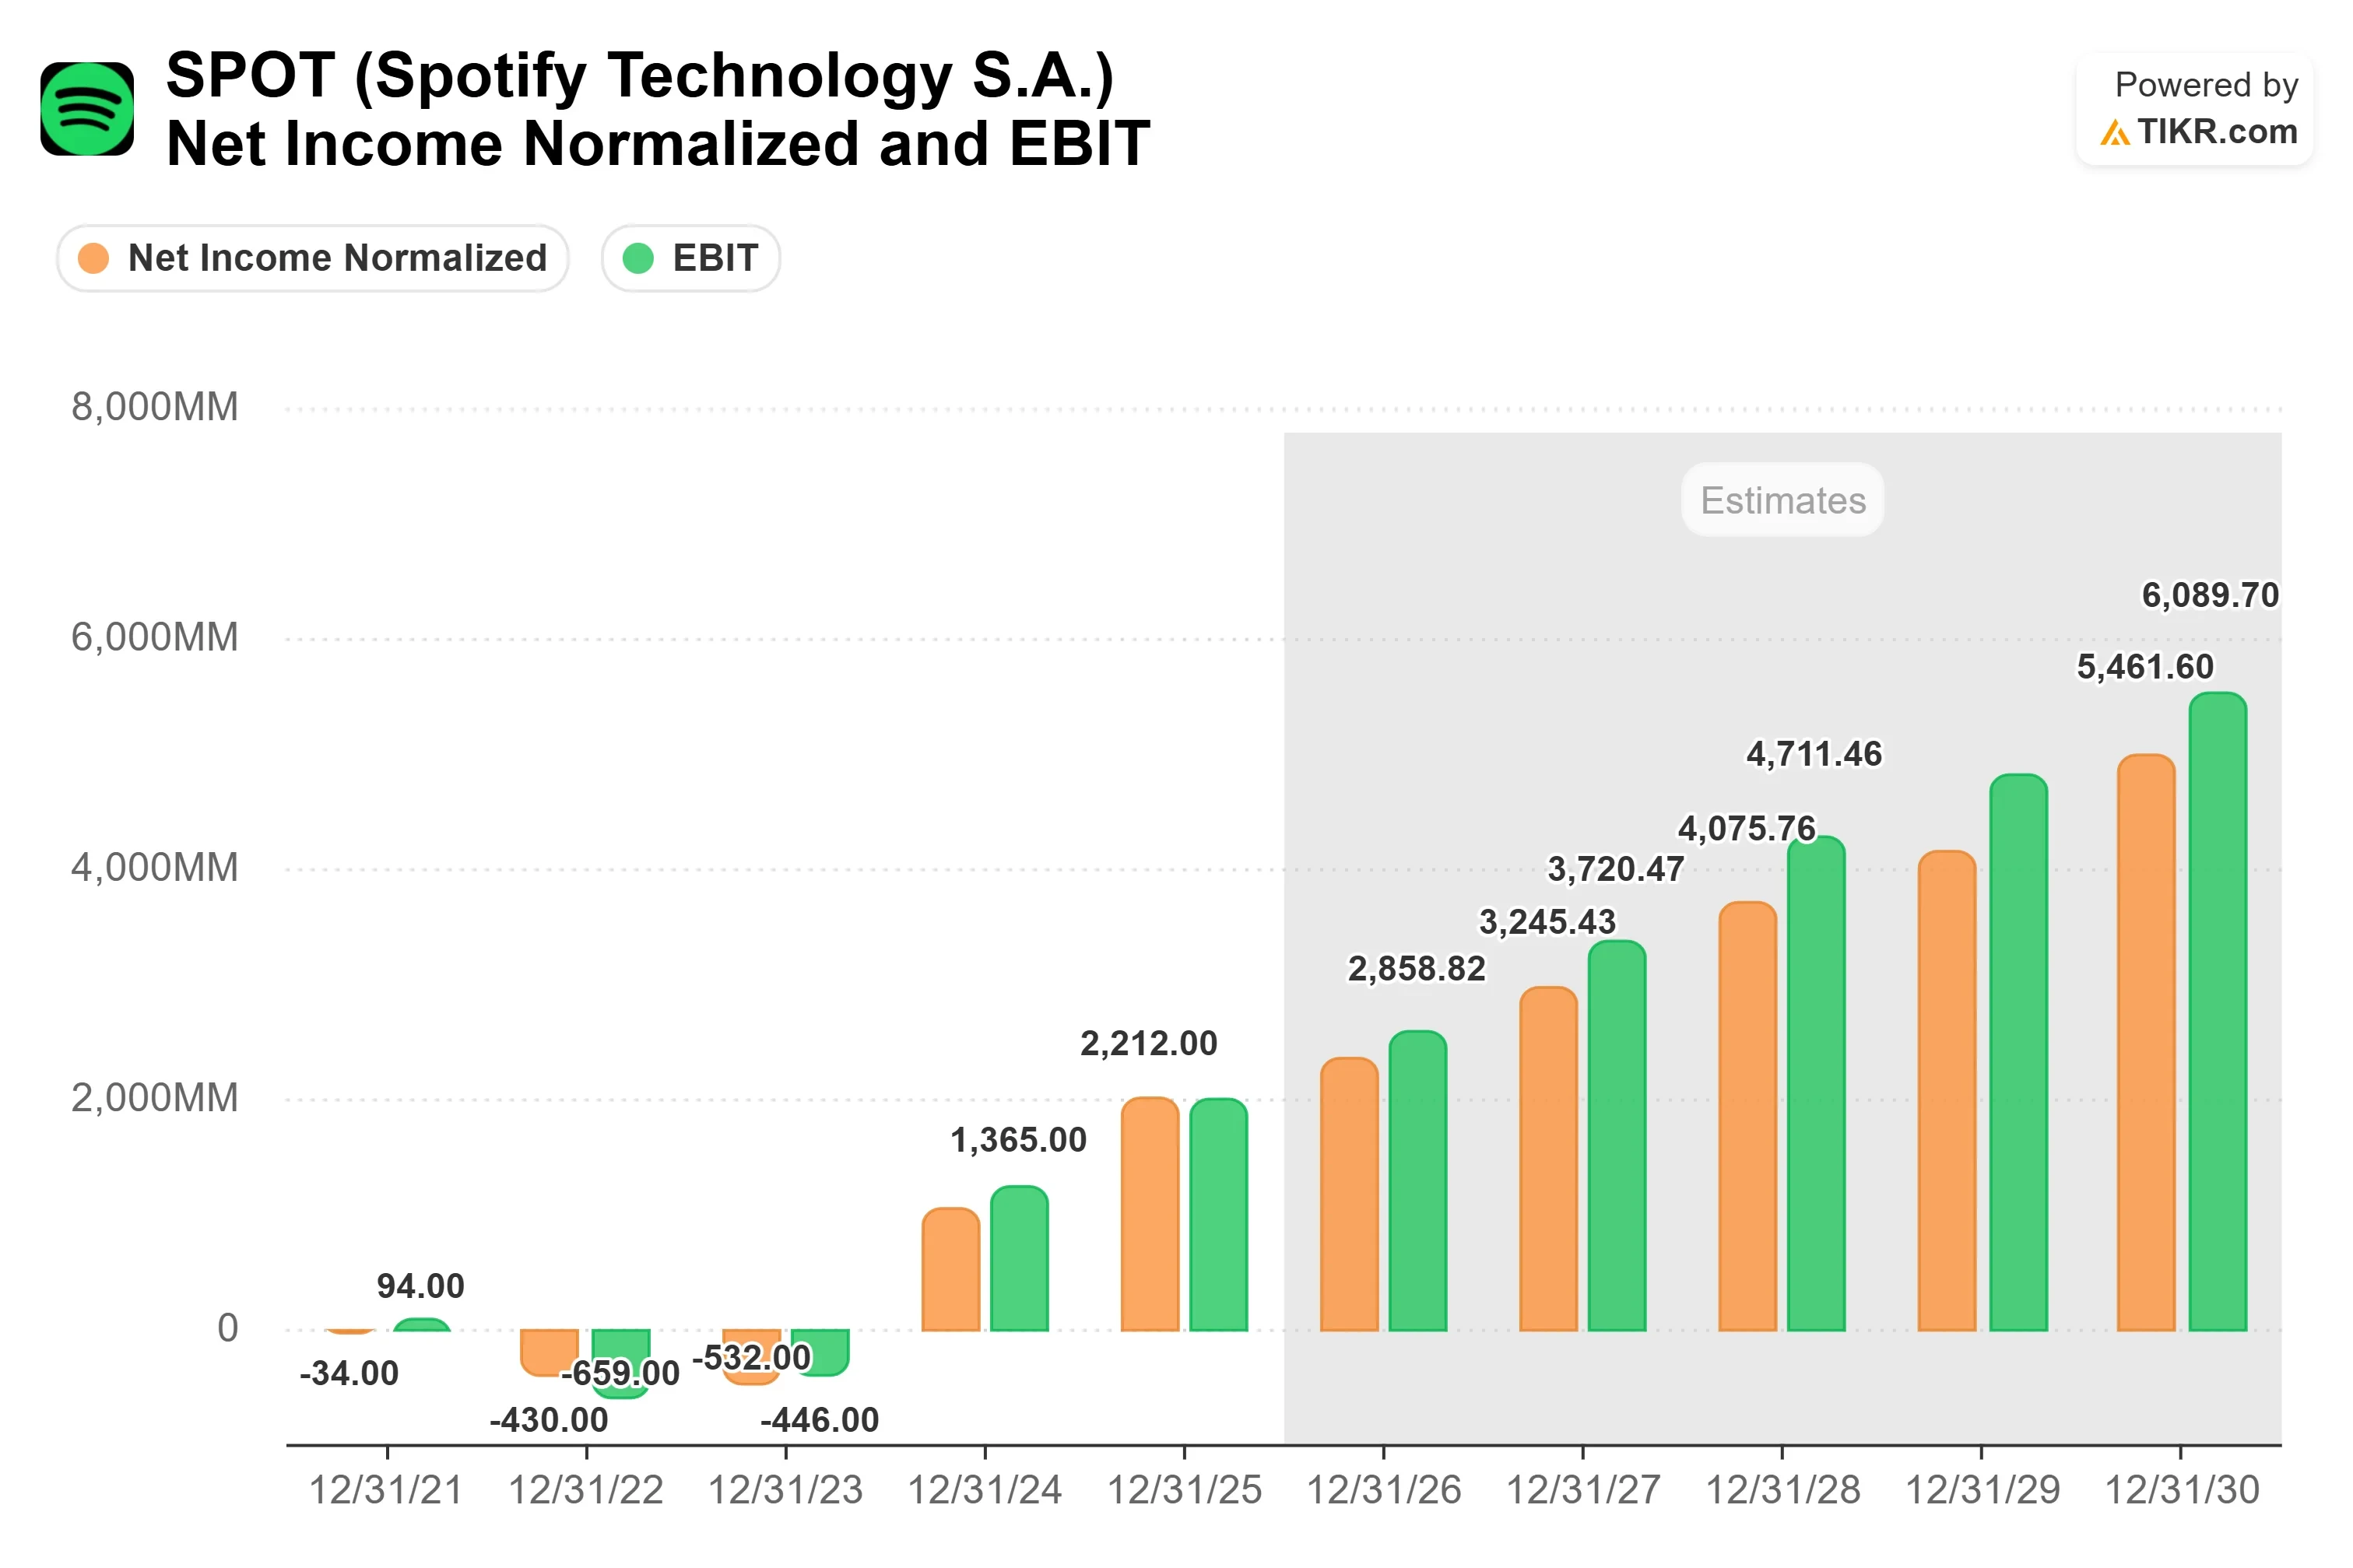
TIKR’s mid-case reaches around $1,040 by December 31, 2030, measured from the October 9 close of $529.14. For context, Street consensus on TIKR has revenue rising from €17,186 million in 2025 to around €30.7 billion in 2030, about 12% a year, with normalized net margins near 18% by 2030.
Pricing drives the margin case. Söderström said Spotify is “more expensive than our competitors in all markets, and we still don’t see the churn.”
The primary risk is licensing costs in lower-priced audiobook markets eating into gross margin. Upside comes from add-ons beyond Audiobooks+. On the downside, the Street’s lowest target of around $408 sits about 23% below the October 9 close, with ratings at 24 Buys, 8 Outperforms, and 8 Holds.
Conclusion
October 22 can only hint at the rollout’s cost, since the third quarter ended on September 30. Revenue above management’s €5.0 billion guide, which the Street’s roughly €4.98 billion trails, would show the base business holding up. The fourth-quarter gross margin guide matters more: one at or above 32.9% would be an early sign the 12-hour tier is not diluting margin.
Consensus already calls for a headline EPS decline. Adjusted EPS is expected to fall about 13% as operating income rises about 16%, because the third-quarter 2025 net income of €899 million ran well above its €582 million operating income.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is Spotify stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Spotify could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Spotify on TIKR Free →
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!