AT&T (T) shares fell 5.6% on Friday, October 23, to a more than three-month low after Bloomberg reported that SpaceX (SPCX) is in talks to access at least 80,000 U.S. cell sites for a wireless carrier of its own. T-Mobile (TMUS) lost 5% and Verizon (VZ) slipped 1.6%, according to Reuters. None of the companies has confirmed the talks.
It’s the second SpaceX hit in two weeks. On October 9, after SpaceX agreed to buy Grain Management’s nationwide 800 MHz spectrum for a reported $8 billion, AT&T closed down 9.81% and Verizon had its worst day since 2002.
Spectrum Was the Paper Threat. Towers Make It Real.
A carrier needs two things: airwaves, and somewhere to hang the radios. SpaceX has a deal for the first (still pending FCC approval), and the tower talks go after the second. Bloomberg named Crown Castle among the companies SpaceX is talking to.
The scale is what stands out. 80,000 sites would be about half of the 158,500 purpose-built cell towers operating in the U.S. last year, per the Wireless Infrastructure Association, and TD Cowen puts the cost of a nationwide network above $80 billion. That’s carrier scale, well beyond a satellite service for dead zones.
Crown Castle (CCI) jumped 11.6%. AT&T, Verizon and T-Mobile were expected to generate nearly 90% of its 2025 site rental revenue, so SpaceX would be its first new national carrier tenant in years.
AT&T’s Estimates Are Rising. Its Multiple Isn’t.
Analysts are raising AT&T’s numbers, not cutting them. Wall Street now expects $2.40 of normalized EPS for 2026, in line with the guidance AT&T raised on October 21, and $2.93 for 2028. On the day of the report, those estimates stood at $2.34 and $2.90.
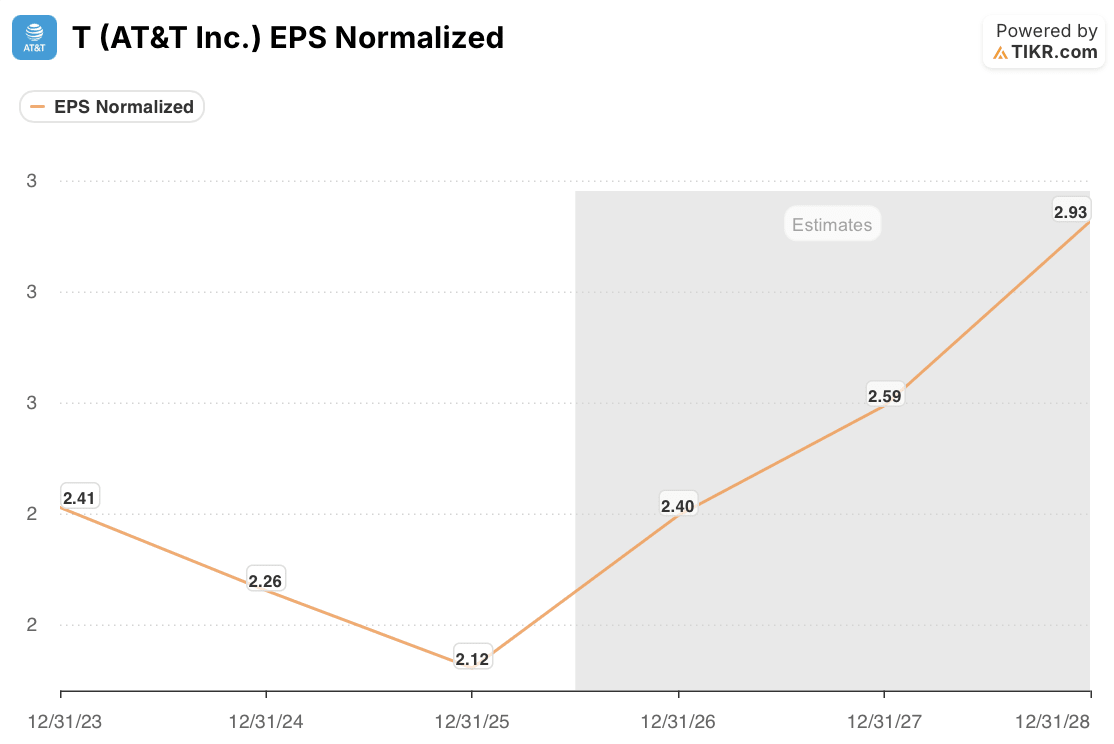
The stock has gone the other way. AT&T trades at 8.96x NTM earnings, below its five-year average of 9.11x and down from 9.70x on October 21. That’s a 7.6% cut to the multiple since then, while the 2026 estimate rose 2.6%.

The market looks to be pricing longer-term competitive risk even as AT&T’s earnings estimates rise.
TIKR Tracks 27 Analysts on AT&T. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AT&T, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AT&T’s Analyst Ratings
Why the Bears Still Have a Case Against AT&T
CEO John Stankey said on the October 21 earnings call that he wouldn’t “over-rotate” on one carrier of low-band spectrum, since AT&T runs six to eight in a typical metro area. He added that building a network to match isn’t done overnight.
The quarter he was defending gives the bears material, though. Wireless service revenue was $17.76 billion, about 55% of AT&T’s $32.3 billion total, and the third-quarter release said promotional discounts on new lines partly offset its 5.0% growth. Postpaid phone adds slowed to 379,000 from 432,000, and churn rose to 0.92% from 0.86%.
AT&T also cut its capital investment outlook to $22 billion to $23 billion a year for 2027 and 2028. That plan was set before a fourth carrier looked this concrete.
The Question AT&T Holders Can’t Answer Yet
It’s whether these talks turn into signed master leases. A lease covering tens of thousands of sites would be a major step toward a ground network, though deployment and pricing pressure could still be years away. If the talks stall, the timing and scale of that buildout would stay uncertain, which leaves the debate closer to Stankey’s view that a rival network takes years.
With the multiple below its five-year average and estimates still climbing, AT&T stock appears to be pricing in the threat before a nationwide leasing agreement has been publicly confirmed. I’d read Friday’s drop as concern about future competition rather than a change in AT&T’s current earnings outlook. The first real check is Verizon’s postpaid phone churn on October 26.
So what is AT&T stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what T stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!