Key Takeaways
- GE Vernova fell 4.9% on Monday in an AI selloff, even though third-quarter orders jumped 96% organically and backlog reached $197 billion.
- Customer deposits drove most of the cash: contract liabilities and deferred income added $19.5 billion to operating cash in nine months, against $2.4 billion a year earlier.
- SoftBank’s Ohio project is under “a thorough reassessment,” a reminder that deposit-heavy cash flow depends on buyers keeping their plans.
- The fourth-quarter report, expected in late January, will show whether backlog clears $200 billion as management expects.
GE Vernova (GEV) fell 4.9% on Monday as an Nvidia-led tech selloff hit stocks tied to AI data centers. The shares then held flat on Tuesday.
It has been a rough month. On November 10, the stock slid after SoftBank Group (9984.T) wrote down $3.7 billion on data center projects. That figure included $2.85 billion of non-refundable advance payments to equipment makers, and GE Vernova was on an early supplier list for its Ohio campus.
German rival Siemens Energy (ENR) is caught in the same trade. Its shares sit roughly 36% below an April record, yet it expects revenue growth to average as much as 14% a year through fiscal 2030.
Meanwhile, the order books keep getting bigger.
Orders nearly doubled in a quarter
GE Vernova’s October 28 report was about as strong as an industrial quarter gets:
- Orders of $29.3 billion, up 96% organically and led by Power equipment.
- Backlog of $197 billion, up $20 billion in three months.
- Revenue of $12.6 billion, up 27%, while adjusted EBITDA margin rose 690 basis points organically to 15.4%.
Gas Power equipment backlog and slot reservations climbed to 122 gigawatts from 116. Management now expects at least 130 gigawatts by year end and a backlog above $200 billion this quarter.
Revenue is still catching up to all those orders…
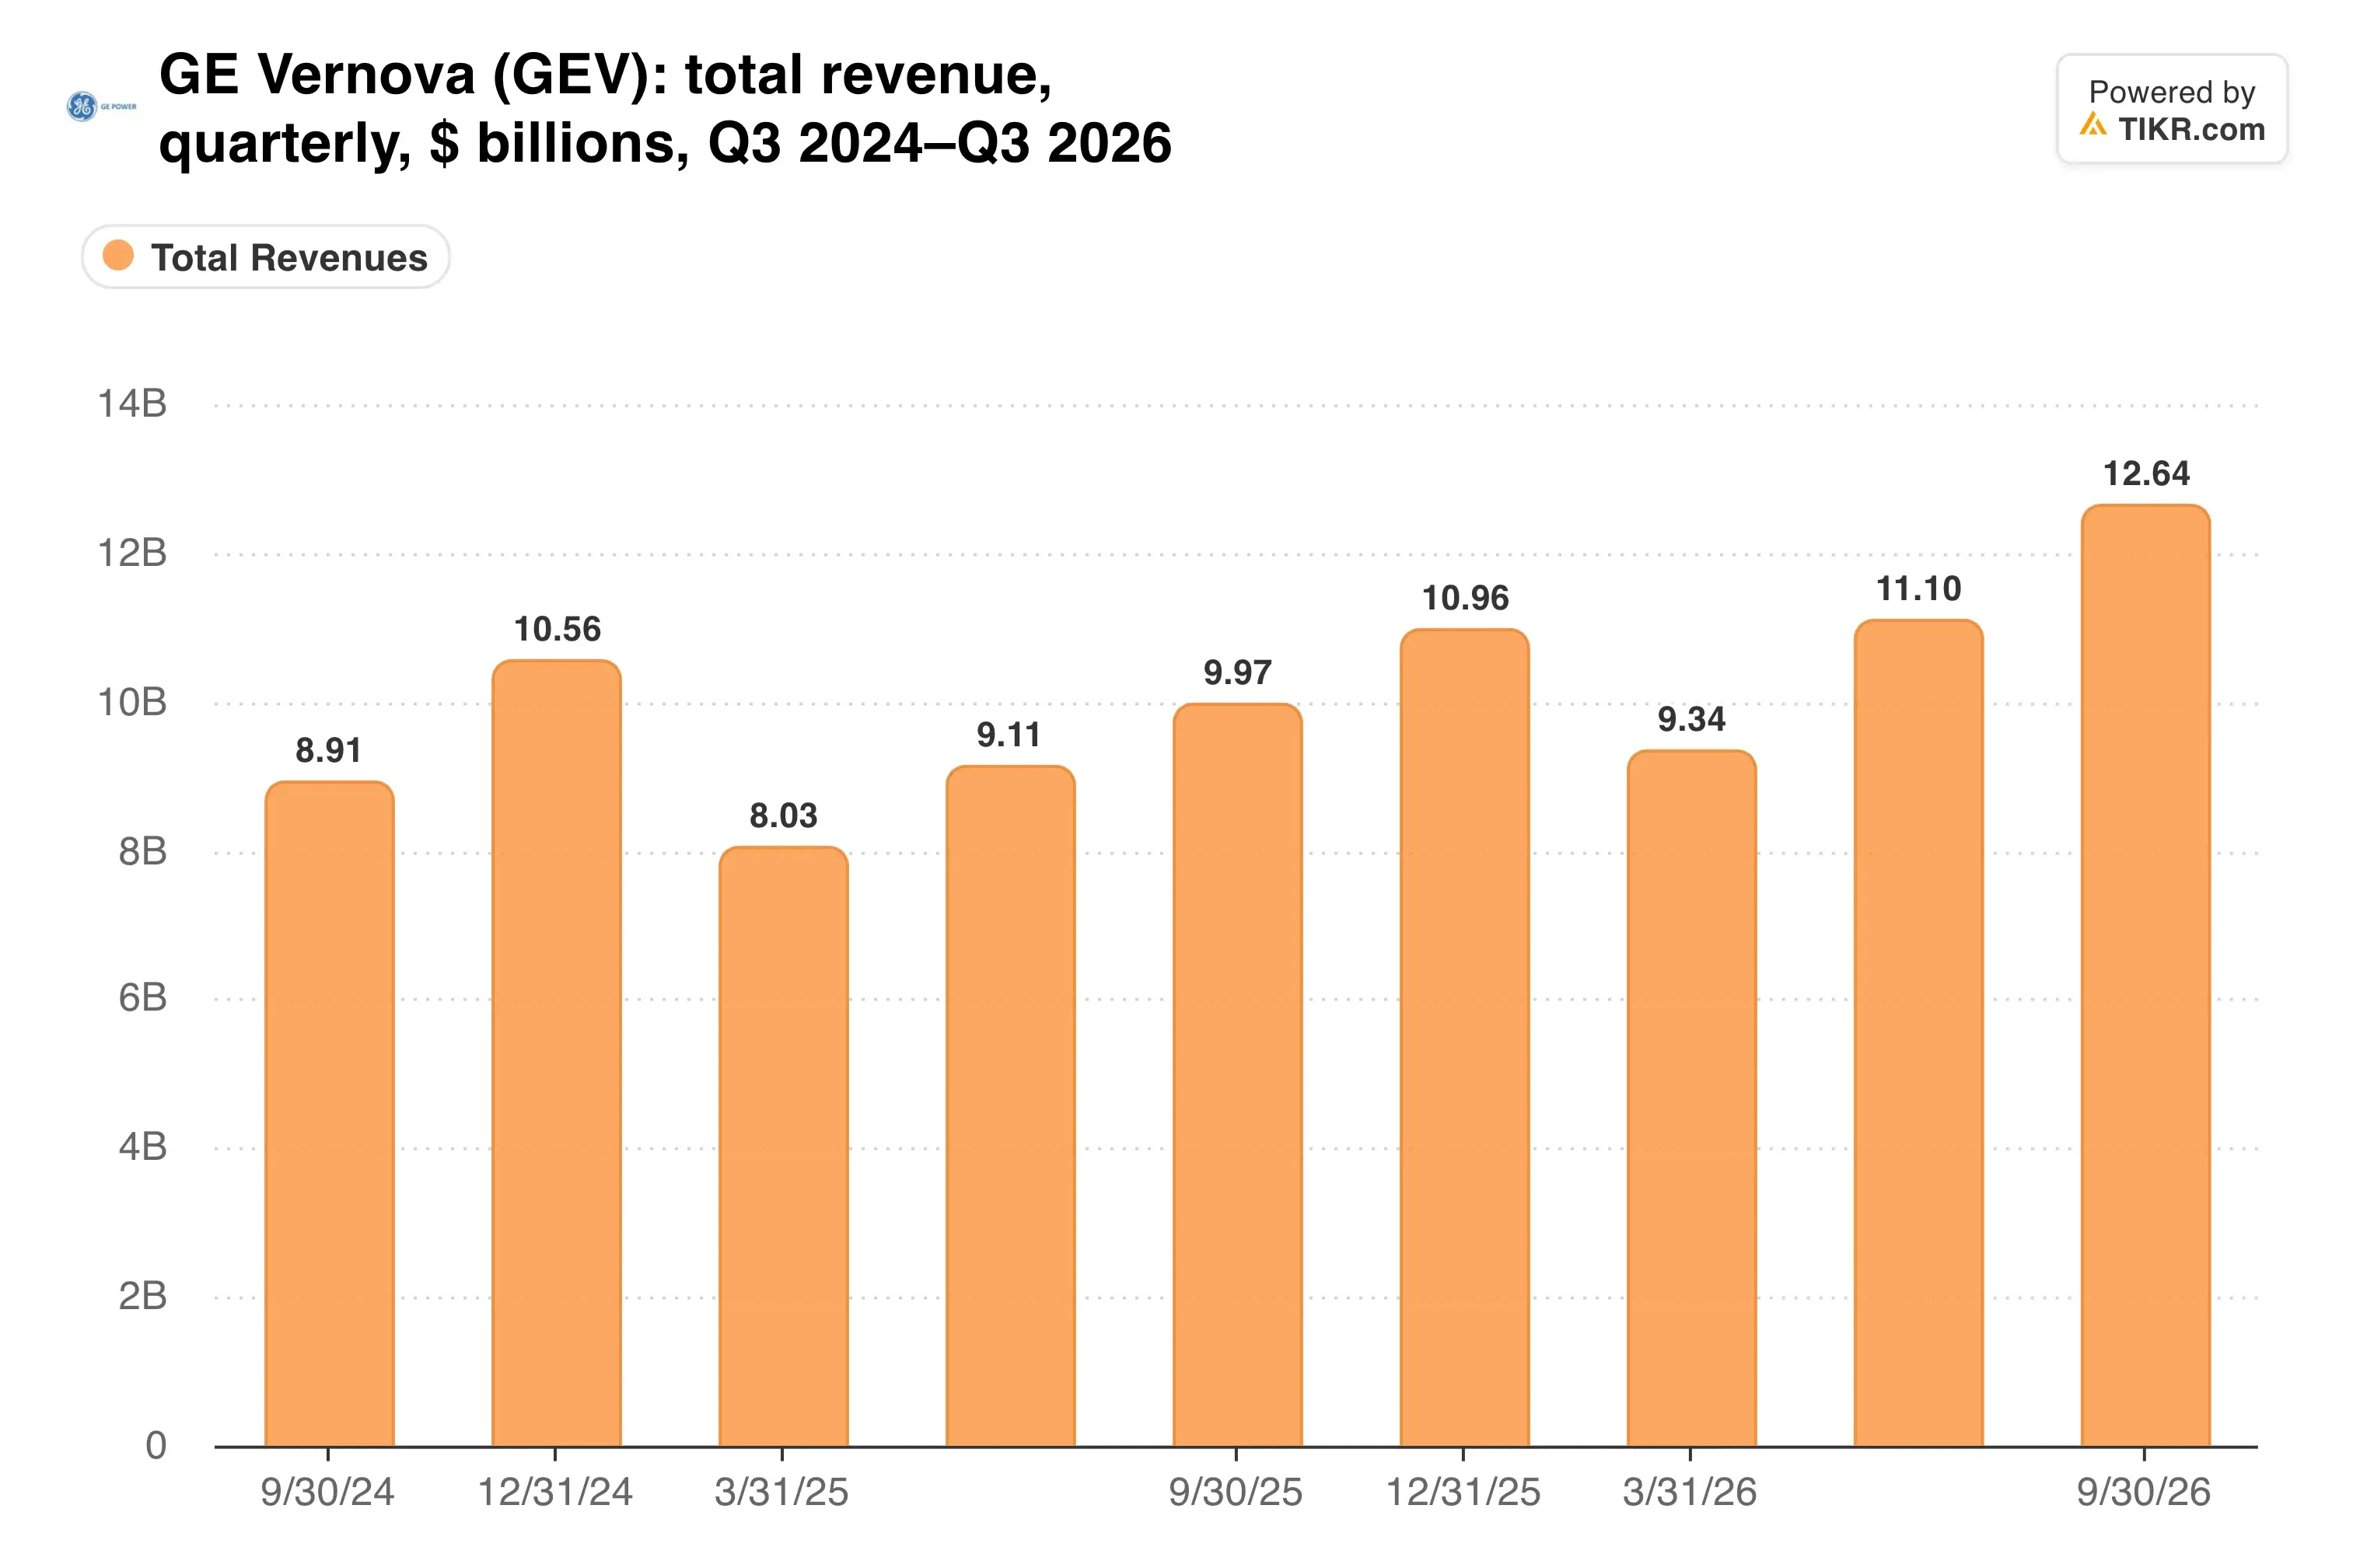
Quarterly sales have grown from $8.9 billion in the third quarter of 2024. But orders ran at more than twice revenue, so the backlog keeps outrunning what the factories can ship.
“Our opportunity to create value is accelerating,” CEO Scott Strazik said in the earnings release.
Siemens Energy tells a similar story. Its Gas Services orders rose 45.9% to €32.8 billion in fiscal 2026, a sign the turbine boom is industry-wide.
Customers are funding the cash surge
Cash is the standout. GE Vernova produced $5.4 billion of free cash flow in the quarter and lifted its 2026 outlook to $16 billion to $17 billion, from $11.5 billion to $12.5 billion.
So where is all that money coming from?
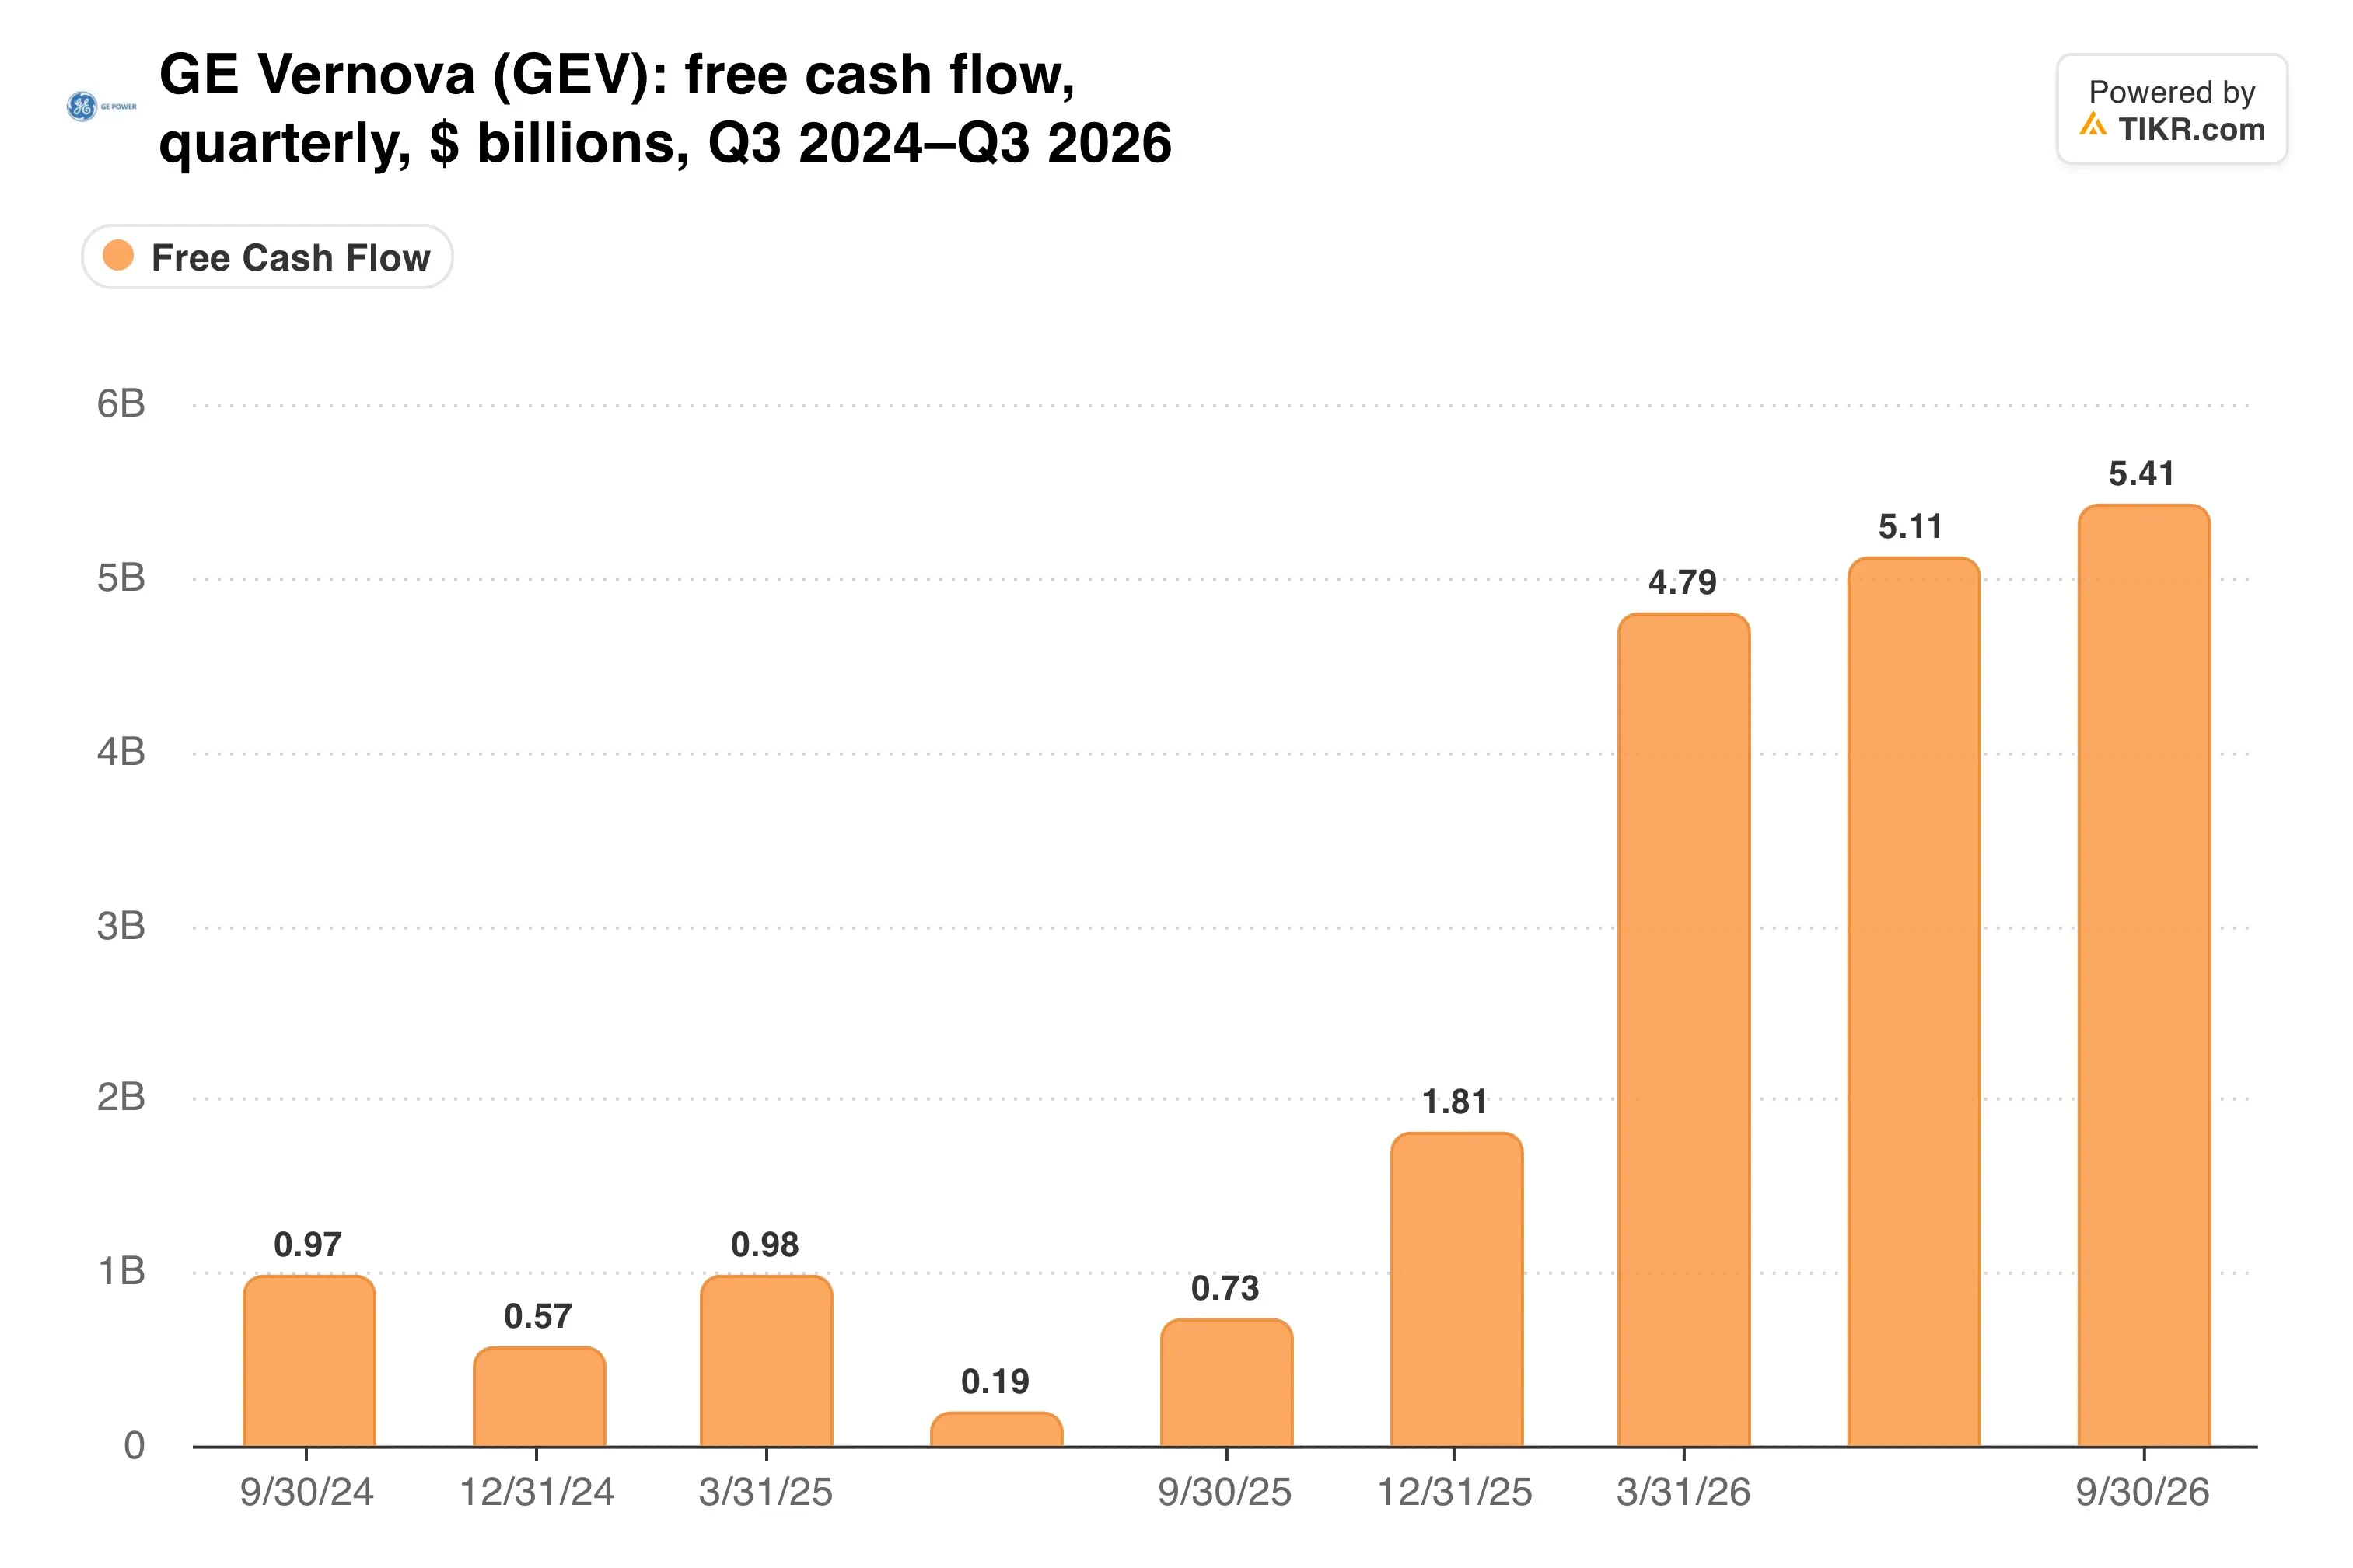
Mostly from customers. Contract liabilities and deferred income added $19.5 billion to operating cash in the first nine months, against $2.4 billion a year earlier. Buyers are paying up front to lock in turbine slots.
That pile ended September near $17 billion, and the board doubled the buyback authorization to $20 billion. Through October 23, GE Vernova had repurchased 15.6 million shares at an average of about $635.
TIKR tracks 38 analysts on GE Vernova. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on GE Vernova, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See GE Vernova’s Analyst Ratings
Deposits cut both ways
Those deposits also carry the risk. SoftBank’s finance chief Yoshimitsu Goto said its Ohio project is undergoing “a thorough reassessment,” including how it buys equipment, Bloomberg reported.
One buyer rethinking its plans won’t empty a $197 billion backlog. Still, it shows how fast a customer can change course when financing tightens. Wind remains a drag too, with $400 million to $500 million of segment EBITDA losses expected this year.
Both turbine makers have given back a chunk of their AI premium since the summer.
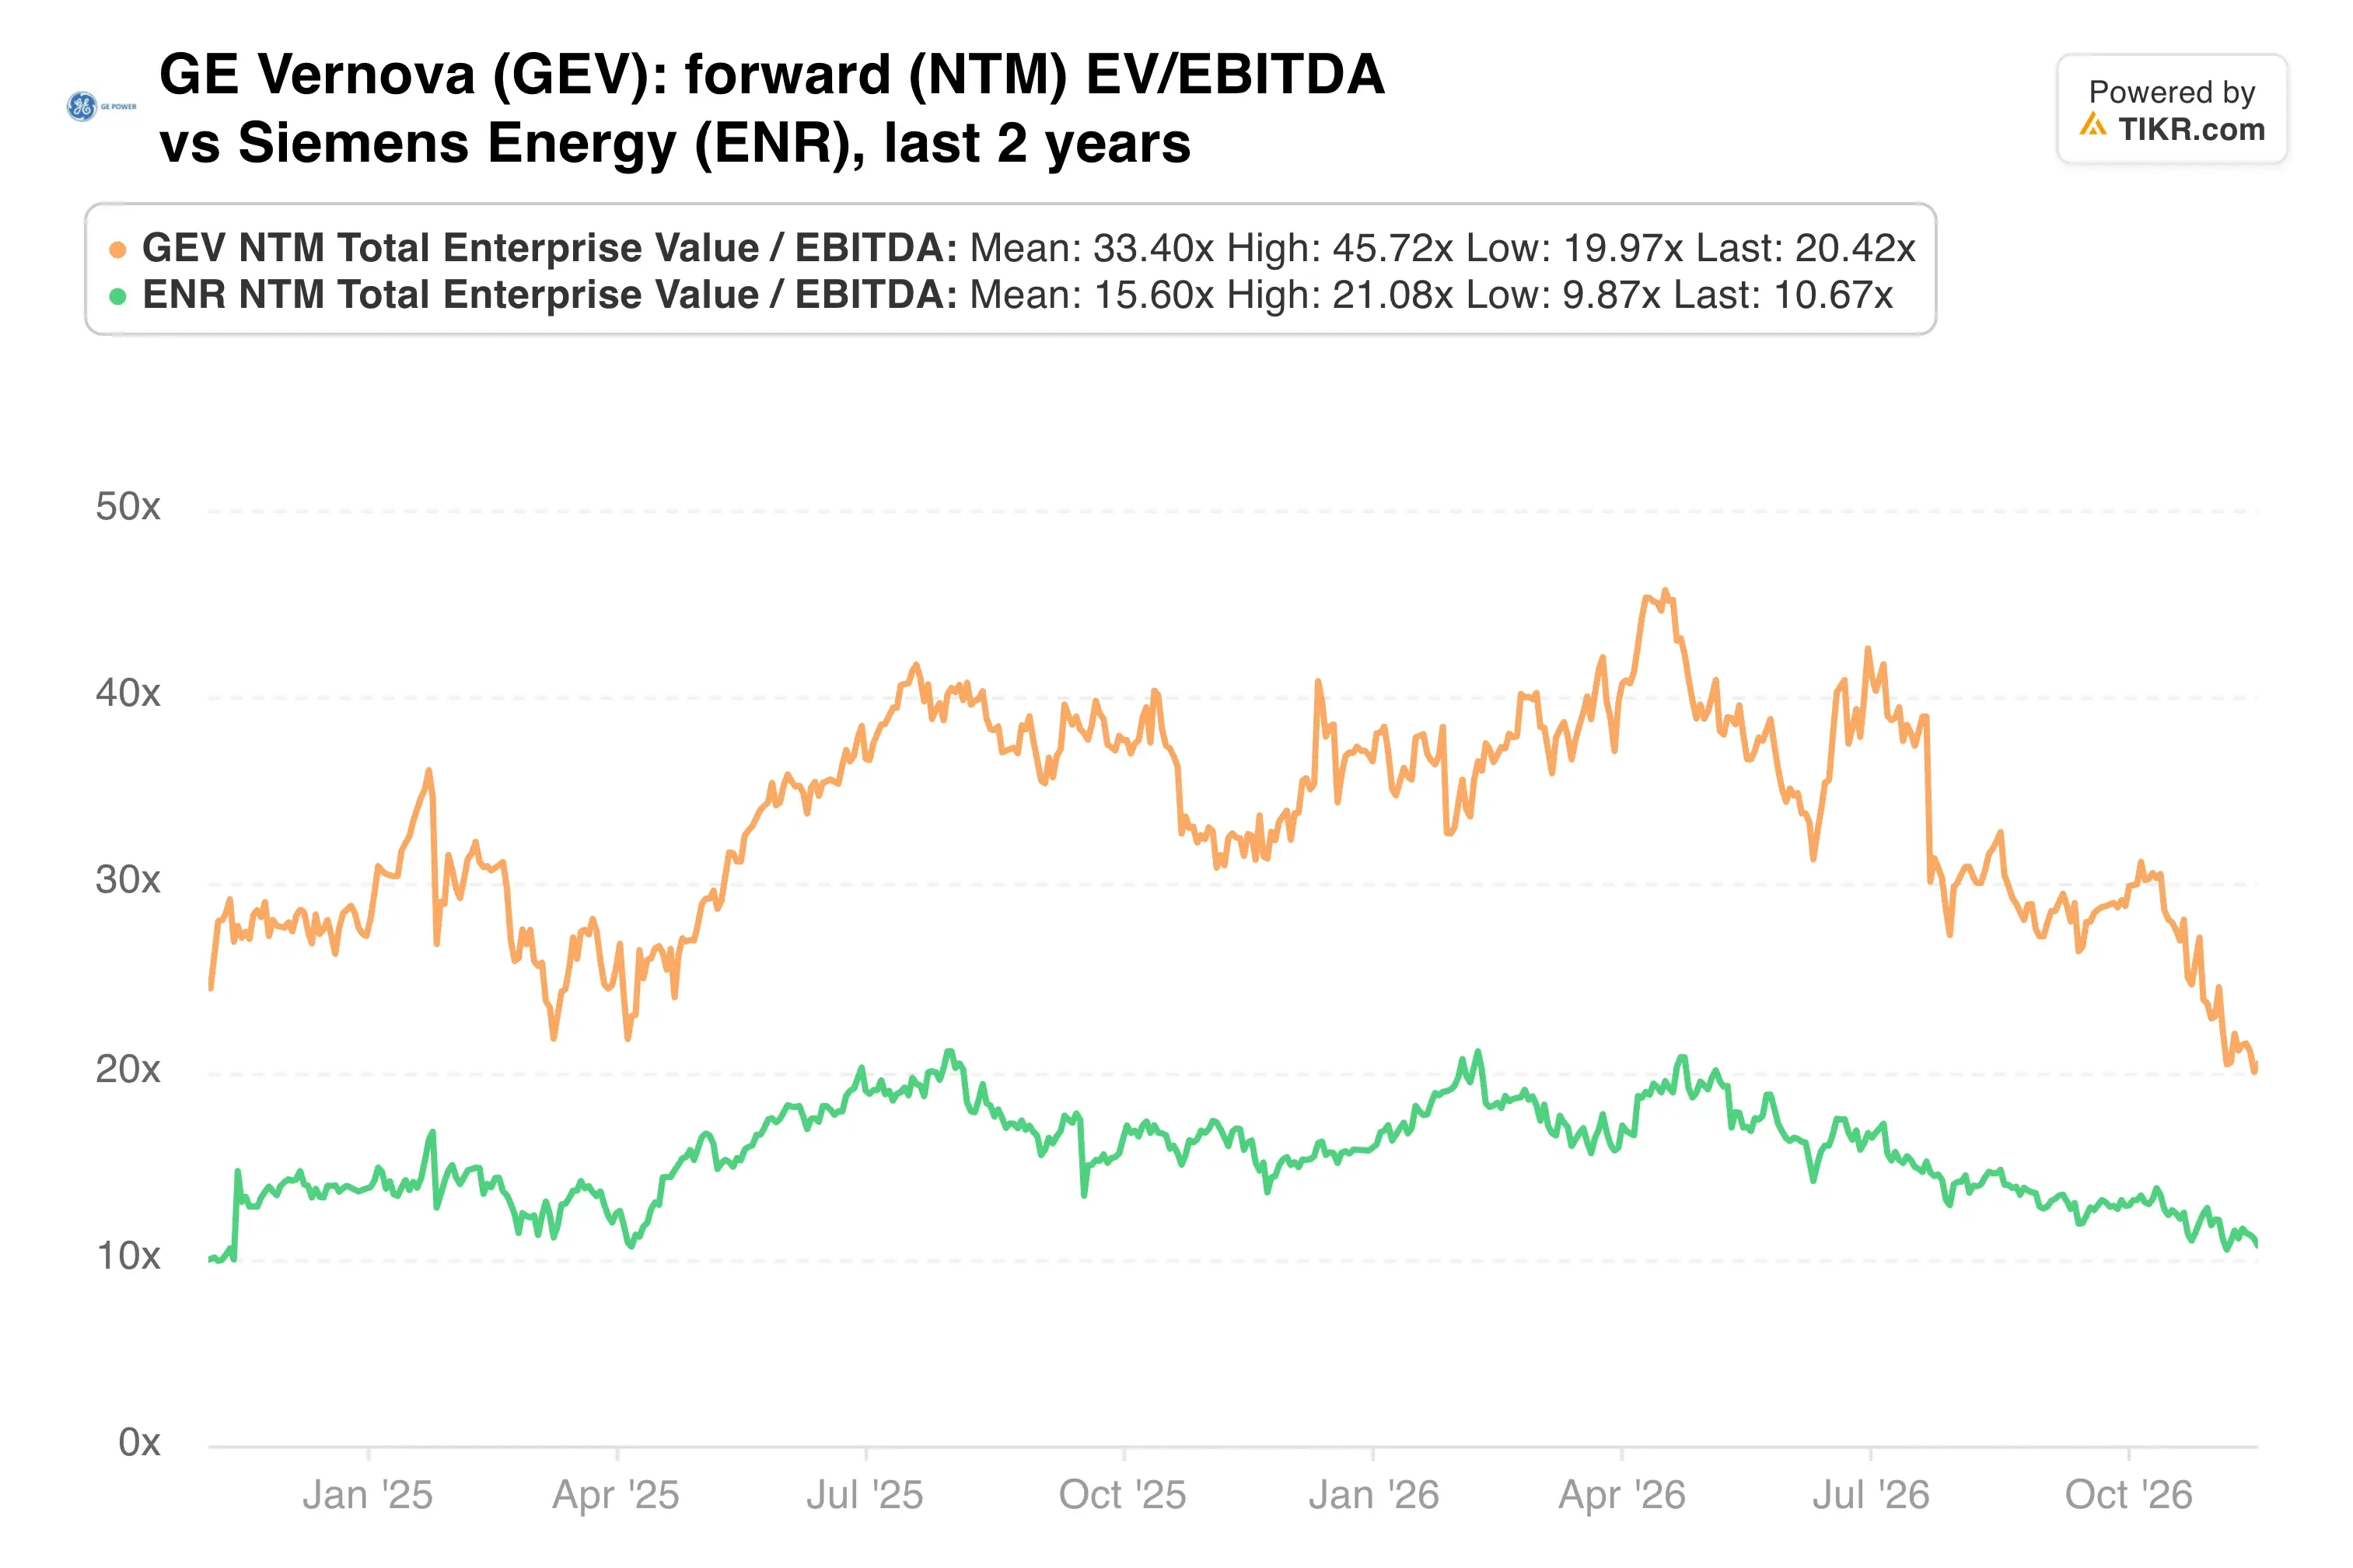
For each, the next leg depends on turning backlog into margin. GE Vernova’s Power segment is already doing that, and its 2026 EBITDA margin outlook rose to 19% to 21%.
My take: The stock has traded on AI headlines this month while the business kept improving. I’d still want proof that deposits keep flowing before calling it a bargain, because customer cash carries much of that free cash flow outlook. A bigger buyback gives management a cushion if the selloff runs further.
GE Vernova’s fourth-quarter report, expected in late January, is the next real test. It will show whether backlog clears $200 billion and whether any gas customer pulled back after SoftBank’s reassessment.
So what is GE Vernova stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what GE Vernova could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!