Key Takeaways
- Snowflake fell 12% in the past week as the AI trade sold off, and the company itself had no bad news.
- RBC’s Matthew Hedberg put Snowflake among the few software companies he sees with real AI acceleration, along with Cloudflare and CrowdStrike.
- UBS and BofA cut their price targets but kept their Buy ratings, and Oppenheimer and Morgan Stanley expect a product revenue beat when Snowflake reports on Dec. 2.
- The stock got cheaper while earnings estimates rose, so it looks like a buy before the report, as long as product gross margin holds at 74%.
Snowflake (SNOW) has dropped 12% in the past week, and the company didn’t report anything to cause it. The whole AI trade sold off, led by the chipmakers, and the Nasdaq 100 fell 10%. Anthropic’s IPO was priced bigger than planned, but it didn’t turn things around on Thursday.
That’s a rough week for a stock one analyst had just put in AI’s top tier. On Nov. 17, RBC Capital Markets software analyst Matthew Hedberg talked with Dan Nathan on the RiskReversal Pod about software stocks and the market’s AI worries. He said he has “seen clear AI leadership from five or six names that I cover where there’s real acceleration.” Snowflake made his list, along with Datadog (DDOG), Cloudflare (NET), CrowdStrike (CRWD) and Palo Alto.
TIKR tracks 51 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
Nobody downgraded it
Snowflake’s only news this week came from analysts, and all of them kept their Buy ratings. UBS cut its target to $450 from $500 on Nov. 18. BofA cut its target to $400 from $470 on Nov. 20 and said demand trends were still strong. Also on Nov. 18, Oppenheimer and Morgan Stanley said Snowflake should beat its fiscal third-quarter product revenue guidance.
Investors are nervous because of Datadog, which also bills by usage. Its third-quarter revenue grew 35% to $1.20 billion. Then it guided to $1.19 billion to $1.20 billion for the fourth quarter, about flat with the third quarter, after its largest customer, an AI company, cut back its usage. Datadog’s stock is down 15% in the past week too. But that was one customer, and no single Snowflake customer makes up even 10% of revenue.
What Dec. 2 has to show
Snowflake reports after the close on Dec. 2. It has guided to product revenue of $1.588 billion to $1.593 billion, up 37% to 38%. Last quarter, product revenue rose 37% to $1.49 billion, and growth sped up for a third straight quarter. Net revenue retention held at 126%. Analysts expect growth to slow after this year:
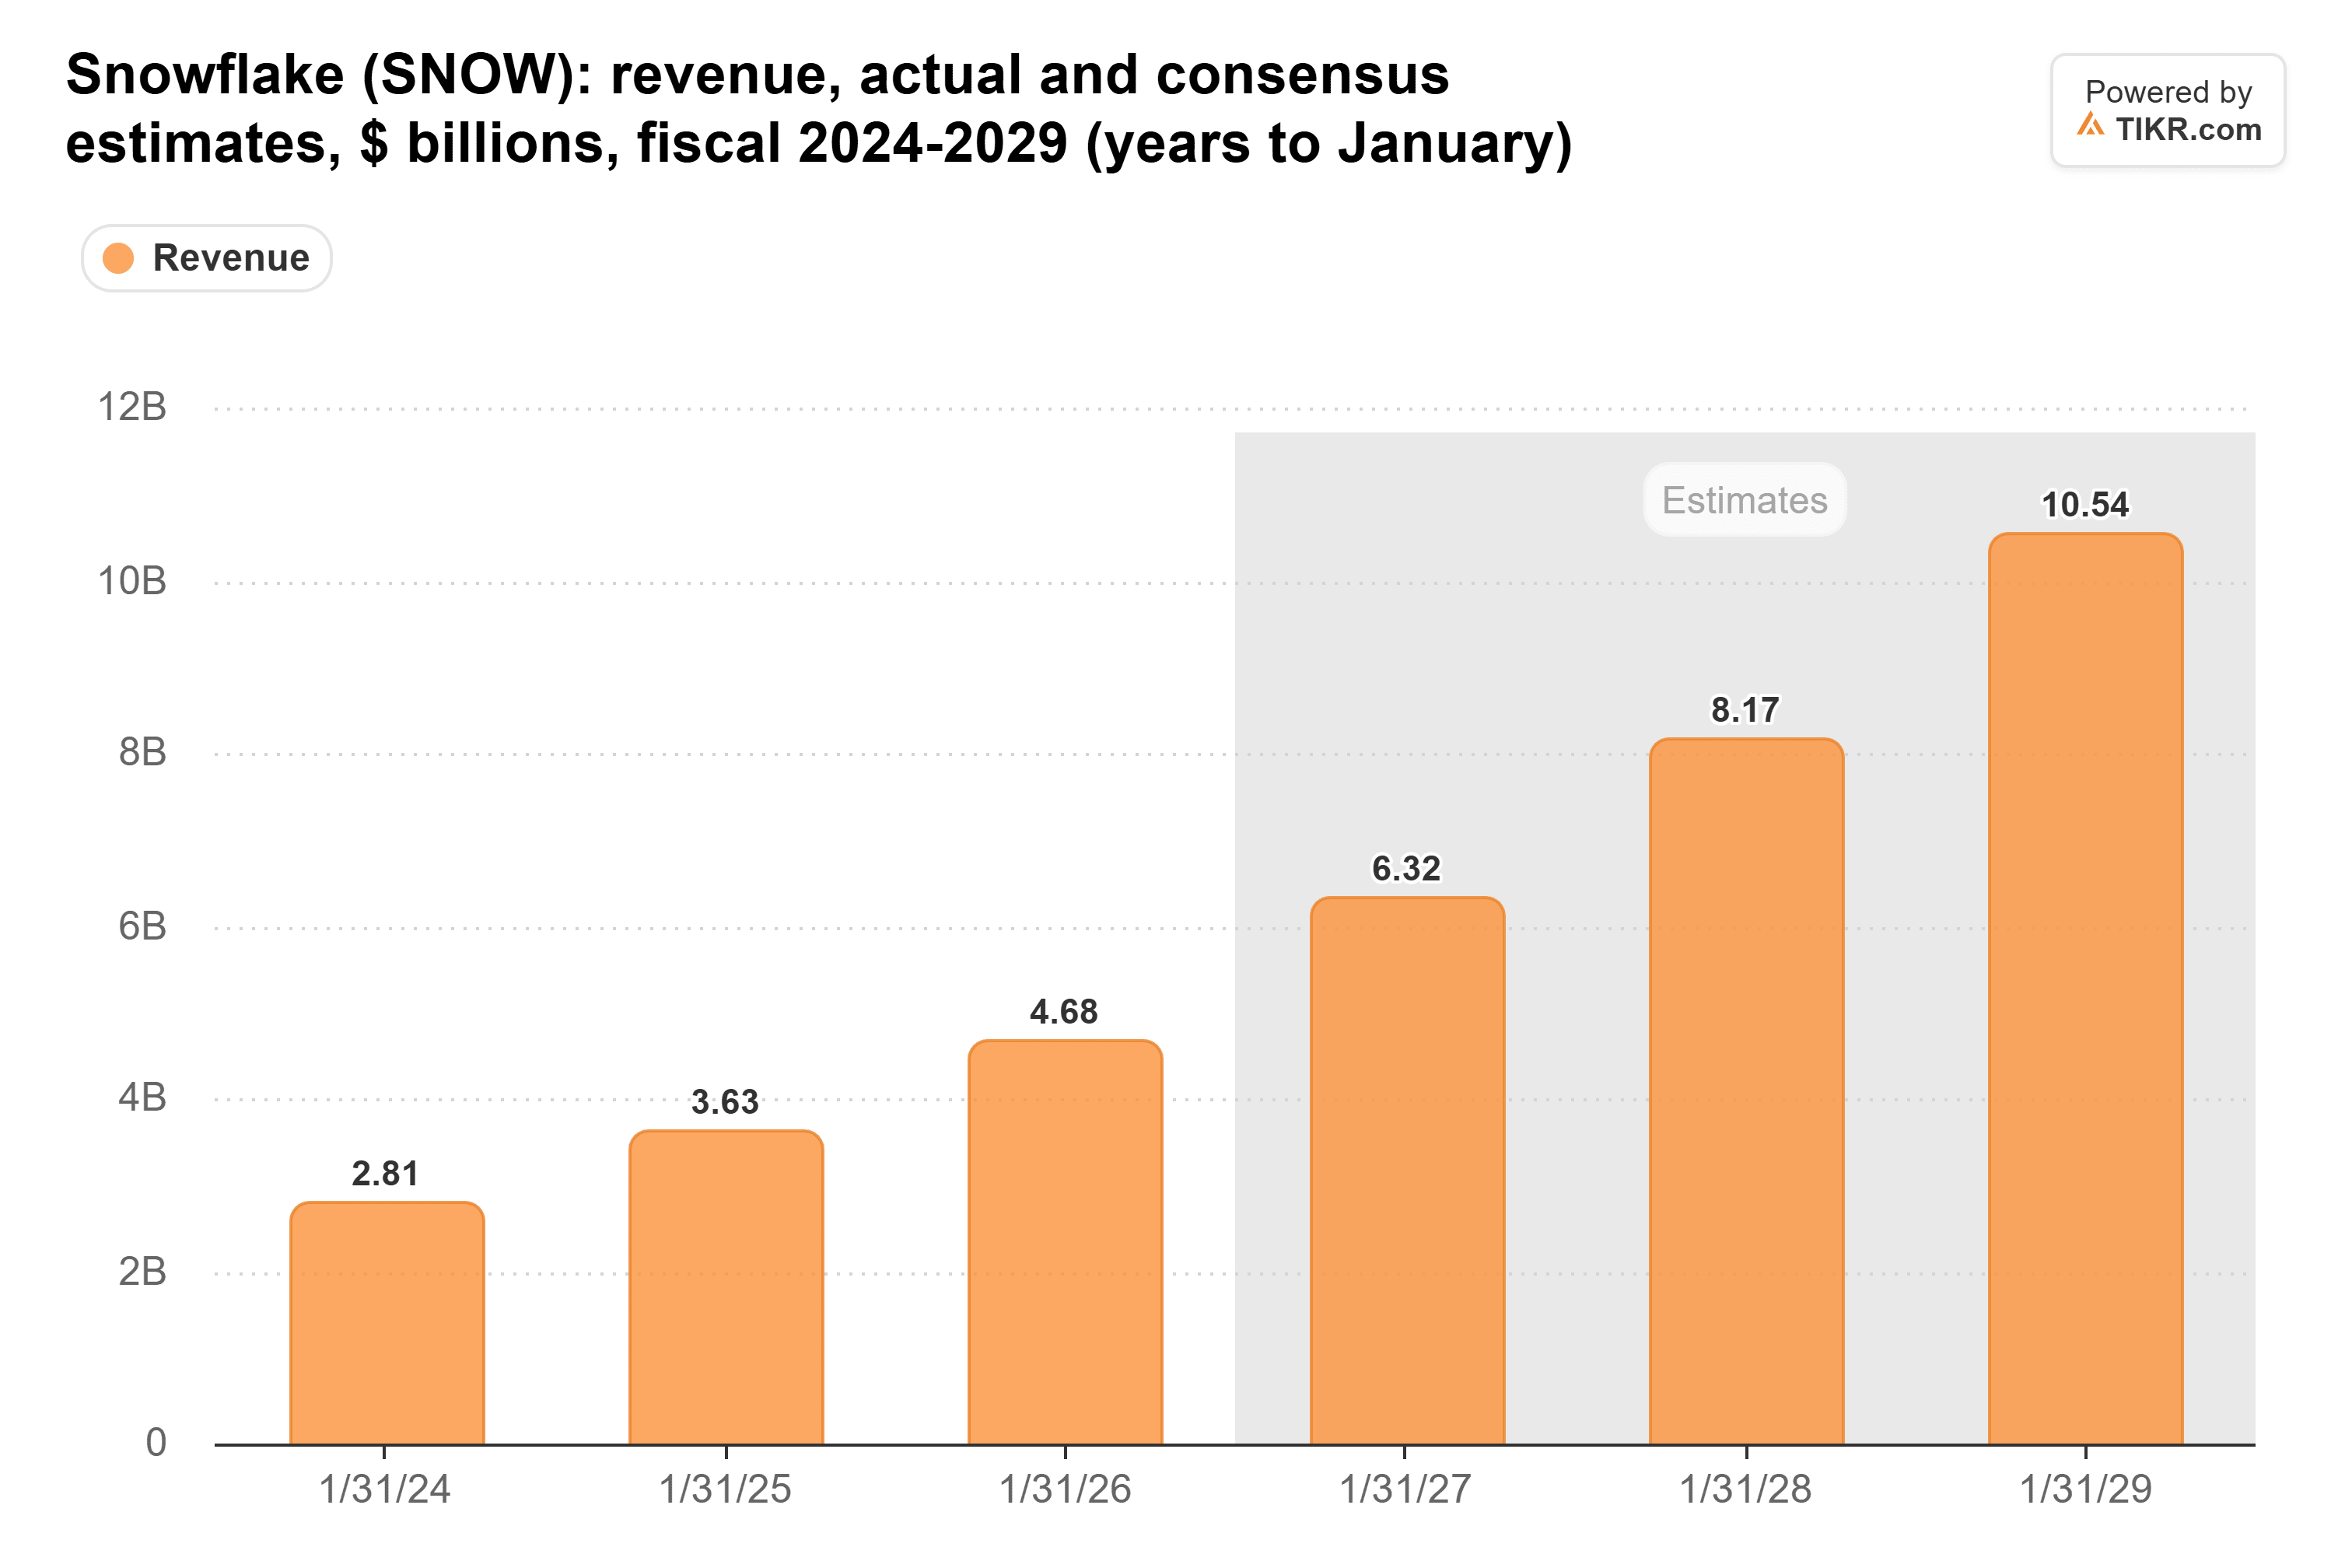
Analysts expect $6.32 billion of revenue for the year ending January 2027, up 35%, then 29% growth in each of the next two years. Nothing in this week’s analyst notes suggests those numbers will come down.
CrowdStrike reports on Dec. 1, so it gives the first read on Hedberg’s list. Last quarter, its net new ARR jumped 51% to a record $332.8 million. Cloudflare, also on his list, shows what fast AI growth can cost. Its third-quarter revenue rose 39%, its fastest growth in nearly four years, but its GAAP gross margin slipped to 71.2% from 74.0%.
Snowflake has the same risk. Its non-GAAP product gross margin fell to 74.7% last quarter from 76.4% a year earlier. Management also cut its full-year outlook for that margin to 74% from 75% as more of the business comes from AI workloads.
The dip comes with a discount
Snowflake traded at about 101x forward earnings going into Friday’s drop. That’s down from 115x when Evercore ISI raised its target a week earlier, and well below its three-year average of 165x. Over the past 90 days, analysts raised their normalized EPS estimate for the year ending January 2027 to $2.23 from $1.94, and for the year after to $3.06 from $2.70.
Bottom line: I’d buy this dip before Dec. 2. The stock got cheaper while estimates went up, and nothing changed at the company.
The report has to show three things. Product revenue should come in above the $1.593 billion top of the guide. Product gross margin should be 74% or higher. And the fourth-quarter guide should beat the roughly $1.65 billion that the full-year outlook implies. If the margin slips below 74%, this week’s drop may not be the last.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!