Key Takeaways
- Snap shares rose 7% after Deutsche Bank kept its Buy rating and $8 target, saying investors underrate its subscriptions.
- Paid subscribers rose 77% to about 30 million last quarter, bringing in about three-quarters of Snap’s added revenue.
- Meta Platforms, Pinterest and Reddit all grew revenue far faster than Snap’s ads, so the slowdown looks like Snap’s own.
- The stock looks cheap on forward earnings, though those exclude about $1 billion a year of stock pay.
Snap (SNAP) shares are up 7% today, after Deutsche Bank’s Benjamin Black argued last week’s post-earnings selloff missed what’s driving the business. His Nov. 10 note is titled “Better Than the Tape Suggests; Subs Mix and Earnings Power Matter.”
Reddit (RDDT) is up 7% too. But the note goes straight at Snap’s weak spot: its ad business barely grew last quarter, while Meta Platforms (META) and Pinterest (PINS) kept growing at double-digit rates.
30 million people now pay for Snapchat
Paid subscribers rose 77% to about 30 million in the third quarter, and other revenue, mostly subscriptions, jumped 84% to $350 million. Advertising grew just 4% to $1.37 billion. So subscriptions brought in about three-quarters of the revenue Snap added. Black wrote: “Subscriptions increasingly matter to both the quality of revenue and the margin story, yet we think this remains underappreciated by investors.”
Analysts expect revenue to keep climbing through 2028:
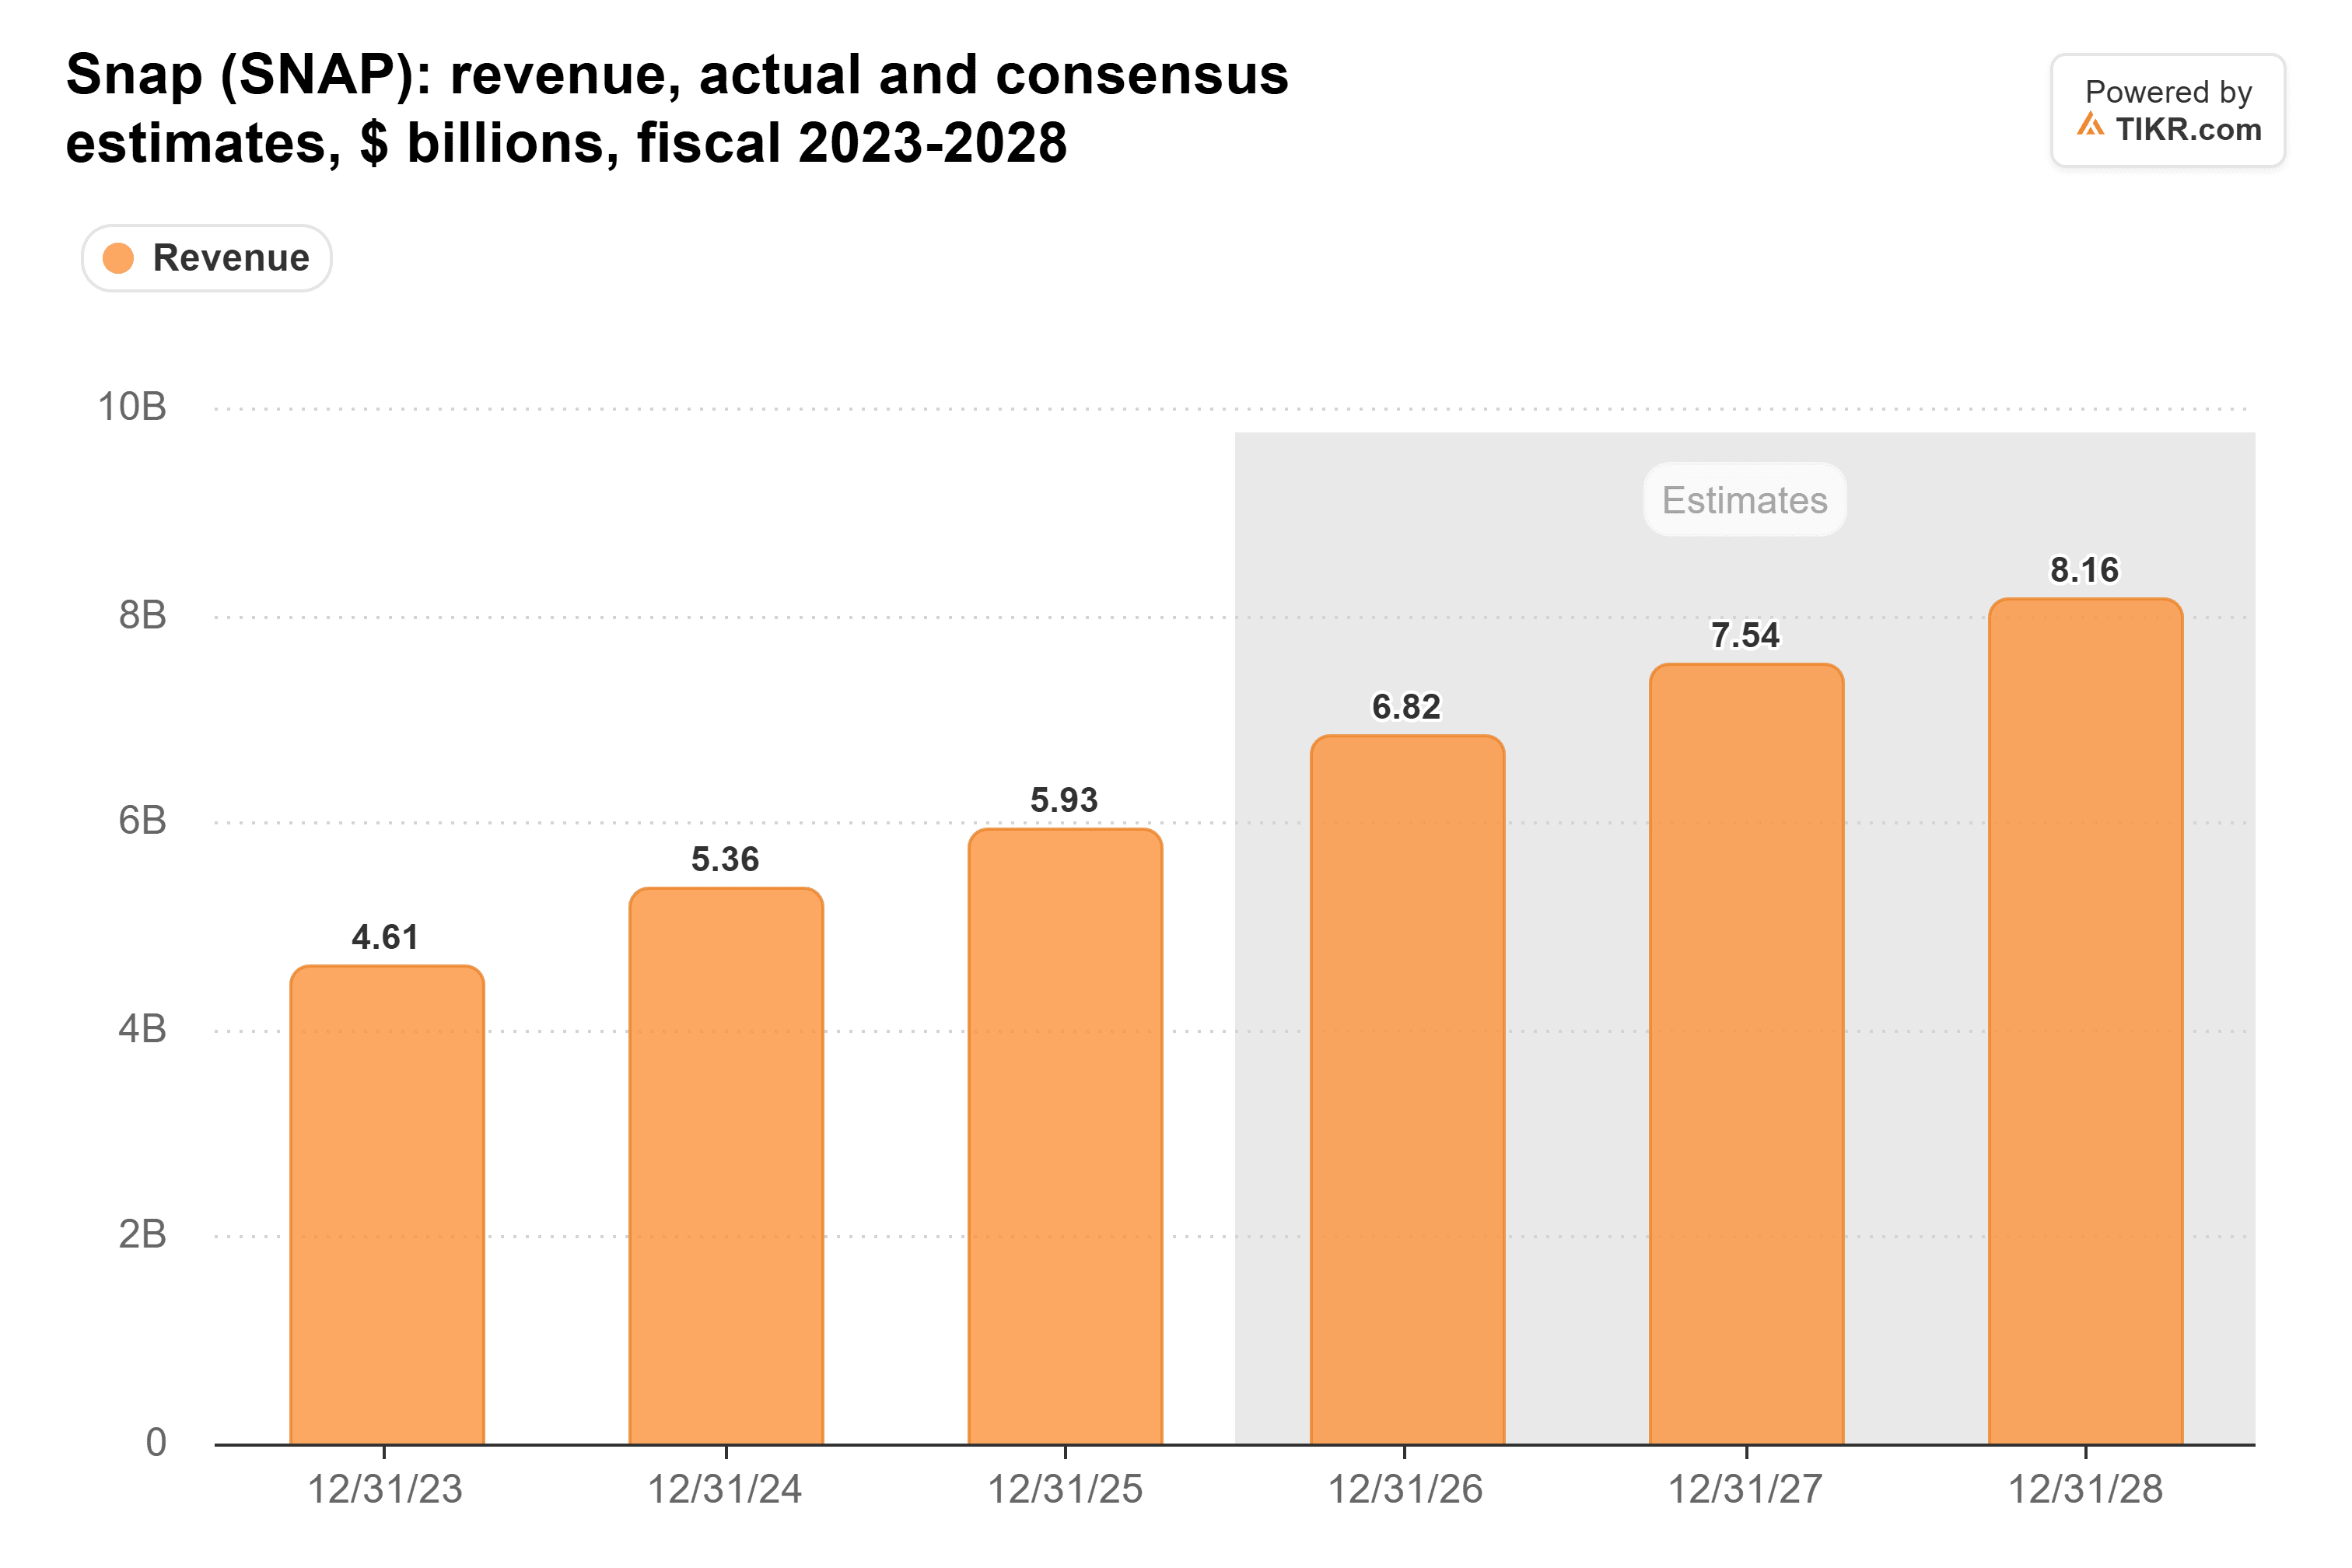
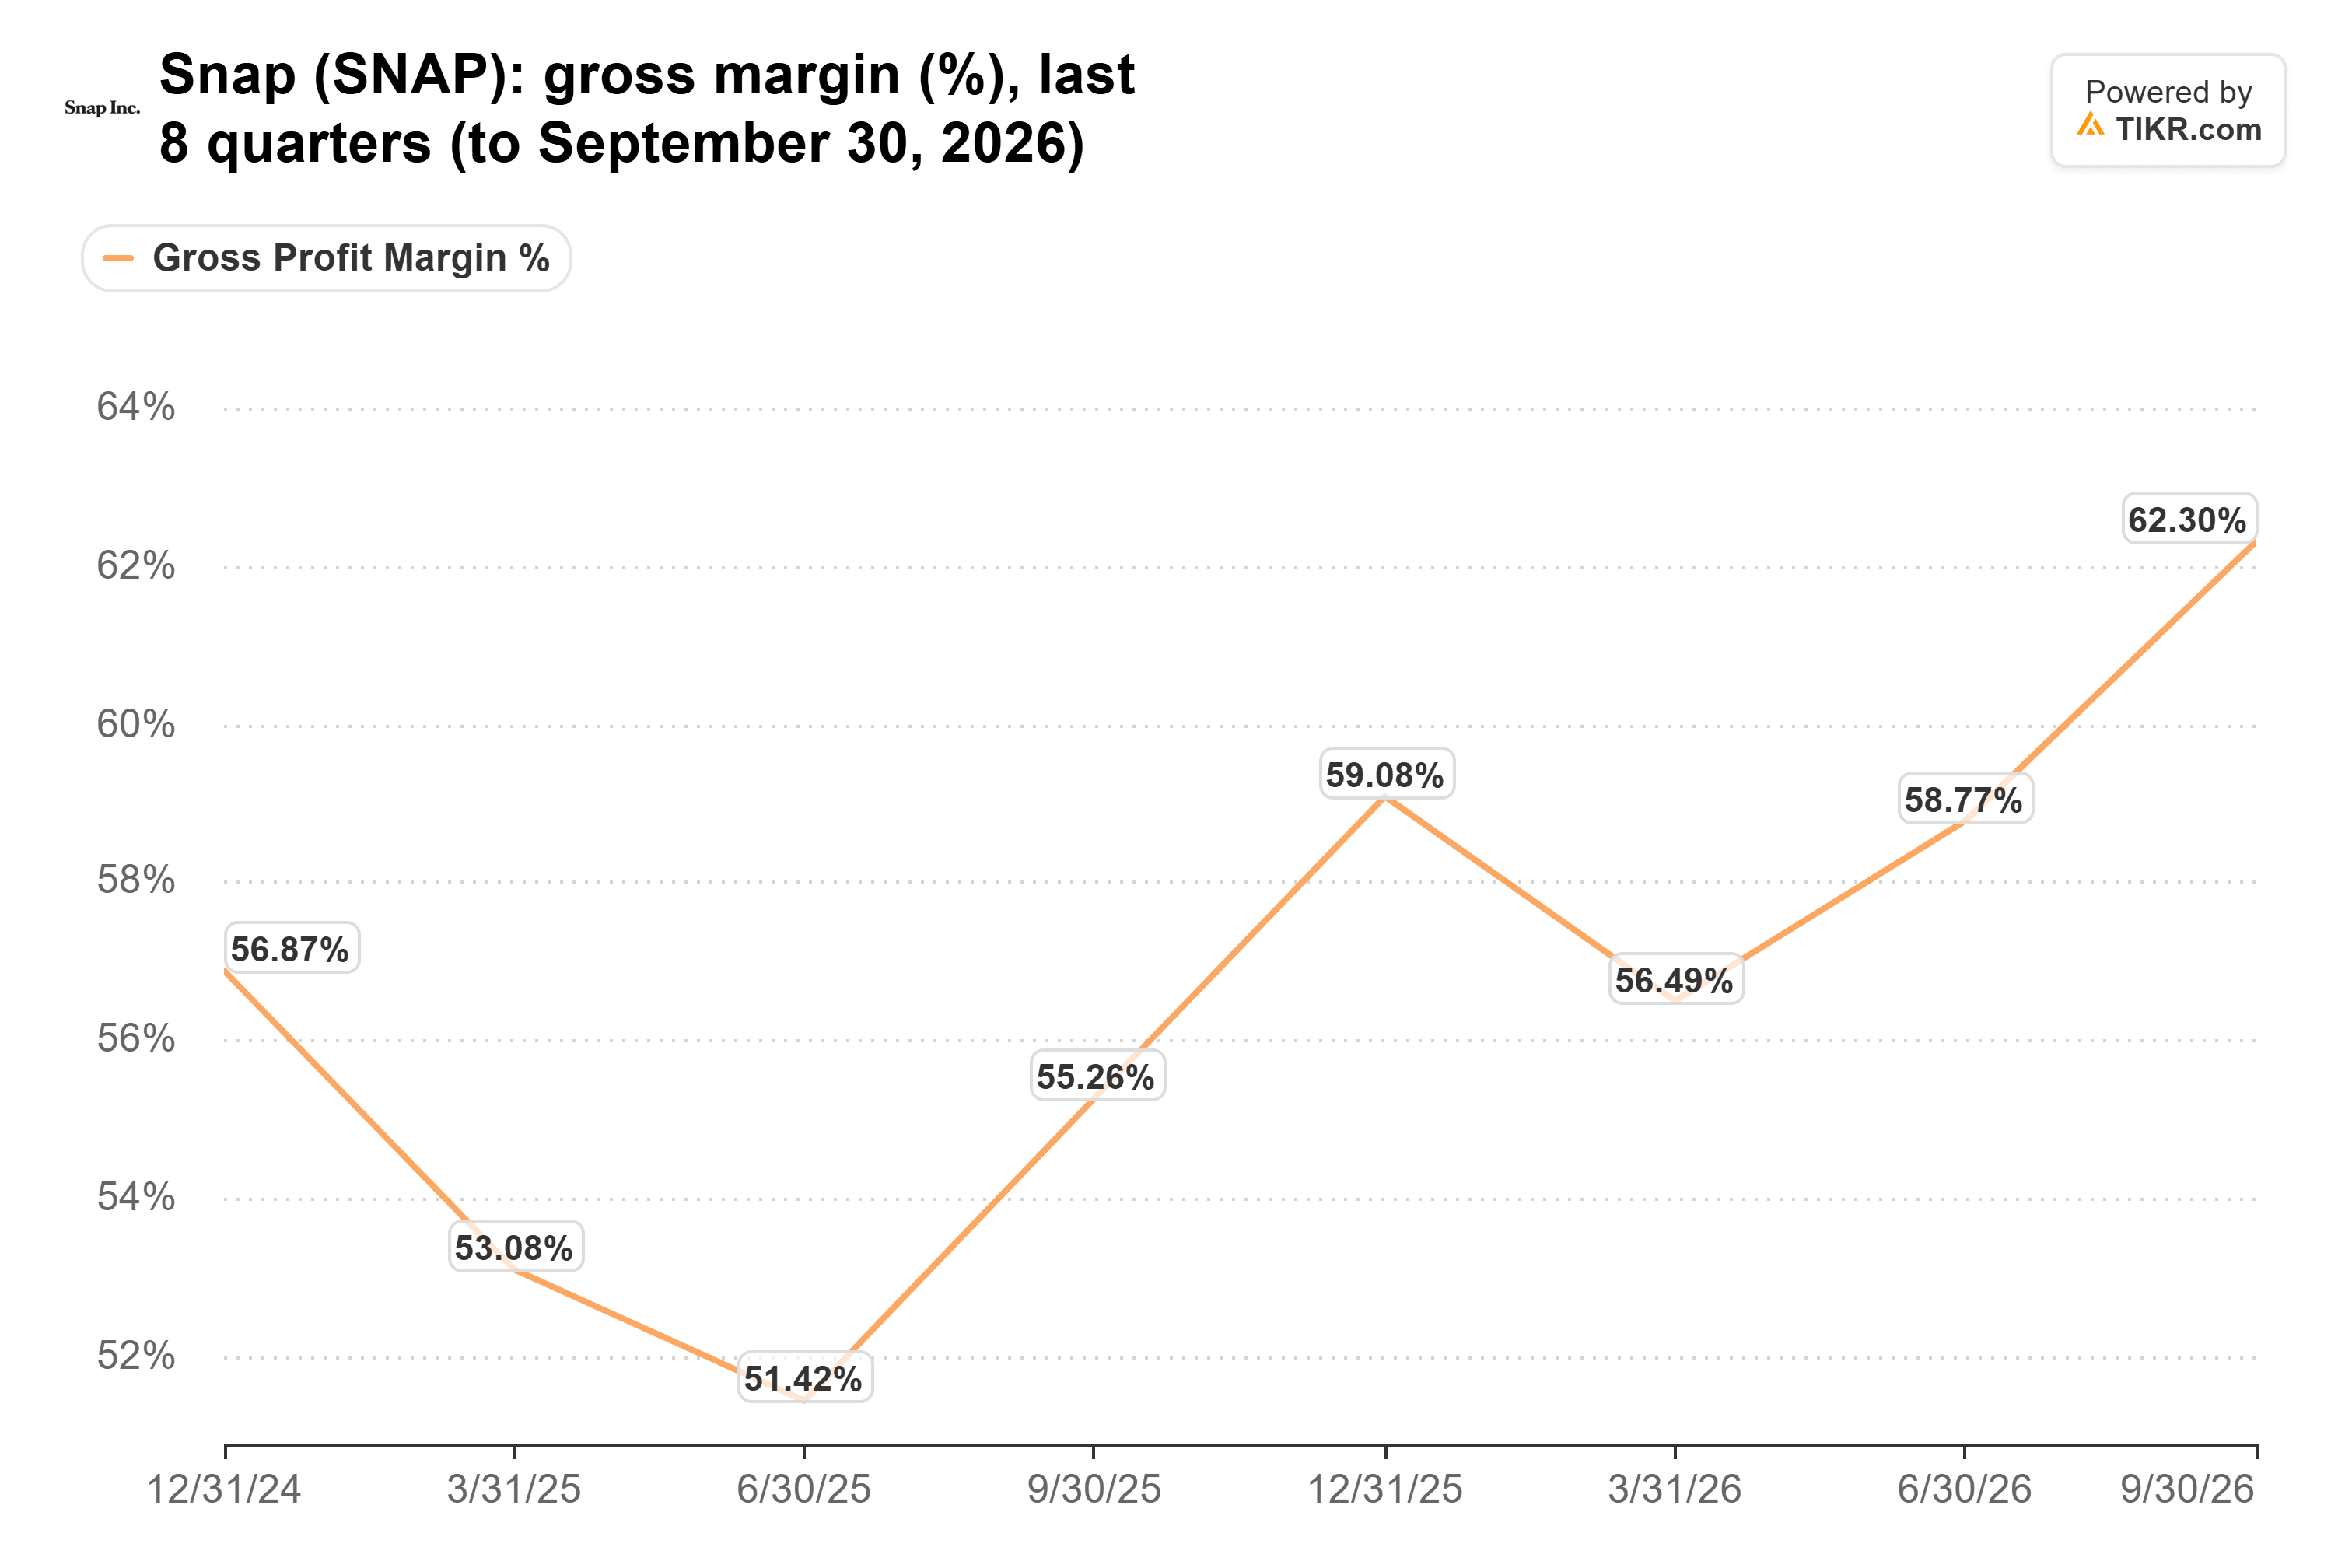
Black sees subscription revenue of about $1.81 billion in 2027, up about 35%, against consensus of roughly 11% growth for the whole company. Gross margin rose from 55.3% a year earlier to 62.3% in the third quarter.
Snap’s ad problem is its own
North American daily users fell 6% to 92 million.
Rivals aren’t seeing the same thing. Meta grew third-quarter revenue 26% to $64.6 billion. Pinterest grew 12%. And Reddit grew revenue 53% as its daily users rose 12%. Advertisers are still spending, just less with Snap, which is why subscriptions matter so much.
TIKR tracks 41 analysts on Snap. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snap, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snap’s Analyst Ratings
Cheap, with one big caveat
Black’s $8 target is about 60% above Snap’s close before today’s jump. The stock traded at 6.6x forward earnings at the last close, well under its one-year average of about 12x. But those normalized earnings leave out roughly $1.05 billion of stock pay this year.
I think Deutsche Bank has this right: at about 7x earnings, Snap doesn’t need much from ads while subscriptions grow over 80% and margins rise.
Of course, Snap will stop reporting daily users with its first-quarter 2027 results, which makes fourth-quarter results in early February the next real check on ads.
So what is Snap stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snap could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!