Key Takeaways
- Snap will switch its main audience metric from daily to monthly users in 2027, after third-quarter daily users of 495 million missed estimates.
- Revenue rose 14% to $1.72 billion, slightly light, but Snap swung to a $56 million profit from a $104 million loss.
- Snap’s advertising grew 4%, while Meta’s advertising revenue jumped 26% to $63.1 billion in the same quarter.
- Snap’s early February report must show ad growth picking up alongside fourth-quarter adjusted EBITDA guided to $490 million to $525 million.
Snap (SNAP) is changing how it keeps score. Starting with the first quarter of 2027, monthly active users replace daily users as its headline audience number.
The switch arrived next to a miss. Third-quarter daily users came in at 495 million against the 499 million analysts expected, and North American daily users fell 6% to 92 million.
Advertising is the wider gap. Snap’s ad revenue grew 4% last quarter, while Meta Platforms (META) grew advertising 26% to $63.1 billion over the same three months.
Shares closed Friday at $4.96, down 39% this year.
Fewer daily users, more profit
Here’s the quarter Snap reported on Nov. 4:
- Revenue rose 14% to $1.72 billion, a touch below the roughly $1.73 billion consensus.
- Net income came in at $56 million, or $0.03 a share, against a $104 million loss a year earlier.
- Adjusted EBITDA climbed to $383 million from $182 million.
Management tied the new metric to a push for more profitable growth, with less money spent buying daily users.
North America shows why that matters. It holds 19% of Snap’s daily users yet produces 59% of revenue, and its daily count peaked at 101 million in 2023.
Monthly users rose 4% to 977 million, so the new headline number starts within sight of a billion. And sales kept rising through the user slump…
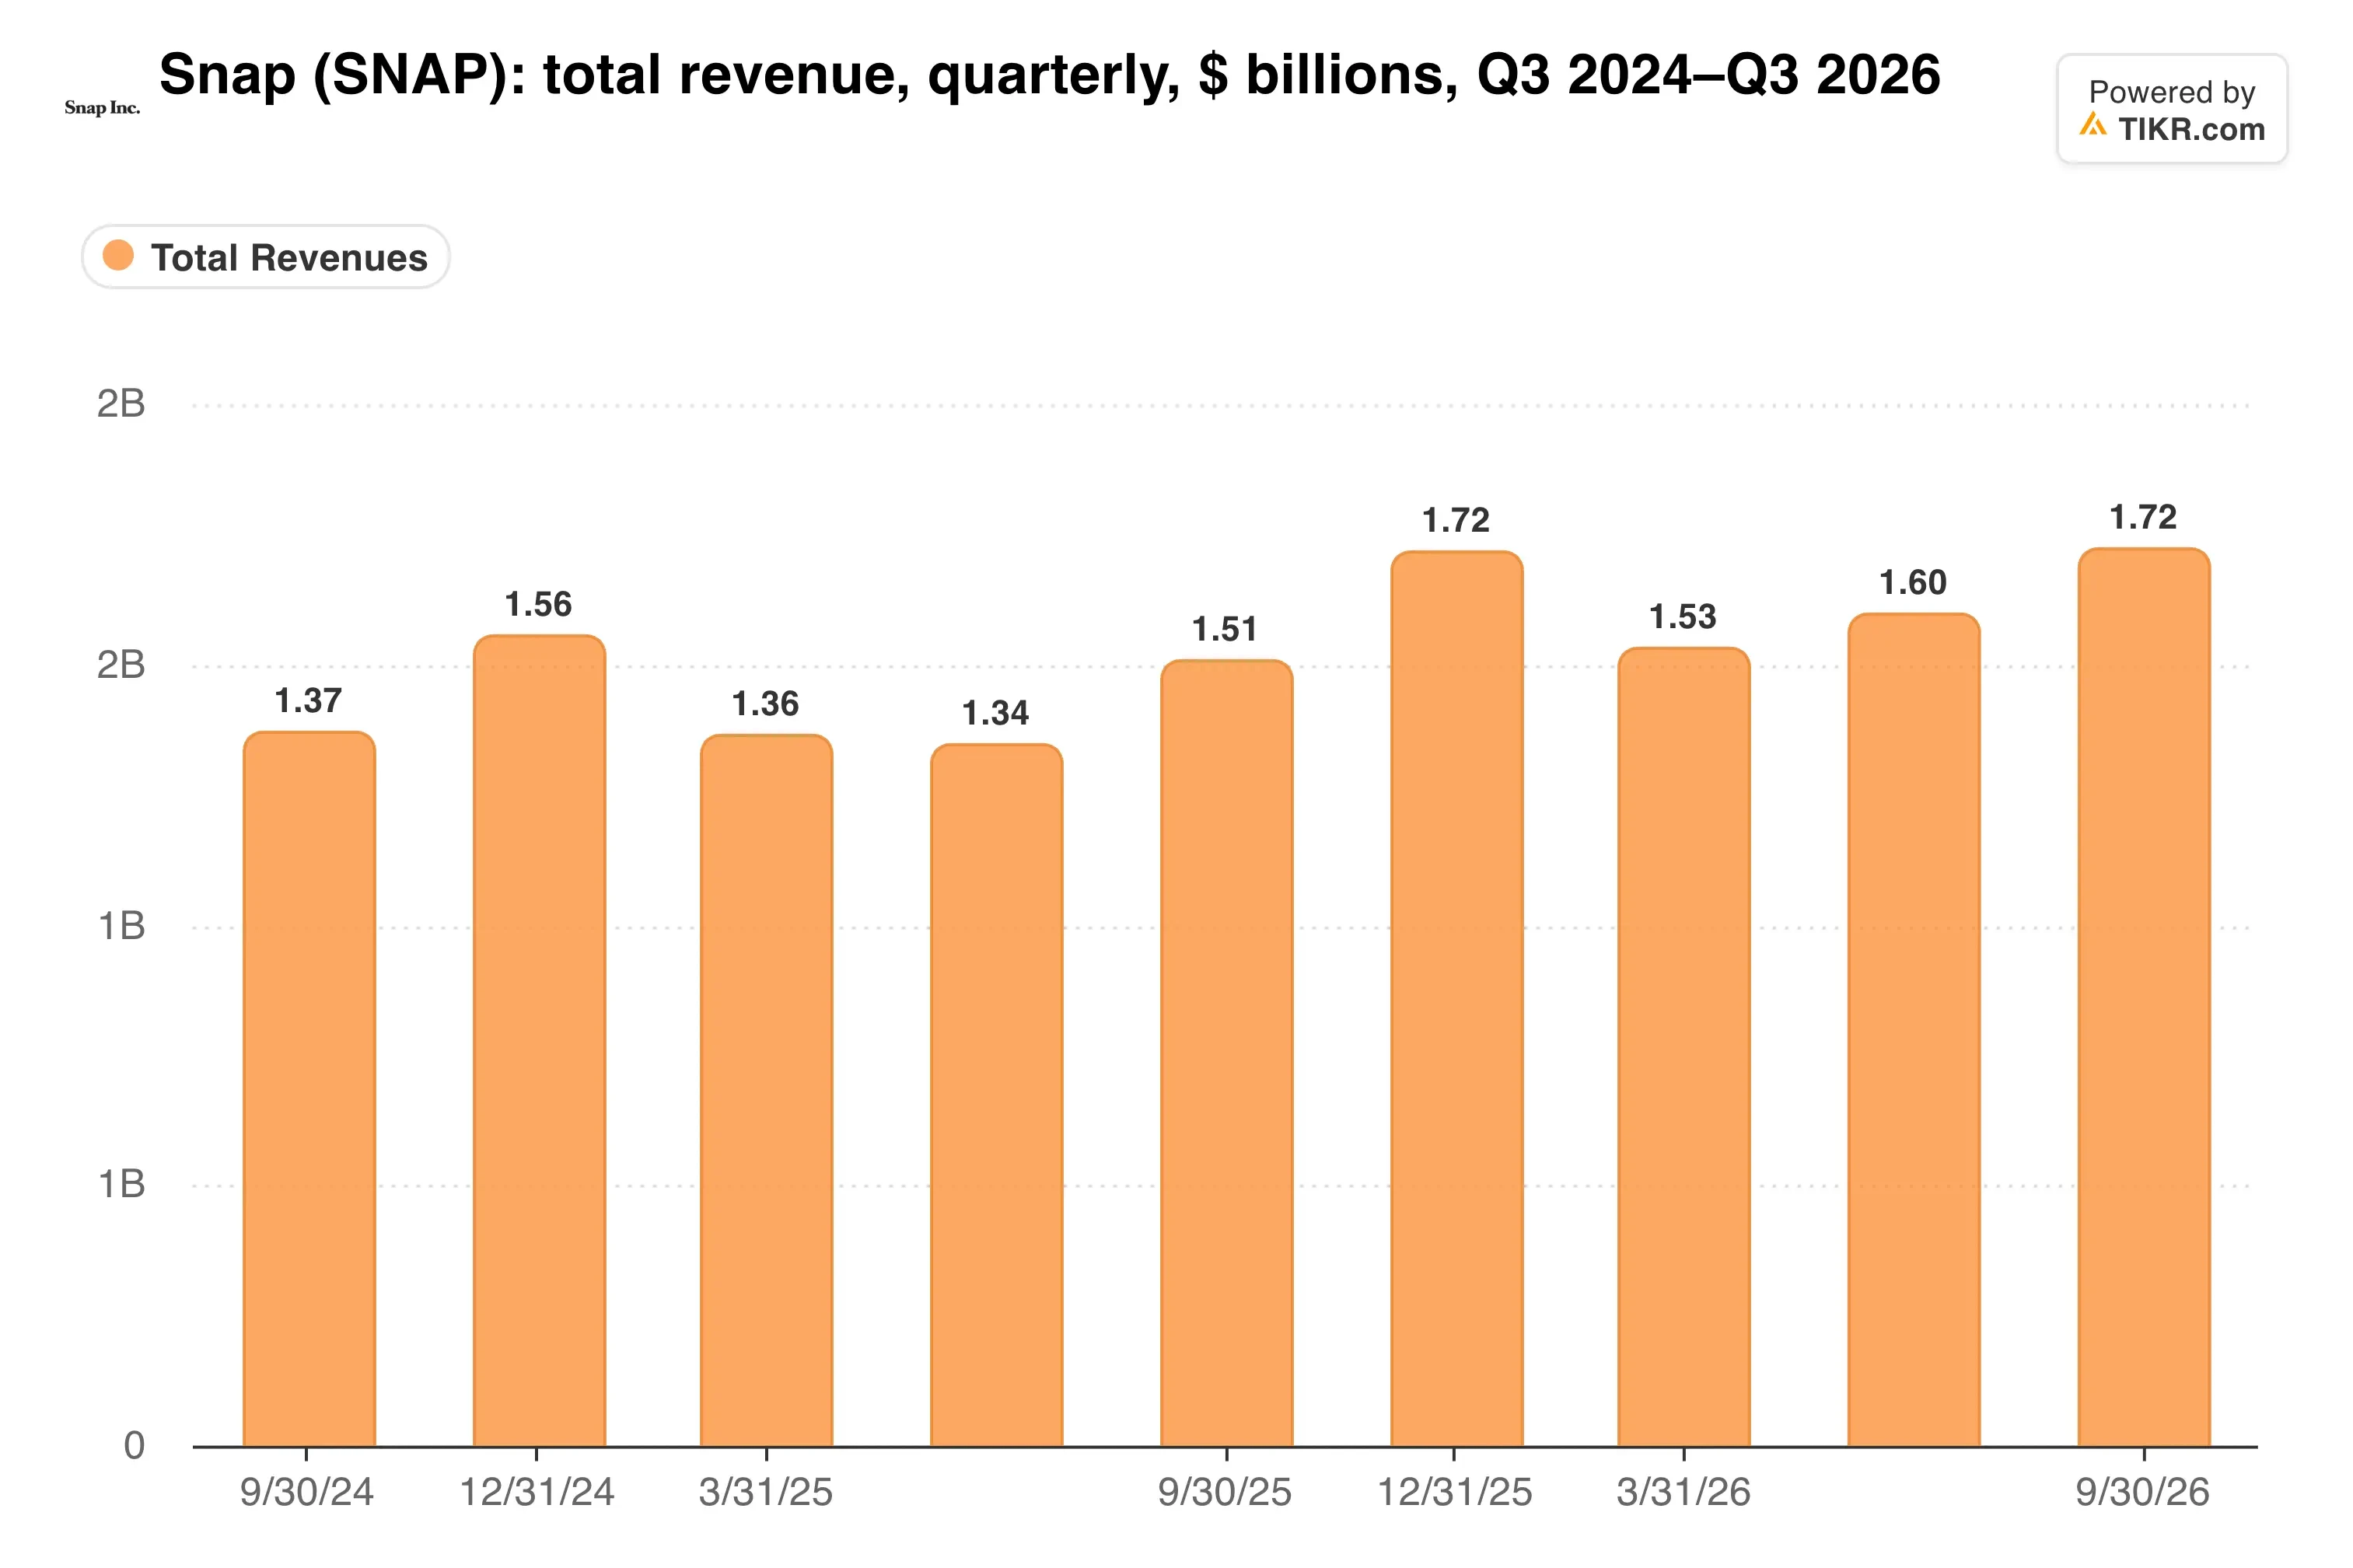
Growth did slow, though, to 14% from 19% in the second quarter.
Subscriptions are paying the bills
Other revenue, mostly subscriptions, jumped 84% to $350 million, and paid subscribers passed 30 million.
CEO Evan Spiegel said in the results release that “AI is becoming a significant advantage for our teams and advertising platform.” Meta can point to proof: its ad prices rose 14% and impressions 10%. Snap’s ad line grew 4%.
Costs are the cleaner win. Total costs and expenses rose under 1% to $1.65 billion while revenue added $216 million. Where does that leave margins?
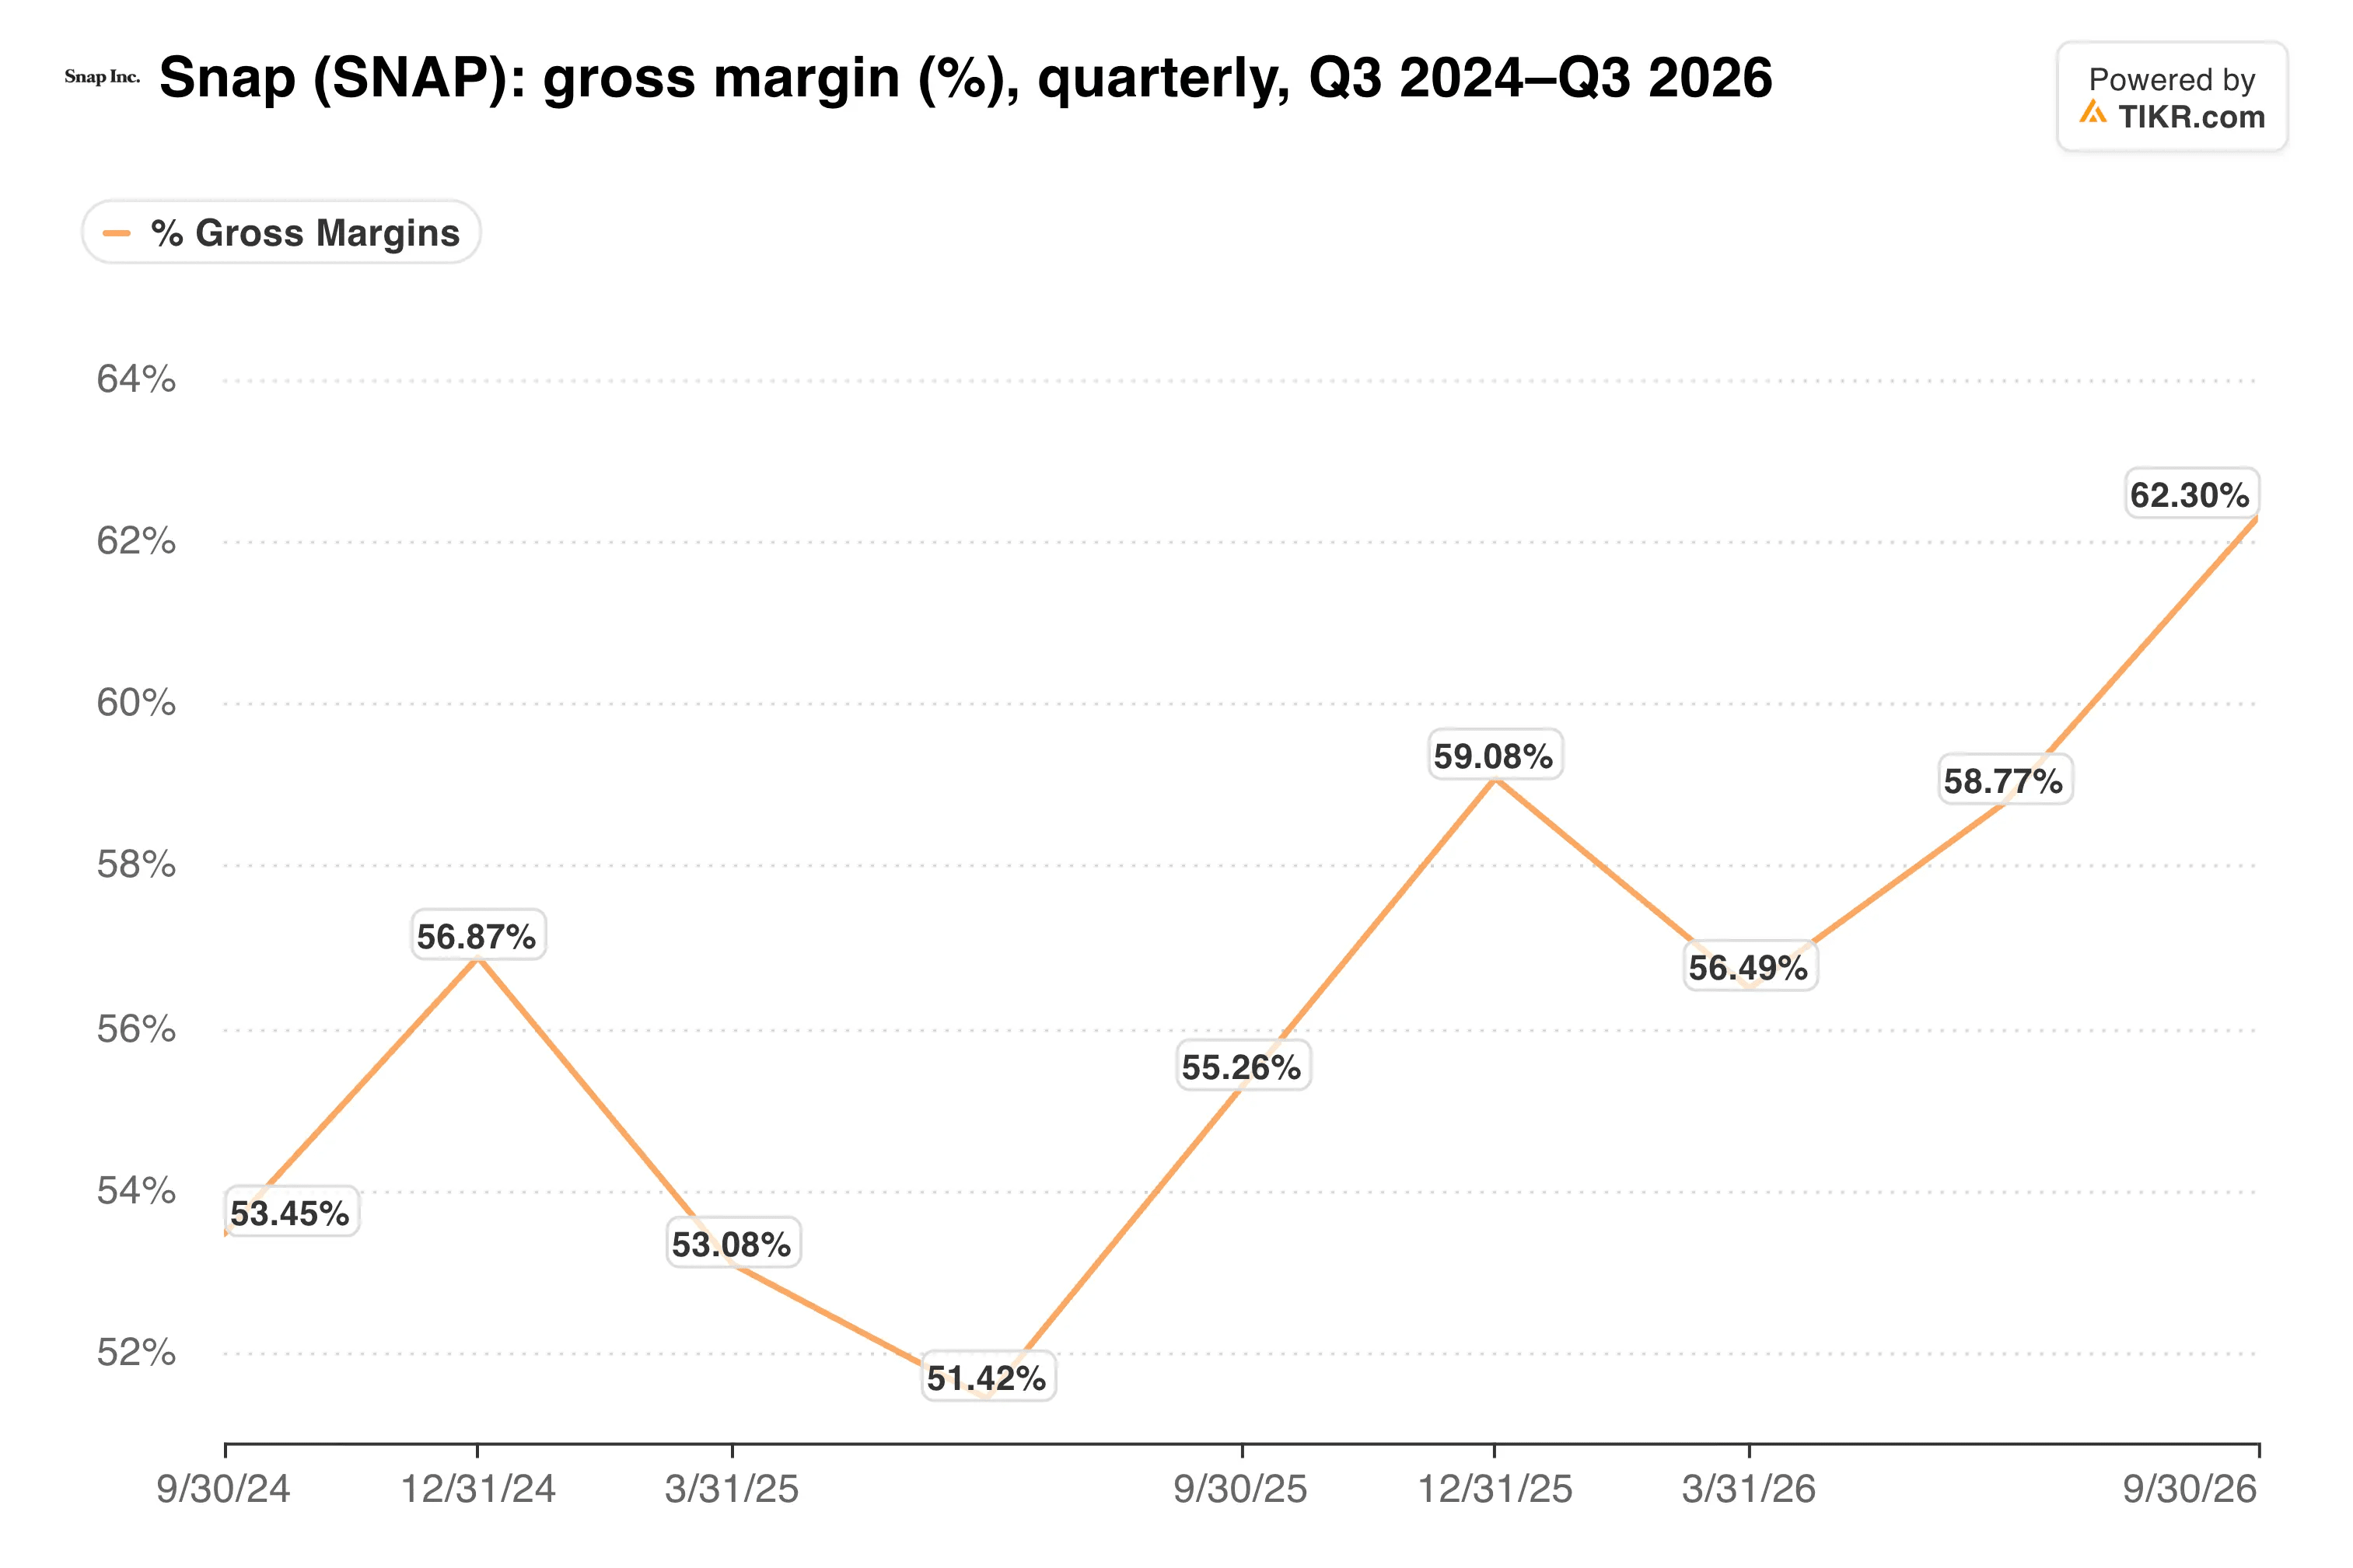
Subscription dollars carry richer margins, which helps explain how EBITDA doubled on 14% growth.
Snap guided fourth-quarter revenue to $1.95 billion to $1.985 billion and adjusted EBITDA to $490 million to $525 million. The revenue midpoint sits slightly above the $1.948 billion consensus.
TIKR tracks 42 analysts on Snap. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snap, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snap’s Analyst Ratings
A cheap stock with legal baggage
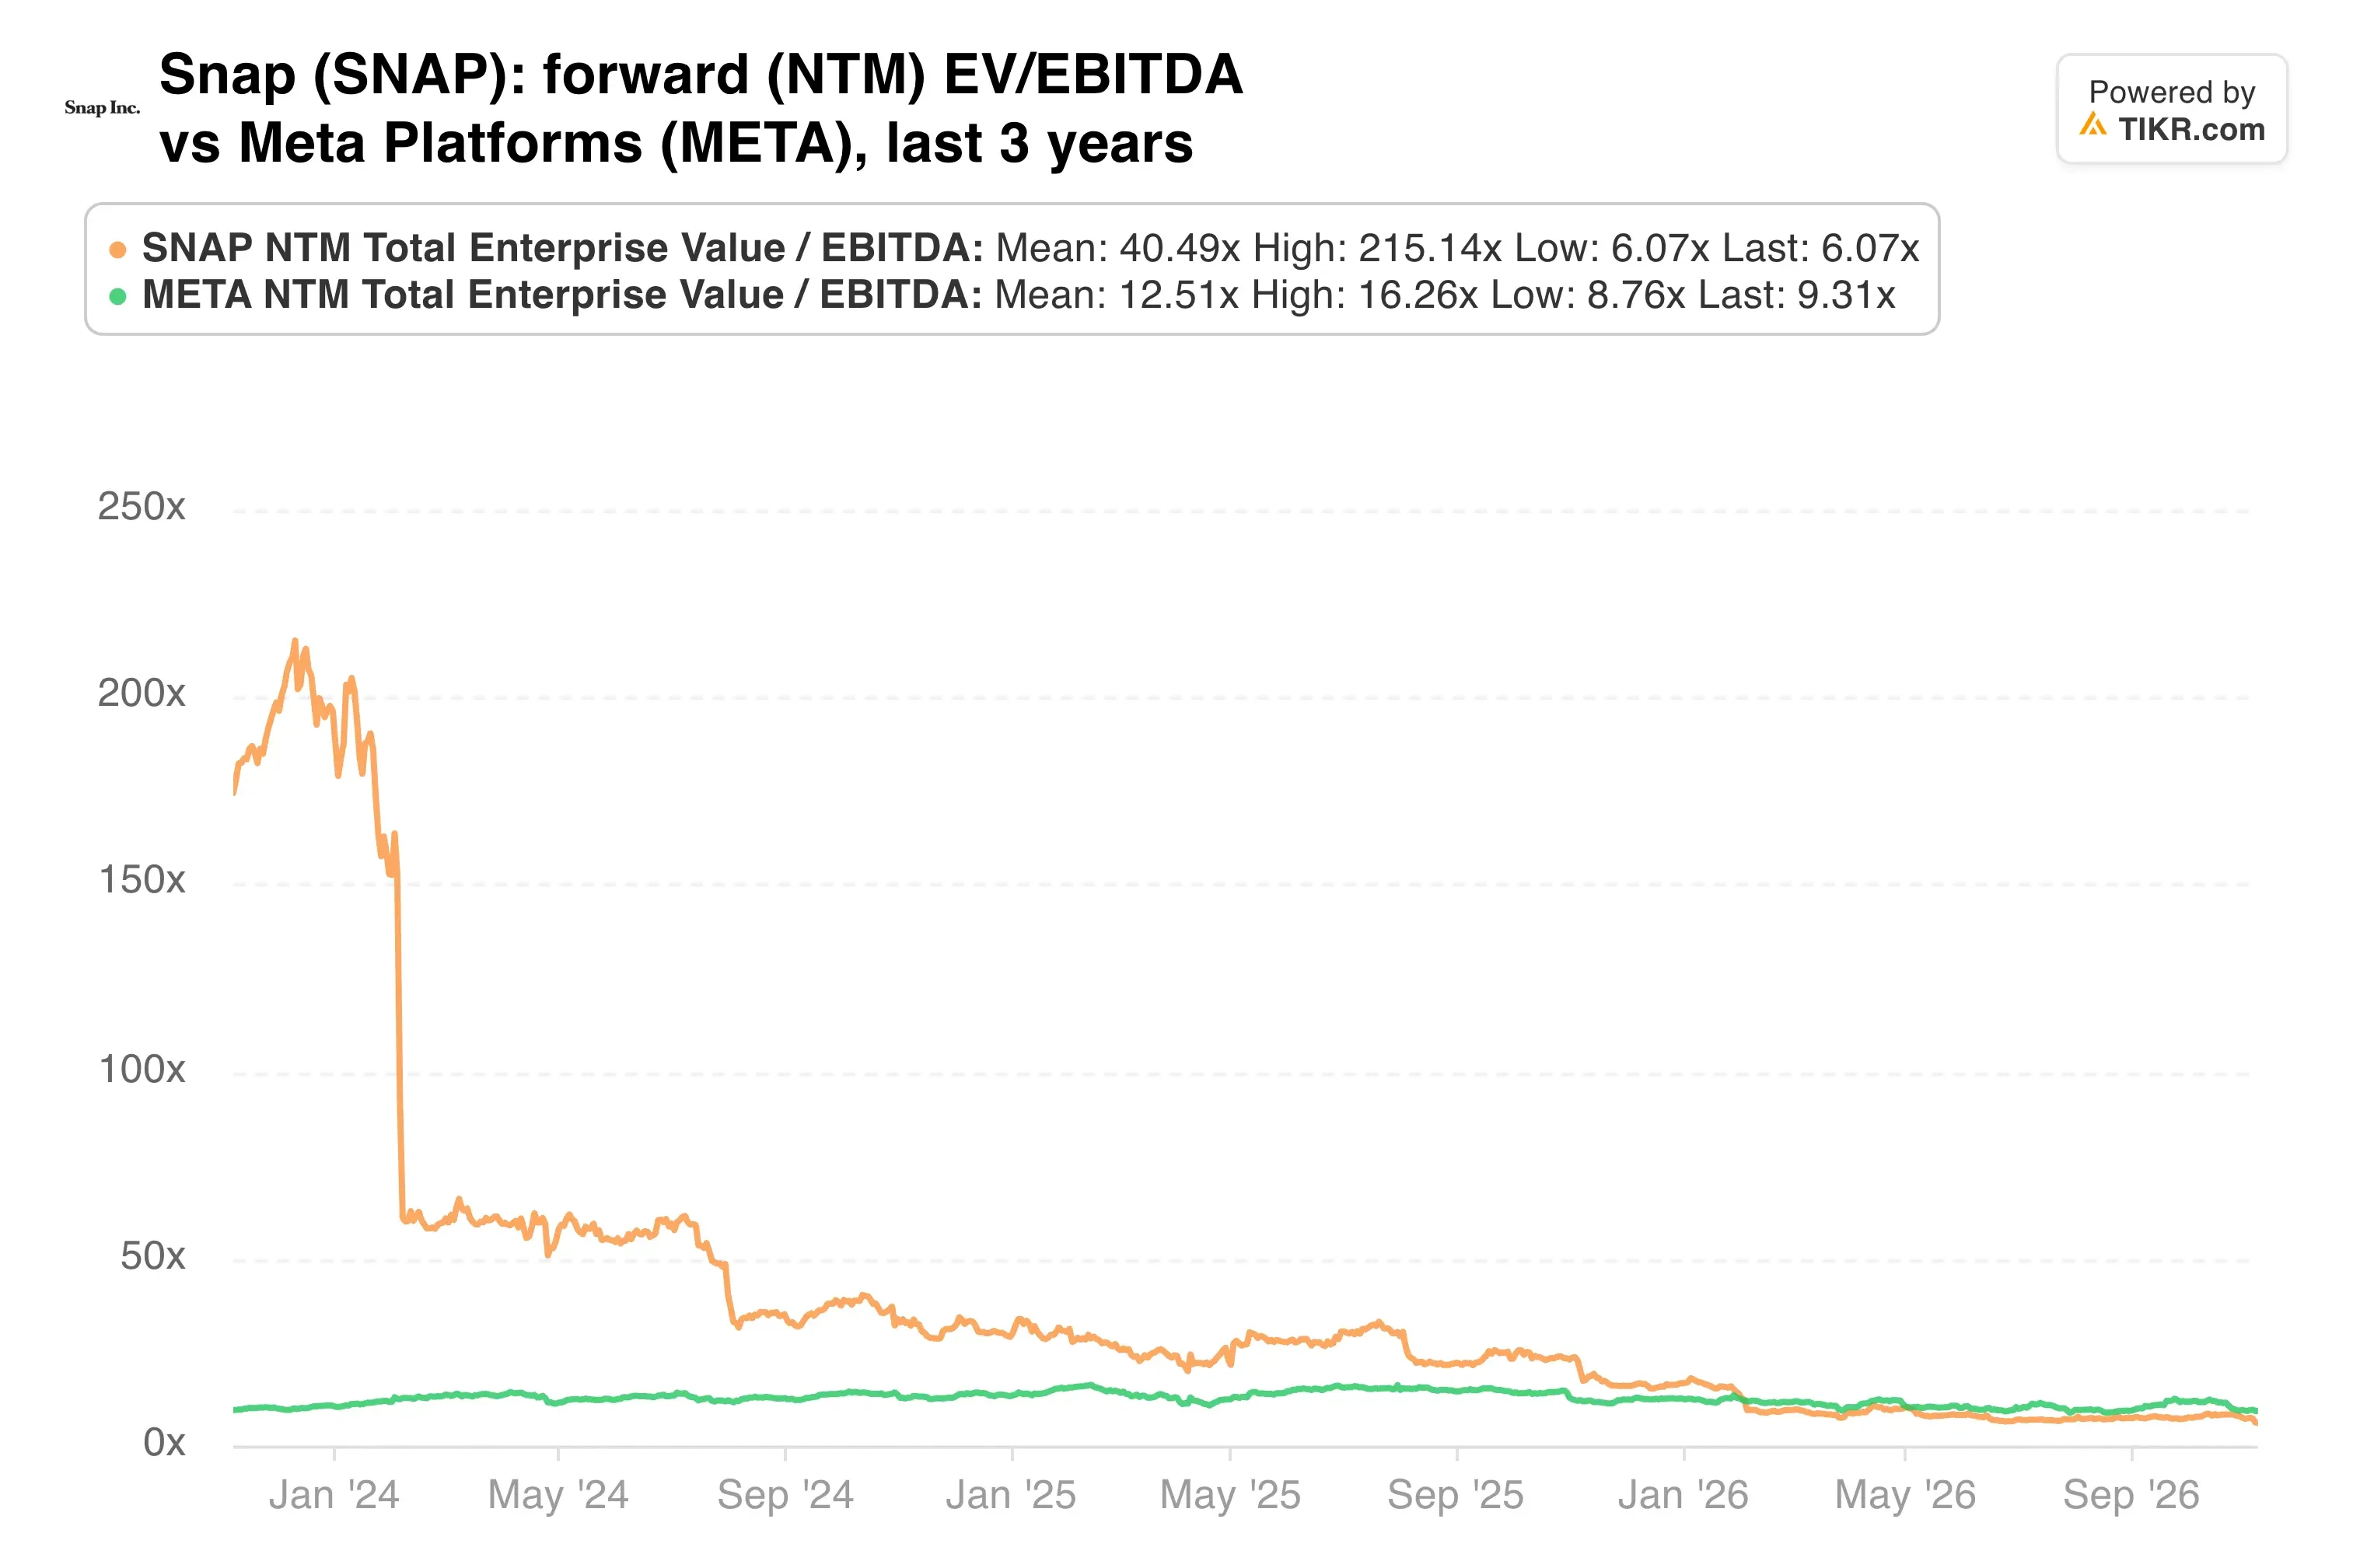
The company trades at 6.1x forward EBITDA and 6.4x forward earnings, a steep discount to the ad leader it shares a courtroom with.
Snap and Meta both faced the first major U.S. trial testing claims that social media caused teen depression and eating disorders. Meta settled with its plaintiff on Oct. 30, and Snap settled with two teens on Nov. 2. More than 3,000 related lawsuits are still moving through the courts.
Regulators keep pressing too. In the UK, the regulator said Snapchat has started disabling its friend-finder feature for children.
Dilution is a quieter cost. Shares outstanding plus stock awards reached 1.93 billion, up from 1.86 billion a year earlier.
My take: at 6x EBITDA with a GAAP profit, Snap is cheap, and the Street’s $7.10 average target implies 43% upside. Retiring the daily user count right after missing it still makes this a show-me story, so I’d keep any position small until advertising grows faster than 4%.
The fourth-quarter report, expected in early February, is the next checkpoint. Revenue near the $1.985 billion top of the guide, with ad growth back near double digits, would make the switch to monthly users look strategic.
So what is Snap stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snap could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!