Key Takeaways
- Costco declared a $30-a-share special dividend worth about $13.3 billion, double its last special in December 2023. It also renewed its $4 billion buyback.
- The payout shows Costco makes more cash than it can reinvest: free cash flow was $9.4 billion in fiscal 2026, nearly four times its regular dividends.
- Investors pay a premium for that safety: Costco trades at about 47x forward earnings, against a 10-year average of 37x, and Walmart has moved less with the market over five years.
- The business still looks like a good place to shelter, but a return to its average multiple would cost the stock about 20%. That makes it a hold for owners and a stock to wait on for new money.
Costco Wholesale (COST) declared a $30-a-share special dividend after the close on Nov. 10, a payout of about $13.3 billion, and renewed its $4 billion buyback.
Barron’s ran the news under the headline “Costco Stock Is a Good Place to Shelter From the AI Chaos.” Investors have been doing just that: the stock is up 25% in 2026.
But shelter has gotten pricey. Charlie Bilello set Costco’s trailing P/E beside those of Walmart (WMT) and Nvidia on X last week and asked: “Which one is the bubble?” (Costco’s, at about 51x, was the highest of the three.)
Double the last special
The $30 is payable Dec. 4 to shareholders of record on Nov. 24. It’s double Costco’s last special, $15 a share in December 2023, and about five times its regular dividend of $5.88 a year. The new $4 billion buyback runs to November 2030 and replaces a program under which Costco had bought $3.1 billion of stock. It’s small for a company this size: Costco spent $847 million on its own shares in fiscal 2026, less than the $924 million of stock-based compensation it paid.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
The business has earned the label
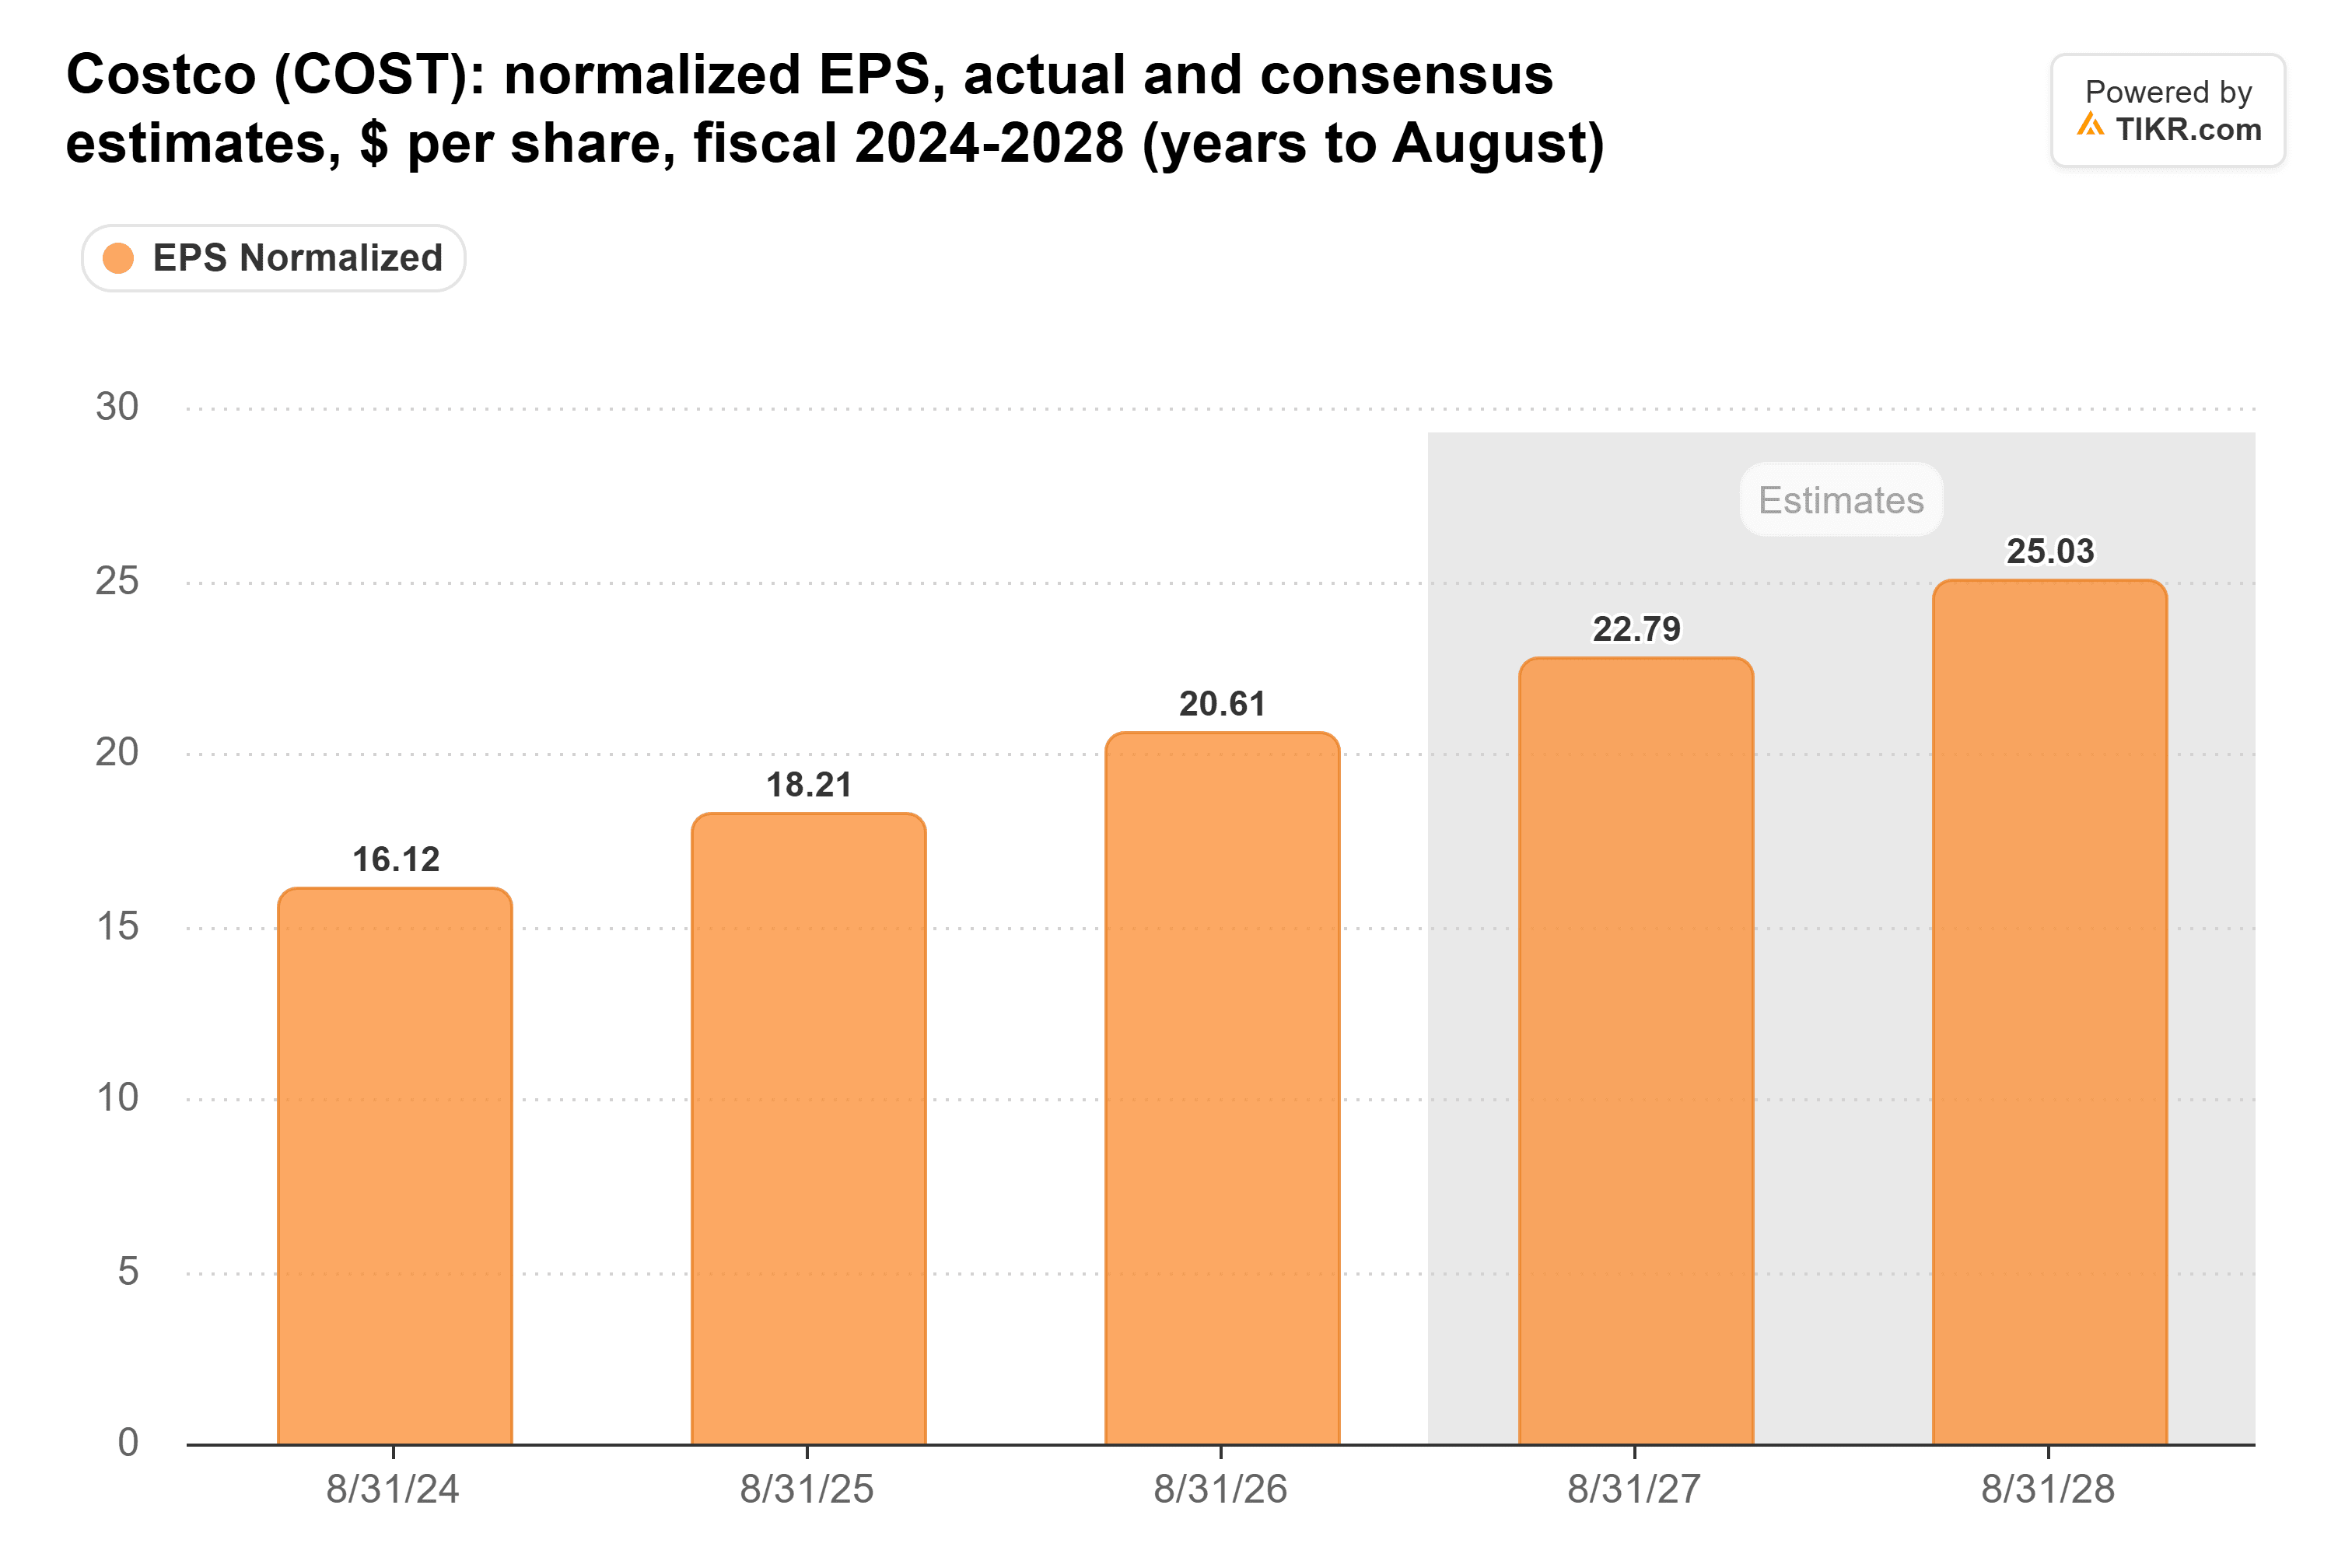
Costco’s business does look built for rough markets. Its U.S. and Canada renewal rate ended fiscal 2026, the year to August, at 92.3%. Comparable sales excluding gas and currency rose between 6.4% and 6.7% in every quarter. Membership fees of $5.9 billion made up half of its $11.7 billion of operating income. Analysts expect that steadiness to keep normalized EPS climbing about 10% a year through fiscal 2028:
The special comes from a cash machine that keeps outrunning Costco’s needs. Free cash flow nearly tripled, from $3.5 billion in fiscal 2022 to $9.38 billion in fiscal 2026, which is also its latest four quarters. Regular dividends took just 26% of it:
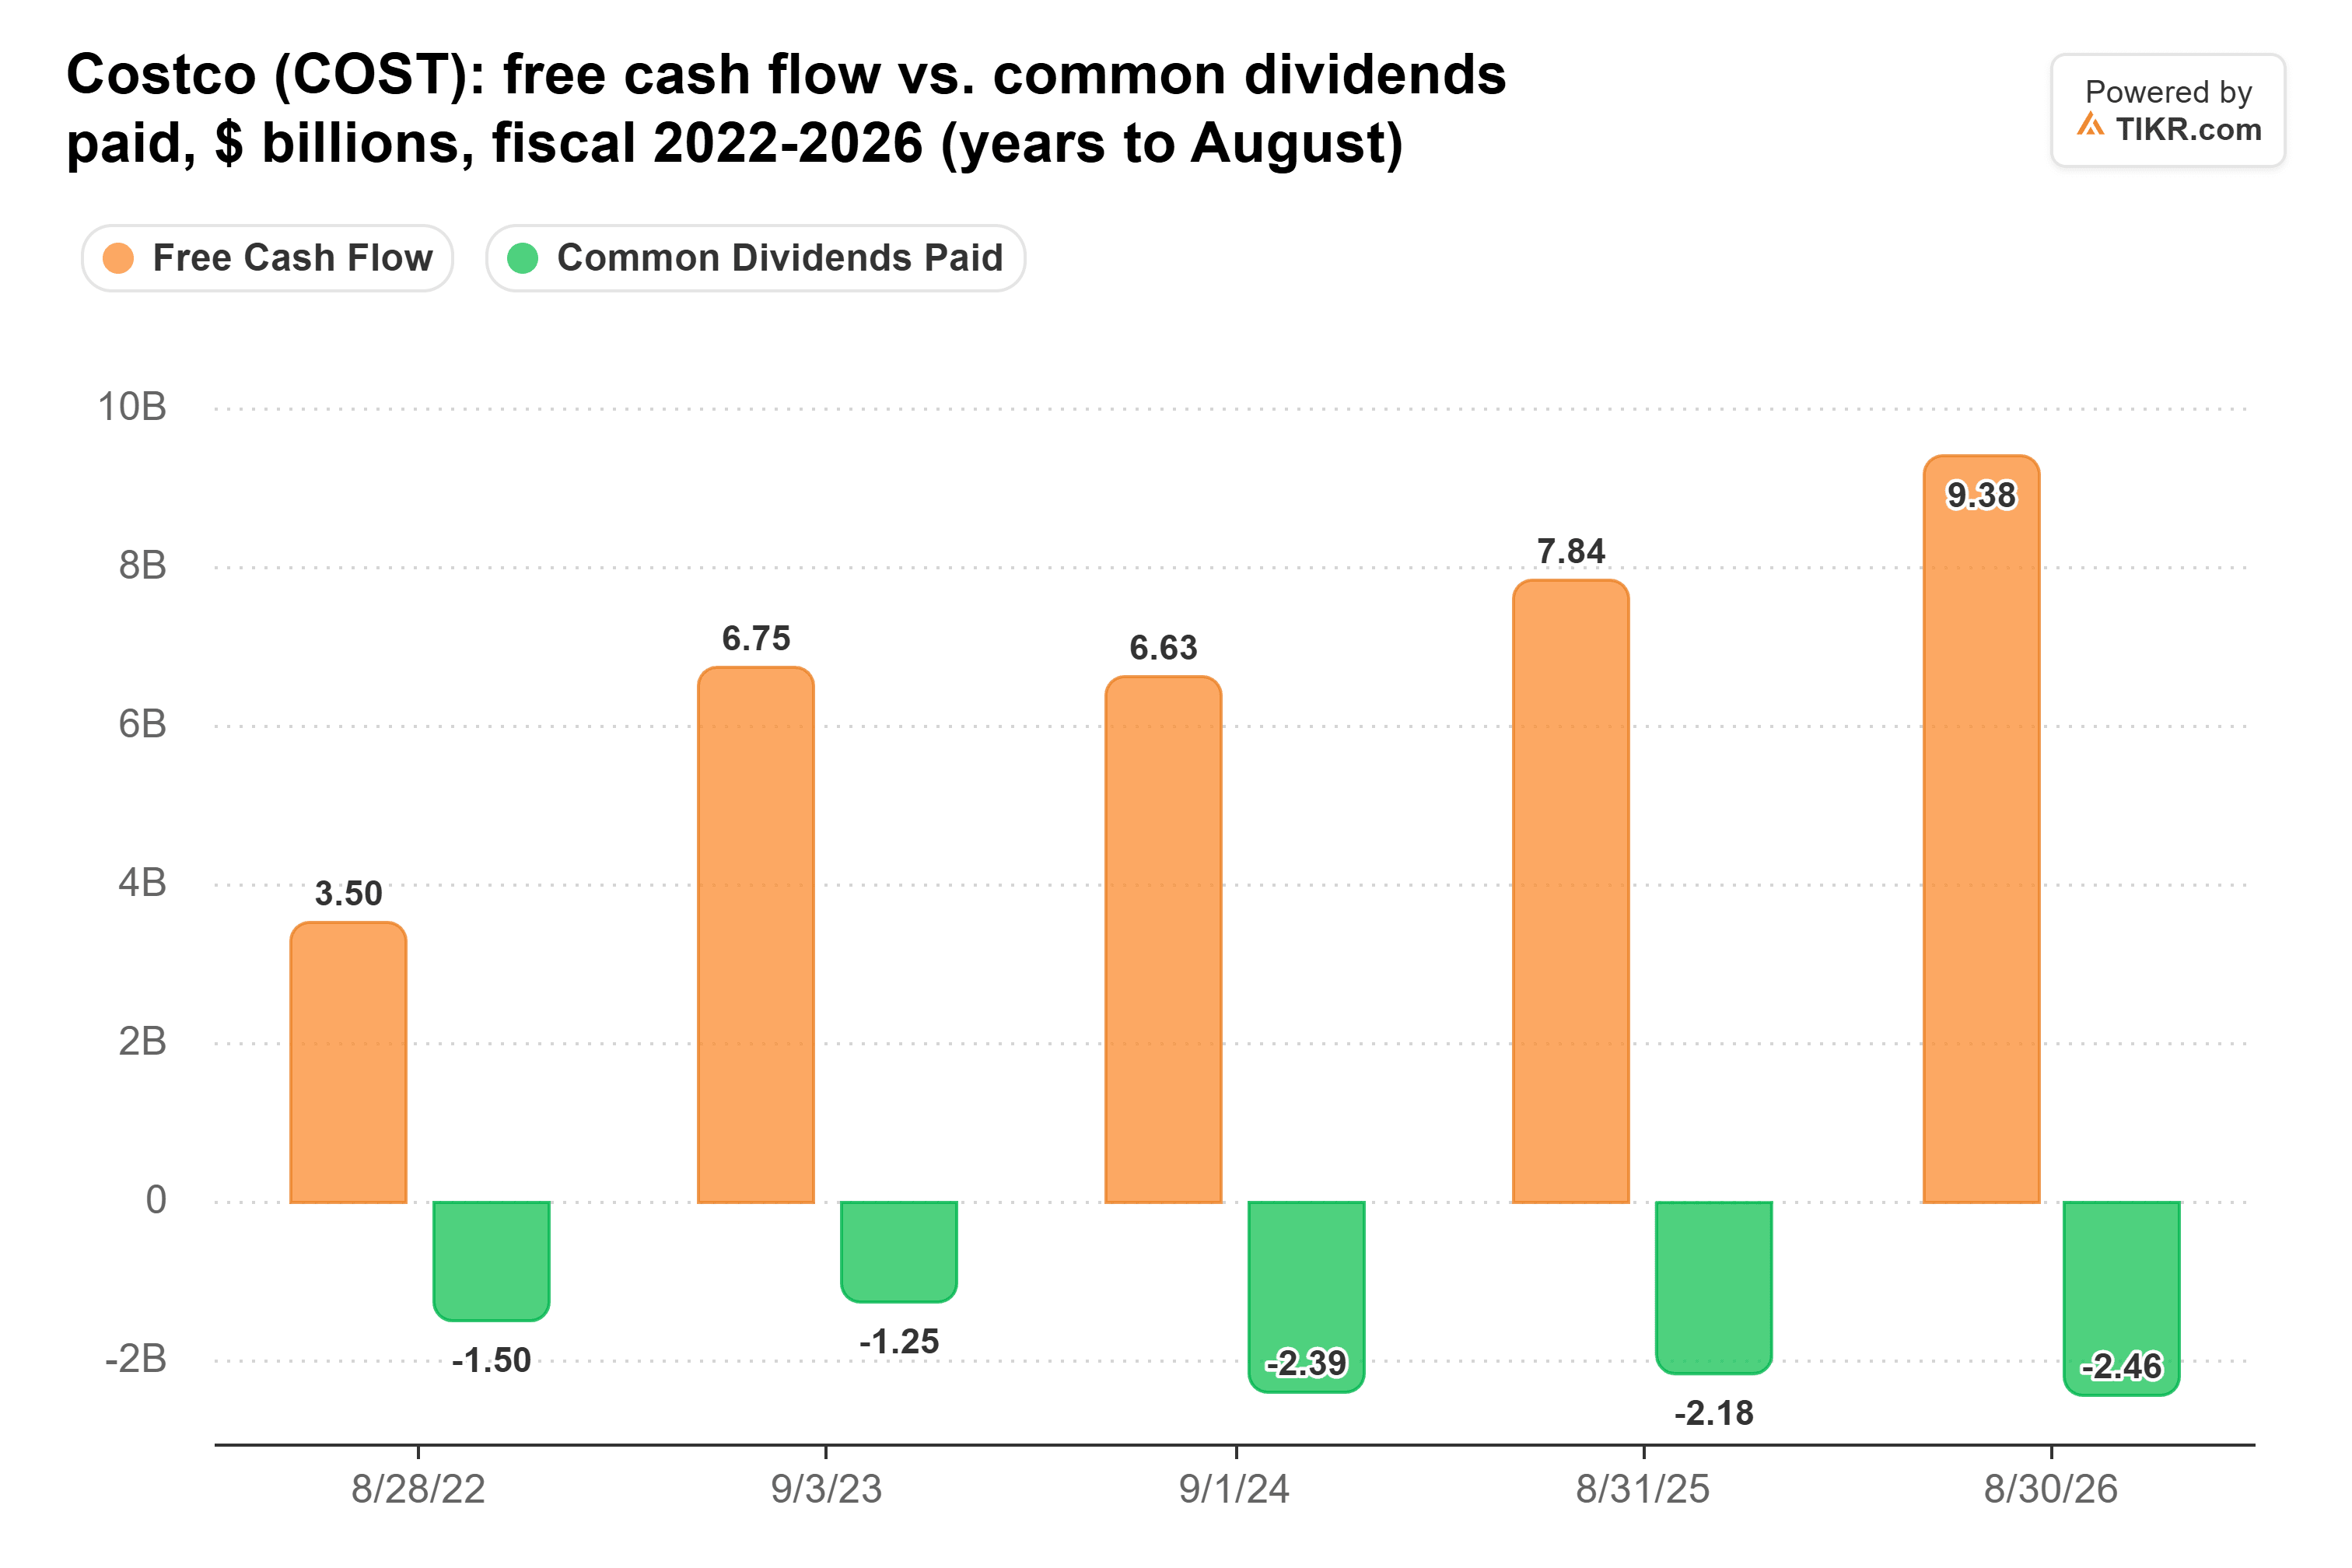
Analysts expect free cash flow to dip to about $7.5 billion in fiscal 2027 as Costco spends more on new warehouses. Even that would cover fiscal 2026’s regular dividends about three times. As one investor pointed out in a Reddit thread on the news, the $13.3 billion check is bigger than the roughly $8.5 billion Costco kept last year after capital spending and stock comp. So part of it comes out of the $20.2 billion of cash Costco had at the end of August.
The price of shelter
The stock is another matter. At about 47x forward earnings, Costco trades well above its 10-year average of 37x.
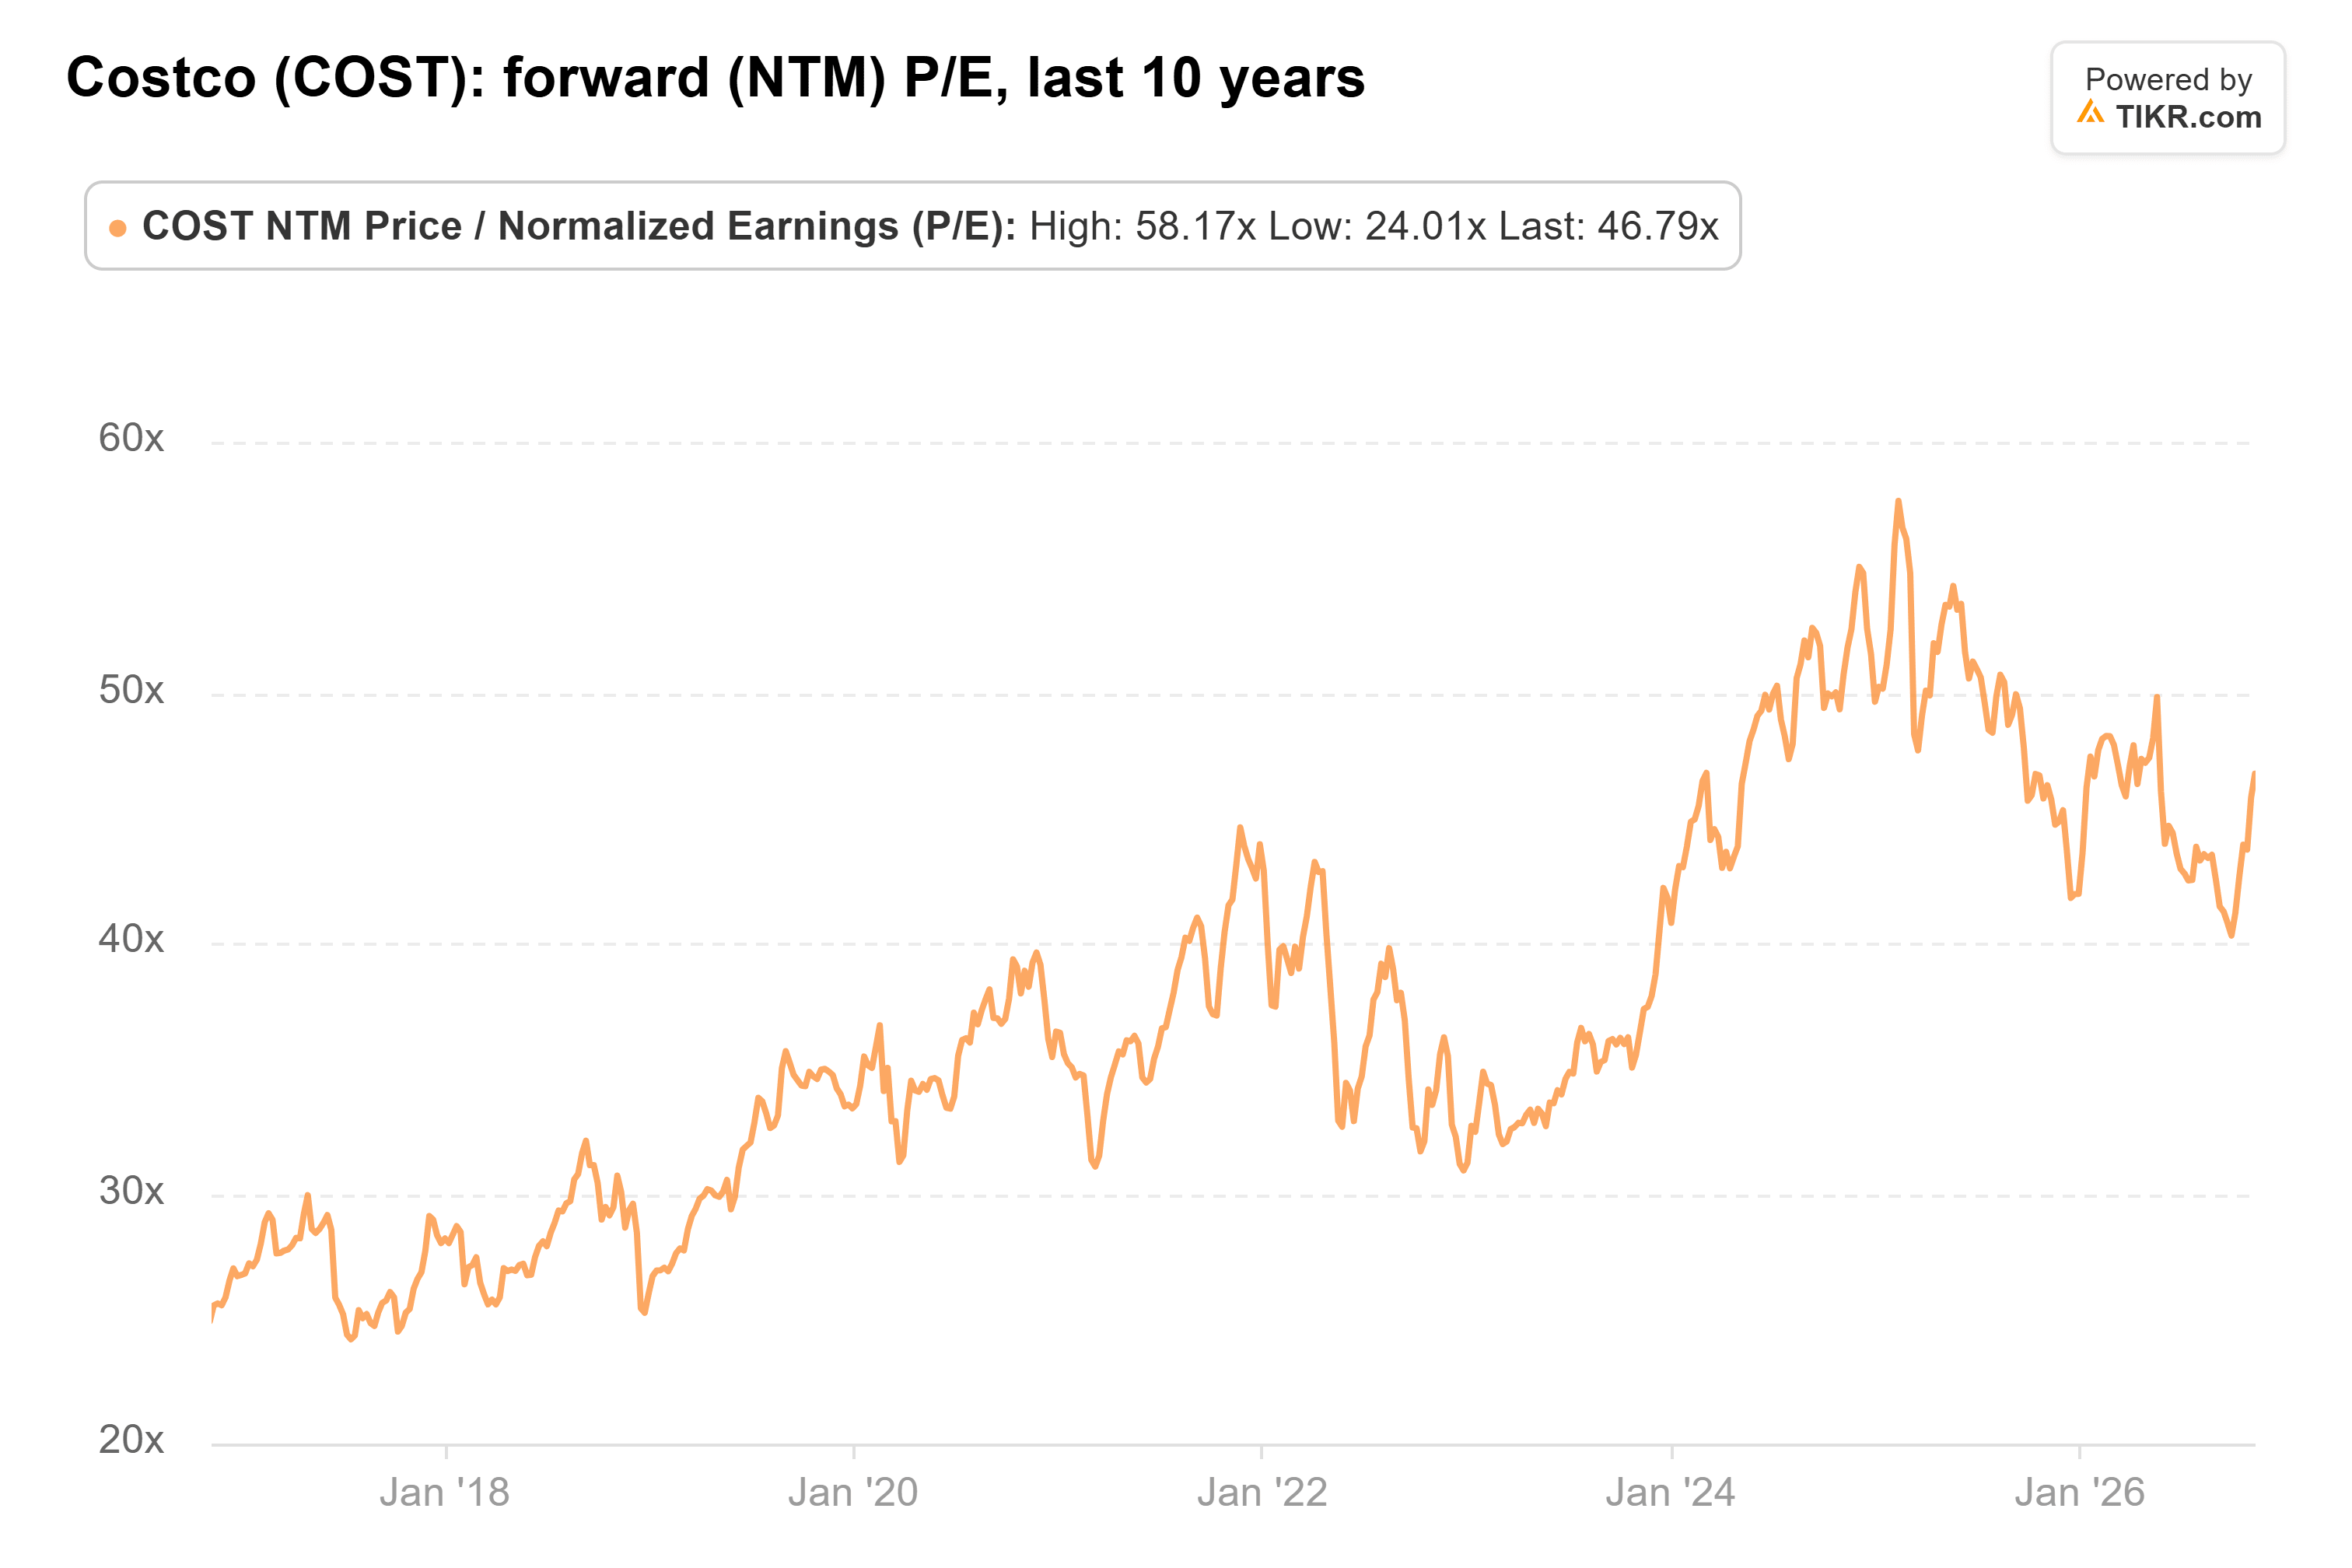
Costco has carried a premium for years, and anyone who sold on the multiple alone missed EPS growth of about 15% a year, from $5.33 in fiscal 2016 to $20.76 in fiscal 2026. But analysts now expect about 10% a year. At that pace, a slide back to the 10-year average would leave the stock about 20% lower, even if estimates hold. The investor who started that Reddit thread went further, putting Costco’s value at $660-$774 and saying they wouldn’t buy at $1,066. That would take a forward multiple of roughly 29x to 34x, a harsher call than a simple return to the average.
And if shelter means a stock that holds steady when the market drops, Walmart has done that better, with a five-year beta of 0.53 against Costco’s 0.85.
Collect the check, and wait on the stock
Costco’s business is about as sturdy as retail gets, and it just proved the cash behind it is real with a $13.3 billion check. But at about 47x forward earnings, investors are already paying a growth-stock price for that safety, while earnings grow closer to 10% a year. If you own it, enjoy the special and hold on. If you don’t, I’d wait for a better price.
The next test comes with first-quarter fiscal 2027 results on Dec. 10. It’s the first quarter in which fee income gets no lift from the 2024 fee increase. Paid-member growth slowed from 5.2% in the first quarter of fiscal 2026 to 3.8% in the fourth, and if it slows again, investors may not keep paying 47x for Costco.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!