Key Takeaways
- SK hynix just hit a new 52-week low, down 38% from its September high, in an AI-hardware selloff that has also hit Micron and Sandisk.
- Most of the selling followed news from other companies, including the CEO’s resignation at Nvidia, SK hynix’s biggest customer, while SK hynix posted the best quarter in its history.
- The stock trades at its lowest forward multiple since its July US listing, even though contracts with 14 customers cover more than half of its 2027 and 2028 capacity.
- For investors who can sit through a memory cycle, it looks like a buy, and the late-January results will show whether its 80% operating margin held.
SK hynix (SKHY) hit a new 52-week low of $117.40 on Nov. 17 before closing at $122.61, down 38% from its Sept. 9 closing high. The AI-hardware selloff has dragged down Micron (MU), Sandisk (SNDK) and SK hynix’s biggest customer, Nvidia (NVDA).
SK hynix’s own news has mostly been good, apart from a Nov. 14 ruling letting a proposed DRAM price-fixing class action against it, Samsung and Micron proceed; the claims are unproven. The day it reported its best quarter ever, Daniel Newman, CEO of Futurum Group, called the stock “ridiculously cheap” on CNBC.
It’s a lot cheaper now.
TIKR tracks 41 analysts on SK hynix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SK hynix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SK hynix’s Analyst Ratings
Most of the bad news was someone else’s
AI-spending fears came back with Lam Research’s December-quarter outlook on Oct. 21 and grew with Intel’s and Amazon’s results on Oct. 29. The Democrats’ midterm sweep raised fears of slower data-center building, and Qualcomm’s results on Nov. 4 showed handset chip sales down 26%, partly on rising memory costs. The one relief came on Nov. 10, when CoreWeave, a customer of SK hynix’s Solidigm unit, raised its 2026 outlook.
Micron is down 31% over the same stretch, though it says more than 75% of its 2027 output is committed. Sandisk is down 55%, even after data center revenue jumped 61% from the prior quarter to $4.8 billion. Investors are selling the whole group, whatever each company has under contract.
Nvidia, down 30%, matters most: TrendForce reported in January, citing Korean media, that it was expected to give SK hynix about two-thirds of its HBM4 orders. Hours after SK hynix’s low, Nvidia gave its first report since CEO Jensen Huang resigned on Nov. 12. Revenue for the quarter ended Oct. 25 rose 103% to $115.8 billion, and it guided to $130 billion for a fourth quarter with an extra week, against estimates of about $125 billion.
That’s hardly a customer pulling back.
A record quarter, and a buyback to match
On Oct. 28, SK hynix reported preliminary third-quarter revenue up 328% year over year to ₩104.6 trillion, and operating profit up 632% to ₩83.3 trillion, an 80% margin. It also laid out about ₩100 trillion of 2026 shareholder returns and started a new ₩20 trillion buyback, half of it for employee stock pay, running through Jan. 28.
CEO Kwak Noh-Jung said the business is “transforming into one with earnings stability and mid-to-long term demand visibility.” He has contracts to point to: long-term agreements with 14 customers cover more than half of SK hynix’s 2027 and 2028 capacity.
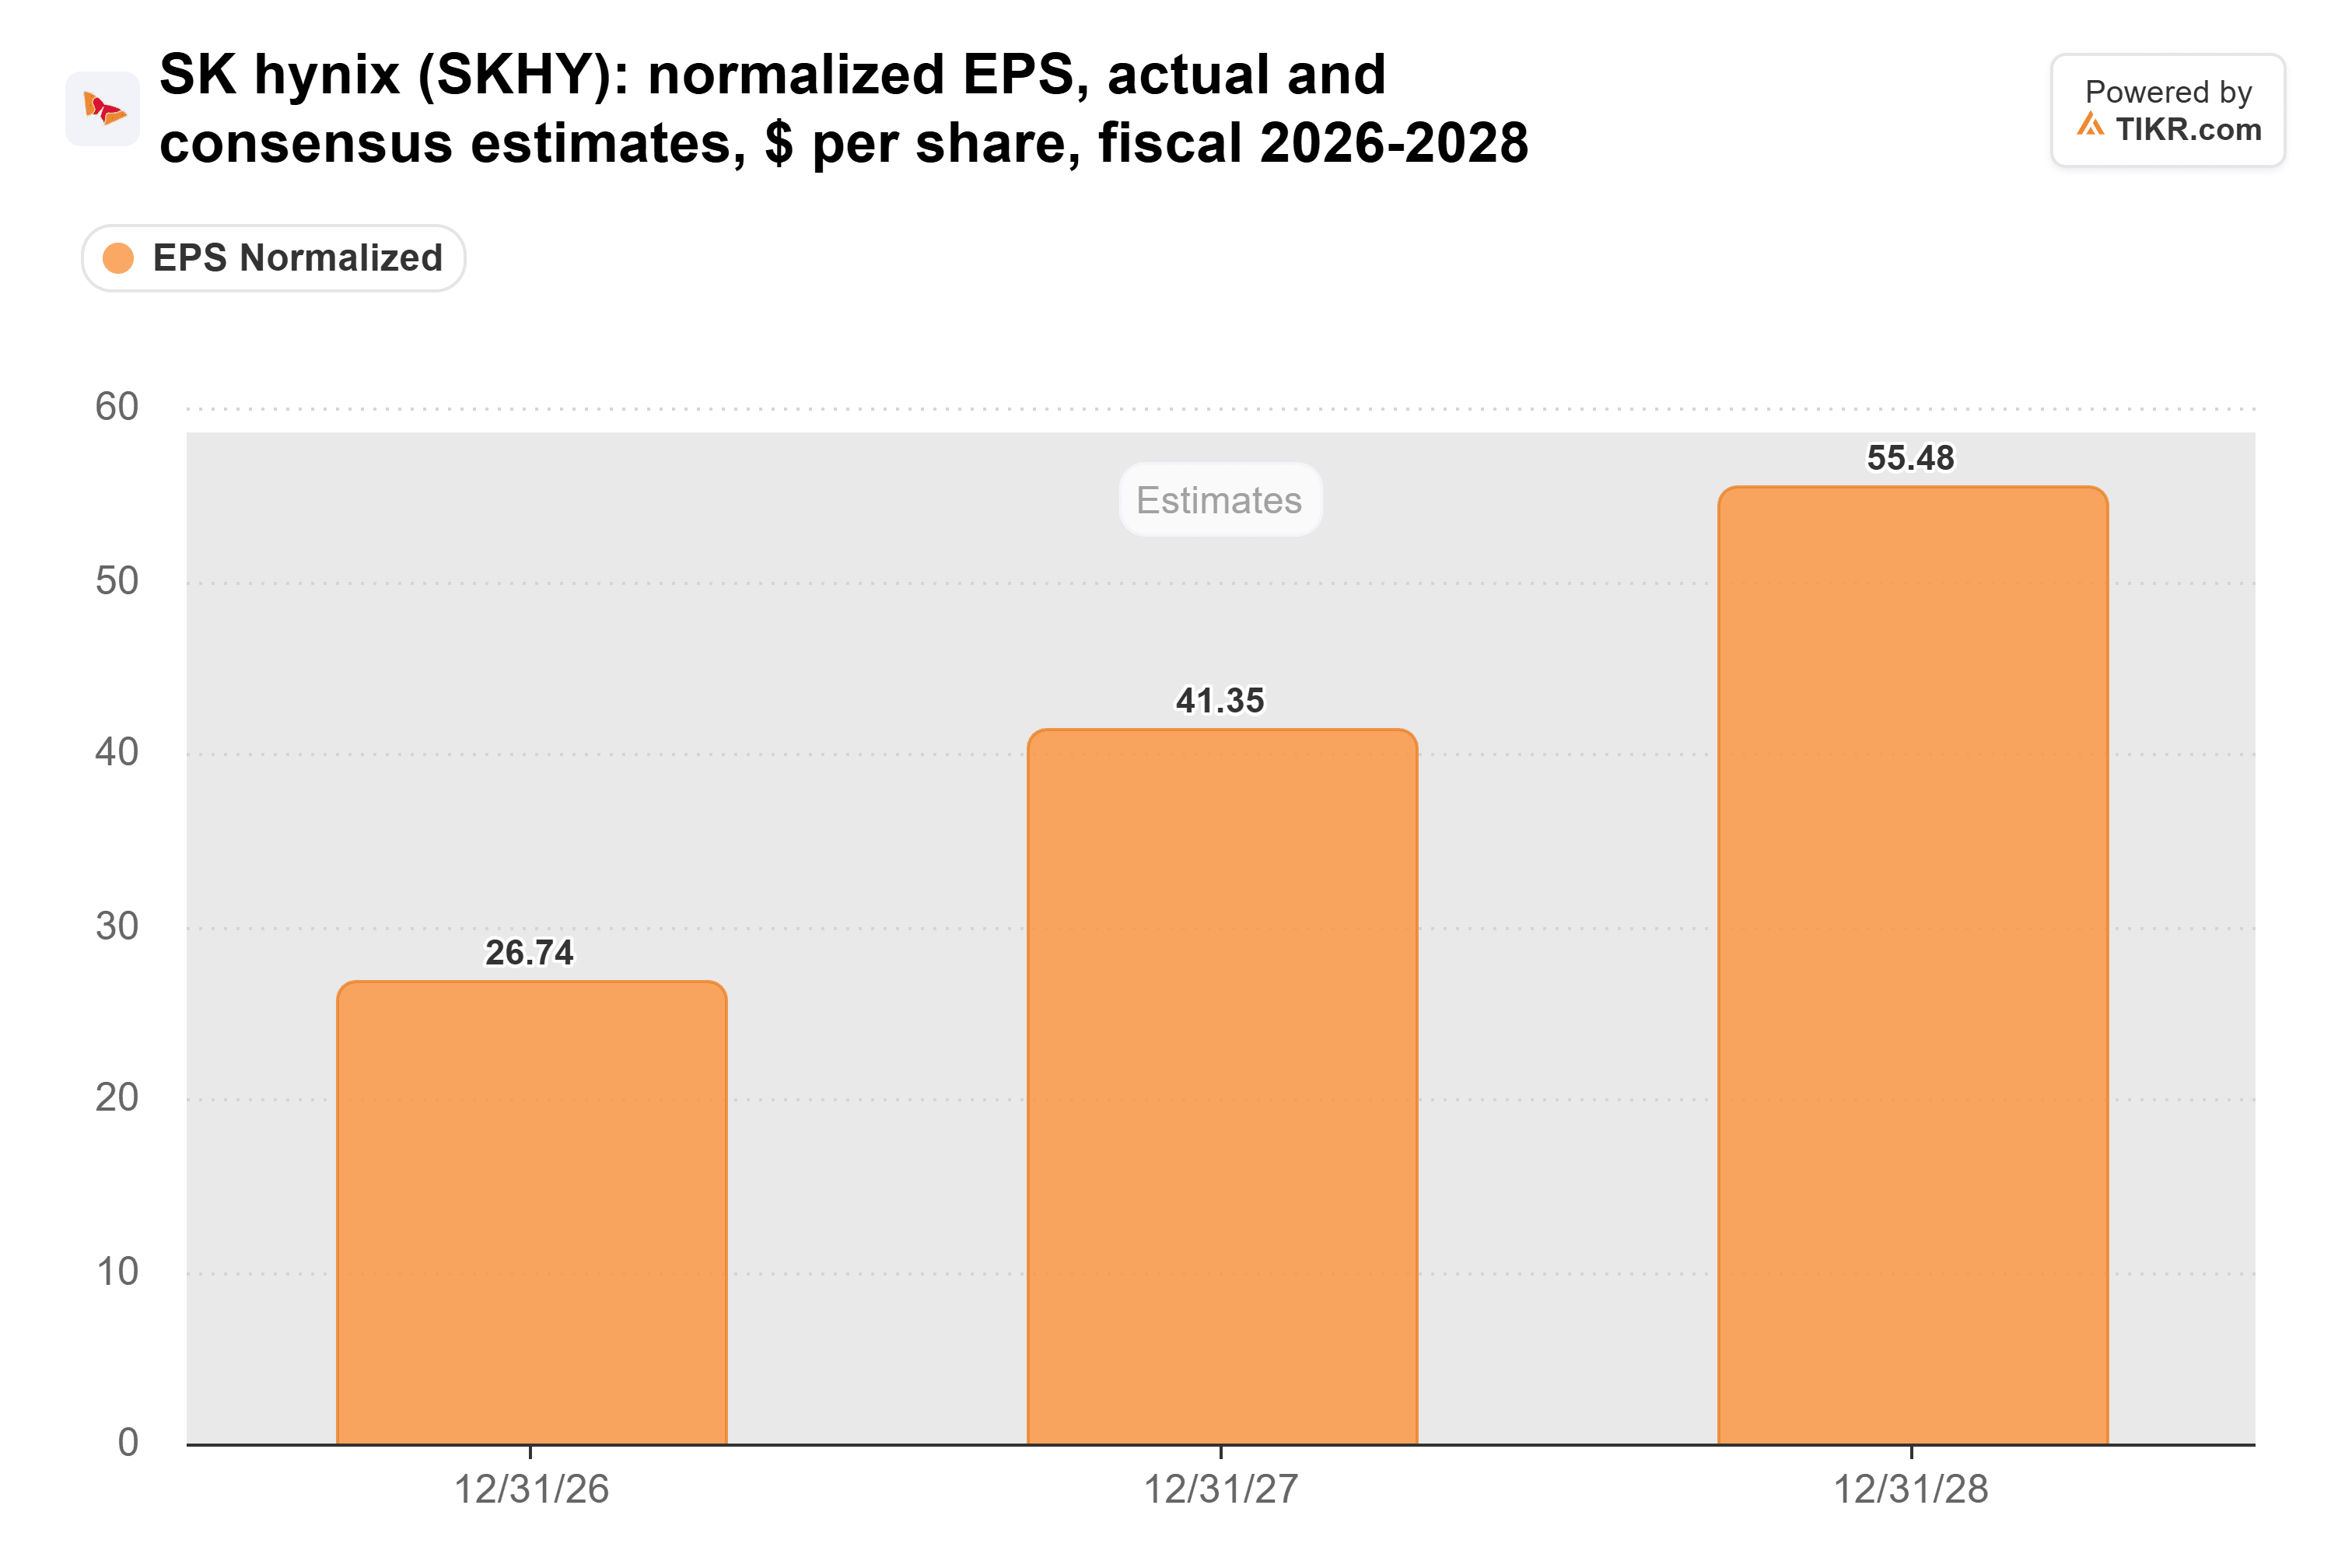
Analysts expect normalized EPS per US share to roughly double from 2026 to 2028:
Priced for a bust
SK hynix trades at 2.2x forward earnings, its lowest since the US shares listed in July, against a 3.7x average:
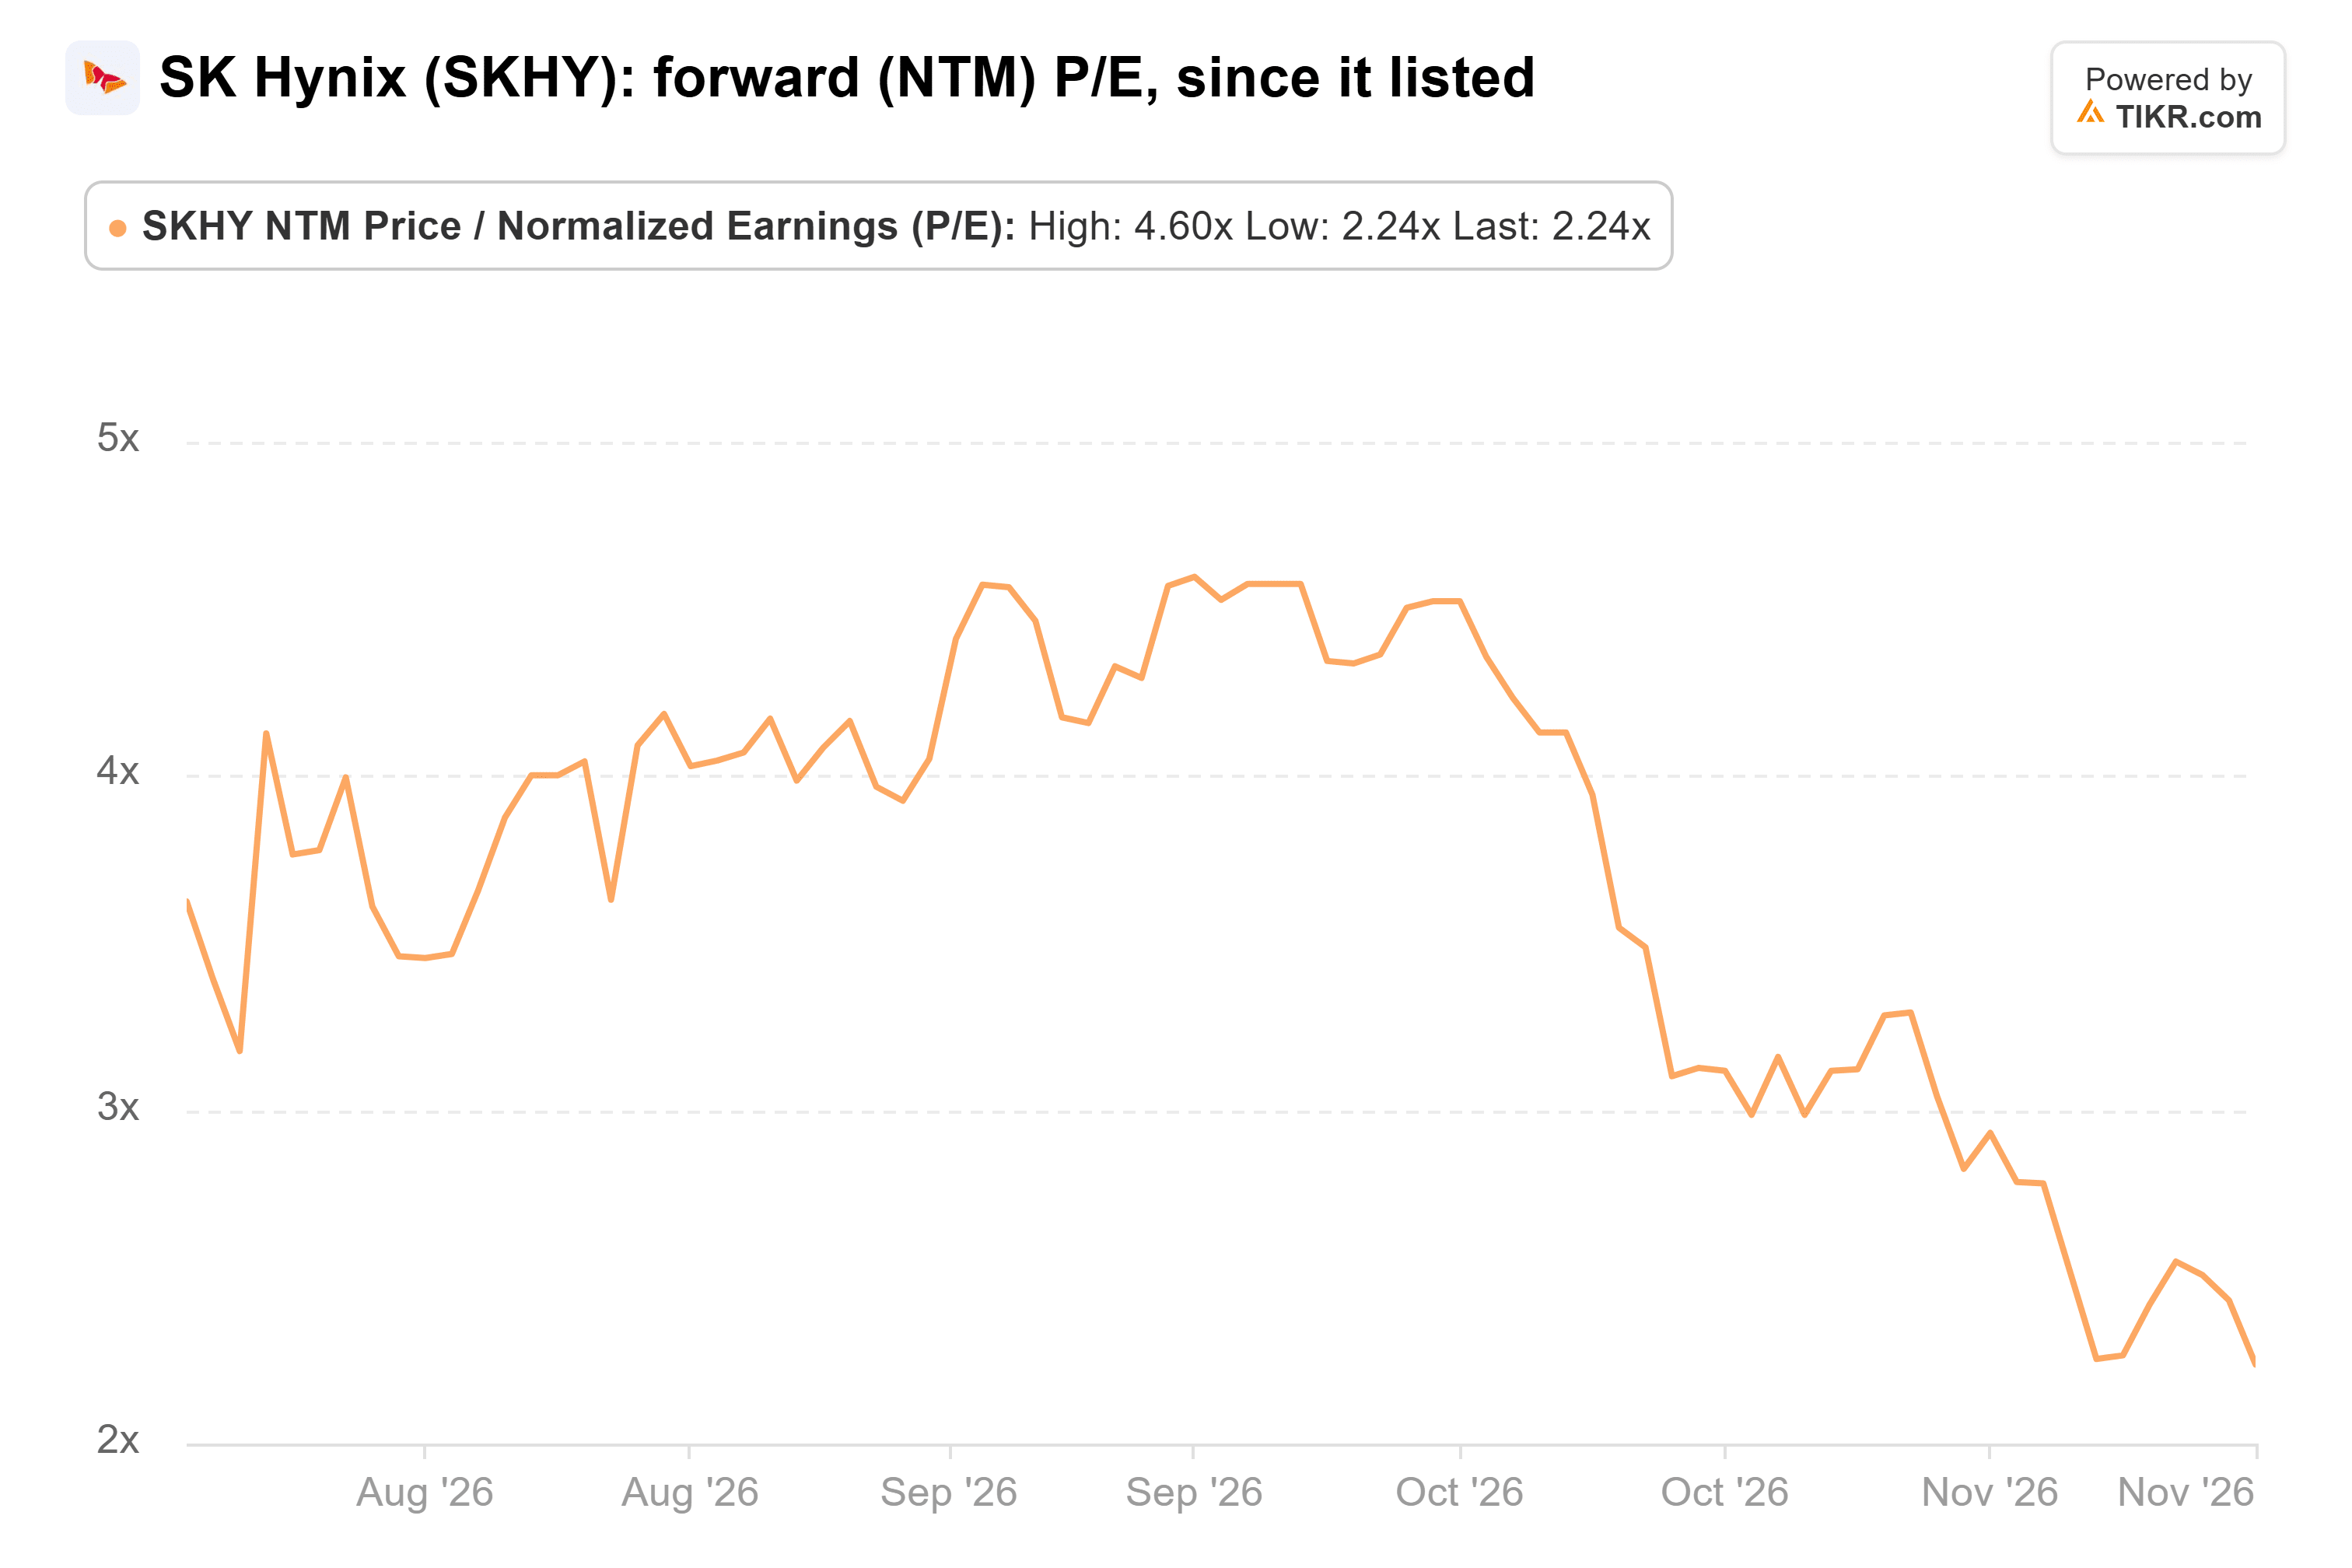
That prices in a profit collapse, and memory makers have lived through those. SK hynix’s operating margin fell from 28.9% in 2021 to -23.6% in 2023:

Capex is set to rise in 2027 from this year’s high-₩40 trillion range, the kind of buildout that preceded past busts. Reuters also reported that US officials are holding up licenses for tools SK hynix needs to expand its Dalian, China, plant.
For 2.2x to make sense, profits would have to fall well before those contracts run out. The average Street target of $260 is more than double the last close.
Cheap enough for the patient
Nothing in SK hynix’s numbers looks like a business heading for a bust, and its biggest customer guided above estimates. For investors who can sit through a memory cycle, the stock looks like a buy at 2.2x.
Memory stocks can stay cheap. Late-January results will show whether fourth-quarter DRAM shipments grew the guided mid-20%. An operating margin well below the third quarter’s 80% would be the first sign the peak is in.
So what is SK hynix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SK hynix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!