Key Takeaways
- SK Hynix posted record third-quarter revenue of ₩104.6 trillion and an 80% operating margin, yet its U.S.-listed shares sit about 34% below their September high.
- The AI selloff after the U.S. midterms hit SK Hynix harder than Samsung Electronics, even though SK Hynix earned the richer chip margin.
- Washington has delayed licenses for tools SK Hynix needs to expand its Dalian plant in China, which complicates a planned New York buildout.
- Long-term agreements cover more than half of 2027 and 2028 capacity, and the results expected in late January will show whether HBM4 has taken over.
SK Hynix (000660.KS) just posted the best quarter in its history. The stock has traded as if the cycle already peaked.
Its U.S.-listed shares closed at $132 on Friday, about 34% below their September 9 high. Most of the damage came fast, because the AI selloff that followed the Democrats’ midterm win spread from Wall Street to Seoul.
Samsung Electronics (005930.KS) fell too, but less. On November 6, SK Hynix plunged more than 8% in Seoul while Samsung shed 7%. That gap makes sense, since SK Hynix is the purer AI memory bet.
A second worry landed the same week. Reuters reported that U.S. officials have delayed licenses for tools SK Hynix needs to expand its Dalian plant in China.
Records the market shrugged off
The October 28 report cleared every bar:
- Revenue rose 328% from a year earlier to ₩104.6 trillion, the first quarter above ₩100 trillion.
- Operating profit jumped 632% to ₩83.3 trillion, well above the ₩76.7 trillion LSEG SmartEstimates had expected.
- Net cash climbed to ₩98.7 trillion as cash reached ₩114.5 trillion.
Even the sequential pace stayed hot…
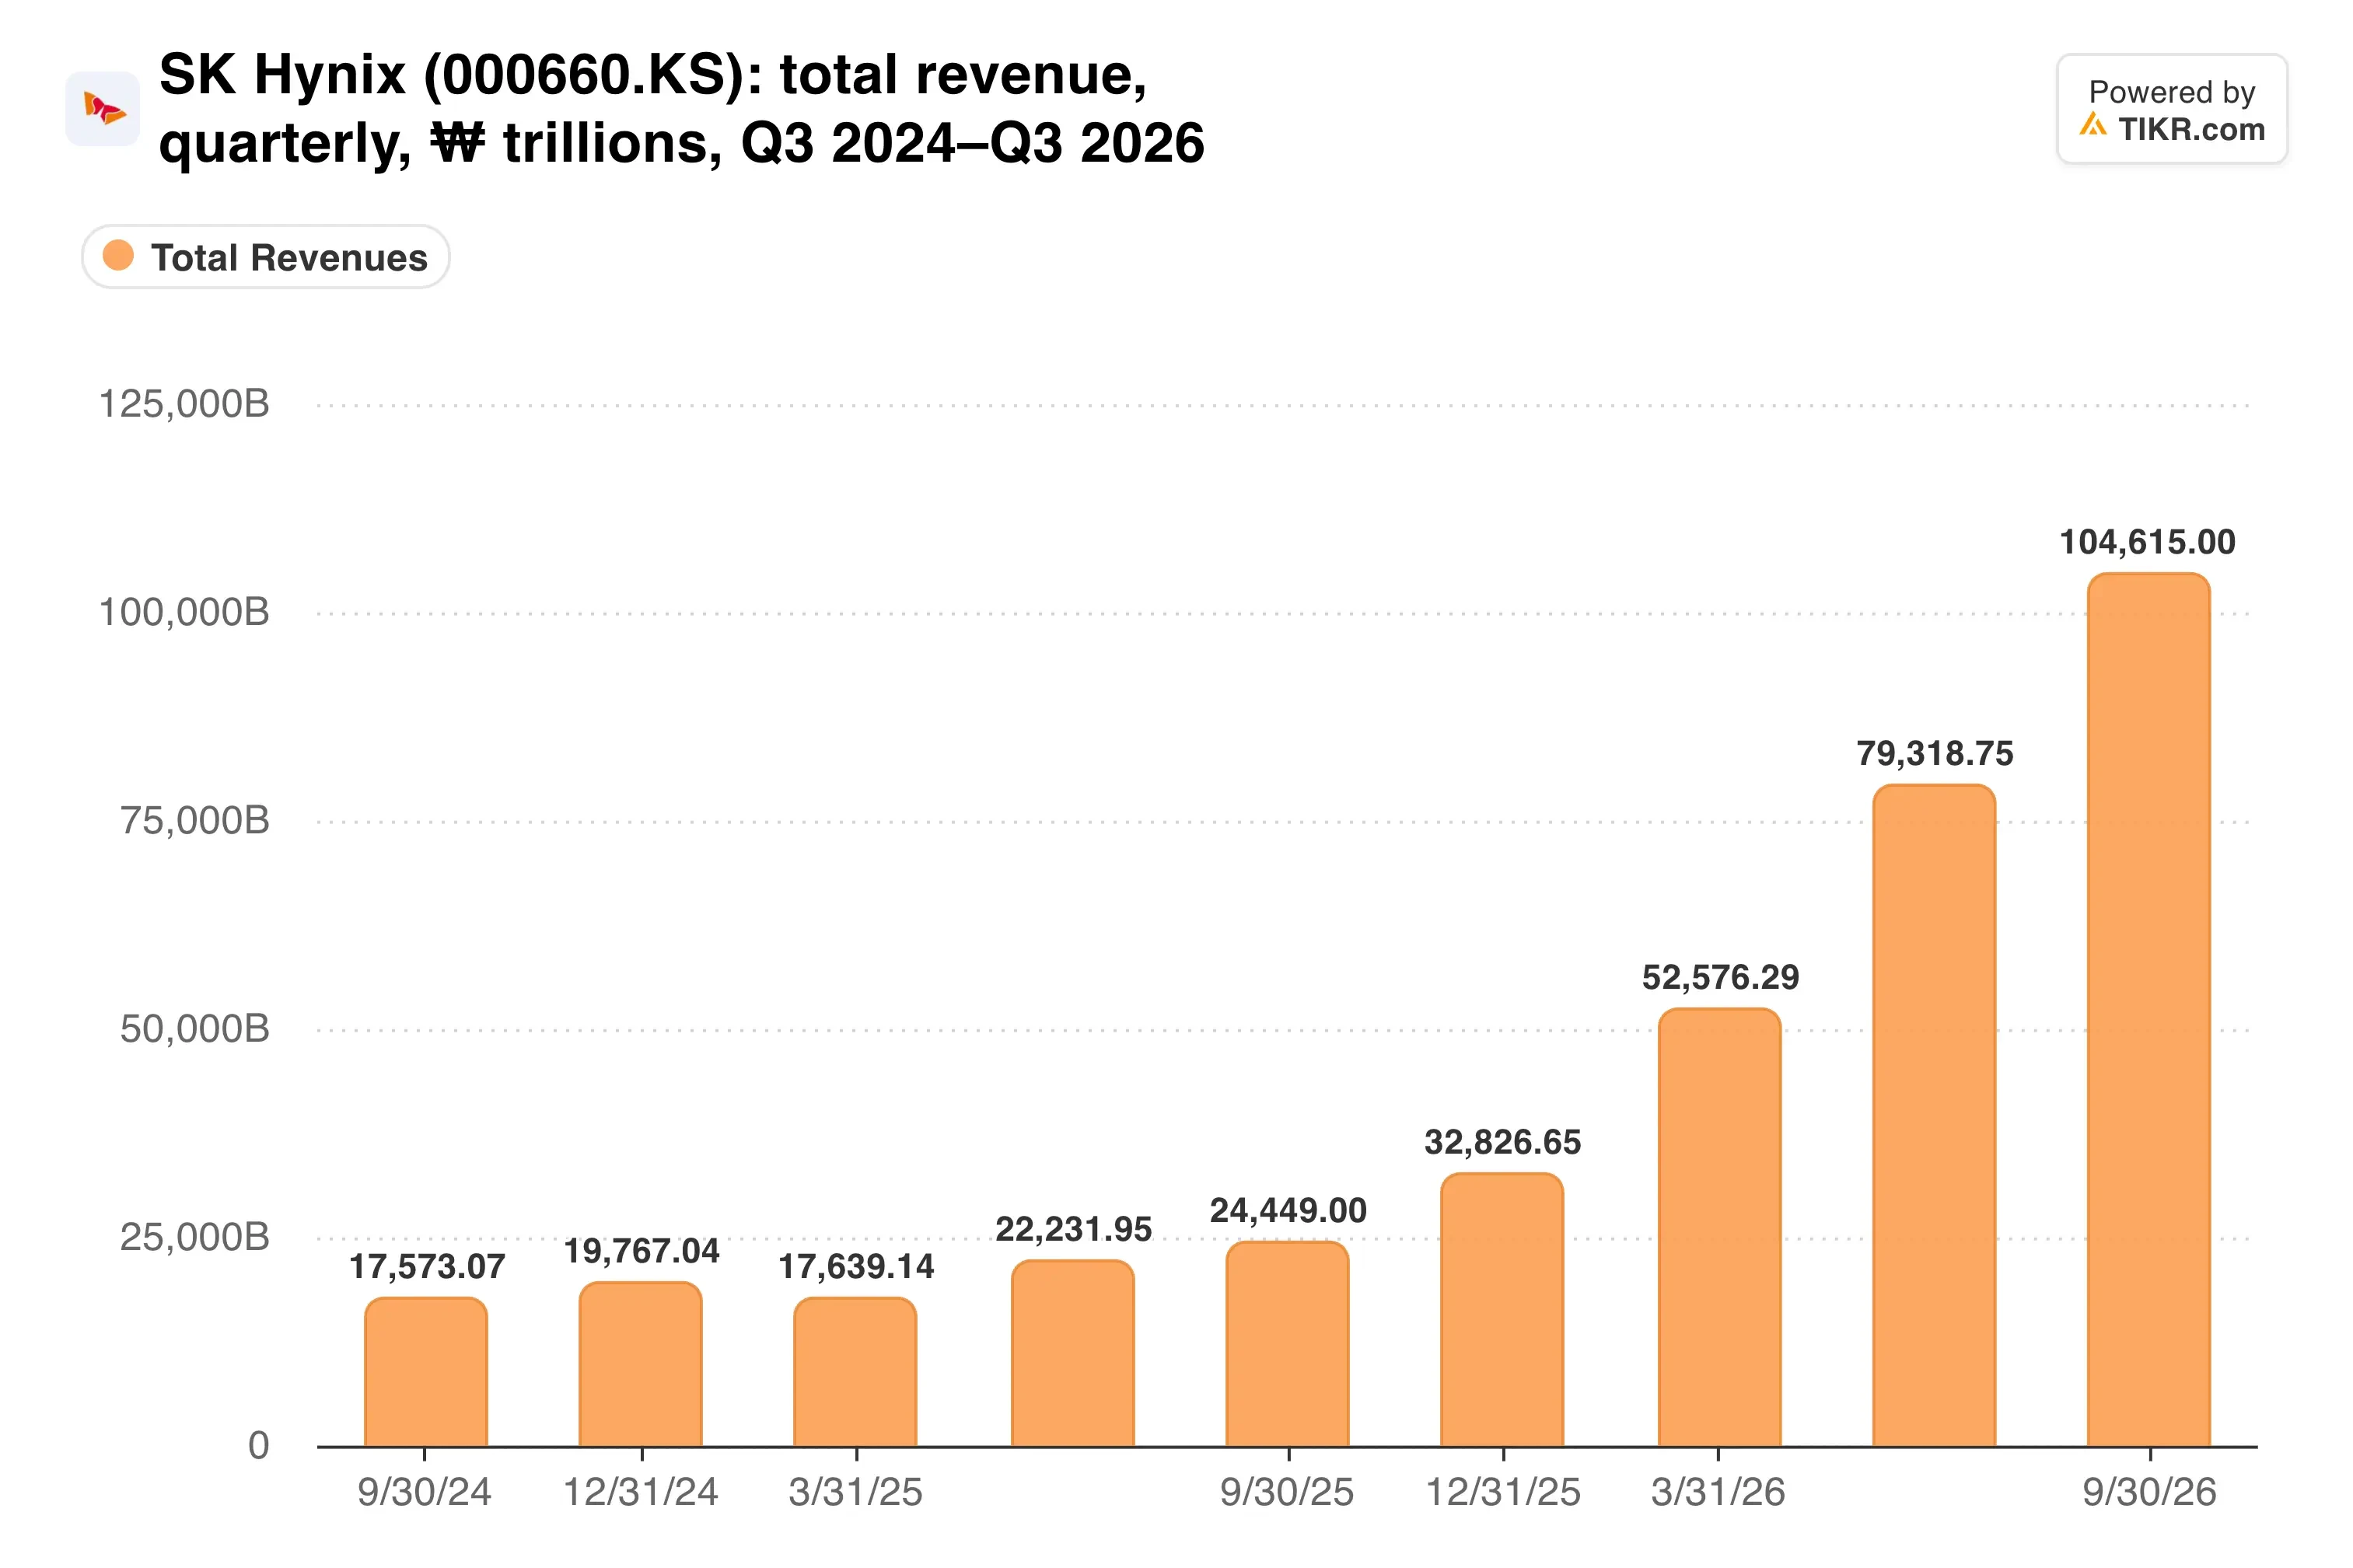
Revenue grew 32% from the second quarter alone, so the curve has not flattened yet.
Investors cheered at first. The Seoul shares closed 10.9% higher on results day, and Futurum Group CEO Daniel Newman told CNBC the stock looked “ridiculously cheap.” Yet by November 5, the U.S. shares had touched a 52-week low of $122.
TIKR tracks 16 analysts on SK hynix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SK hynix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SK hynix’s Analyst Ratings
Contracts change the cycle math
What makes this upcycle different is visibility. SK Hynix has signed long-term agreements with 14 major customers, including leading cloud providers. Those deals cover more than half of its 2027 and 2028 capacity.
Pricing moves within a range agreed with each customer, so SK Hynix keeps some upside while limiting the downside. CEO Kwak Noh-Jung said on October 28 that the business is “transforming into one with earnings stability and mid-to-long term demand visibility.”
And product mix is the other lever. HBM4 should overtake HBM3E in both shipments and revenue this quarter, while the M15X fab runs at full capacity by year end.
Where does all that pricing power show up?
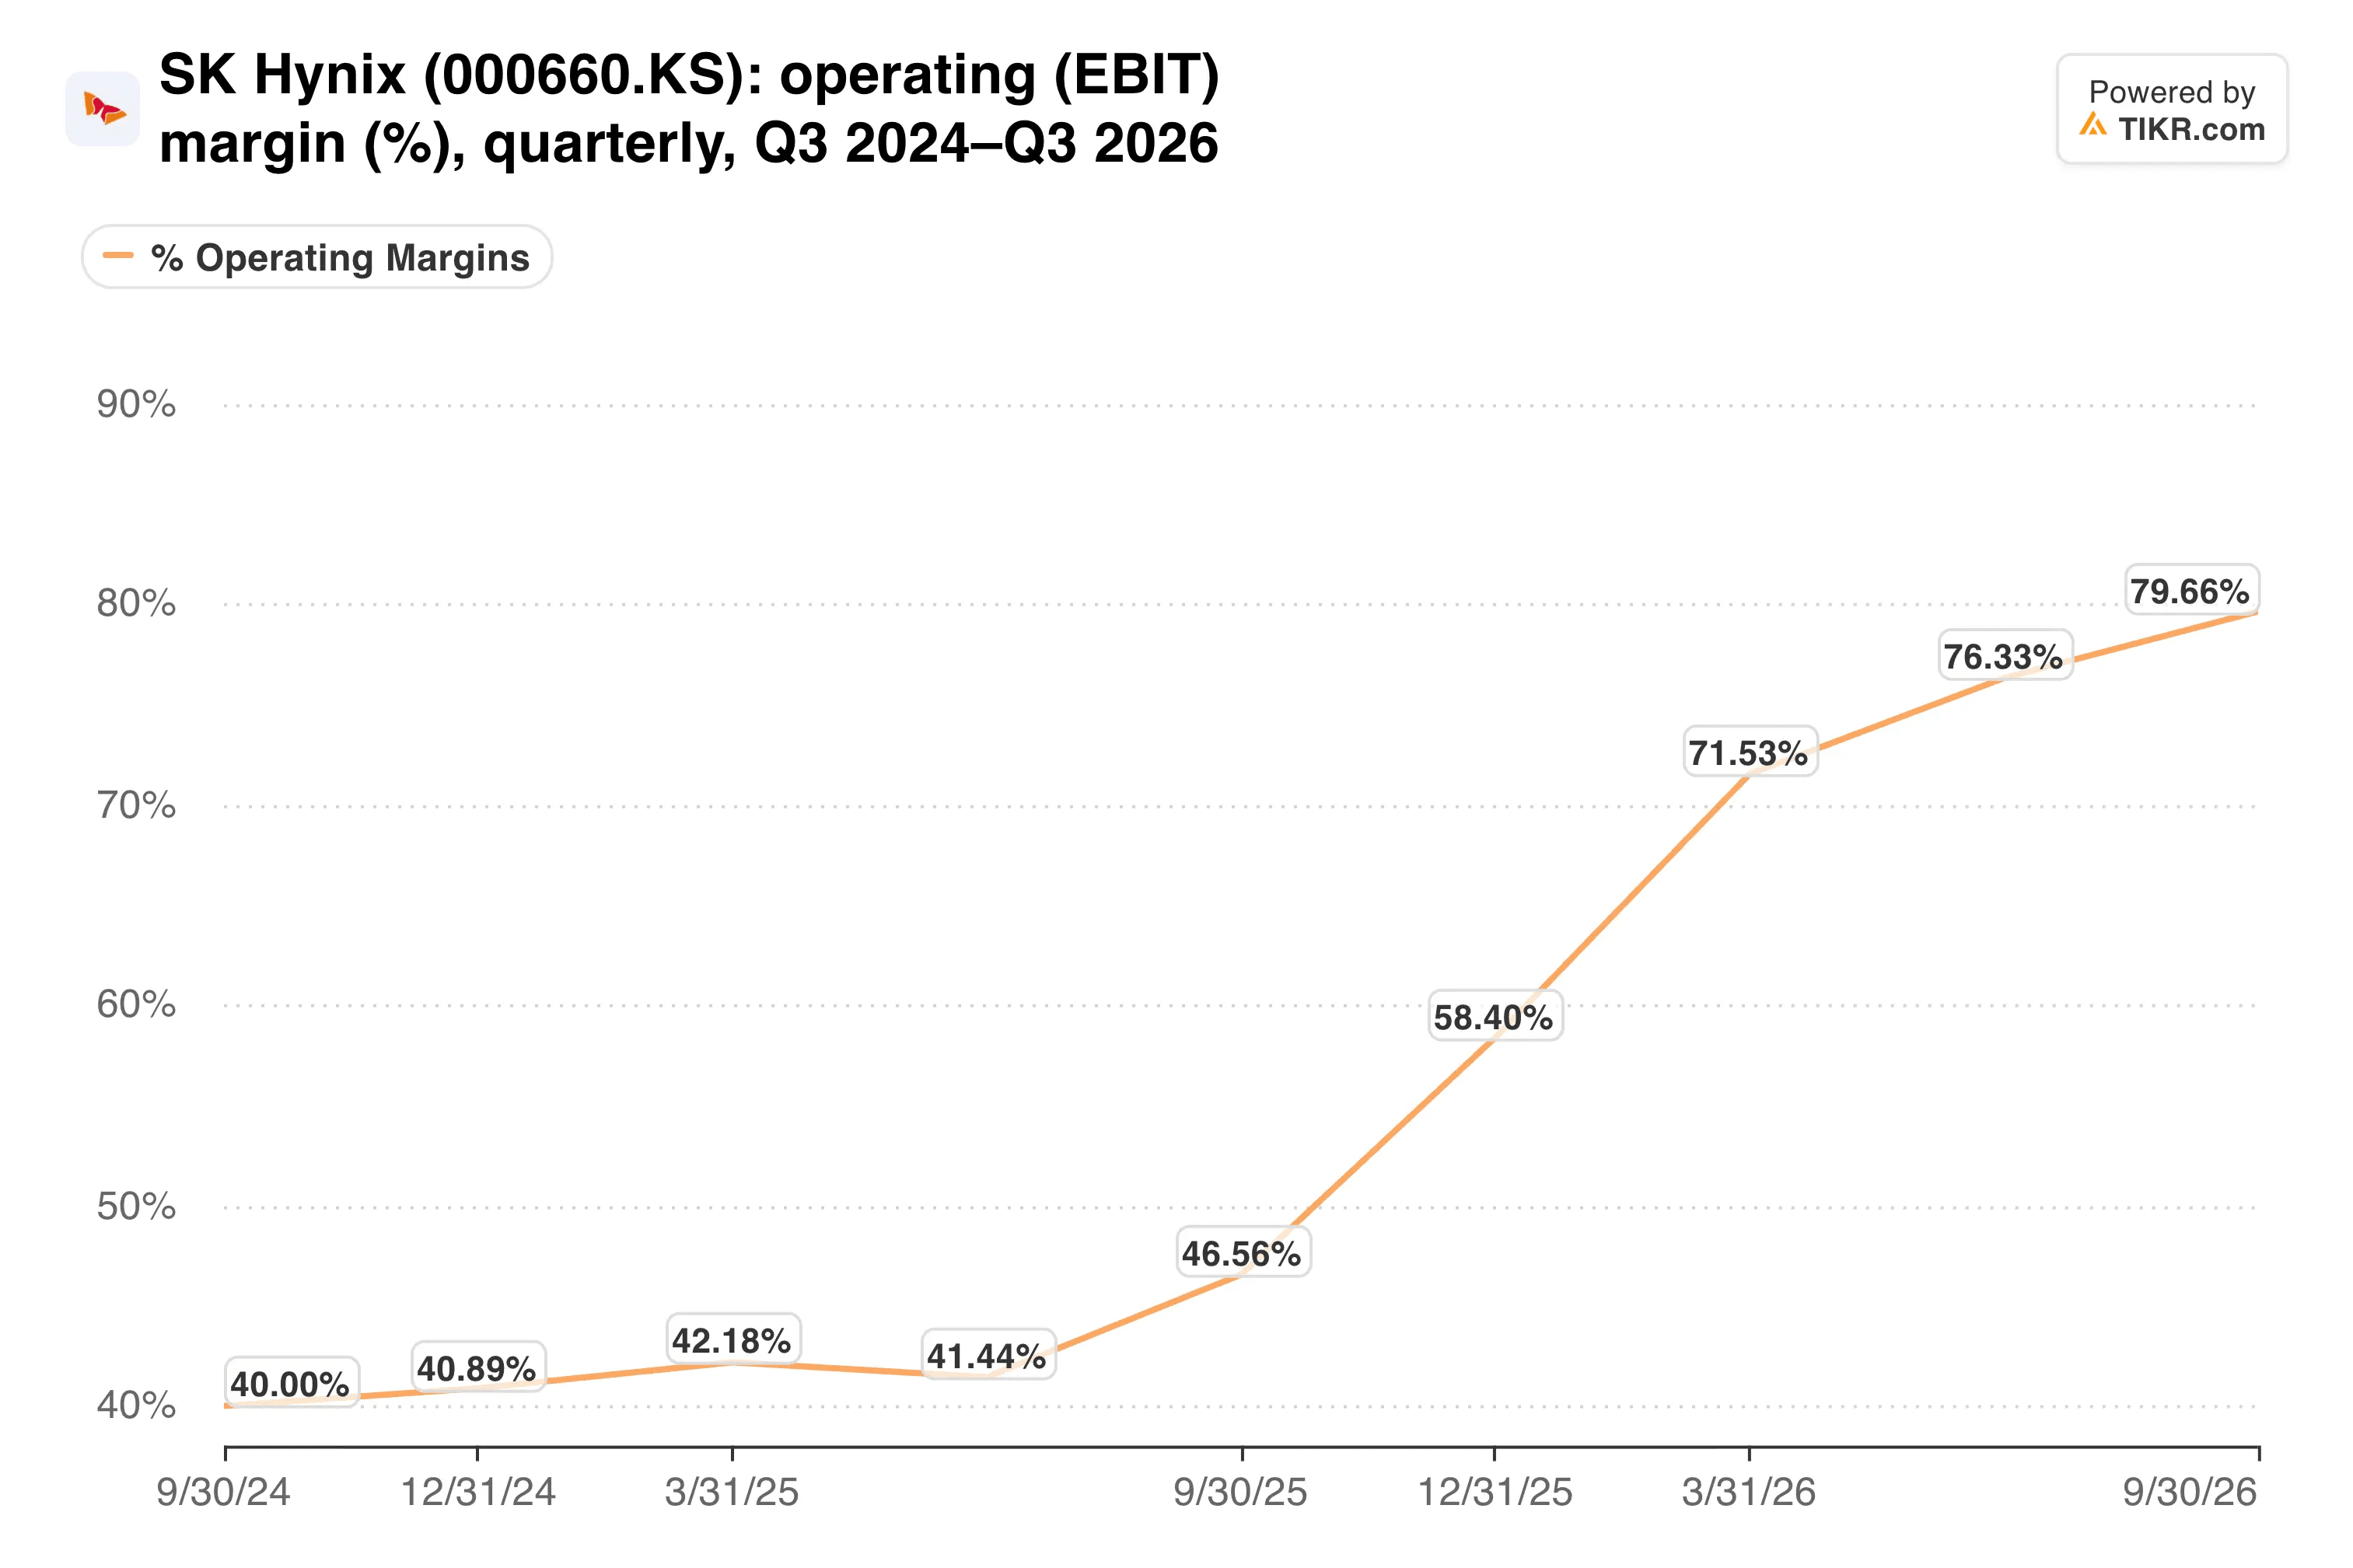
Operating margin hit 80% in the third quarter, up from 47% a year earlier.
That beats Samsung, too. Samsung’s chip division earned ₩106.5 trillion on ₩147.1 trillion of revenue, a 72.4% margin. Still, Samsung earned more in total.
The license fight and the bill ahead
The harder questions sit outside the income statement. Reuters said Commerce Under Secretary Jeffrey Kessler has held firm against more U.S. tools going to expand or upgrade Dalian. That matters because SK Hynix wants higher Dalian output to help fund Solidigm’s planned NAND plants in New York, a project Reuters put at roughly $45 billion.
Spending will also climb. Management expects investment to rise significantly next year as Yongin Phase 1 enters full operation. Meanwhile, SK Hynix plans about ₩100 trillion in shareholder returns this year.
Then there is the multiple. Bank of America said the recent AI hardware selloff came from shrinking valuation multiples while earnings estimates held up.
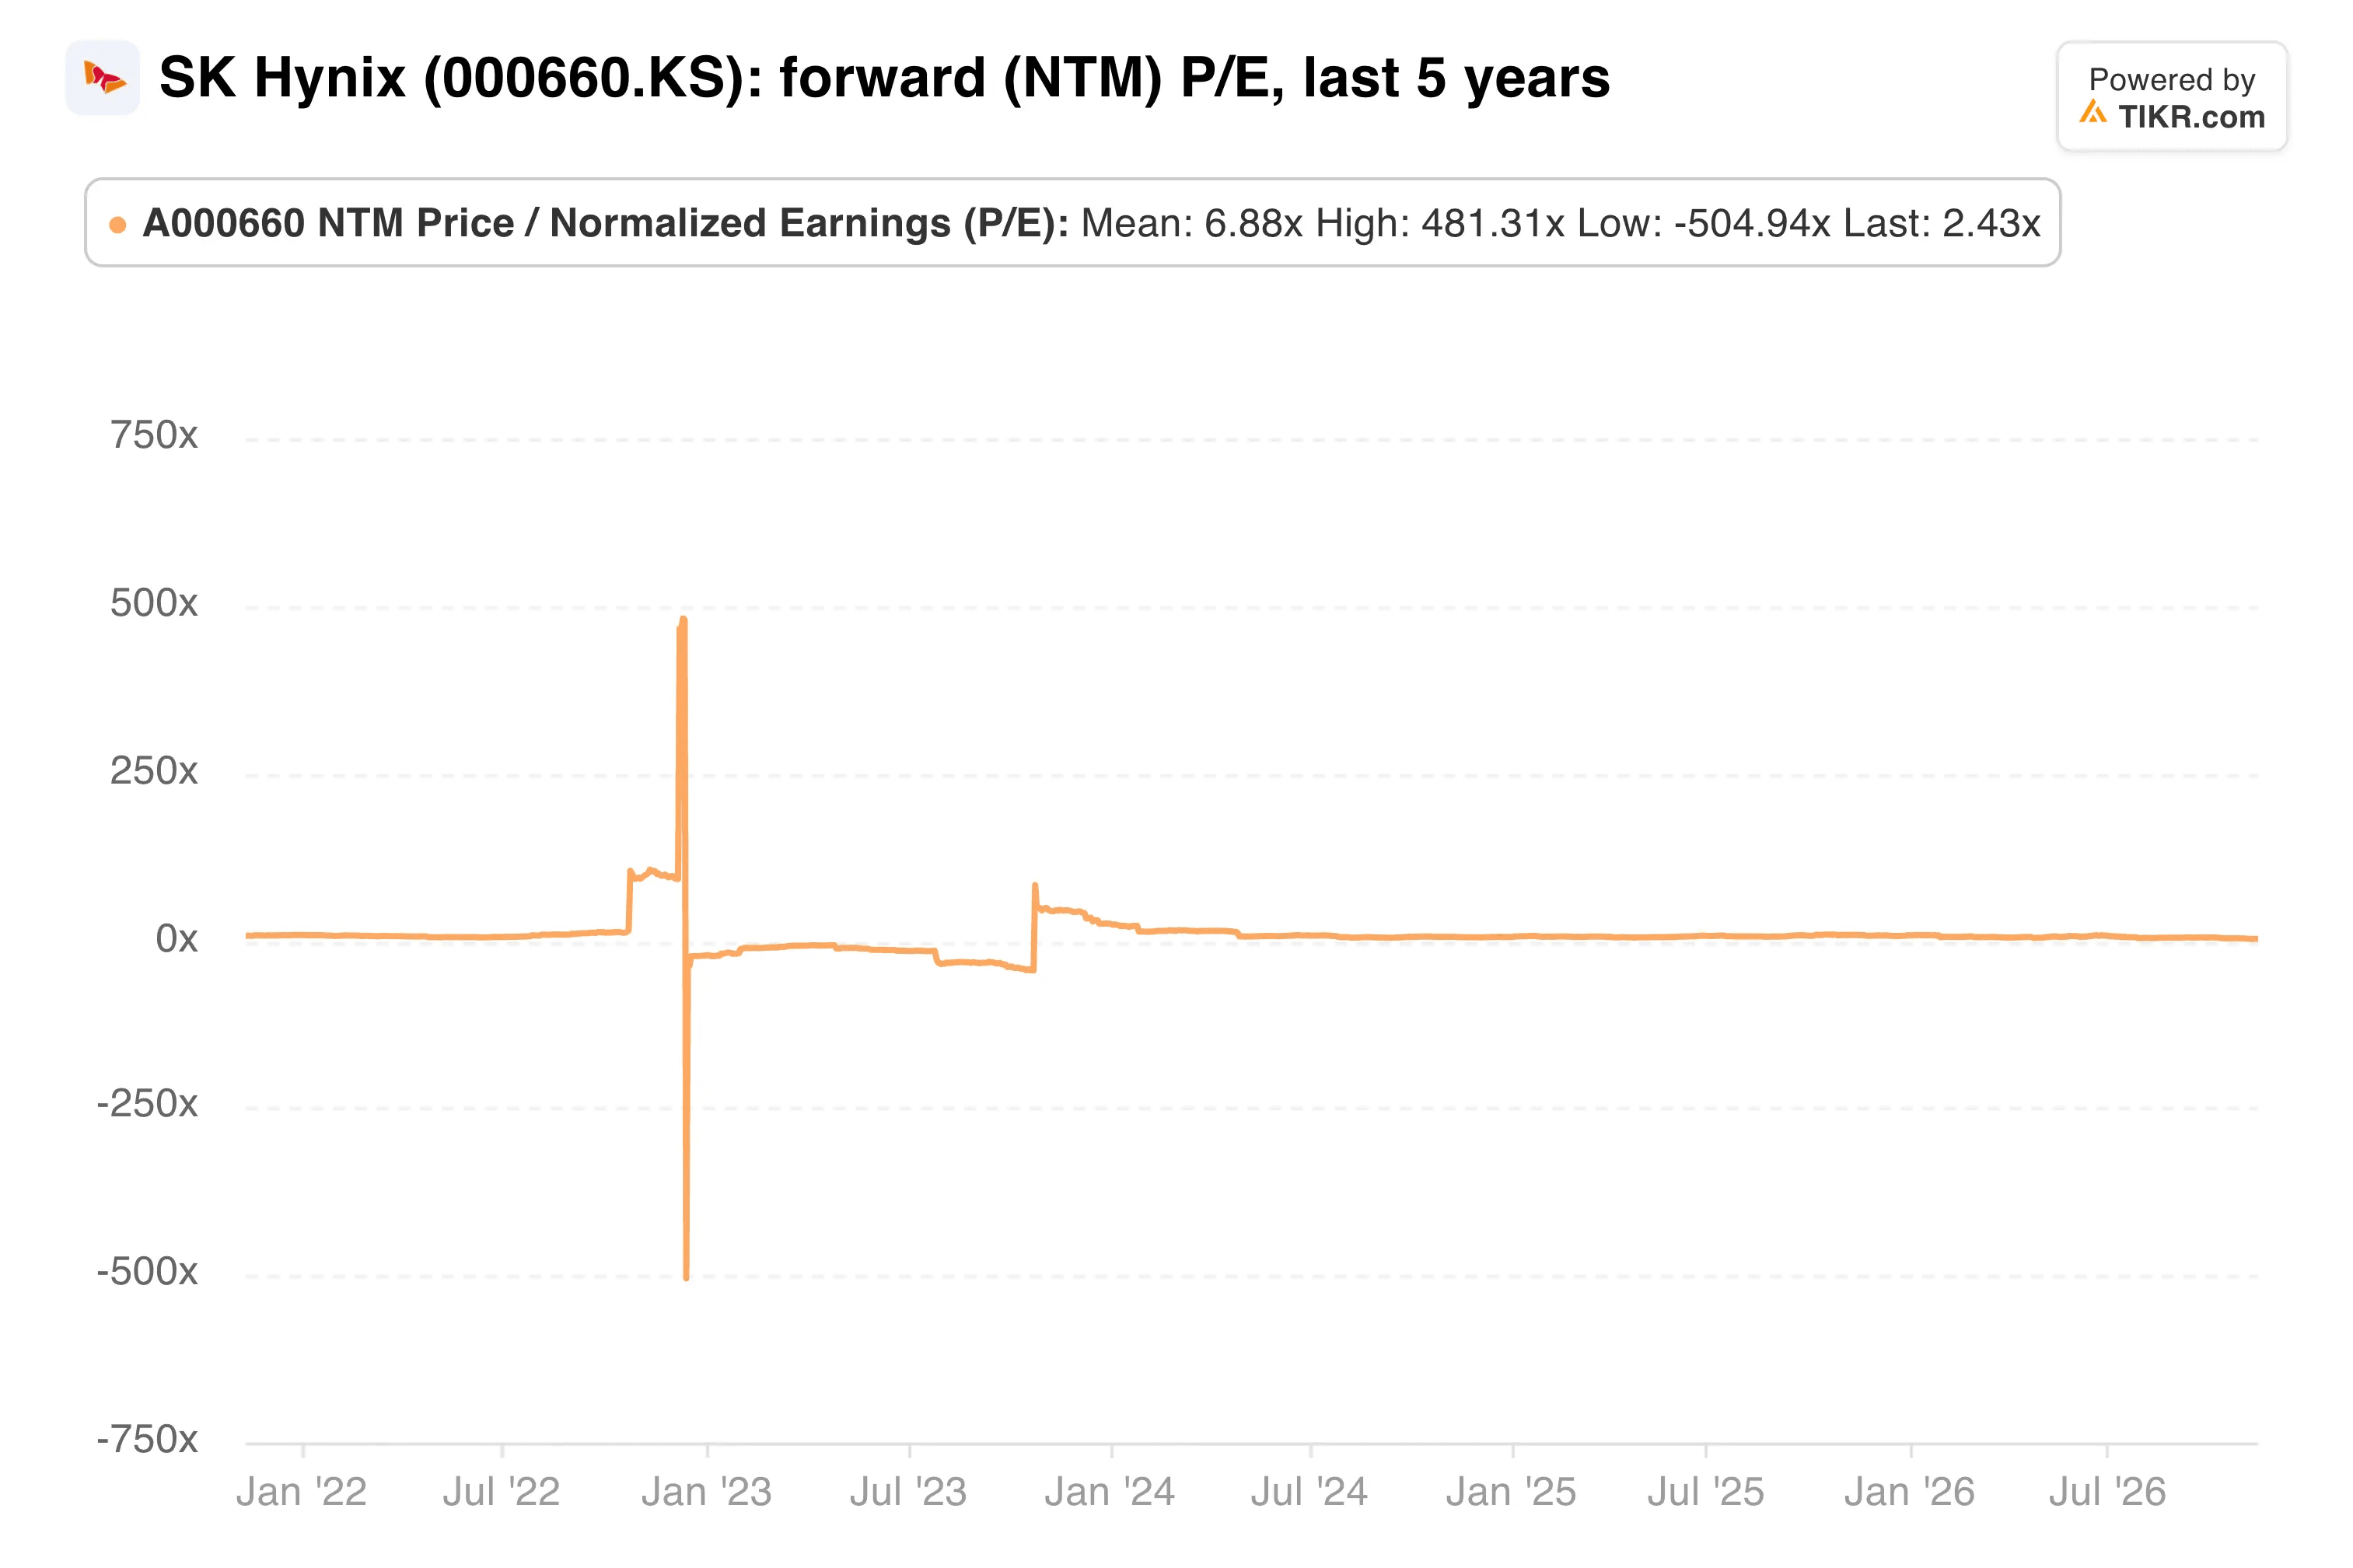
SK Hynix fits that pattern, with its forward multiple compressed sharply since September.
My take: The market is pricing SK Hynix as if 80% margins must collapse soon. Contracts covering over half of 2027 and 2028 make that harder to justify, although memory cycles have humbled confident bulls before. I’d lean toward holding, because the balance sheet and buybacks cushion the downside while the Dalian fight plays out.
The next checkpoint is fourth-quarter results, expected in late January. They should show whether HBM4 really took over and whether margins held near 80%.
So what is SK Hynix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SK Hynix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!