Key Takeaways
- GE Vernova is up 44% over the past year after raising its 2026 guidance three times, with free-cash-flow guidance going from $5.0-5.5 billion to $16-17 billion.
- Since July the stock has lost about a third on data-center fears that came from outside the company, and Vertiv and Bloom Energy fell in the same selloffs.
- Customer down payments supplied most of the third quarter’s free cash flow, so a pullback in data-center spending would hit the cash first.
- The forward P/E is near its lowest point in a year while estimates keep rising, so the stock looks like a buy, and the late-January fourth-quarter report is the next test.
GE Vernova (GEV) stock is up 44% over the past year, and the business behind it has gotten better every quarter. Even so, the shares sit about a third below their July high after a run of outside data-center scares.
The same scares hit Vertiv (VRT), up 24% over the past year, and Bloom Energy (BE), up 85%.
Three raises in three quarters
GE Vernova raised its 2026 guidance with each of its last three reports. Its free-cash-flow guidance went from $5.0-5.5 billion to $16-17 billion. Third-quarter orders rose 96% organically to $29.3 billion, which took the backlog to $197 billion. Gas equipment under contract reached 122 gigawatts, up from 83 at the end of 2025.
Analysts have raised their numbers too. Their 2027 normalized EPS estimate has climbed from $18.38 at the end of September 2025 to $26.06. They also expect earnings to more than double from 2026 to 2028:
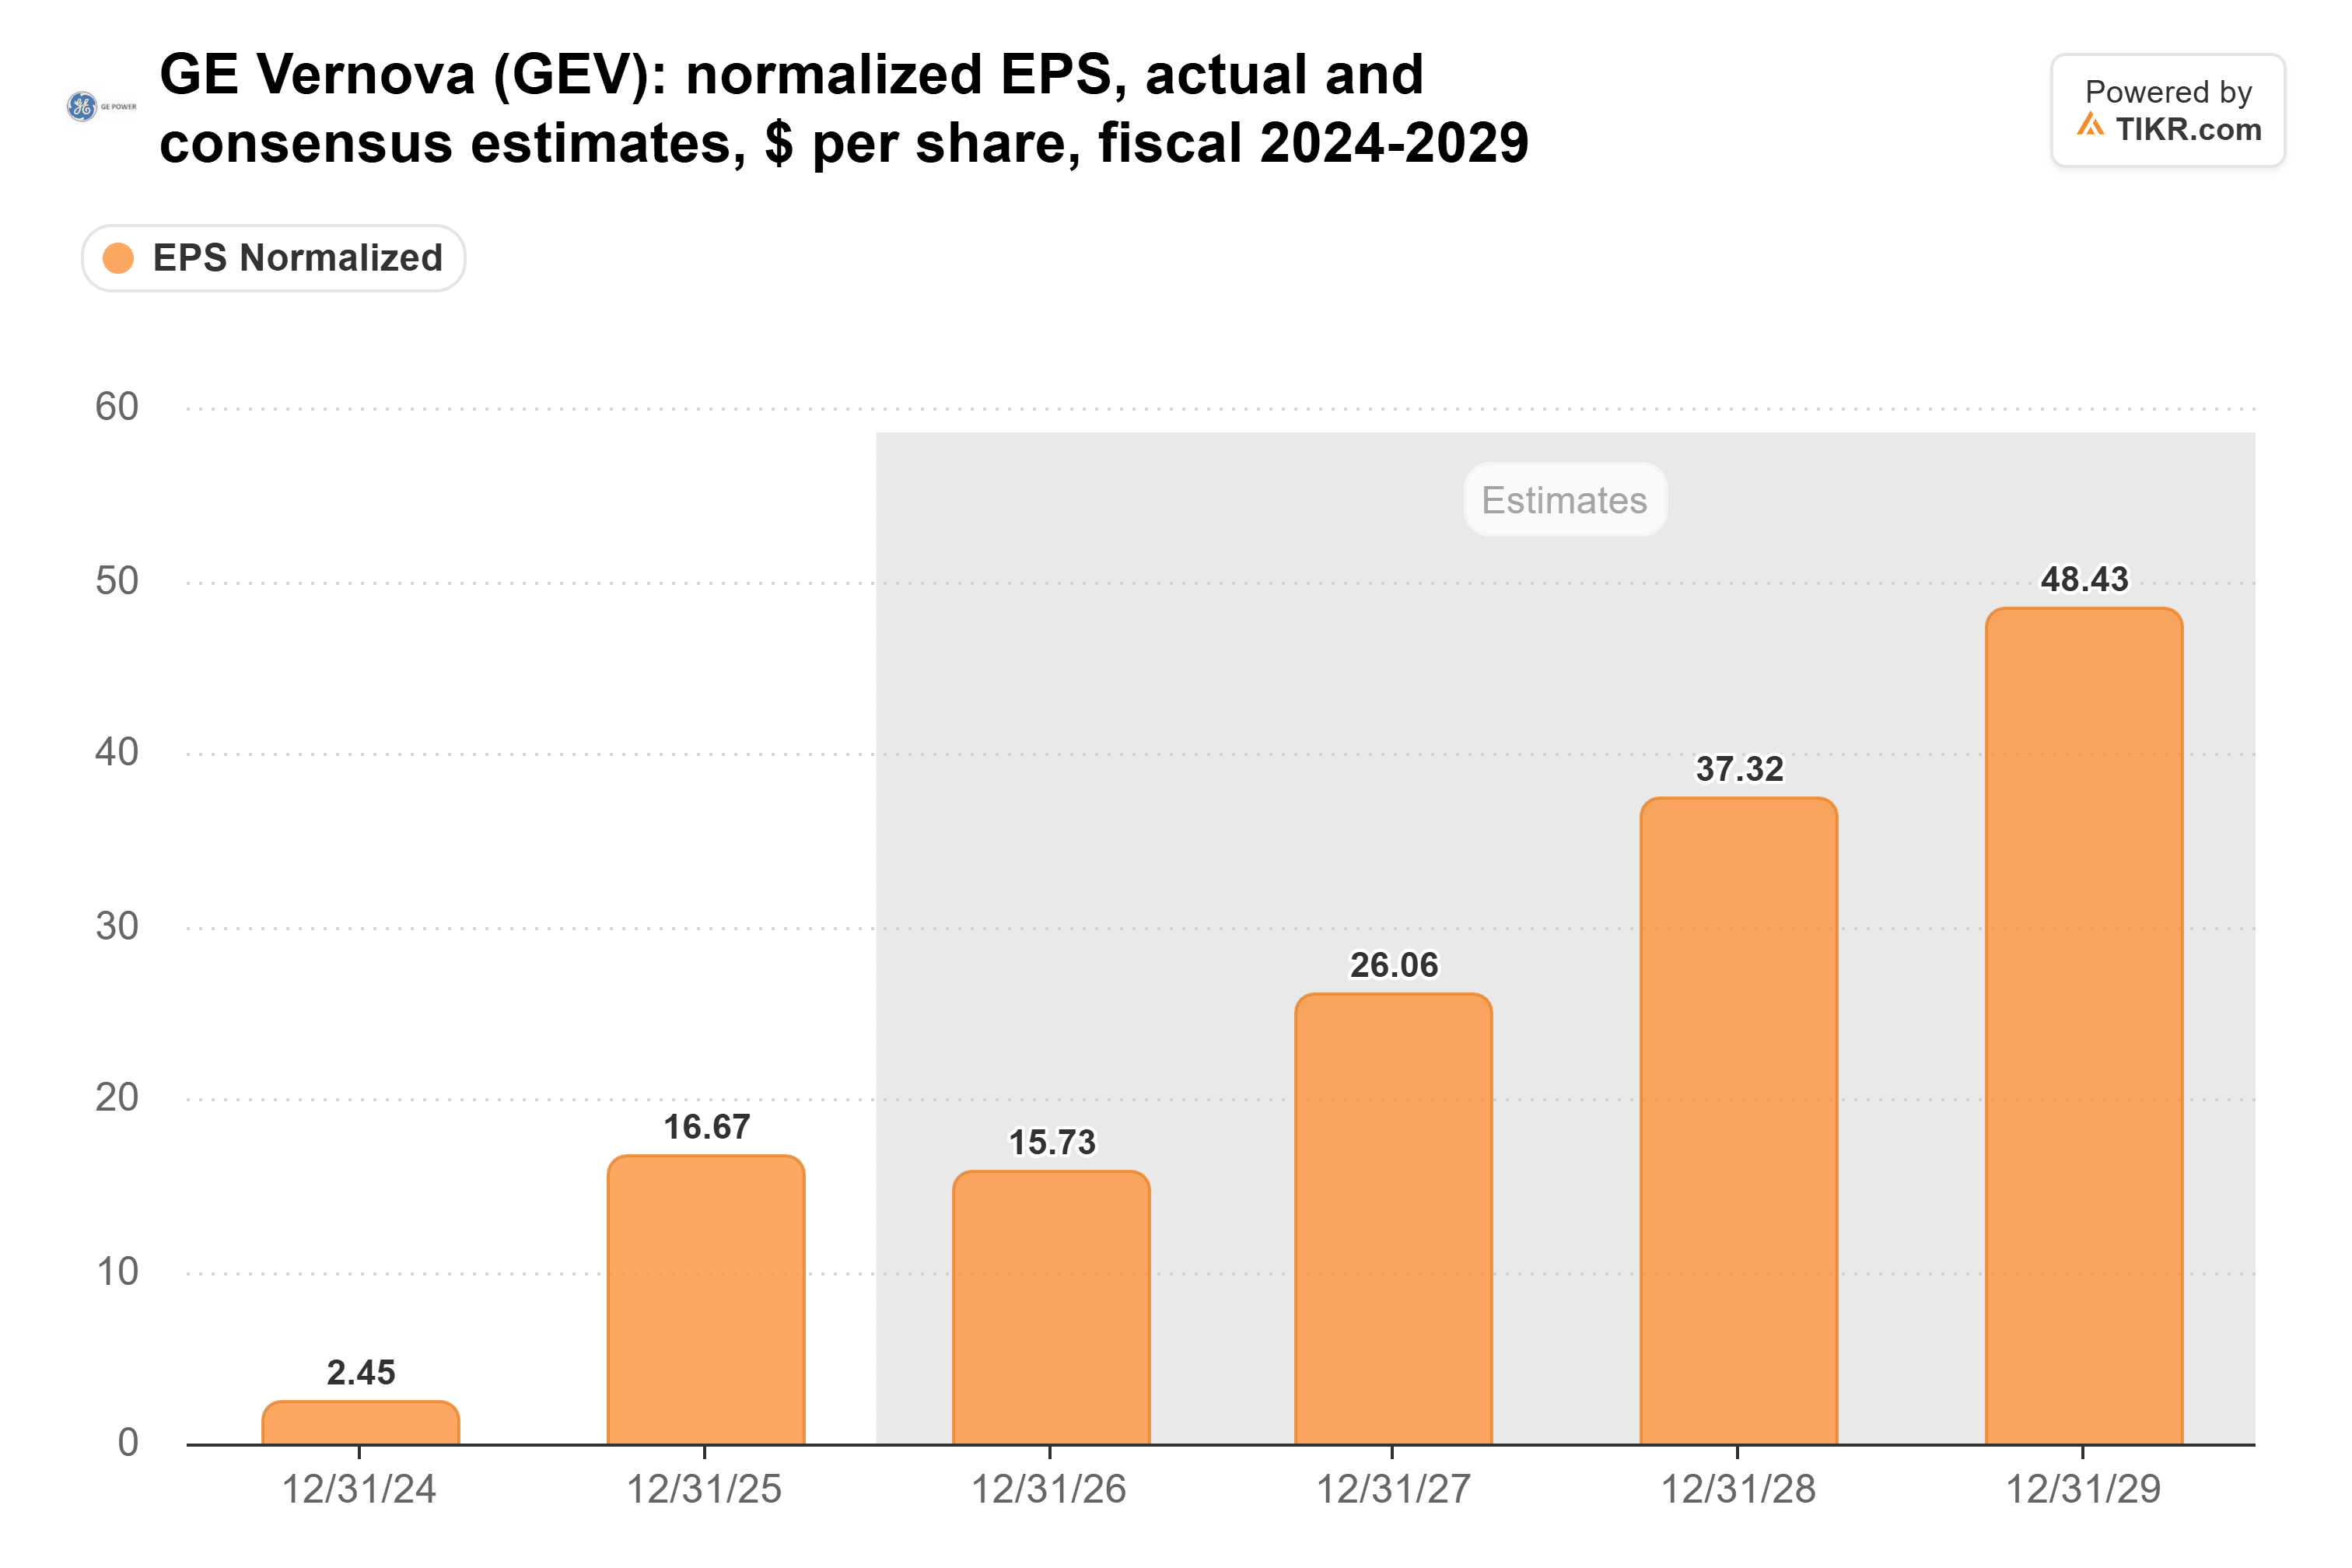
(2025’s $16.67 includes a $2.9 billion tax benefit, which makes 2026 look flat when it isn’t.)
TIKR tracks 38 analysts on GE Vernova. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on GE Vernova, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See GE Vernova’s Analyst Ratings
Every scare came from outside the company
On Oct. 21, Meta reported negative free cash flow of $2.12 billion and raised the low end of its 2026 capex range. AI power stocks sold off the next day. Then Democrats won both chambers of Congress on Nov. 3. Texas’s governor-elect, Gina Hinojosa, pledged to pause new data-center approvals.
SoftBank came next. It had reserved turbines from makers including GE Vernova for a 9.2-gigawatt gas plant in Ohio, and Elon Musk posted on Nov. 6 that “SoftBank is defaulting on their turbine orders.” SoftBank took a $3.7 billion power-equipment charge on Nov. 10, but its CFO, Yoshimitsu Goto, told analysts there was no default. Even the whole Ohio plant would be well under a tenth of GE Vernova’s 122 gigawatts. Management says data centers make up about 20% of its contracted gas gigawatts.
Vertiv’s third-quarter revenue rose 61% to $4.31 billion. However, it no longer reports orders, so its next report is the first real test of demand. On Nov. 2, just before the selloff, Bloom signed a nonbinding agreement with California Resources. The two will evaluate at least 1 gigawatt of fuel-cell projects.
A cash flow boom with a catch
GE Vernova brought in more free cash flow in each quarter of this year than in all of 2025: $4.8 billion, $5.1 billion and $5.4 billion, against $3.7 billion. Free cash flow only turned positive in 2023:
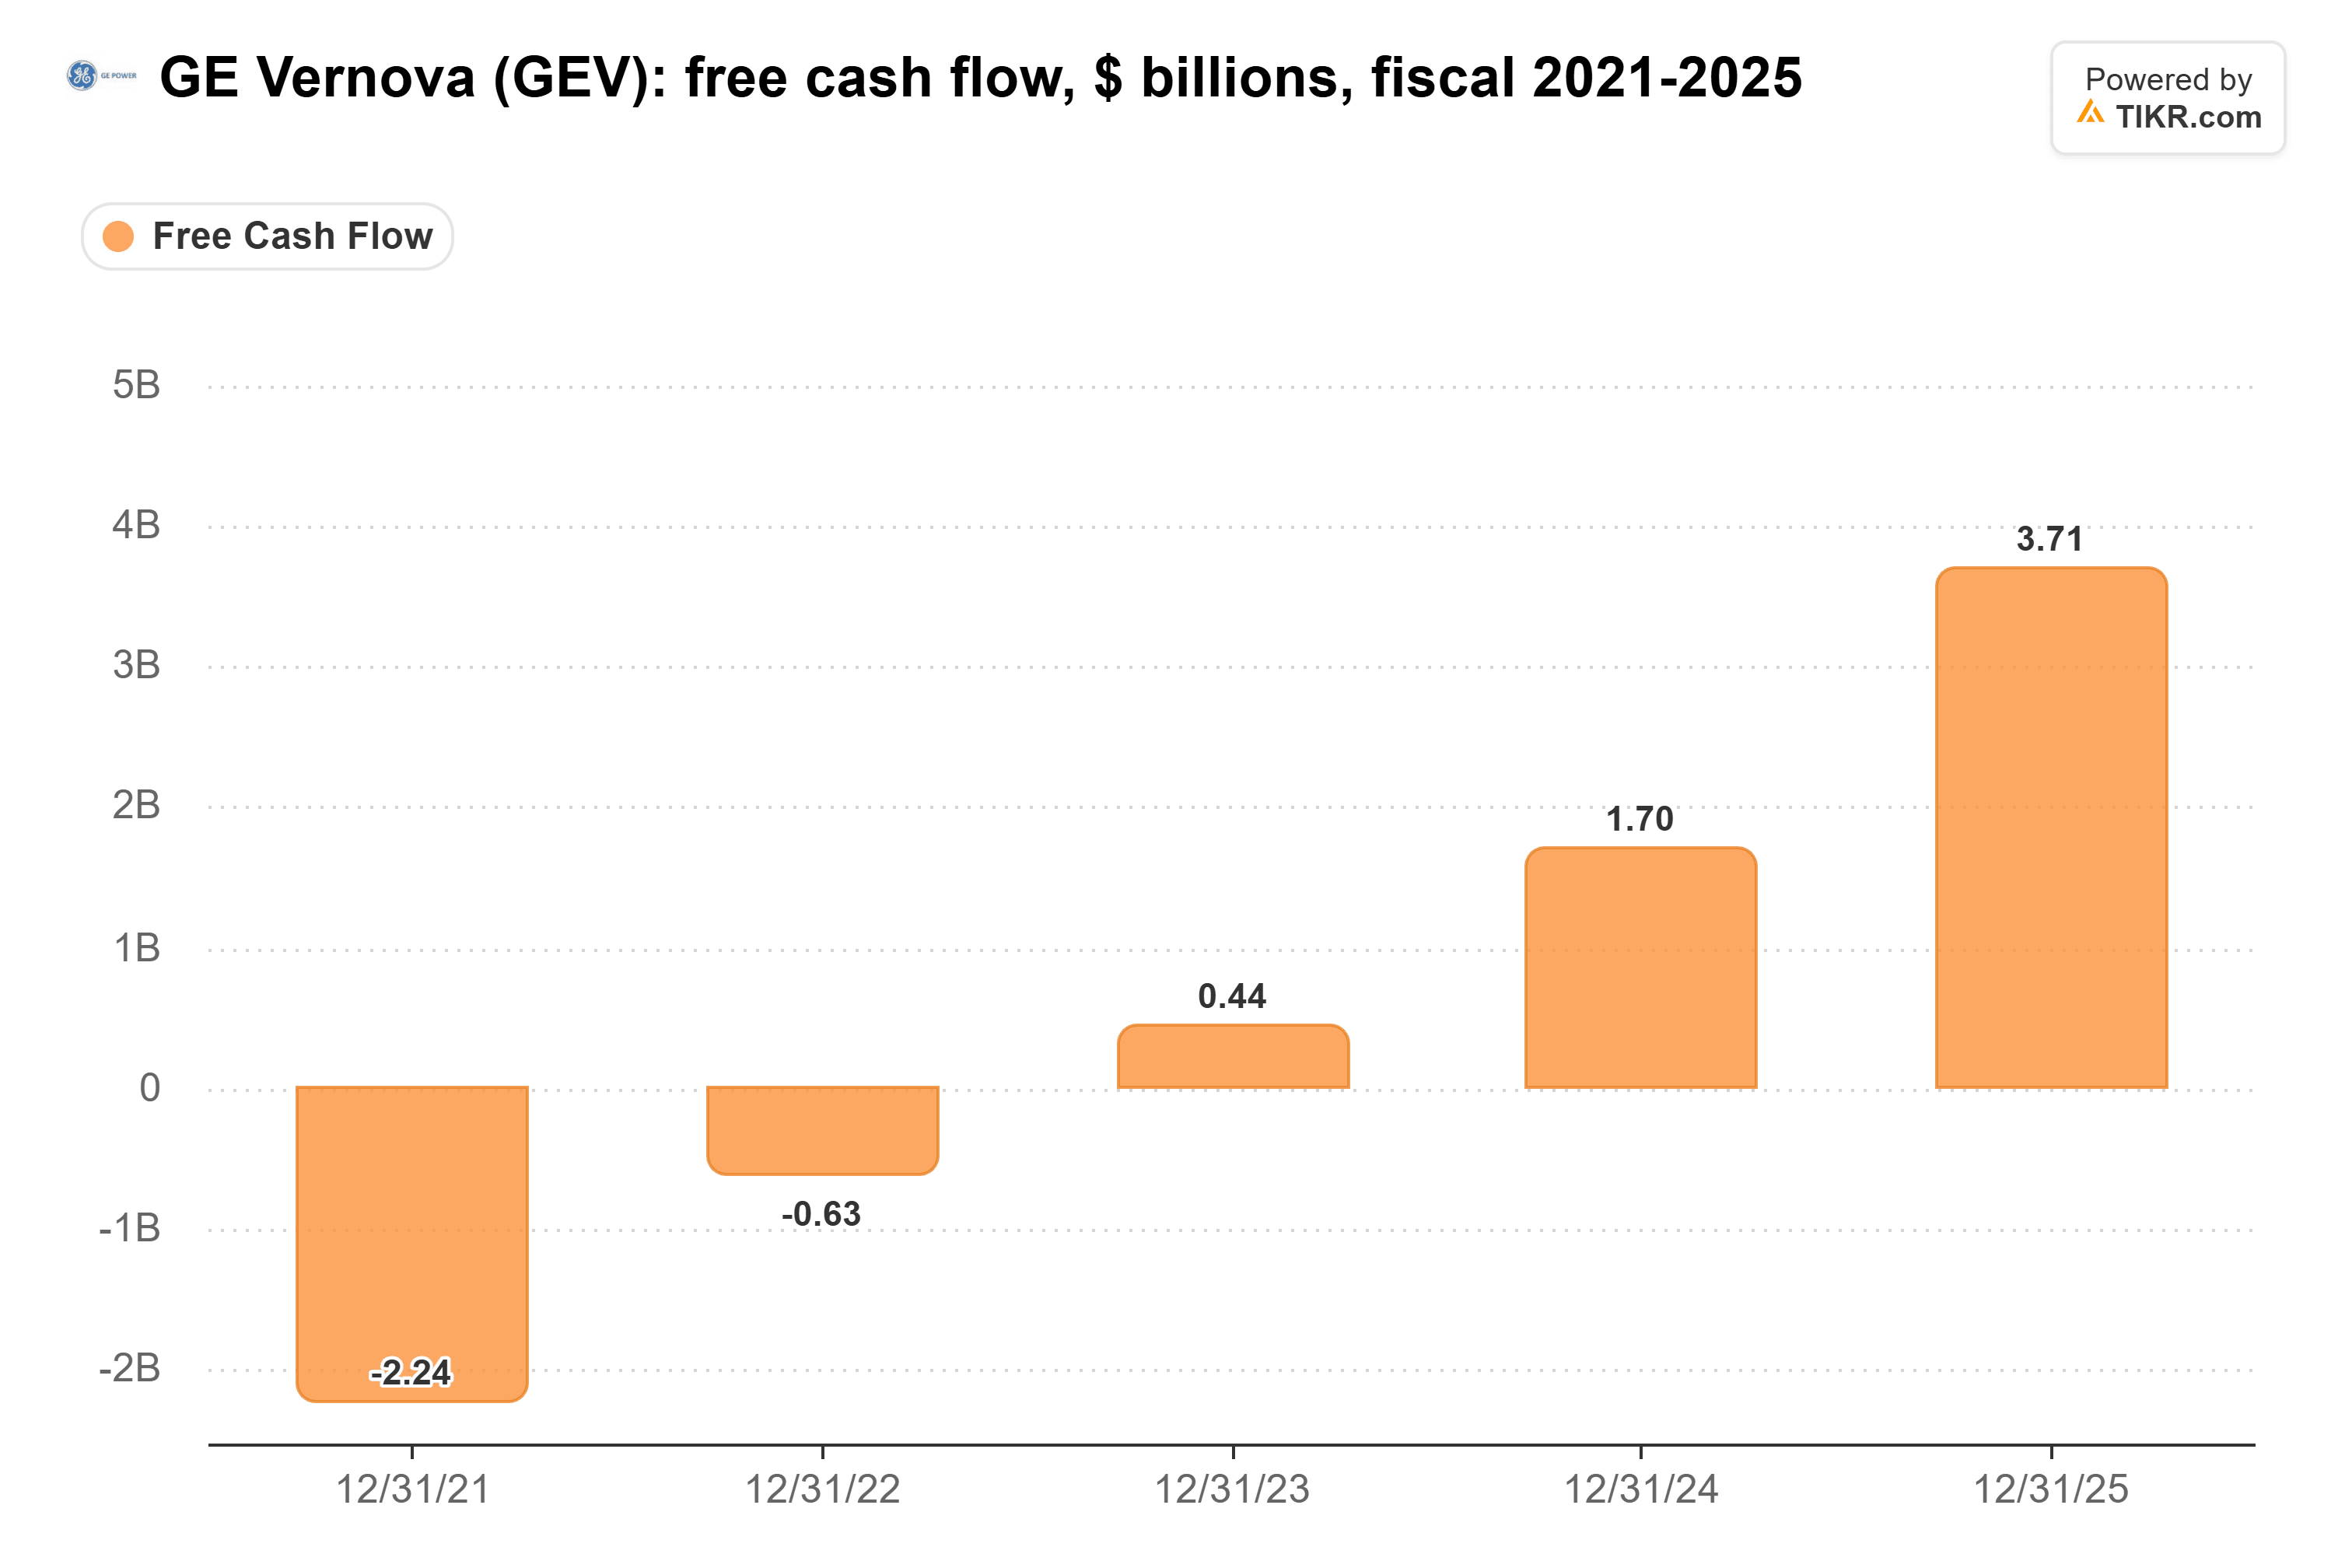
Most of that cash came from customers. Working capital, mostly down payments, supplied $5.3 billion of the third quarter’s $5.4 billion, so a pullback in data-center spending would hit the cash first. (At least those deposits are nonrefundable.) The quarter had weak spots too. Electrification orders fell 9% organically against big orders a year earlier, and Wind’s loss guidance widened to $400-500 million.
Cheaper than it’s been all year
Estimates went up while the stock went down, and that cut the multiple in half. GE Vernova trades at about 35x forward earnings, down from 70x in April and well under its 54x average over the past year:
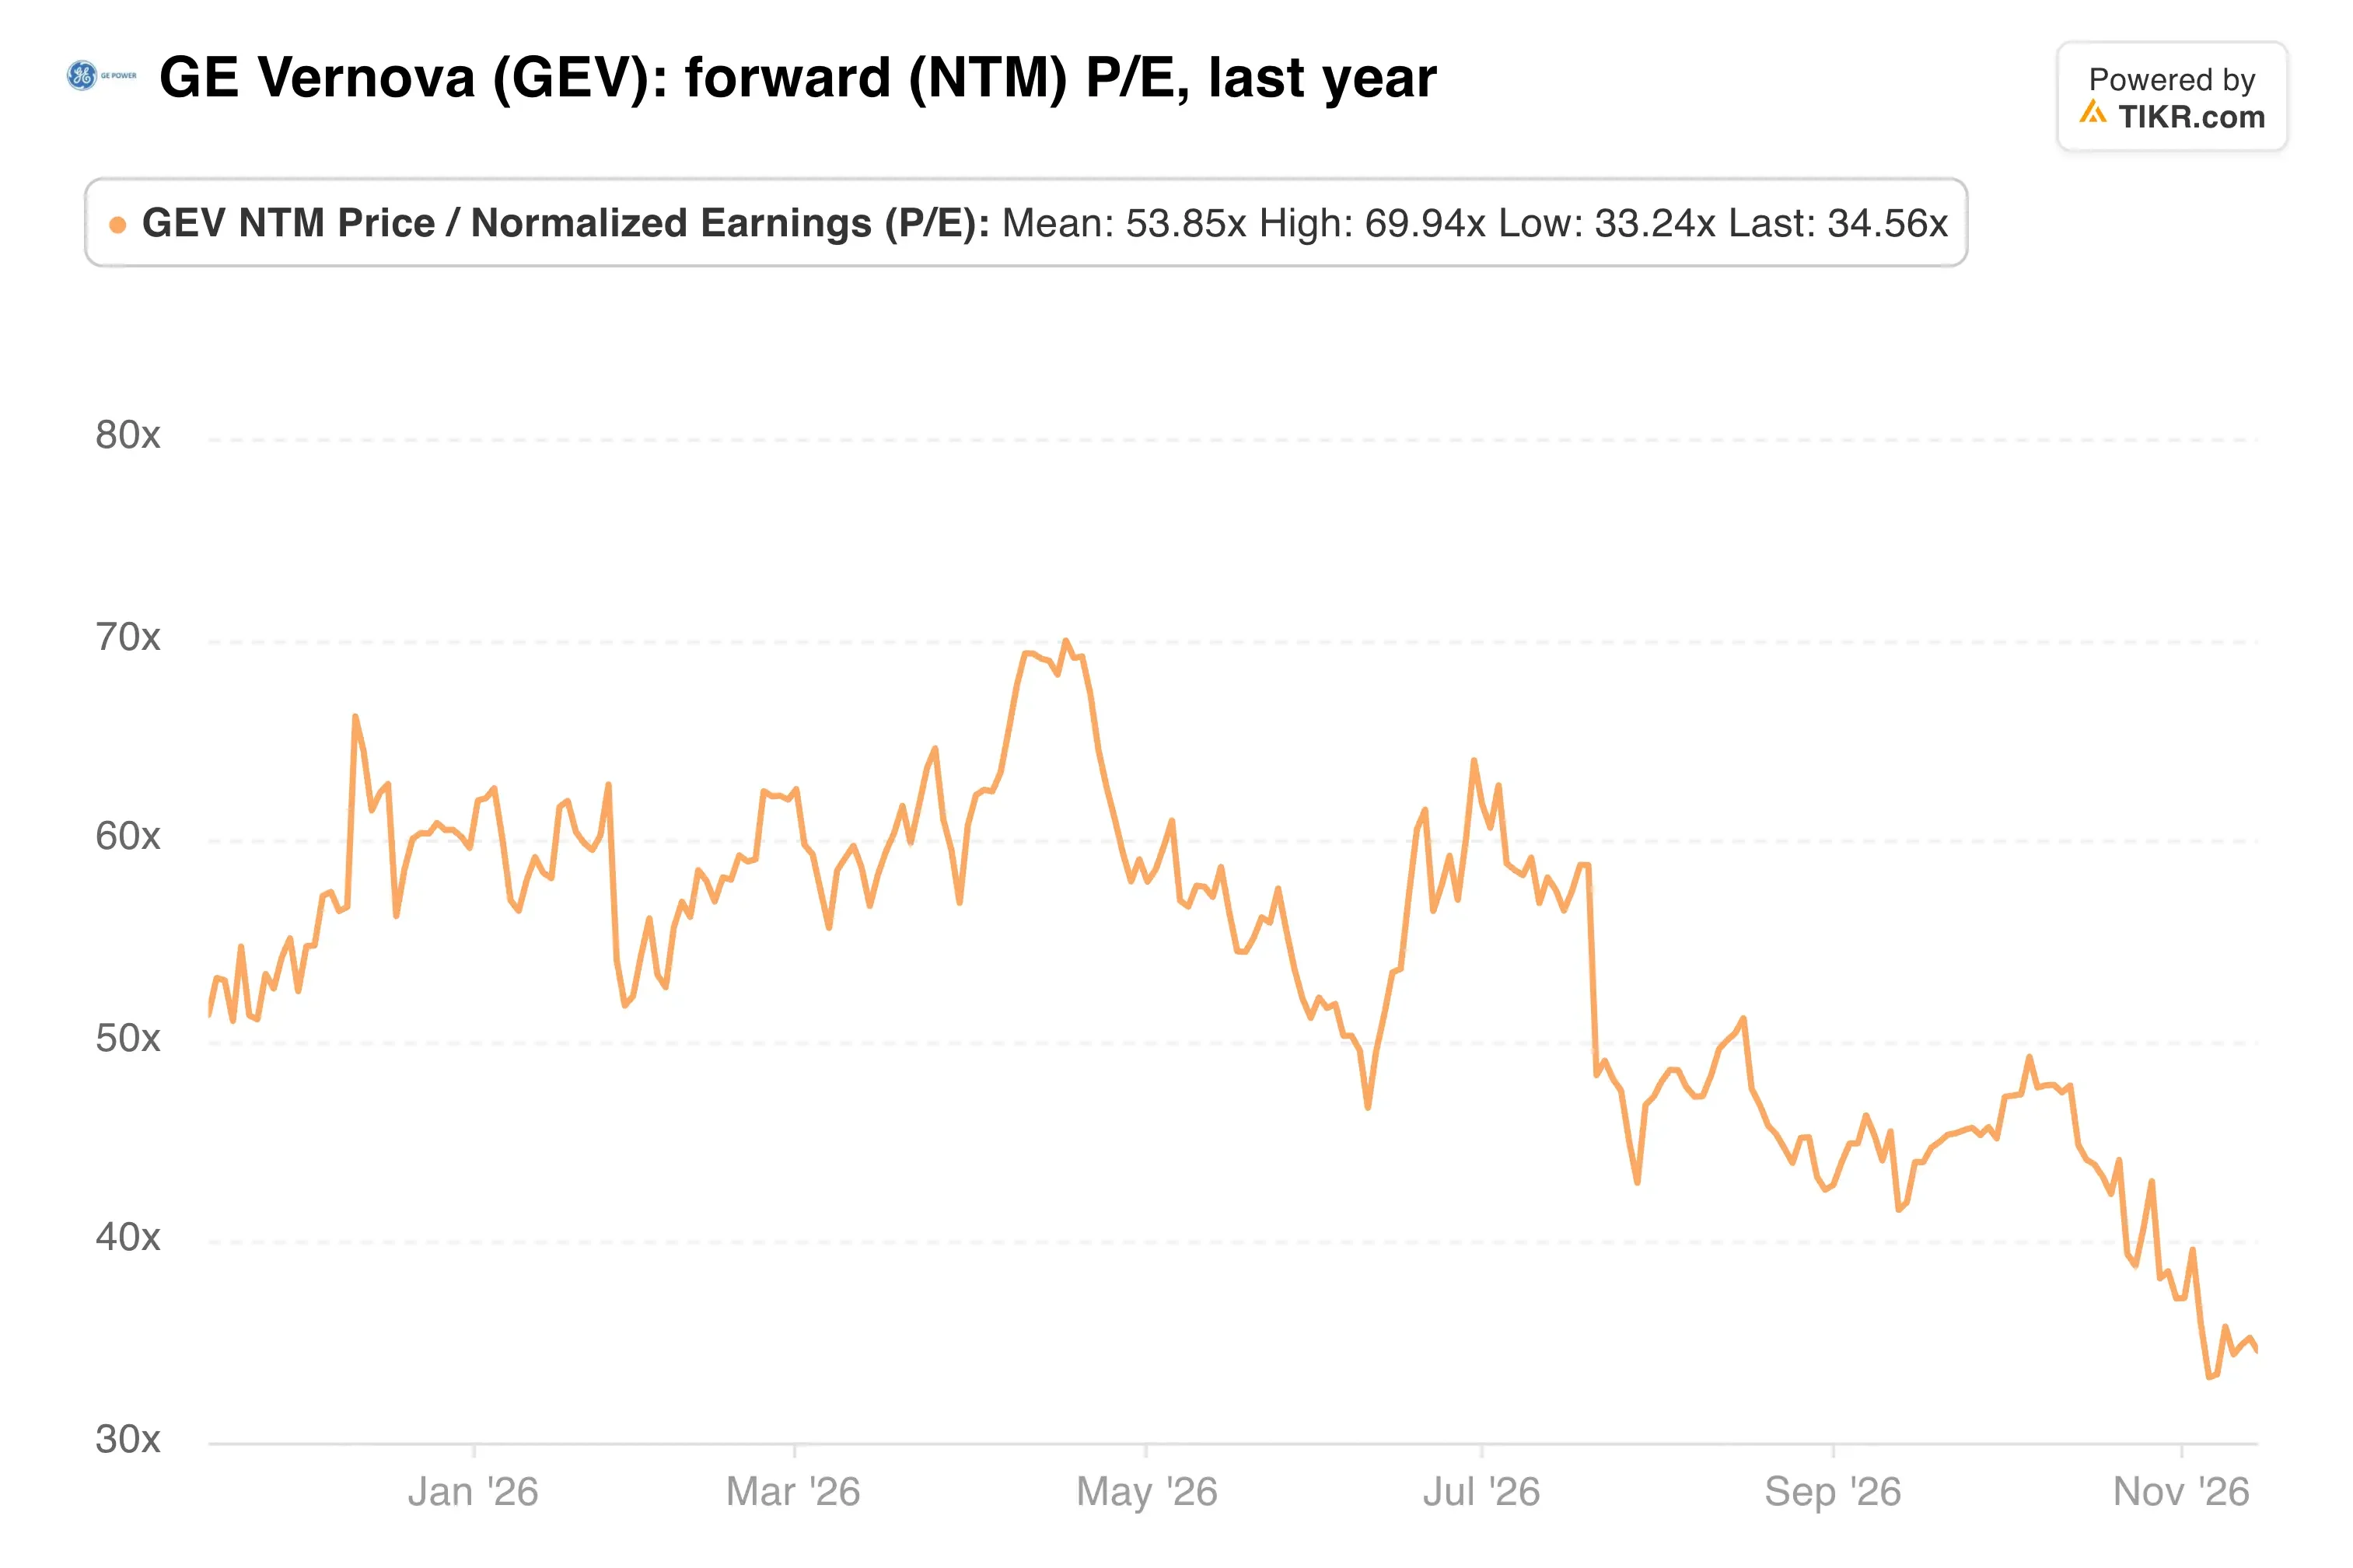
The consensus price target from 32 analysts is $1,182, about 47% above its latest close. Each big turbine it ships also brings decades of service work. On the third-quarter call, CEO Scott Strazik said, “we expect every gigawatt of HA to generate half a billion dollars of high margin services revenue over the first 20 years of its lifetime.”
Bottom line: it isn’t too late. The stock trades at half its April multiple even though estimates are higher. The next test is the fourth-quarter report in late January. Management expects the backlog to top $200 billion and gas equipment under contract to reach at least 130 gigawatts by year-end. That report will also show whether SoftBank or Texas cost it any data-center orders.
So what is GE Vernova stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what GE Vernova could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!