Key Takeaways
- Truist cut its Affirm price target to $86 from $88 on Nov. 17 and kept its Buy rating. The new target is still 45% above the stock.
- Truist blamed lower valuations across fintech lenders for the cut, and in the same note it raised its December-quarter volume growth estimate for Affirm to 35%.
- Affirm is 31% below its 52-week closing high after a quarter in which volume grew 34% but delinquencies rose to 2.9%.
- The $86 target is about 20x forward earnings estimates, below the 28x Affirm has averaged since September 2024, so Truist looks conservative as long as credit holds up.
Affirm (AFRM) reported one of its strongest quarters on Nov. 5, yet the stock closed at $59.44 on Nov. 17, 31% below its 52-week closing high. That day, Truist cut its price target to $86 from $88 and kept its Buy rating, which still leaves 45% upside.
Everything grew, including delinquencies
Affirm’s quarter to Sept. 30 was strong almost everywhere. Gross merchandise volume (GMV) grew 34% to $14.4 billion. Revenue less transaction costs came to $617 million, or 4.3% of GMV, above the top of management’s 3.75% to 4% medium-term range.
Credit was the weak spot. The share of monthly installment loans 30 or more days past due (excluding Peloton and Pay-in-X loans) rose to 2.9%. That’s up 35 basis points from the June quarter and 9 from a year earlier.
Truist raised its growth estimate anyway
Going into the report, Truist analyst Matthew Coad’s estimate already matched the top of Affirm’s 30% to 32% GMV growth guide for the December quarter. He raised it to 35% after CFO Rob O’Hare said growth was running “at a high 30s rate” in October. Truist says the lower target reflects lower target multiples for most fintech lenders. Cantor Fitzgerald also cut its target, to $84 from $97 on Nov. 9, and RBC Capital cut to $83 from $96 on Nov. 6.
TIKR tracks 36 analysts on Affirm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Affirm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Affirm’s Analyst Ratings
$86 doesn’t ask for much
Wall Street’s average target is about where it was a year ago, even though the stock has fallen:

That $96 consensus is 61% above the price. Analysts have also raised their normalized EPS estimates over the past three months: to $3.96 from $3.72 for fiscal 2027 (the year to June), and to $5.06 from $4.73 for fiscal 2028:
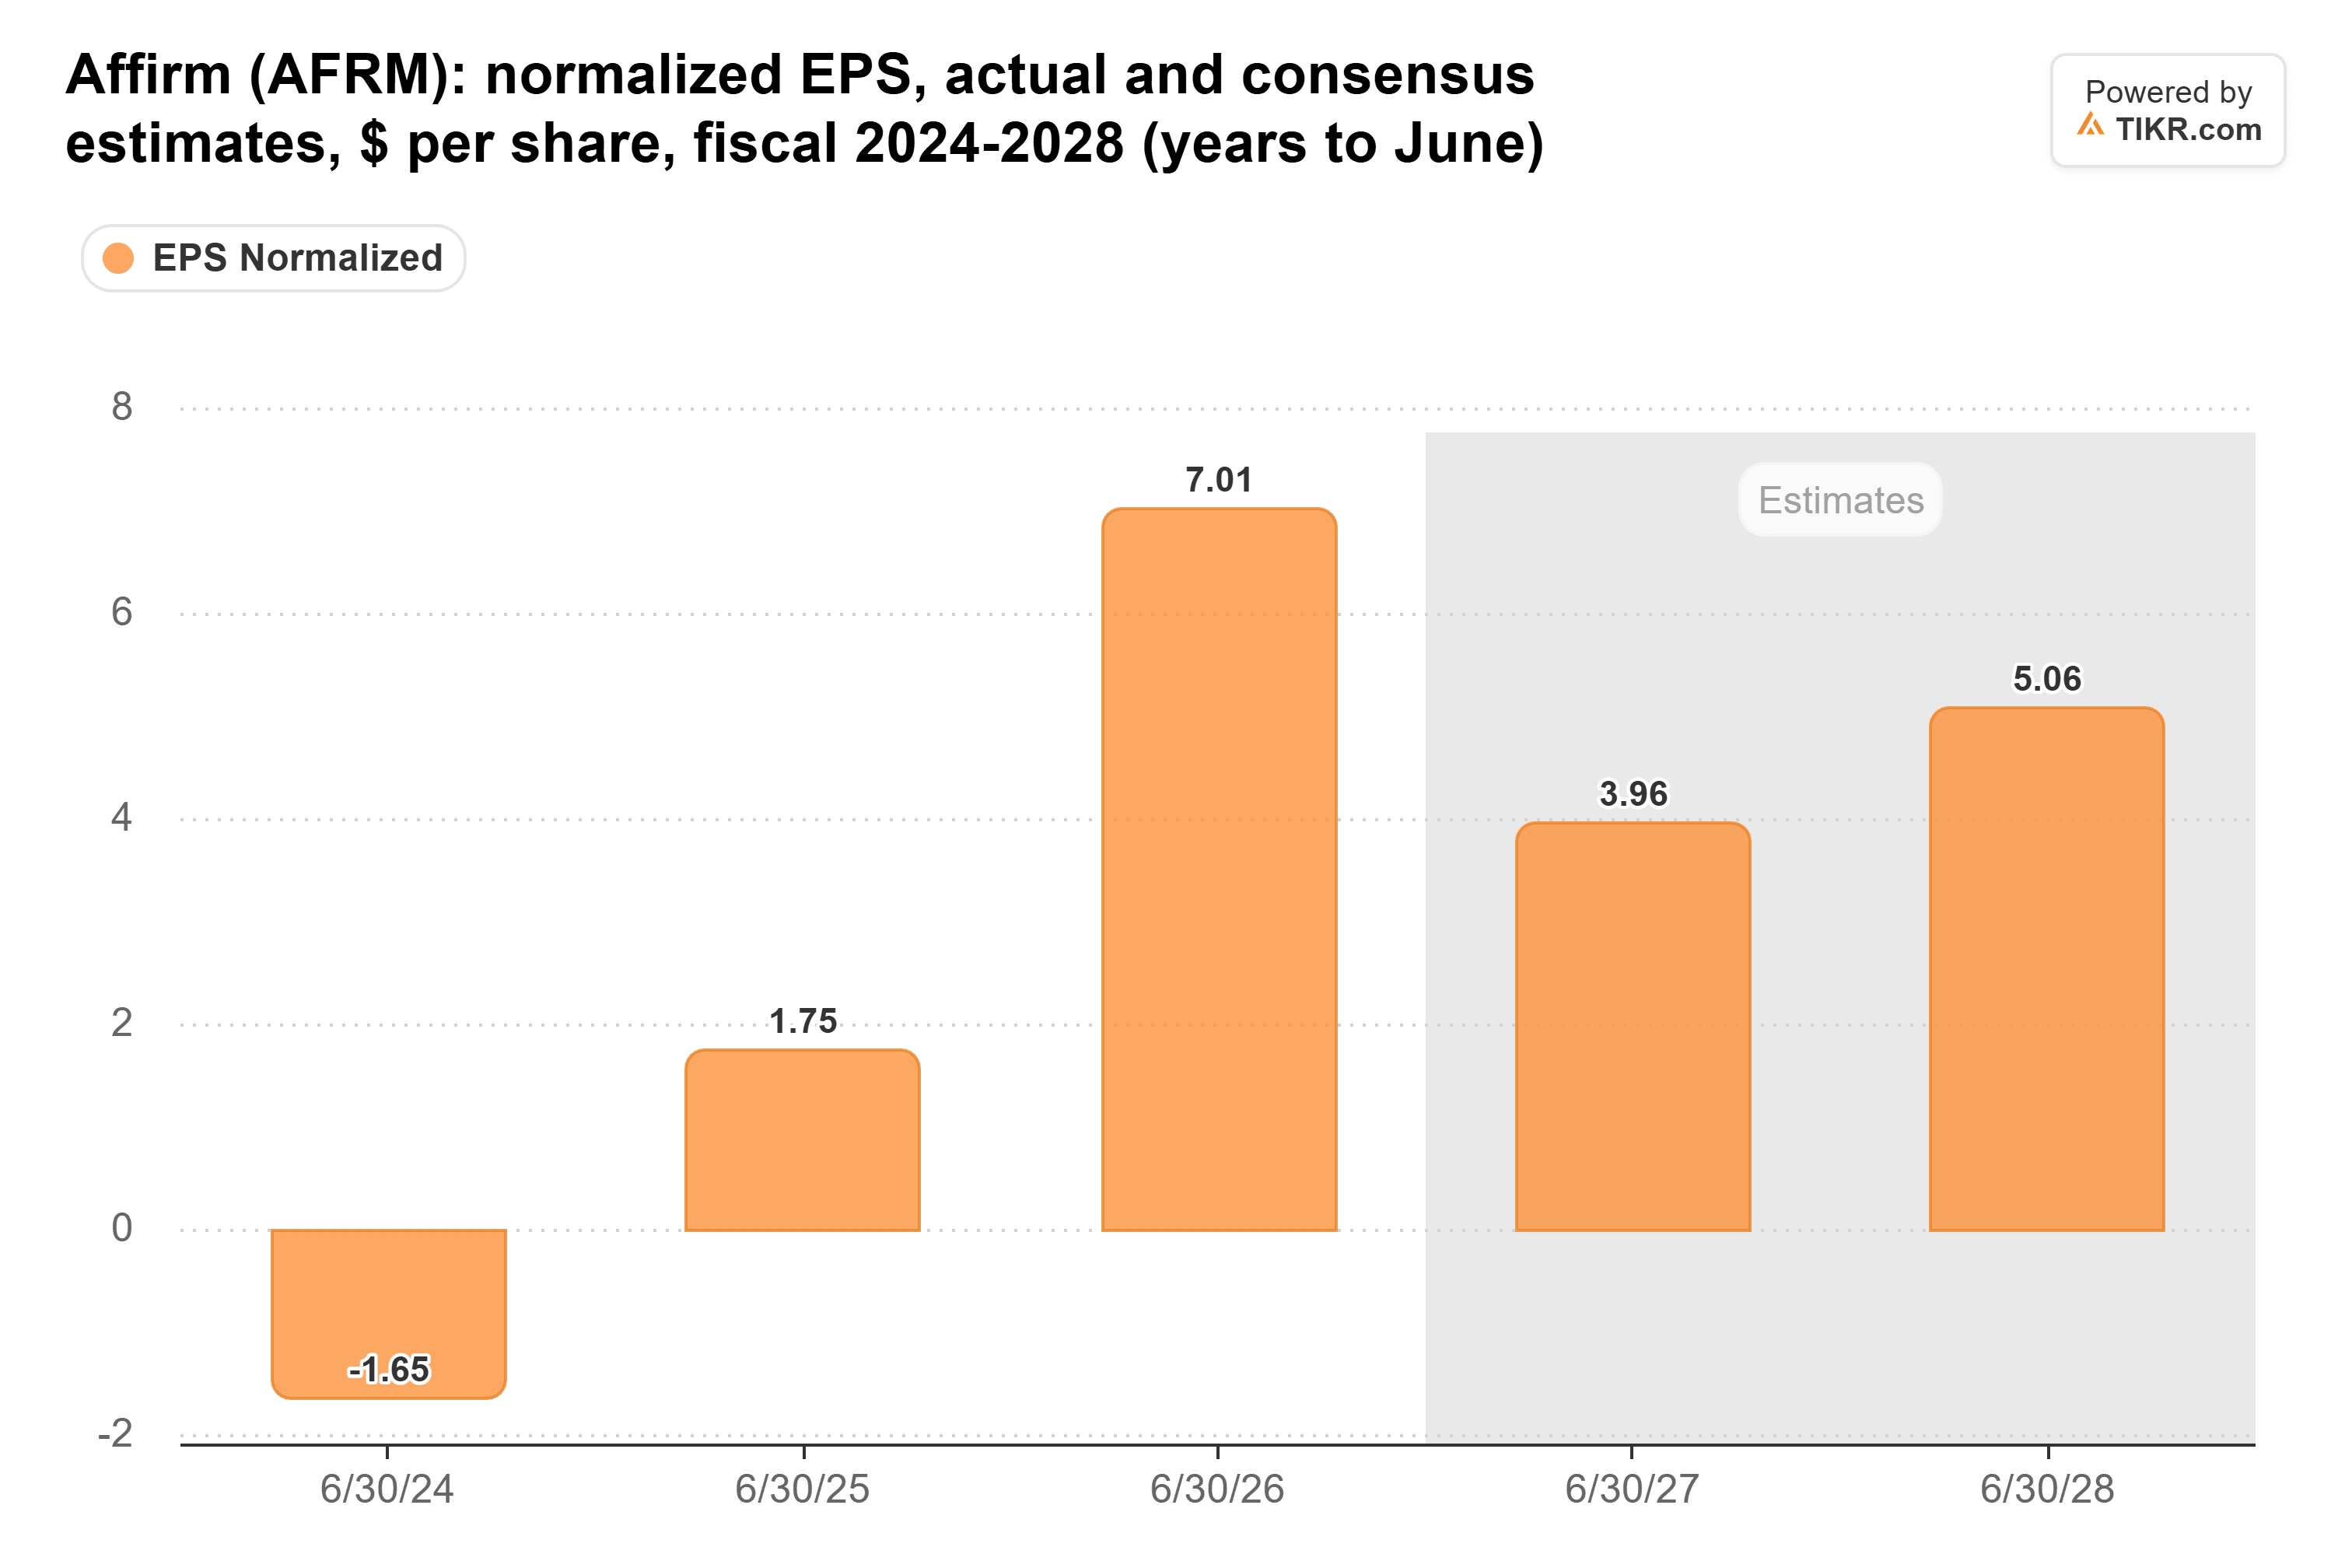
(Fiscal 2026’s $7.01 includes a one-time, non-cash tax benefit of about $1.4 billion.)
At $86, Affirm would trade at about 20x estimated earnings for the next 12 months, against about 14x at the Nov. 17 close. Since its forward P/E turned positive in September 2024, the stock has averaged 28x at quarter-ends, with a low of 12x in March 2026. On fiscal 2028 estimates, the target works out to just 17x.
Watch the delinquencies
Credit is the main risk. Delinquencies rose, funding costs climbed 27 basis points from the June quarter, and Truist’s own reason for the cut, lower multiples across fintech lenders, could keep the stock cheaper for longer.
Still, Truist’s target only asks for a below-average multiple on estimates that are still rising. The next test is the December-quarter report, expected in early February. A clean print would show GMV growth near Truist’s 35%, revenue less transaction costs at 4% of GMV or more, and delinquencies up no more than 9 basis points from a year earlier.
So what is Affirm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Affirm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!