


Key Takeaways
- Meta has reportedly cut the number of employees using Anthropic’s Claude Code in half, from about 60,000 earlier this year to about 30,000, and is moving staff onto its own coding tools.
- This is a big problem for Anthropic: it depends on a small group of large customers, and the biggest of them can now build their own models.
- Anthropic’s reported $16.8 billion third quarter showed slowing growth, and Bloomberg Intelligence’s Mandeep Singh named Meta’s new model as one possible reason.
- For Meta, the savings are small next to its $69.7 billion of capex in 2025, so Wednesday’s capex numbers and any early 2027 guidance matter much more.
Meta Platforms (META) spent much of this year as one of Anthropic’s biggest customers. Now that it has a frontier model of its own, it’s acting like it.
On a recent episode of The Ezra Klein Show, investor Paul Kedrosky made the point in passing:
“And you’re already seeing some of that with Meta cutting in half the number of developers in-house who are allowed to use external frontier tools. Microsoft, the same thing.”
He isn’t guessing, either. Earlier this month, The Information reported that Meta’s Claude Code seats had dropped to about 30,000 from roughly 60,000 earlier this year. Meta is moving engineers onto its own coding tools, MetaCode and Muse Code. Microsoft (MSFT) has reportedly cut its projected internal Claude spending by more than a third.
Even after the cut, Meta reportedly spent more than $105 million on Claude Code in a recent 28-day period.
That tells you how big a customer Meta was to begin with.
Meta was a whale for Anthropic
On the same episode, Kedrosky said Anthropic gave itself away when it tried to hire an account executive to handle sales to one company. People could work out that the company was Meta, and that it was “something like 10% of their revenues.”
Klein was surprised and asked whether Meta really made up 10% of Anthropic’s revenue. “That’s right,” came the answer.
The catch is that the 10% figure is from 2025. Azeem Azhar, Klein’s other guest, pointed out that Anthropic’s revenue in the first quarter of this year was bigger than all of last year’s. Meta’s Claude Code spending runs at roughly $1.4 billion a year. That’s about 2% of the yearly pace Anthropic’s latest quarter implies.
The bigger issue is how few customers Anthropic depends on. In Kedrosky’s words, “it might be eight companies that make up 80% of their revenues,” and most of them are “mostly using it for the same thing”: writing code.
Meta is part of Anthropic’s slowdown
That matters more now that Anthropic’s growth is cooling. Bloomberg reported a $16.8 billion third quarter. As Ed Ludlow put it on Bloomberg Tech, that “represents decelerating top line growth.”
Bloomberg Intelligence’s Mandeep Singh gave two likely reasons. One was Anthropic’s own crackdown on rivals training their models on Claude’s output. The other: “and also potentially Meta, which was a big customer, they have a world class model now.”
Anthropic’s biggest customers are the few companies with the cash and the talent to build frontier models of their own. Meta just showed it can, with Muse Wonder, its first frontier model.
Think of Apple (AAPL) and Intel (INTC). Apple put Intel chips in its Macs for years, until its own chips were good enough to replace them. Then it moved on.
Same deal here.
Small potatoes for Meta
What Meta saves is tiny next to what it’s spending on AI. Its capital spending nearly doubled, from $37.3 billion in 2024 to $69.7 billion in 2025:
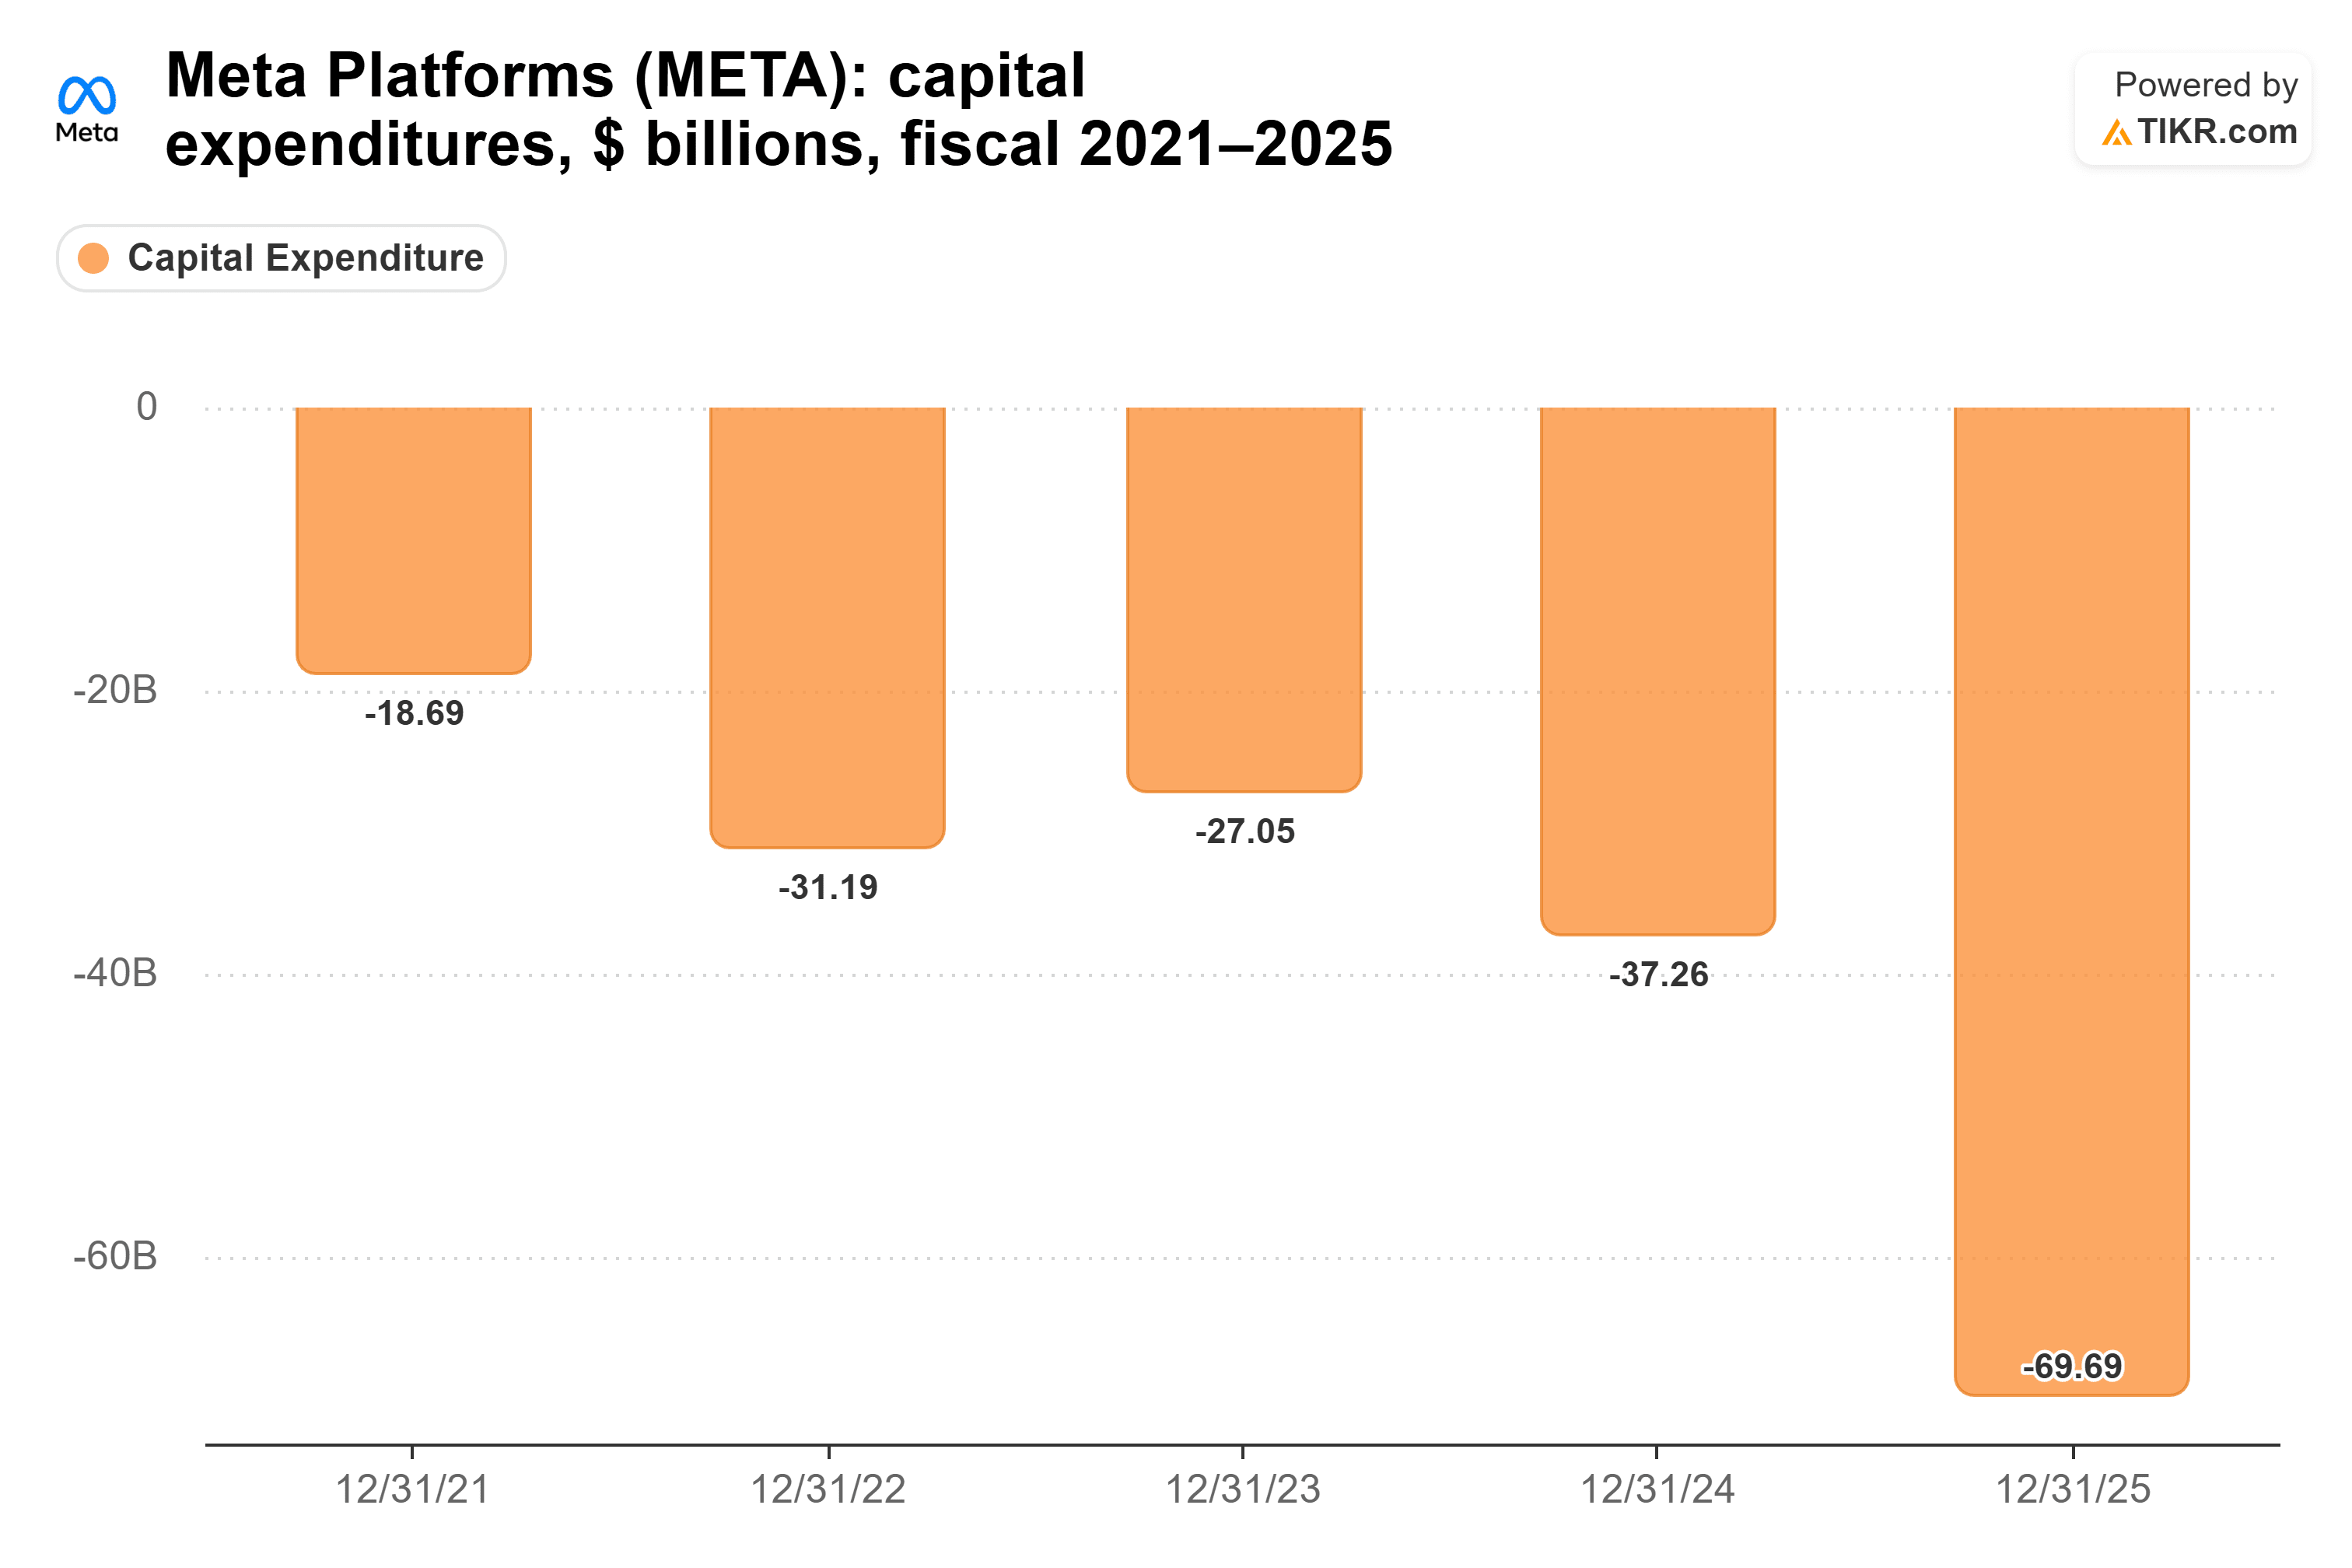
A Claude Code bill of roughly $1.4 billion a year comes to about 2% of last year’s capex. Whatever Meta saves by trimming it won’t change much in its results.
The earnings picture tells the same story.

Analysts expect Meta’s earnings to barely grow this year, from $29.68 a share in 2025 to $30.36, then pick up to $34.63 in 2027. A smaller Claude bill shouldn’t move those estimates much. Capex is what will.
Wednesday is about capex
So yes, this is a big problem for Anthropic. Meta’s Claude bill is a small slice of Anthropic’s revenue today. But Meta is the first big customer to show that a world-class model of your own makes Anthropic optional, and Microsoft is cutting back its own staff’s use too. With so much of Anthropic’s revenue coming from so few buyers, that’s a pattern investors will watch closely once it files to go public.
For Meta, it’s an easy win and evidence that its own models are good enough for its own engineers. The number that matters comes Wednesday after the close. As investor Dan Niles noted on X, Meta will probably be “the first hyperscaler to give hard initial 2027 capex/expense guidance.”
Of course, Anthropic’s other customers could more than make up the difference. Microsoft’s internal cutback was reportedly offset by more Claude use from its own customers.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


