

Key Takeaways
- Sen. Tim Kaine told the Senate Budget Committee that 37% of American seniors would be below the poverty line without Social Security, against 10% now.
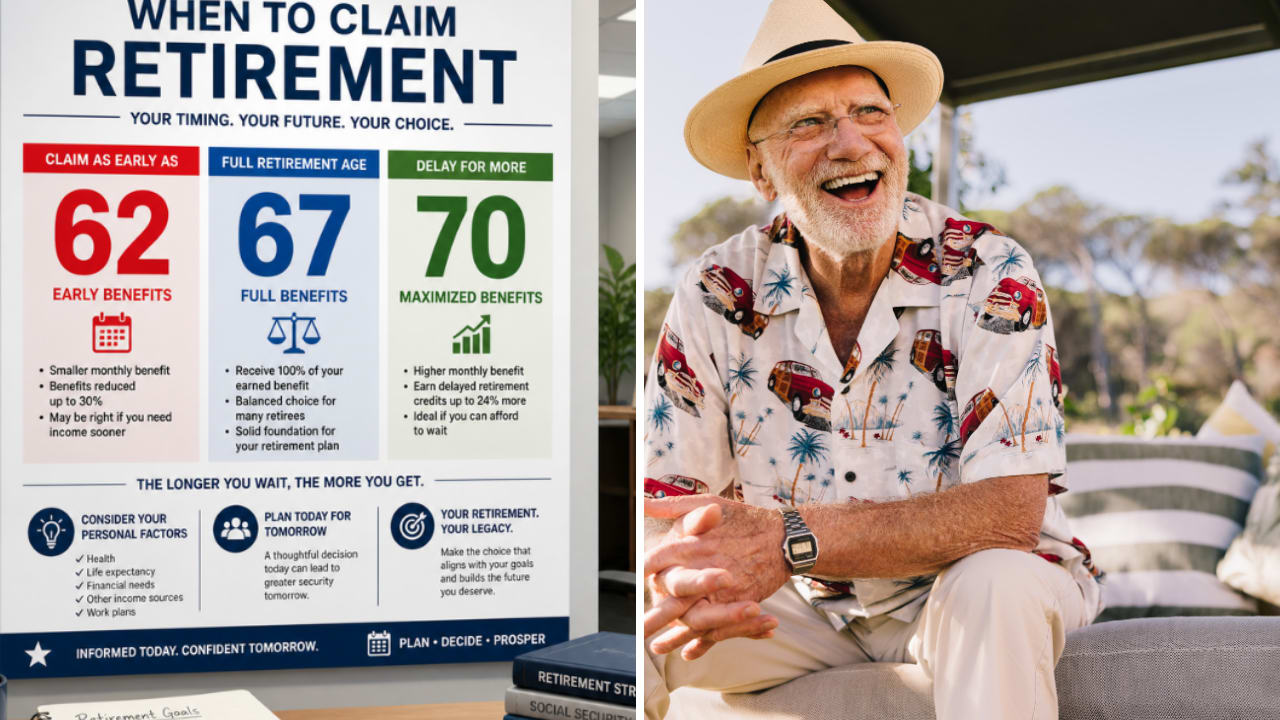
- A worker whose full benefit at 67 is $1,600 a month gets $1,120 a month by claiming at 62. That’s $13,440 a year, $2,520 under the 2026 poverty guideline of $15,960 for one person.
- Waiting until 67 pays $19,200 a year, $3,240 over the line, and waiting until 70 pays $23,808.
- If Social Security will be most of your income, check your own estimate at each claiming age before you file early.
Sen. Tim Kaine (D-Va.) made the case for Social Security at a Senate Budget Committee hearing on Wednesday with one statistic: “Without this critical Social Security program, 37% of American seniors would be below the poverty line.” With it, he said, the rate is currently 10%, which he called too high. His figures come from a February 2026 report from the Center on Budget and Policy Priorities.
If you’re nearing retirement after a modest career, I’d look hard at that 10%. Social Security on its own doesn’t promise a check above the poverty line, and a modest earner who claims at 62 can end up under it for good.
What a $1,600 benefit pays at 62
Let’s take a hypothetical: your full benefit at 67 is $1,600 a month, and Social Security is your only income. For anyone born in 1960 or later, 67 is full retirement age, and you can start benefits as early as 62. But claiming at 62 cuts the benefit 30% for life.
So at 62, your $1,600 becomes $1,120 a month, or $13,440 a year. HHS’s 2026 poverty guideline for a single person is $15,960, so you’d start retirement $2,520 a year under the line, or $210 a month.
Ouch.
And since the cut never goes away, every future cost-of-living raise is a percentage of the smaller check. (The report Kaine cited counts seniors in poverty by the Census Bureau’s official measure, which has its own thresholds, so its line and the guideline are two separate figures.)
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Wait until 67, and you’re over the line
Wait until 67, and you get the full $1,600 a month, or $19,200 a year. That’s $3,240 over the poverty guideline. Each year you wait past 67 adds 8% to the benefit, until 70, so holding off three more years lifts the check 24%, to $1,984 a month, or $23,808 a year.
The catch is the five years in between. Claiming at 62 would have paid you $67,200 by 67, and waiting means covering those years from a paycheck or savings instead.
The cut hurts less on a bigger check. Say your full benefit is $2,500 instead: claim at 62, and you’d collect $1,750 a month, or $21,000 a year. You’d stay above the line even after the 30% cut. So with the bigger check, you’d collect less at 62 and still clear the line. With the $1,600 one, you’d fall below it.
Before you file at 62
Your Social Security statement shows your own estimate at 62, at full retirement age and at 70, so start there. If the 62 figure comes in under $15,960 a year and Social Security will be most of your income, the cut shrinks with every month you hold off, and somewhere between 62 and 67 your check clears the line. Married? The line for a household of two is $21,640, and both of your checks count toward it, so run the same math for the two of you together.
Planning to claim at 62 and keep working to close the gap? If your earnings pass the yearly limit, Social Security withholds whole checks from the start of the year until the excess is covered. It does give you credit for those months later, with a higher benefit from full retirement age on. And if you’ve already claimed, you can withdraw your application once within 12 months of first becoming entitled, by paying back what you’ve received, and claim again later at a bigger benefit.
Bottom line: if your full benefit is on the modest side and Social Security will pay most of your bills, I’d treat 62 as a last resort. Of course, waiting only works if a paycheck or savings can carry you through the years in between, and if your health is poor, a smaller check now may be the better bet.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


