Key Takeaways
- Genuine Parts lowered its 2026 earnings guidance in October as fuel and freight costs rose, while Procter & Gamble kept its fiscal 2027 outlook after a 4% sales gain.
- Genuine Parts yields 3.6% against Procter & Gamble’s 2.7%, so $10,000 pays $360 a year today against $270.
- Procter & Gamble’s dividend used 67% of its free cash flow over the past 12 months, against 76% at Genuine Parts, whose 2025 dividend was bigger than its free cash flow.
- Genuine Parts’ December investor days, ahead of its split into two companies, are the next thing to watch.
Procter & Gamble (PG) declared its quarterly dividend of $1.0885 a share on Oct. 13 and noted that it “has increased its dividend for 70 consecutive years.” On Oct. 22, it reported 4% sales growth for the quarter to Sept. 30 and kept its full-year outlook.
Genuine Parts (GPC) had a rougher October. On Oct. 20, it lowered its 2026 adjusted EPS guidance to $7.50-$7.75, from $7.50-$8.00, because of higher fuel and freight costs tied to the Iran conflict.
Both have raised their dividends every year for decades, and both pay them from free cash flow. So which would I rather own now?
| Metric | Procter & Gamble (PG) | Genuine Parts (GPC) |
|---|---|---|
| Dividend yield | 2.7% | 3.6% |
| Annual dividend | $4.35 | $4.25 |
| 5-year dividend growth | 5.6% a year (fiscal 2021-2026) | 5.4% a year (fiscal 2020-2025) |
| Cash dividend payout ratio (TTM) | 67% | 76% |
| Net debt/EBITDA | 0.9x | 2.3x |
| Interest coverage | 24.2x | 8.2x |
| Forward P/E | 23x | 16x |
Source: TIKR and StockAnalysis, Nov. 9, 2026; payout ratios for the 12 months to Sept. 30, 2026.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Procter & Gamble is growing almost everywhere
P&G’s net sales rose 4% to $23.3 billion in the first quarter of fiscal 2027, the three months to Sept. 30, with growth across all 10 of its product categories and all six regions.
That growth backs a well-covered dividend. Over the 12 months to Sept. 30, P&G paid $10.29 billion in dividends from $15.34 billion of free cash flow, a 67% cash dividend payout ratio.
From fiscal 2017 to fiscal 2026 (years to June), free cash flow rose from $9.37 billion to $15.2 billion, while dividends paid rose from $7.24 billion to $10.2 billion:
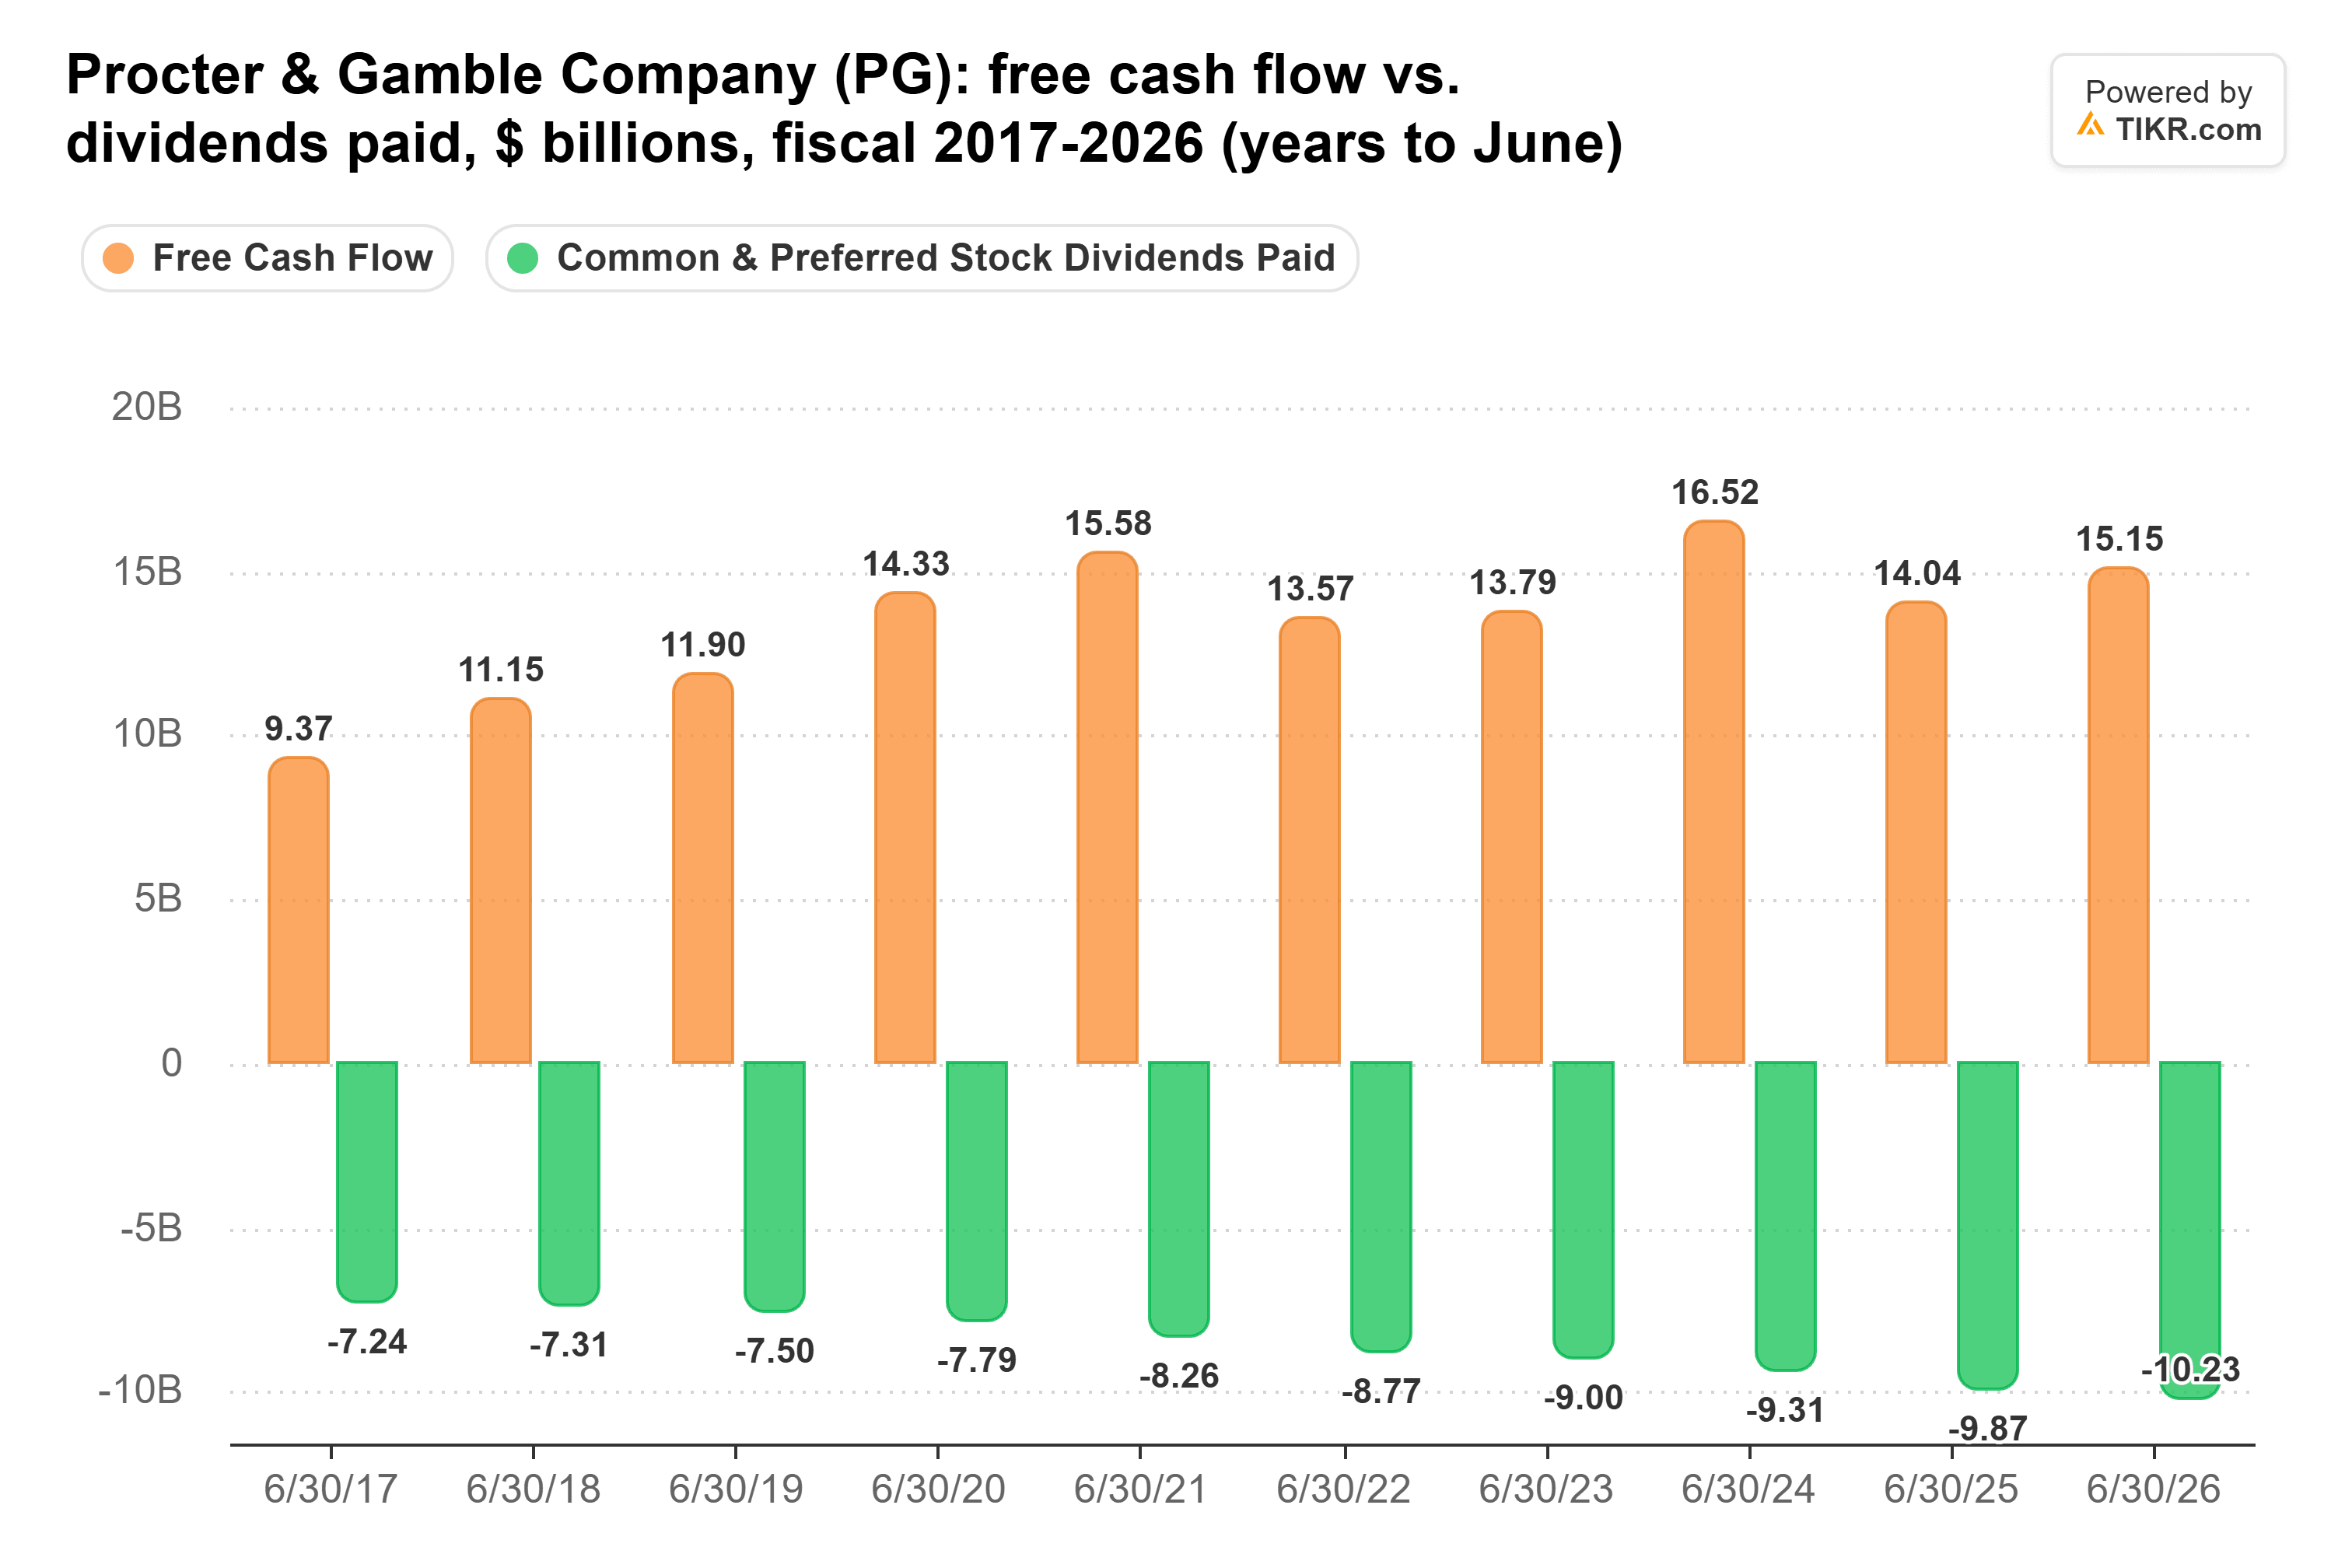
The payout ratio has stayed between 53% and 70% in every fiscal year since 2021.
For fiscal 2027, P&G expects to pay over $10 billion in dividends and buy back about $5 billion of stock, and the buybacks give it room if costs bite. Costs are the risk: P&G expects commodities to take $0.79 a share off fiscal 2027 core EPS, which it guides to grow 0% to 3%.
Genuine Parts’ cash has been shrinking
Genuine Parts pays the bigger check, but the cash behind it has gone the other way from P&G’s. Third-quarter sales rose 4.2% to $6.5 billion, led by its industrial business, Motion, where sales grew 6.1%. North American auto parts are weaker, with comparable retail sales down about 3%.
Over the 12 months to Sept. 30, Genuine Parts paid $578 million in dividends from $763 million of free cash flow, a 76% cash dividend payout ratio. That’s covered, but more tightly than P&G’s, and it’s a recovery from a bad 2025. Free cash flow fell from $1.87 billion in 2020 to $421 million in 2025, while dividends paid rose every year, from $453 million to $564 million:
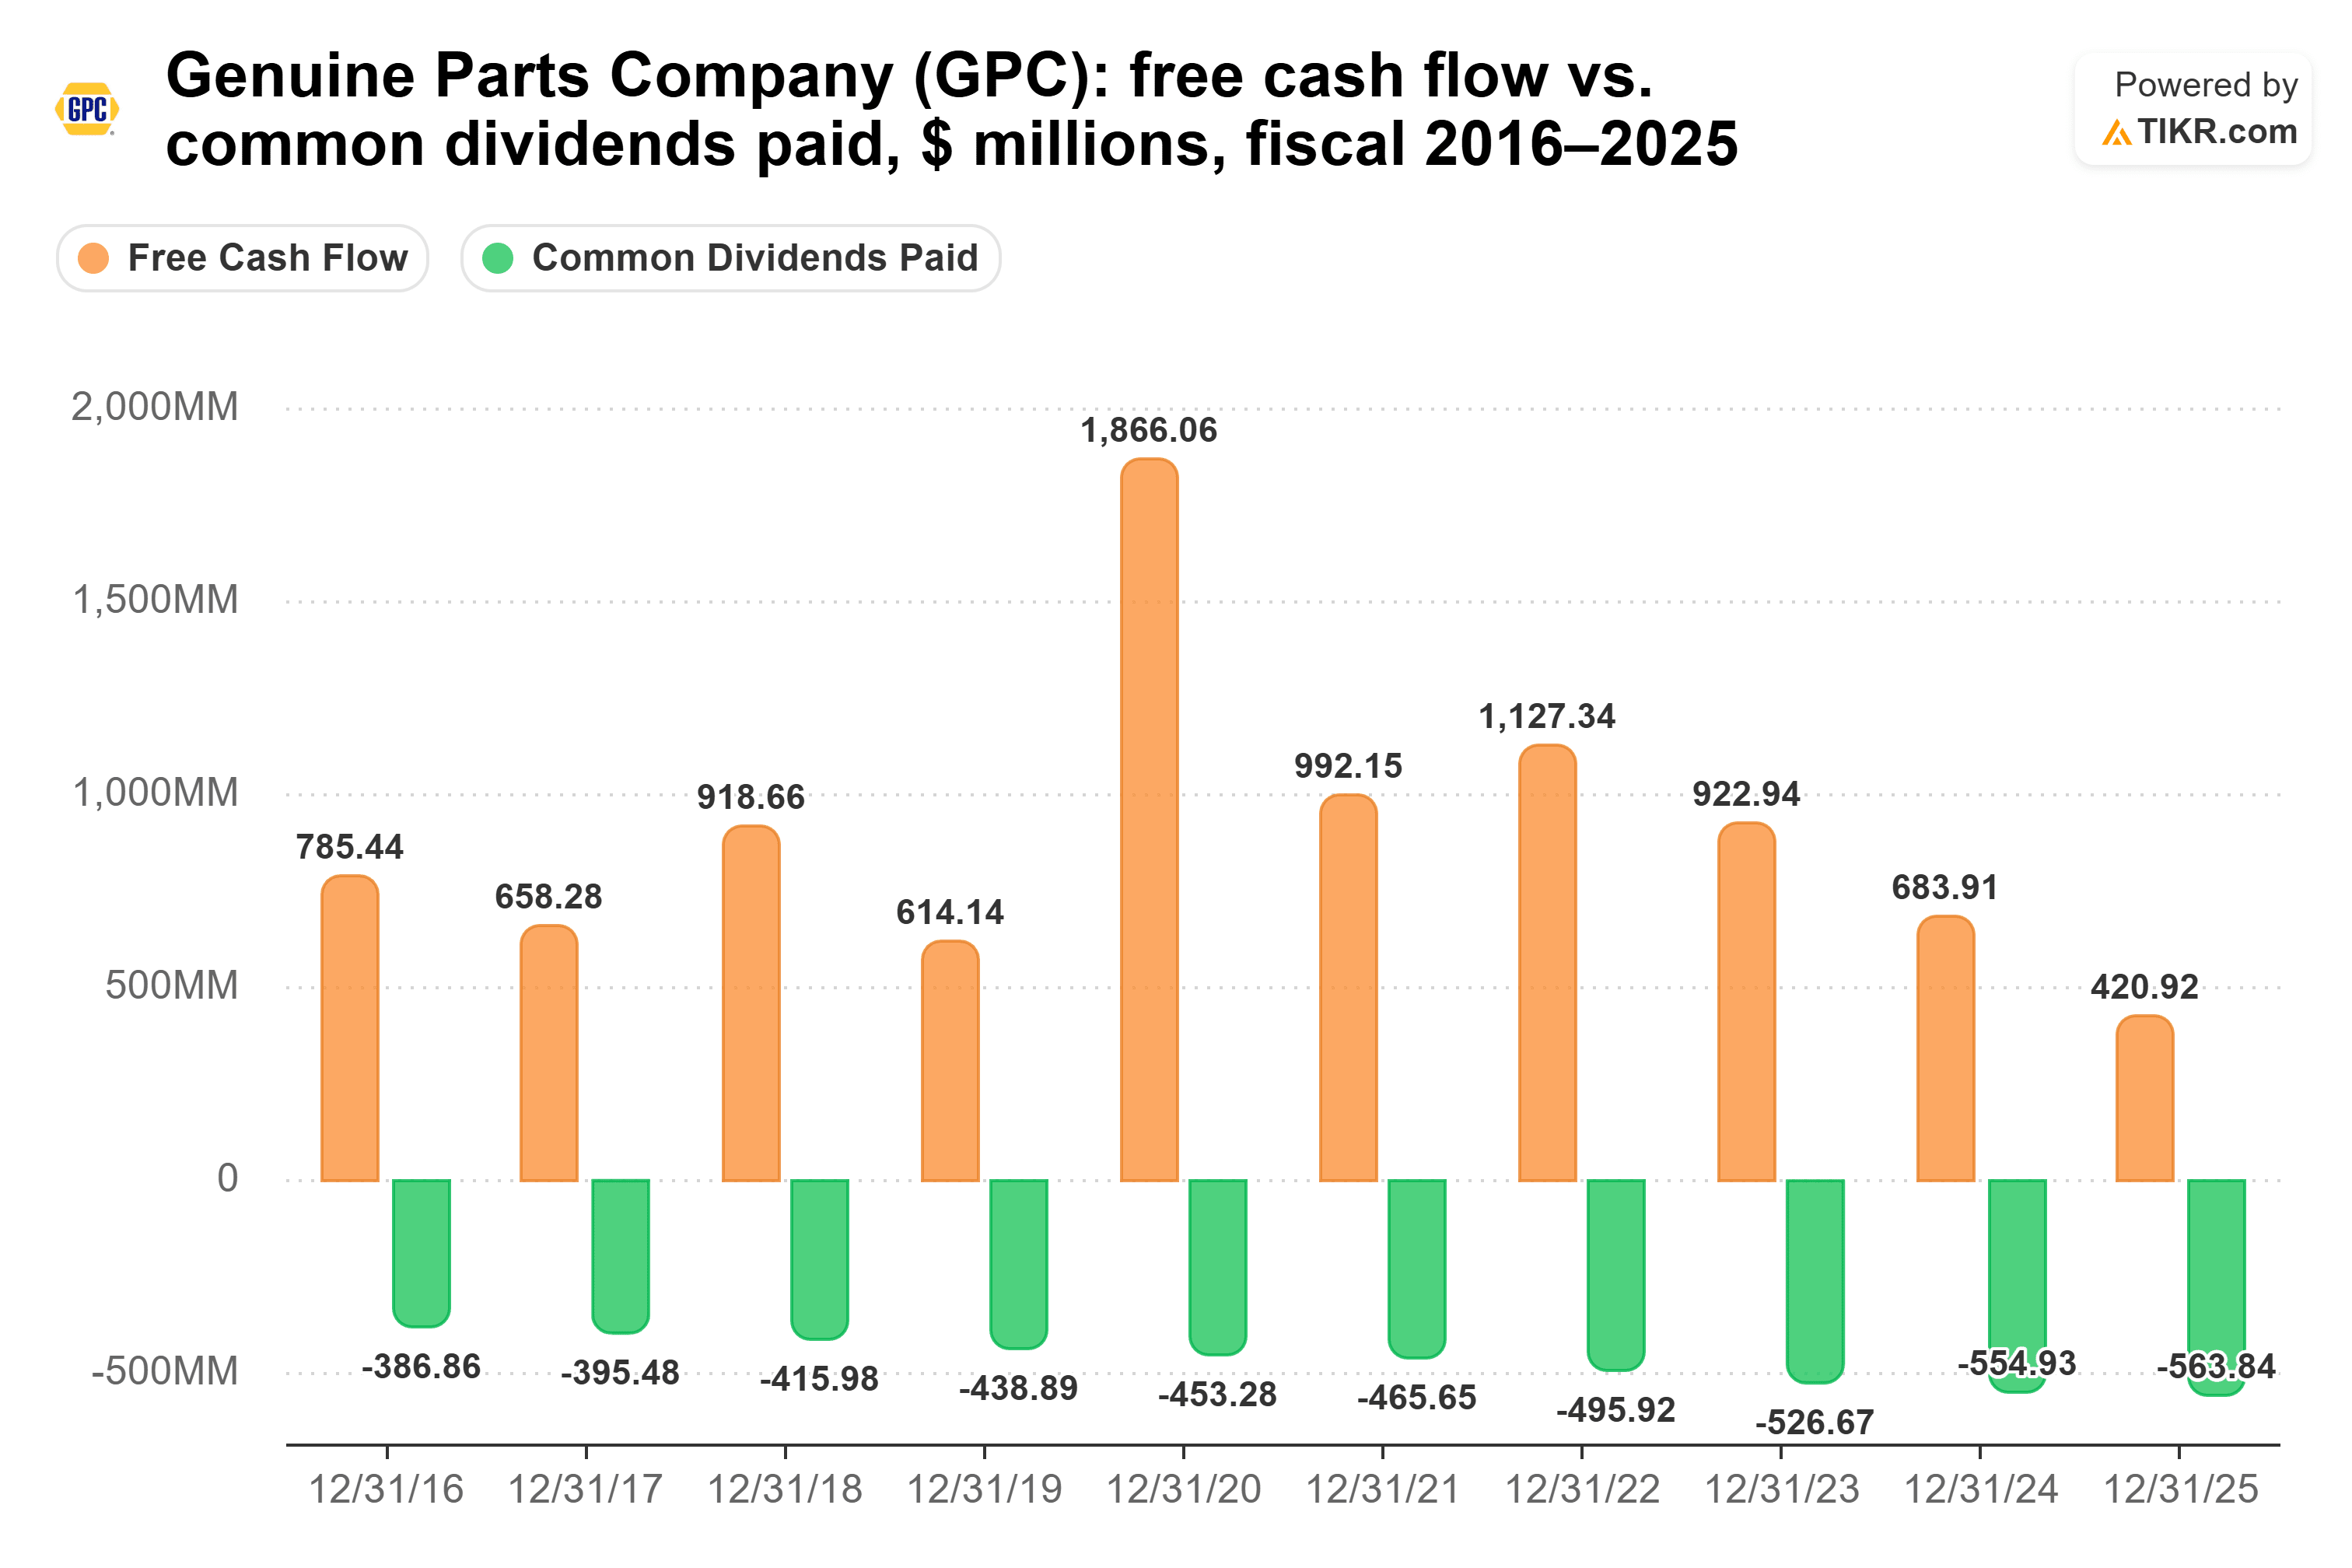
In 2025, the dividend used 134% of free cash flow.
Management guides to $550 million to $700 million of free cash flow for 2026, and the low end would fall short of the $564 million it paid in dividends in 2025. The company also plans to split into two public companies, auto parts and Motion, in the first quarter of 2027.
So which dividend wins?
I’d rather own Procter & Gamble now. Its free cash flow has kept climbing while Genuine Parts’ fell below its dividend in 2025, and its net debt is 0.9x EBITDA against 2.3x. The cash behind the check decides it for me, since a dividend that outgrows the cash paying it can’t keep rising for long.
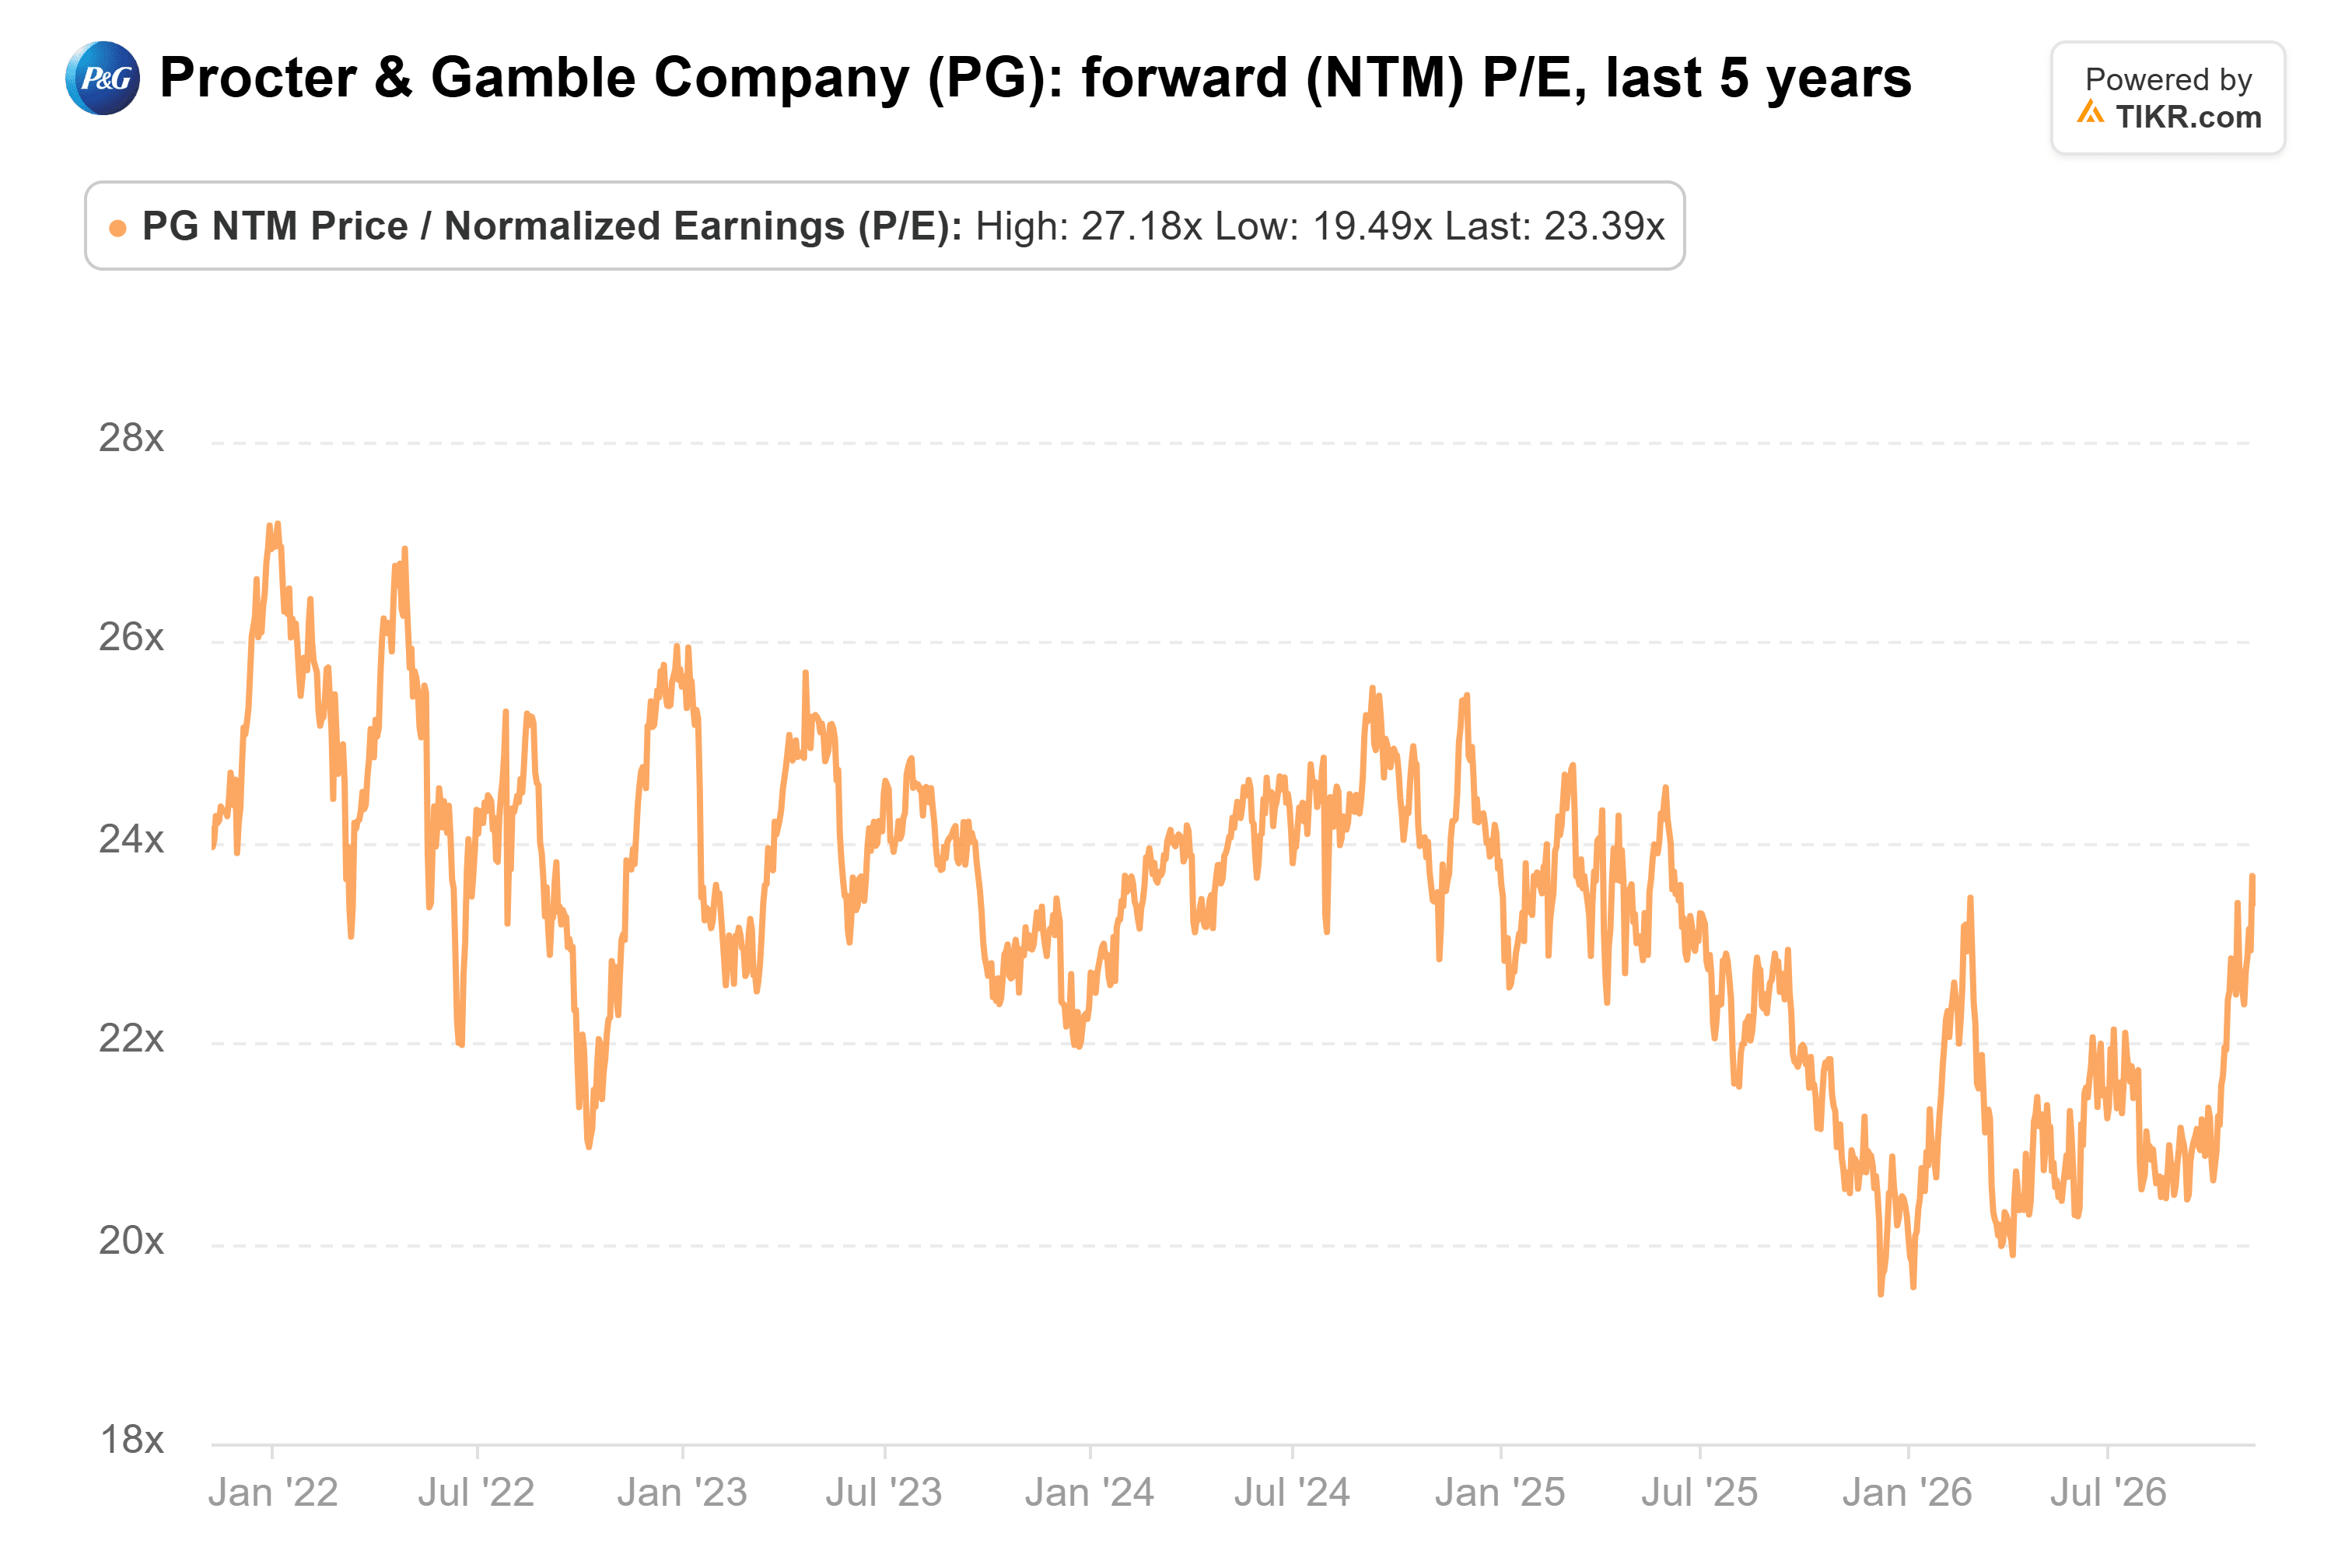
And the safer dividend doesn’t cost a premium today. P&G trades at 23x forward earnings, right at its five-year average of 23x and below its 27x high in January 2022:
Genuine Parts still has a real case. At its 3.6% yield, $10,000 pays $360 a year today, and at its five-year growth rate, that’s about $580 in year 10, a 5.8% yield on your cash, against about $442 from P&G. At those rates, P&G’s income wouldn’t pass Genuine Parts’ for more than 30 years, and even at each dividend’s pace now, not until about 2048. Genuine Parts is also cheaper at 16x forward earnings, and Motion is growing. I’d just want to see free cash flow cover its dividend comfortably again before I trade P&G’s cushion for the extra yield.
The one thing that could change my mind: Genuine Parts’ investor days in New York on Dec. 8-9, where management plans to lay out each business’s earnings power ahead of the split.
Forget Procter & Gamble: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Procter & Gamble isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!