Key Takeaways
- Fractile CEO Walter Goodwin, who is building chips to compete with Nvidia, called TSMC “cheap at the price.”
- Nvidia’s challengers need the same TSMC capacity, so TSMC benefits whichever of them gains share.
- TSMC trades at 16.5x forward earnings, below its five-year average, and its main risk is an AI spending slowdown across several big customers.
Taiwan Semiconductor Manufacturing (TSM) makes the chips for Nvidia (NVDA) and the rivals investors bought after Nvidia announced Jensen Huang’s resignation on Nov. 12. That day Nvidia fell, while AMD (AMD) and Broadcom (AVGO) rose.
Someone building chips to take on Nvidia has a different favorite. On the 20VC podcast, Harry Stebbings asked Walter Goodwin, founder and CEO of chip startup Fractile, which of his suppliers he’d invest in. Goodwin picked TSMC: “It is cheap at the price. I would buy that stock every day of the week.”
Every Challenger Needs the Same Factory
Goodwin’s reason is practical. New chip entrants face “a real challenge” in “accessing, for instance, TSMC capacity, HBM capacity,” he said. Of the custom AI chips he listed, including OpenAI’s, he added: “All of those are rumored to be using Broadcom, for instance. Same or very similar TSMC process nodes, same HBM technology.”
So if chip orders shift from Nvidia to AMD or Broadcom-built designs, TSMC still makes the chips.
TSMC Can’t Make Enough
TSMC’s October revenue rose 59.7% from a year earlier to a record NT$586.9 billion (about US$17.8 billion), and analysts expect revenue to keep climbing:
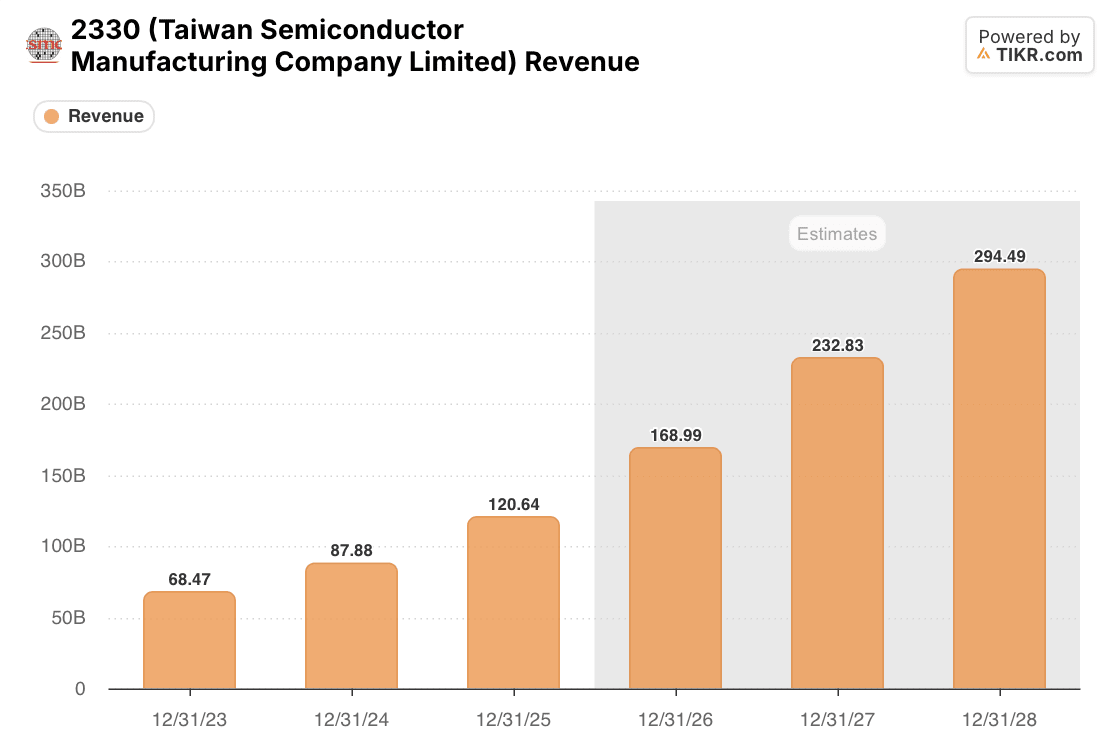
Consensus takes revenue from $120.6 billion in 2025 to $294.5 billion in 2028, 2.44 times as much. Huang’s exit doesn’t change how many wafers an AI chip needs, whoever designs it.
Full fabs show up in the margin:
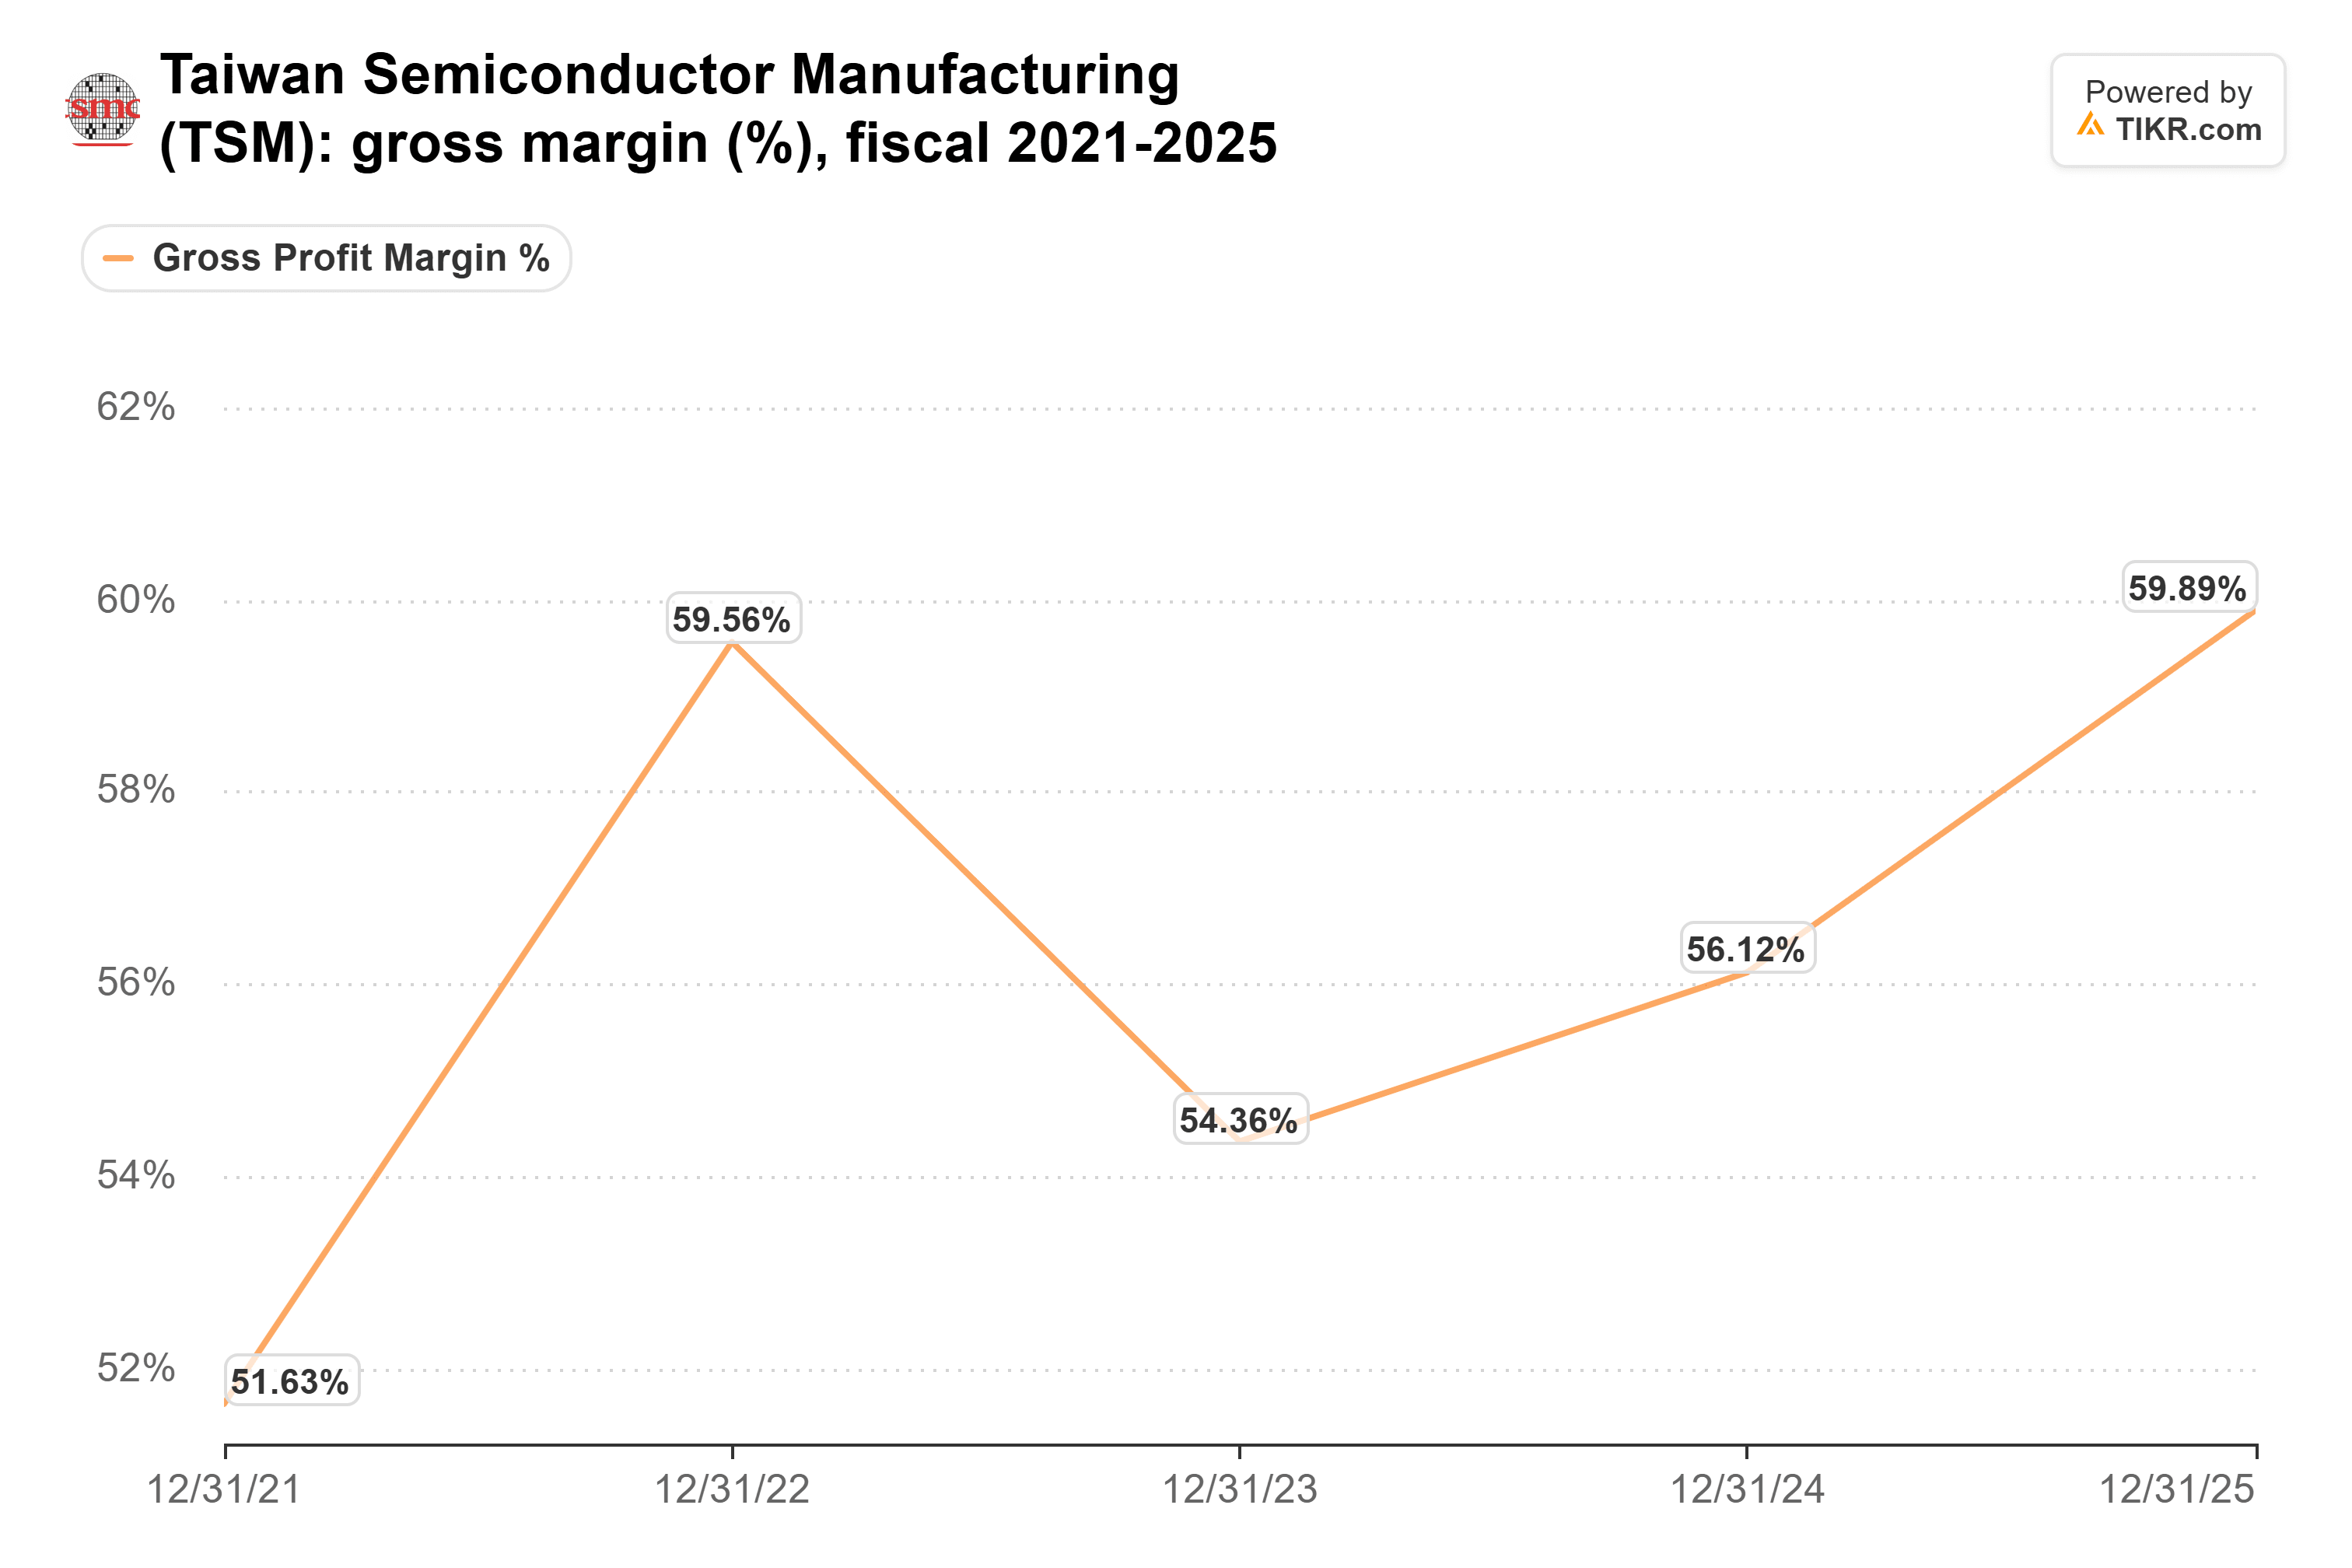
Gross margin reached 66.4% in the third quarter of 2026, well above management’s long-term target of 56% or higher. TSMC has credited high utilization and cost improvements for the gains.
Nvidia Is Still the Customer That Matters Most
TSMC’s largest customer, which it doesn’t name, was 19% of 2025 revenue, up from 12% in 2024, and Nvidia is widely reported to be that customer. If Nvidia ordered more than it can sell, TSMC would feel it in future orders.
Share shifts between chip designers matter less to TSMC than to the designers. The bigger risk is an AI spending slowdown, which would likely hit several of its big customers together. Nvidia reports on Nov. 17, and its outlook is the next read on those orders.
TIKR Tracks 37 Analysts on TSMC. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on TSMC, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See TSMC’s Analyst Ratings
The Case for Owning TSMC Stock
TSMC’s forward P/E has dropped to 16.5x from 19.8x at the end of September:
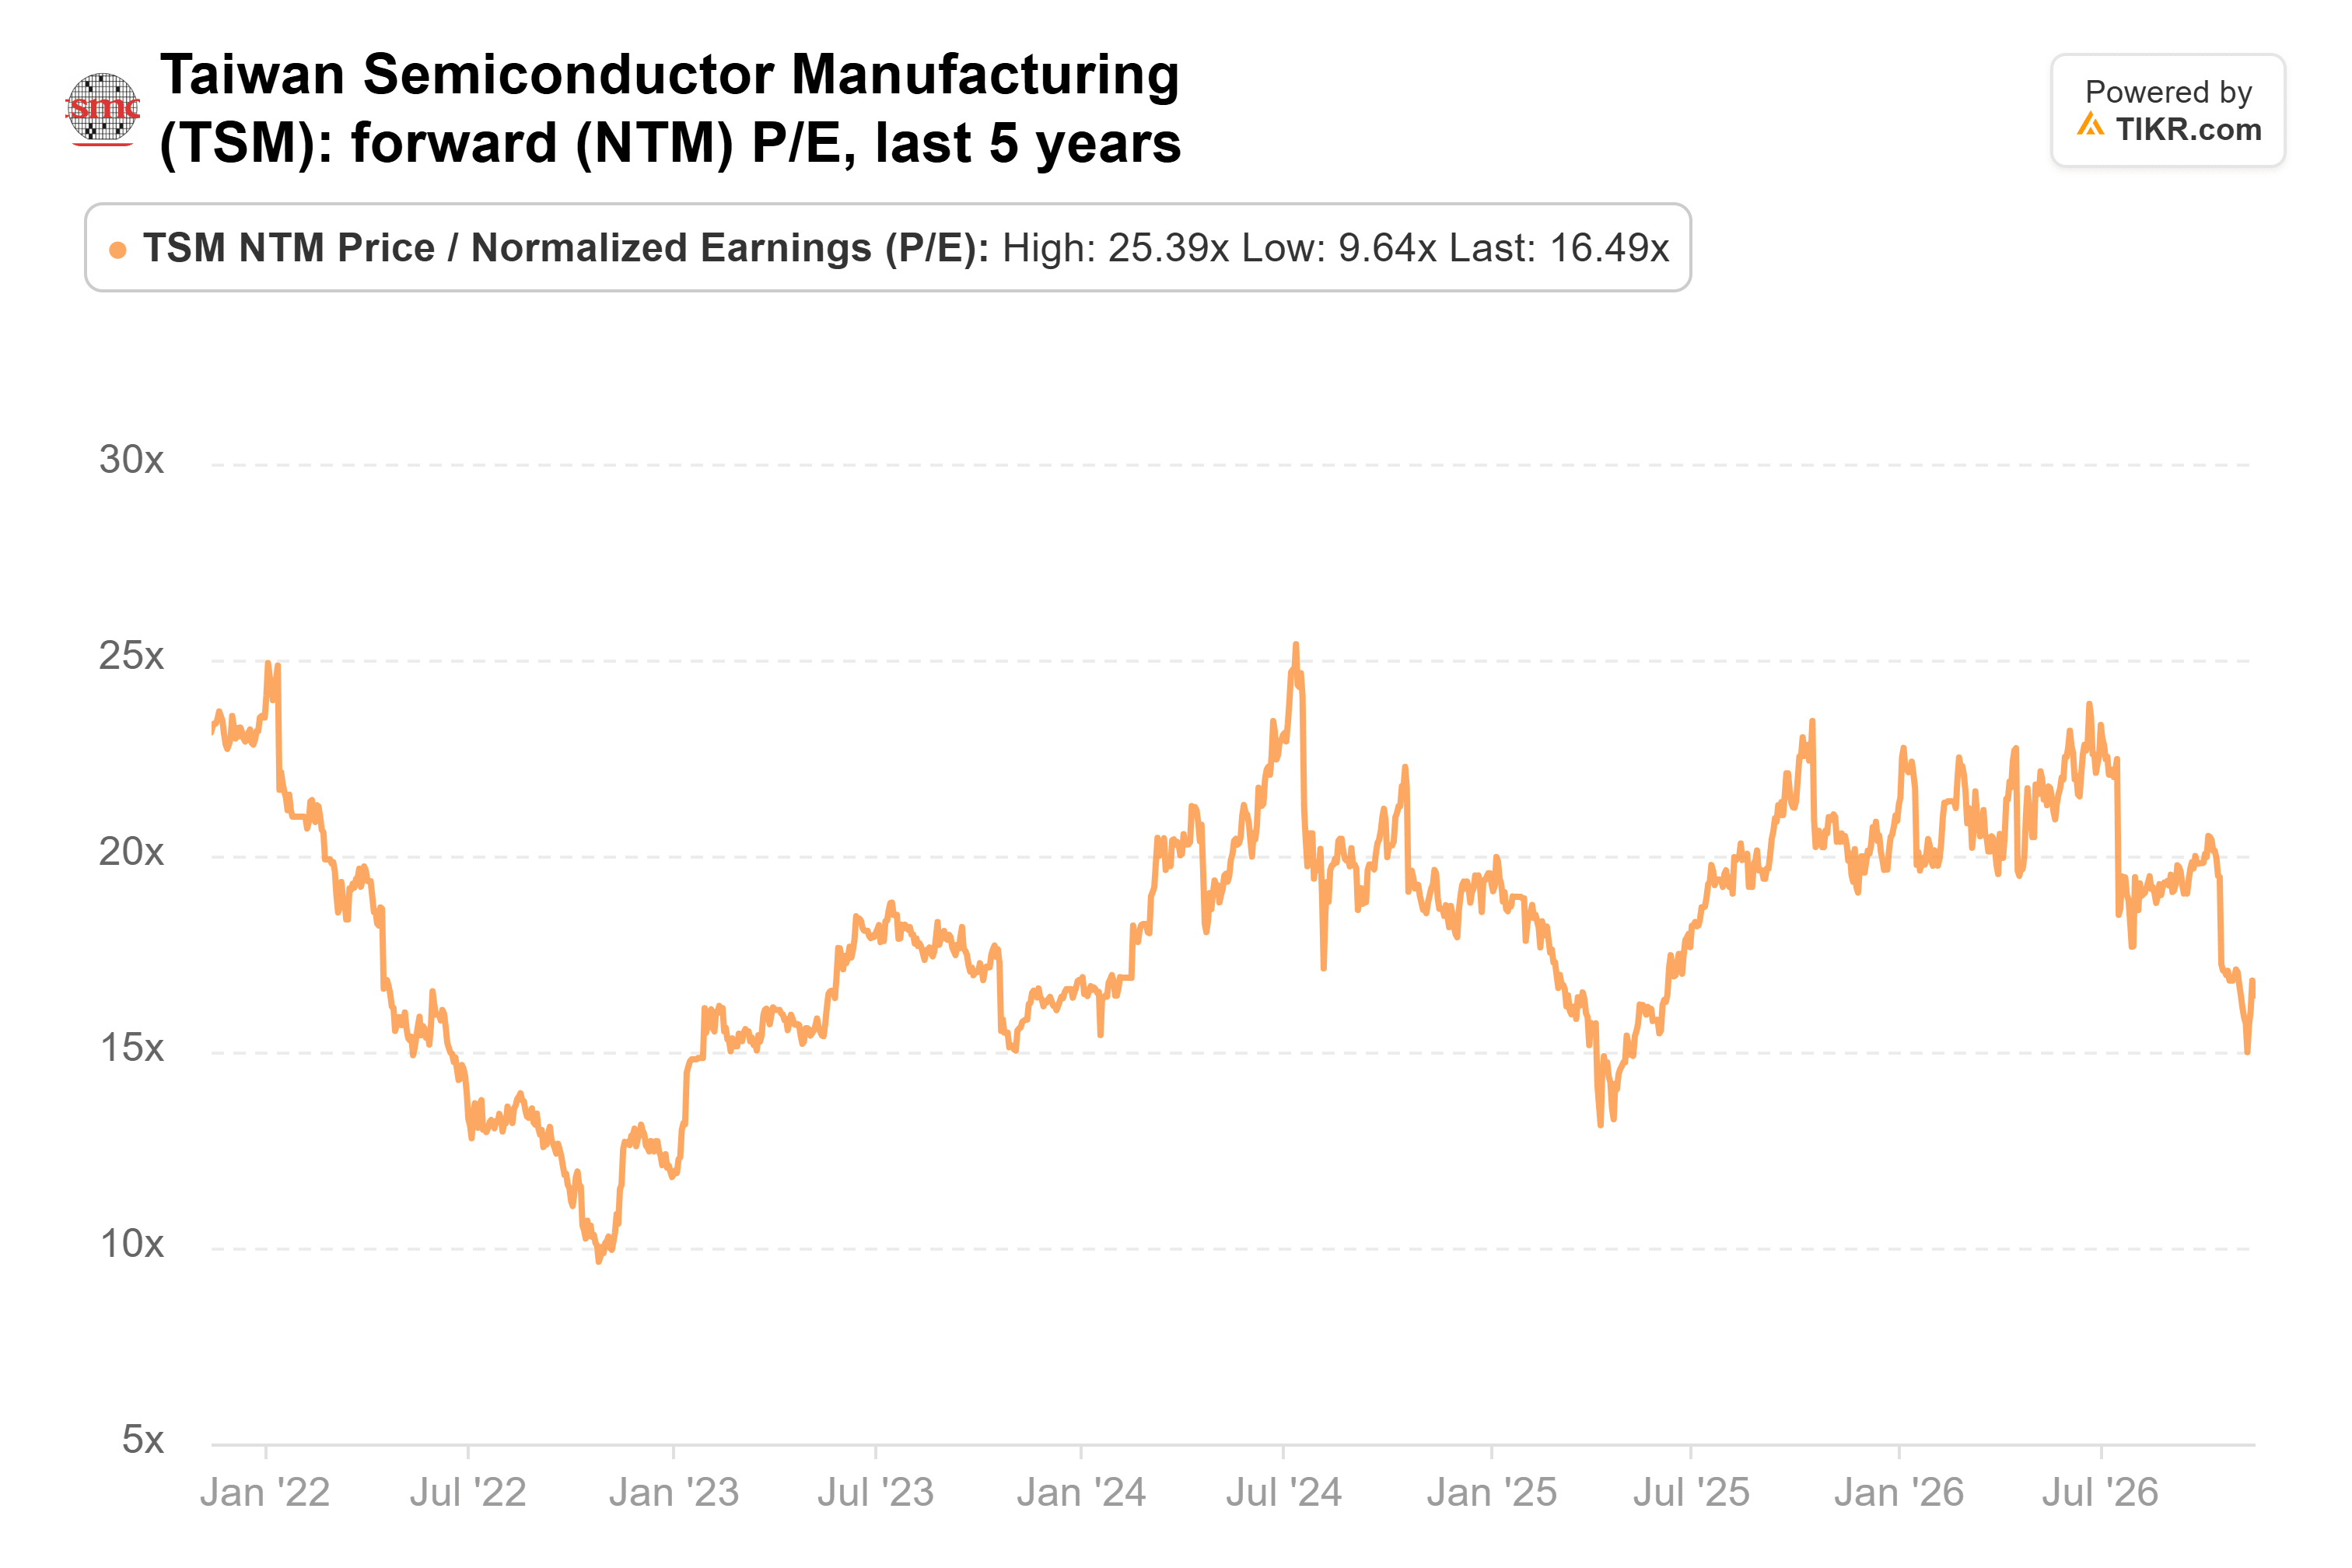
That’s below its five-year average of 18.1x and well under its 25.4x peak in July 2024. The multiple fell even as analysts raised their numbers: consensus 2027 earnings rose 16% from June 30 to Oct. 23. Consensus revenue implies 34.6% annual growth in US dollars from 2025 to 2028, well above management’s plan for growth approaching 25% a year from 2024 to 2029, though the periods differ.
I’m with Goodwin. TSMC gets paid whichever chip designer wins, and it trades below its usual multiple. The next test comes in mid-January, when TSMC is expected to give its 2027 outlook and capital budget.
So What Is TSMC Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what TSMC could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!