Key Takeaways
- Nebius Group (NBIS) fell 9.9% on November 13, closing at $115.88, while Baird maintained its Outperform rating despite cutting its price target from $340 to $200.
- Baird’s revised target implies approximately 73% upside, even as data center delays and substantial infrastructure spending raise concerns about execution.
- Nebius reported third-quarter revenue growth of 571% to $980.8 million, but now expects 2026 revenue near the low end of its previous guidance range.
- Management expects $12 billion to $13 billion in 2027 revenue, although planned capital spending of $40 billion to $45 billion creates substantial financing and dilution risks.
What Happened?
Nebius Group (NBIS) shares continued sliding following its third-quarter earnings report, closing at $115.88 on November 13, down 9.9% for the session and approximately 61% below their 52-week high.
Baird analyst Robert Oliver lowered his price target from $340 to $200 while maintaining an Outperform rating, implying approximately 73% upside from the latest closing price.
The price-target reduction comes as investors weigh accelerating AI infrastructure demand against construction delays and the financing required to support Nebius’s expansion.
According to Nebius’s third-quarter results, revenue jumped 571% year over year to $980.8 million, exceeding analysts’ expectations of approximately $907.5 million.
However, approximately $325 million came from an initial phase of its asset-light partnerships, which management classified as non-recurring revenue in the quarter, raising questions about how consistently this growth can be sustained.
Nebius now expects 2026 revenue near the low end of its previous $3.0 billion to $3.4 billion guidance range, as delays at third-party data centers push some expected revenue into 2027.
In his third-quarter shareholder letter, CEO Arkady Volozh stated, “Our confidence in the fundamentals of what we are building has not changed.”
Management maintained its preliminary 2027 revenue outlook of $12 billion to $13 billion, while increasing expected 2026 capital expenditures to approximately $27 billion.
The company also expects $40 billion to $45 billion in capital spending during 2027, making financing and timely data center delivery critical to its growth plans.
Is Nebius Stock Undervalued or Overvalued?
At approximately $116 per share, Nebius appears undervalued relative to its long-term revenue potential, although substantial execution and financing risks justify caution.
Baird’s $200 target implies approximately 73% upside, while TIKR’s pre-earnings consensus target of $278, recorded on November 4, implies roughly 140% upside from the November 13 closing price.
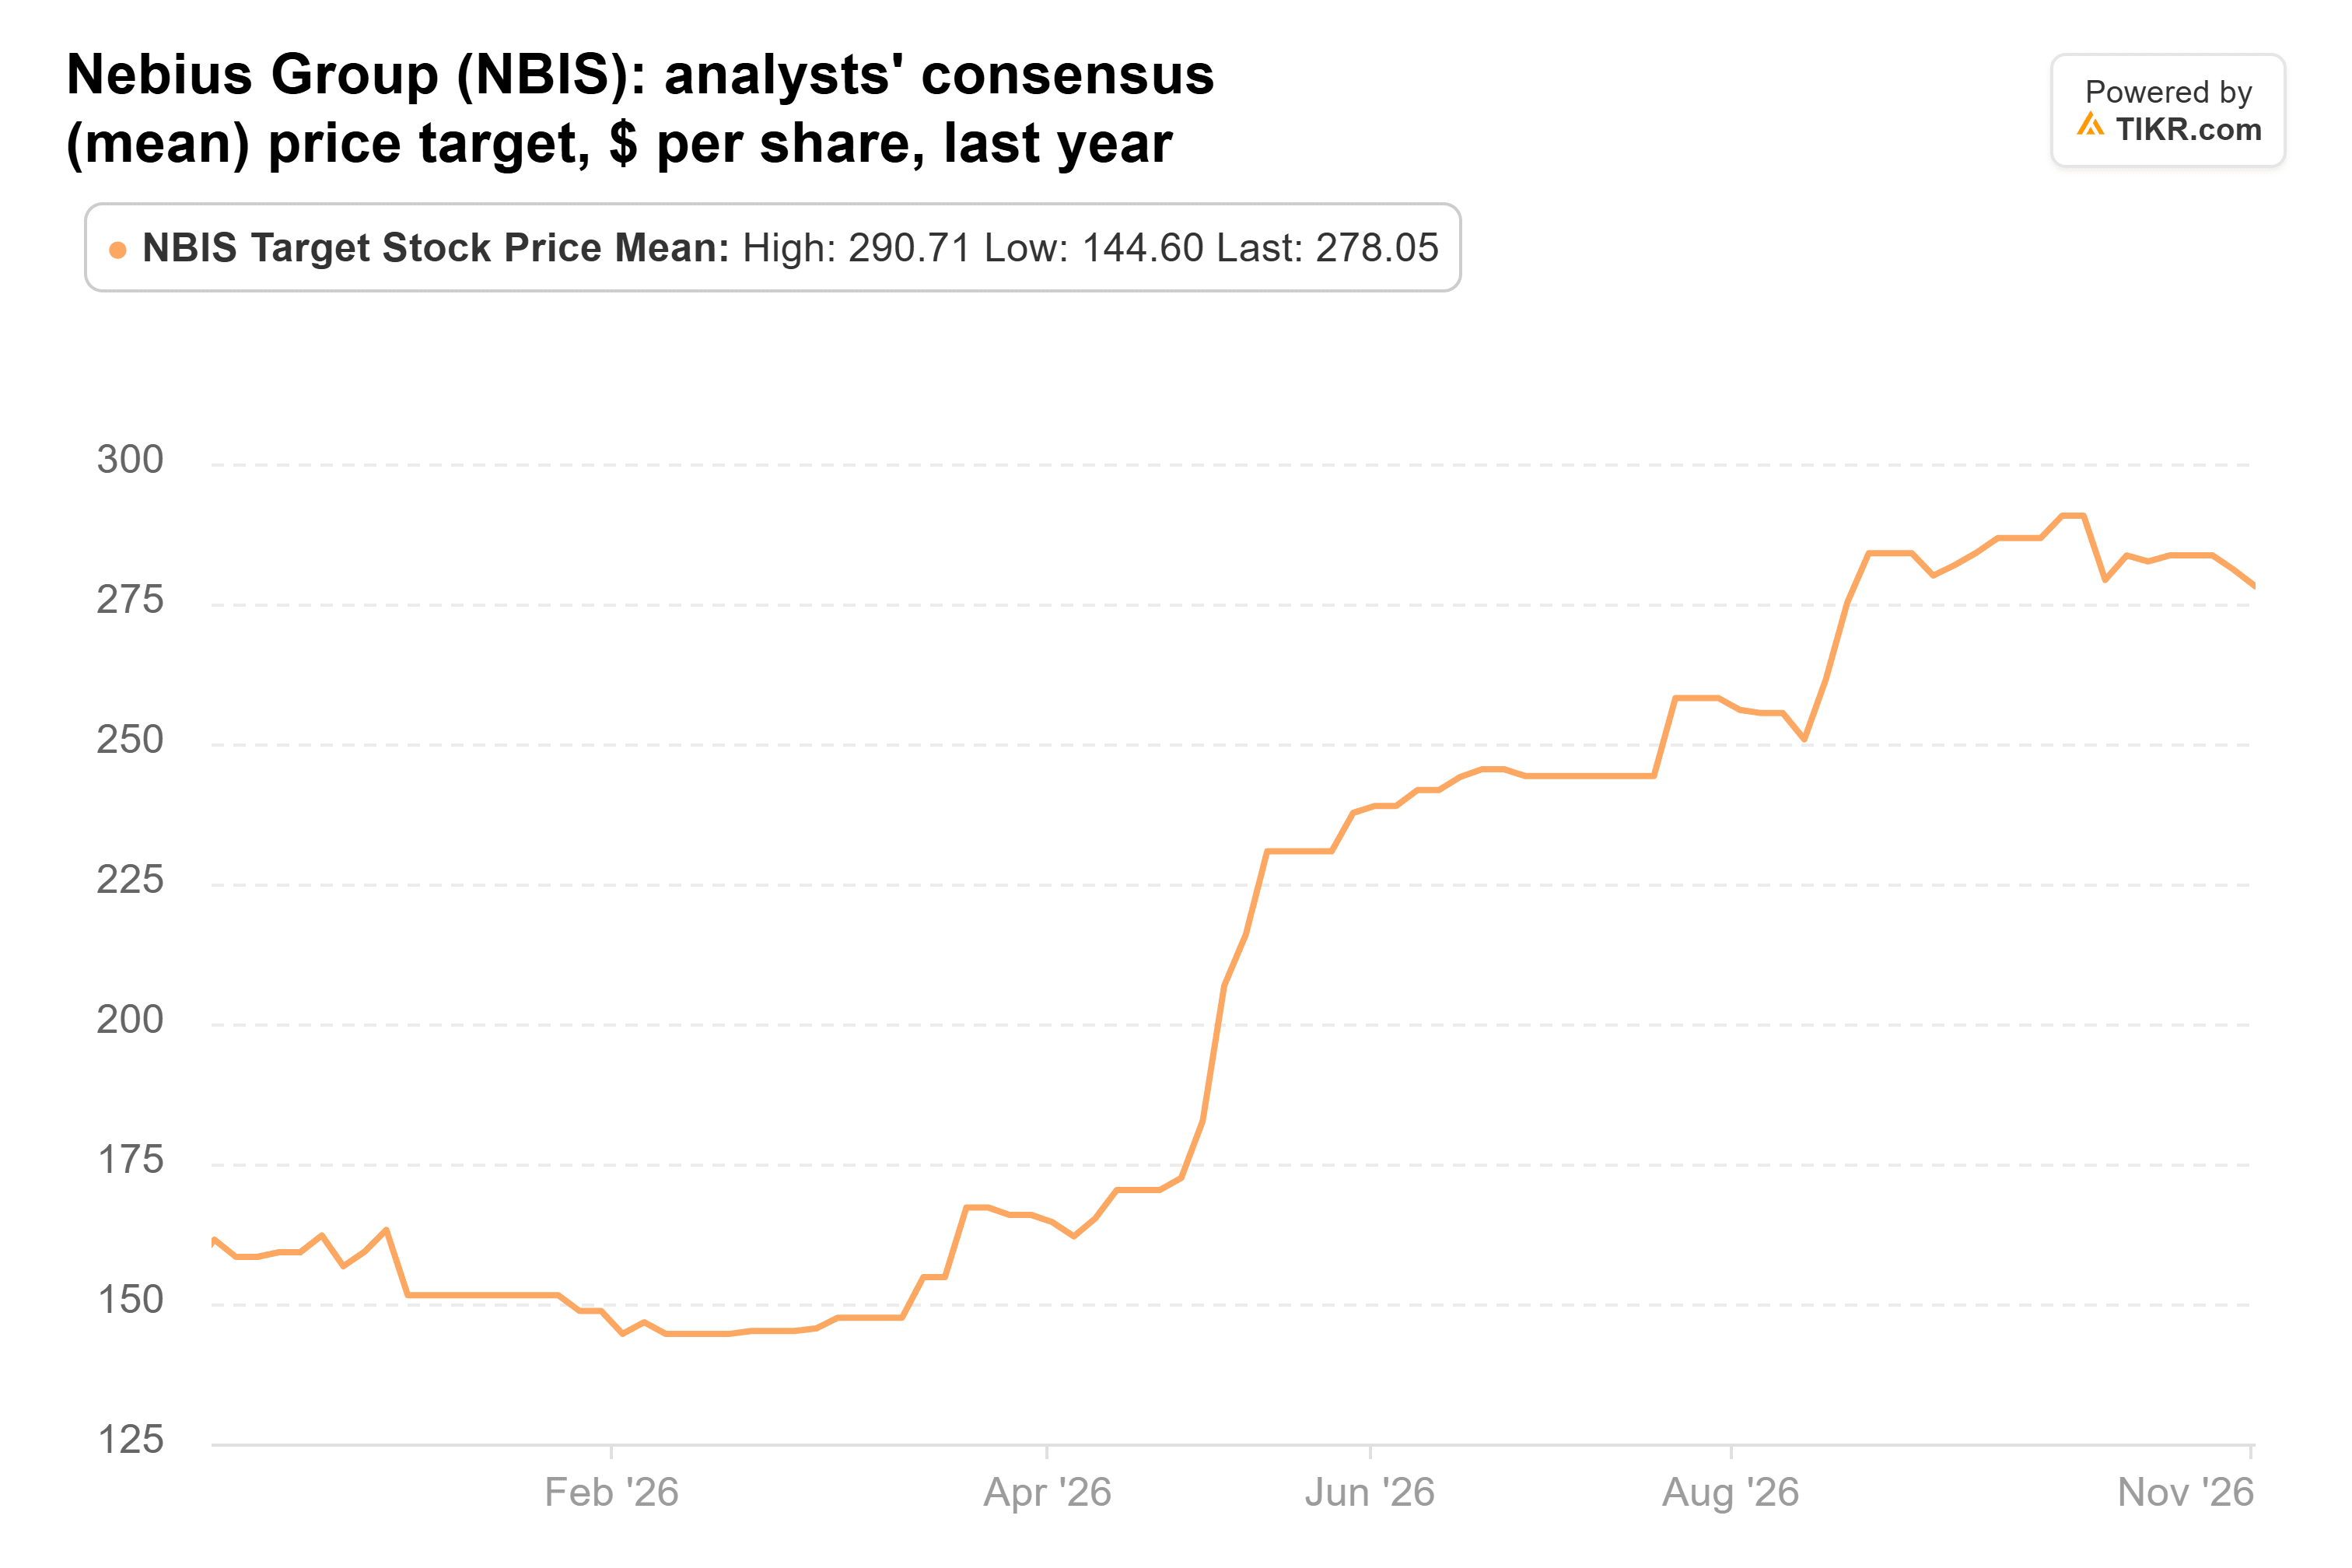
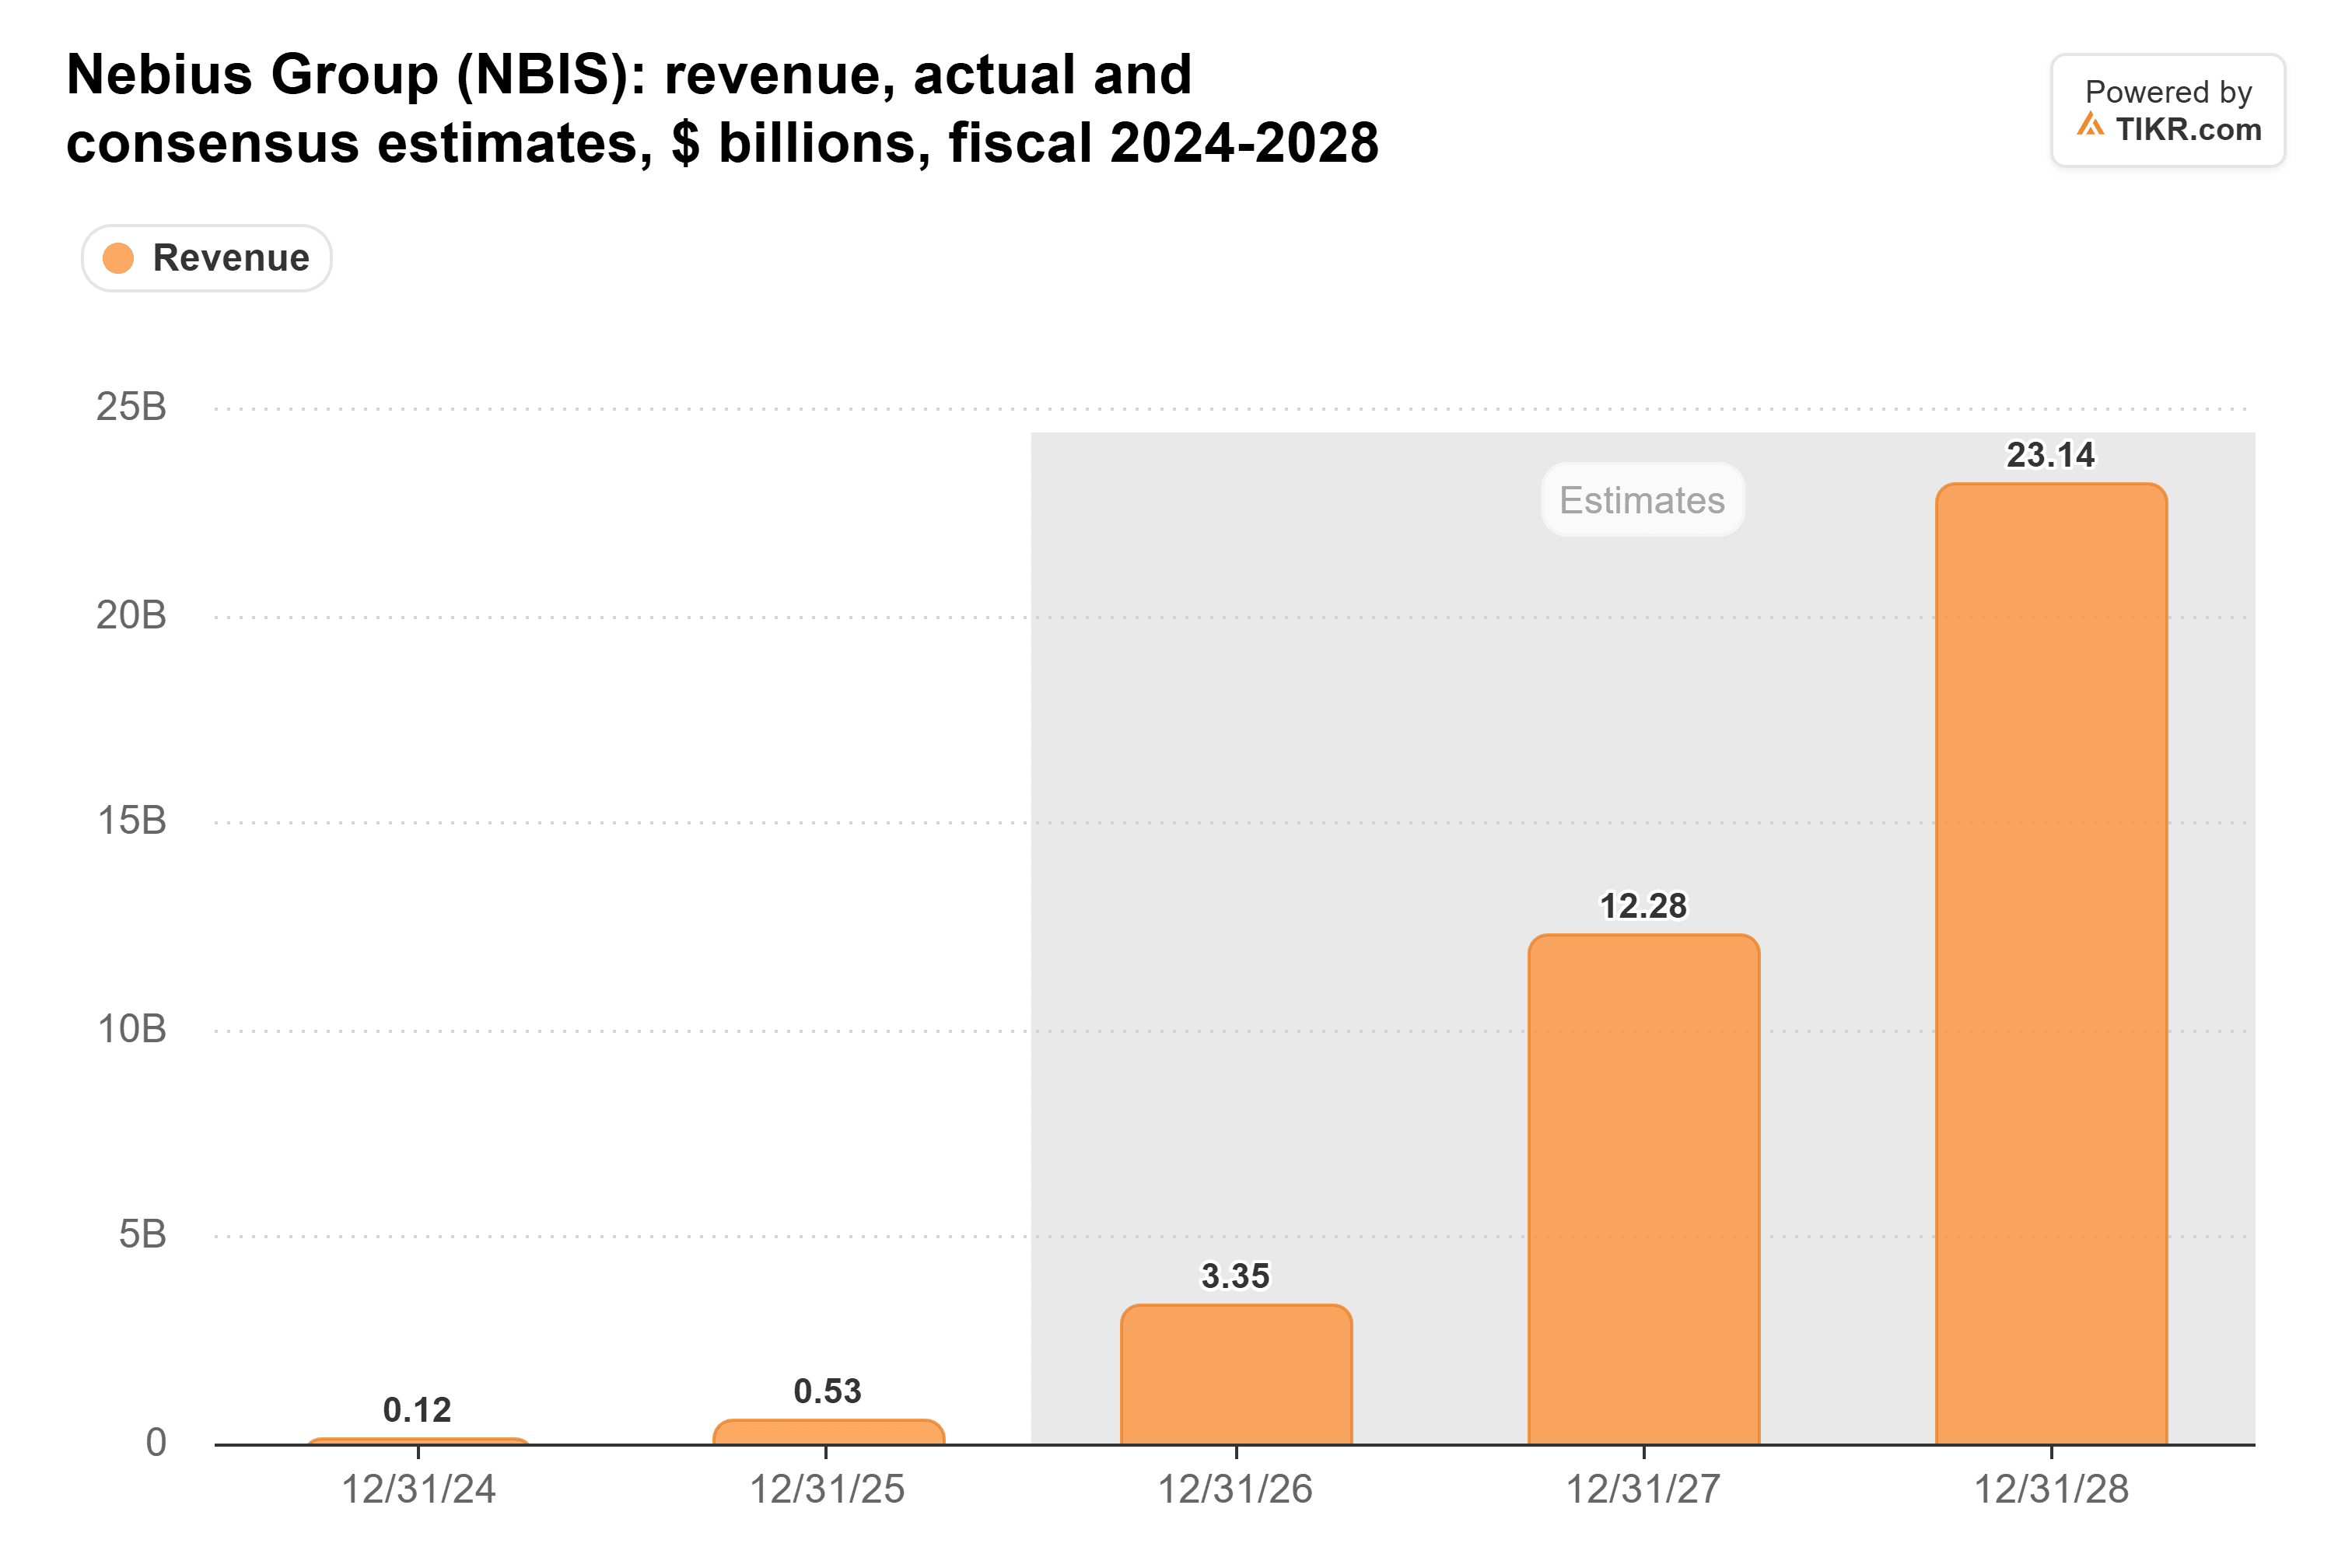
TIKR’s November 4 estimates projected $3.35 billion in 2026 revenue and approximately $12.3 billion in 2027. However, the 2026 figure may require downward revision following management’s reduced guidance.
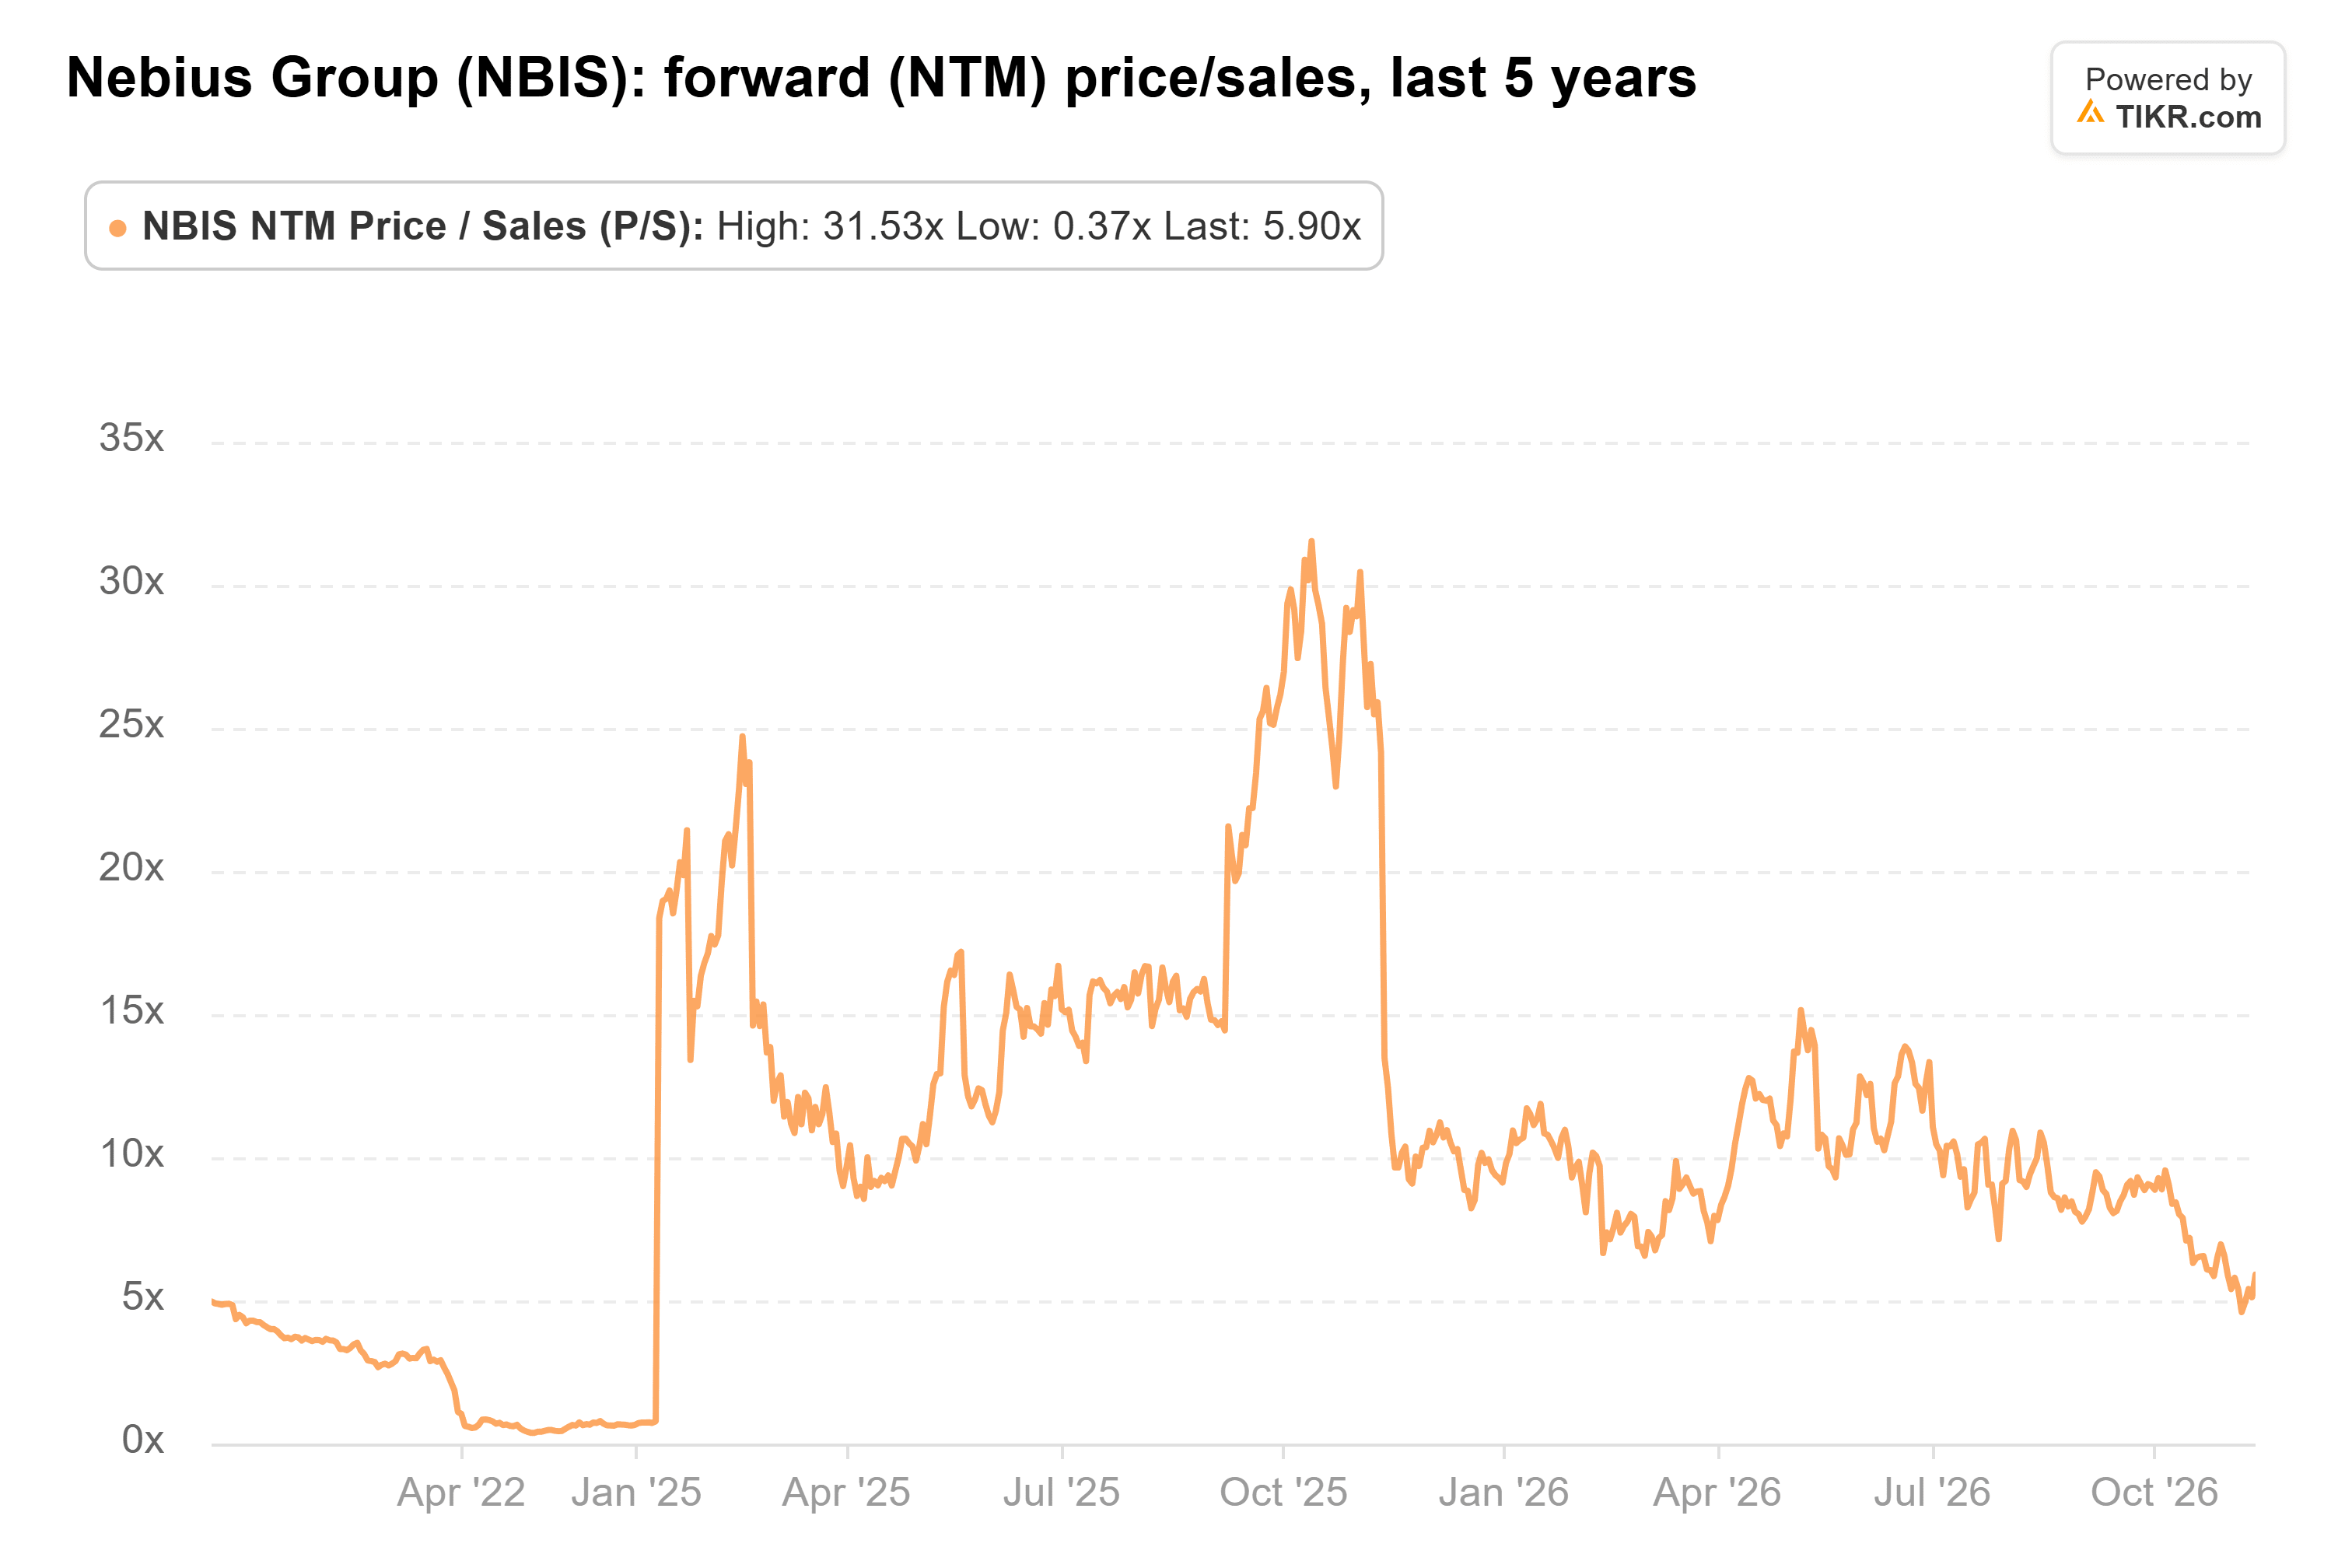
As of November 11, Nebius traded at 5.9x forward sales, compared with an average of approximately 11x over the previous year, according to TIKR’s historical valuation data. Holding the same forward-sales assumptions constant, its lower November 13 share price implies approximately 4.4x forward sales, while Baird’s $200 target would imply around 7.6x.
However, analysts’ projected 2027 loss widened to $6.16 per share from $4.87 three months earlier, highlighting the financial pressure accompanying Nebius’s infrastructure expansion.
Nebius sold 4.6 million shares through its at-the-market program during the third quarter and issued $5.75 billion in convertible notes in August, underscoring potential shareholder dilution.
Management expects customer prepayments and asset-backed financing to cover 75% to 85% of planned 2027 capital expenditures, potentially reducing its need for additional equity financing.
Baird’s $200 target looks achievable if Nebius delivers its 2027 revenue guidance without substantial additional dilution. However, further construction delays, higher financing costs, or weaker profitability could prevent the stock from reaching that valuation.
For investors, the next 12 months will depend on Nebius bringing new data center capacity online, converting contracted demand into sustainable revenue, and funding its expansion without significantly weakening shareholder value.
So what is Nebius stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nebius could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!