Key Takeaways
- Marvell stock is down 41% from its June high after reports that it’s in advanced talks to buy Lumentum, reportedly in an all-stock deal.
- Piper Sandler kept its Overweight rating and $400 target, 104% above the current price, and pointed to Lumentum’s lasers as key to faster, lower-power AI networks.
- The target works out to about 71x the earnings analysts expect over the next twelve months, above Marvell’s five-year peak of 70x and its 33x average.
- Reaching $400 would take a record multiple on estimates that a deal paid in shares could rewrite, so the deal’s terms are the thing to watch.
Marvell Technology (MRVL) stock is down 41% from its June high. Its latest drop followed Bloomberg’s report, after Wednesday’s close, that the chipmaker is in advanced talks to buy laser maker Lumentum (LITE).
Piper Sandler thinks the market has overreacted. On Thursday, it kept its Overweight rating and $400 price target, 104% above today’s price.
A megadeal nobody has priced yet
The business is still growing fast. In August, Marvell reported record Q2 revenue of $2.74 billion, up 37%, and CEO Matt Murphy said “AI-related bookings remain exceptionally robust.”
Lumentum is worth about $76 billion on the market, and Marvell held $3.93 billion of cash at the start of August. So investors balked at the reported megadeal, which would likely be paid mostly in new shares.
On Friday, CNBC’s David Faber said it would be all stock, though it “is not at a big premium” for Lumentum.
Piper likes the lasers
Piper had the same $400 target after Marvell’s Oct. 6 Investor Day, where management forecast $70 billion to $90 billion of revenue in fiscal 2031.
On Thursday, analyst David O’Connor argued that optical networking matters more and more for moving AI data faster on less power, and that Lumentum’s high-powered lasers help make that possible.
TIKR tracks 47 analysts on Marvell. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
What it takes to get to $400
Analysts have raised their consensus target all year, from $90 a year ago to $341 now:
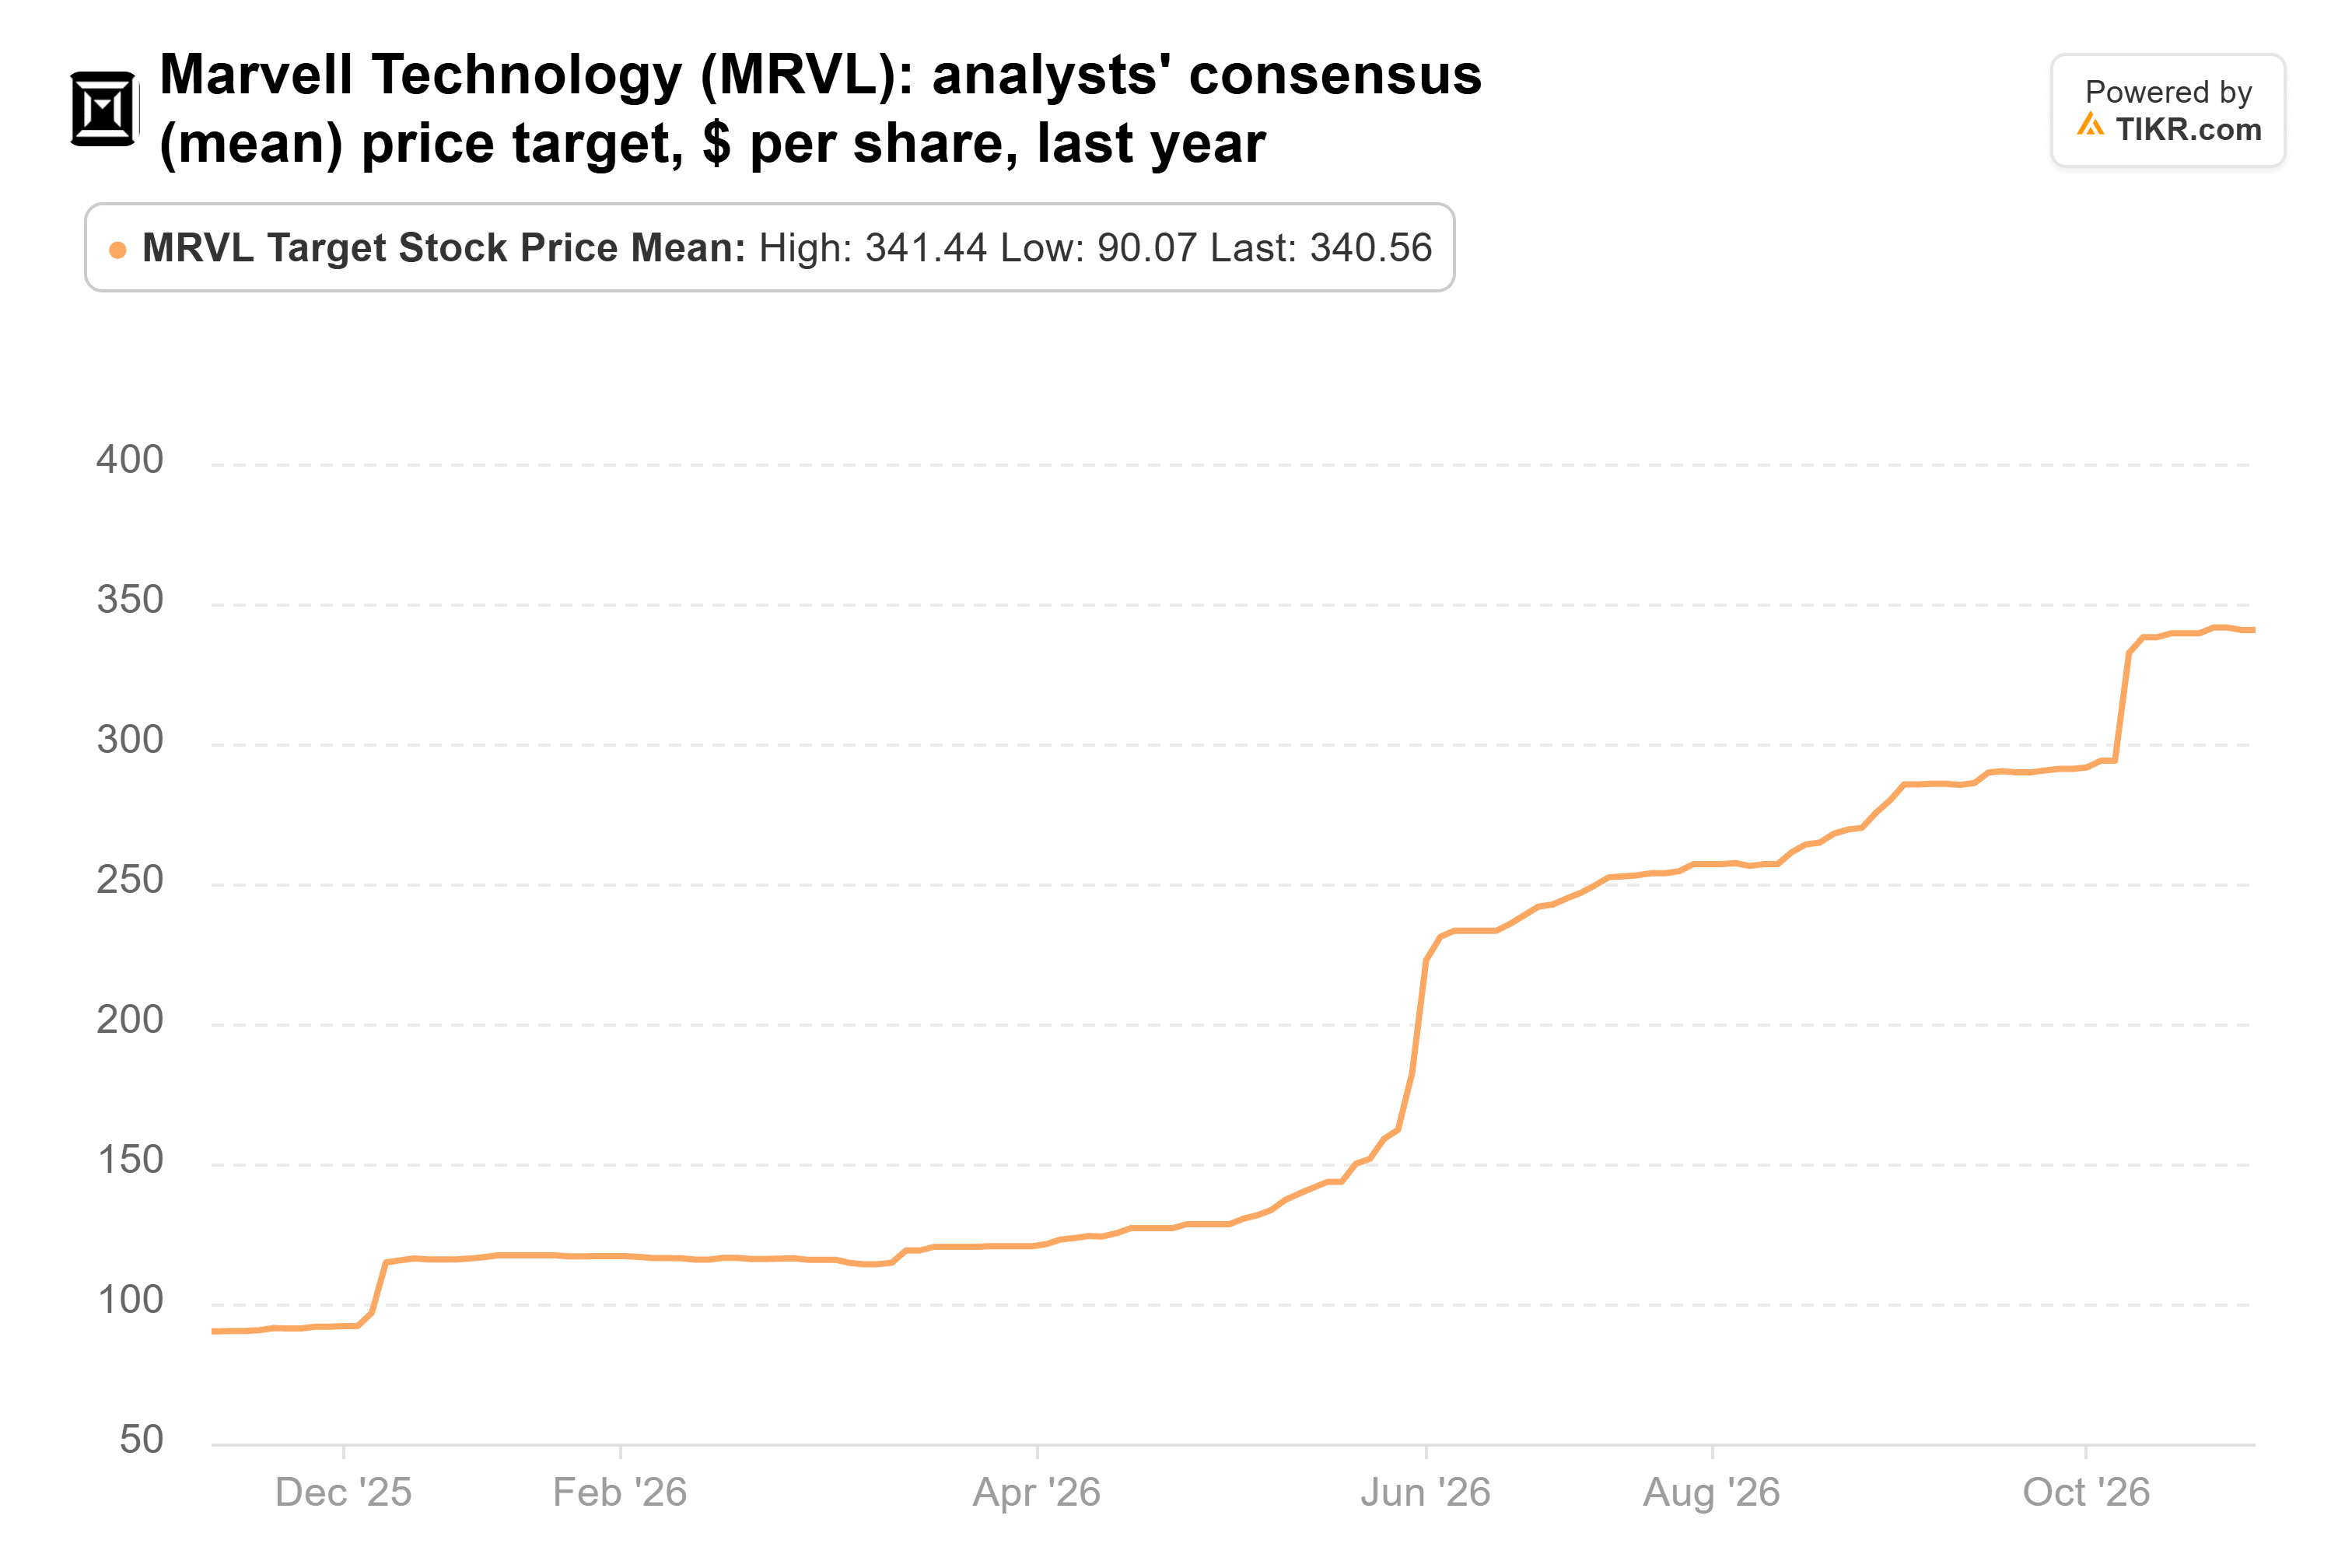
Even the lowest target, $230, sat above Thursday’s close of $218.
Earnings estimates have climbed too. The consensus for fiscal 2028 is $7.33 a share, up from $6.24 three months ago:
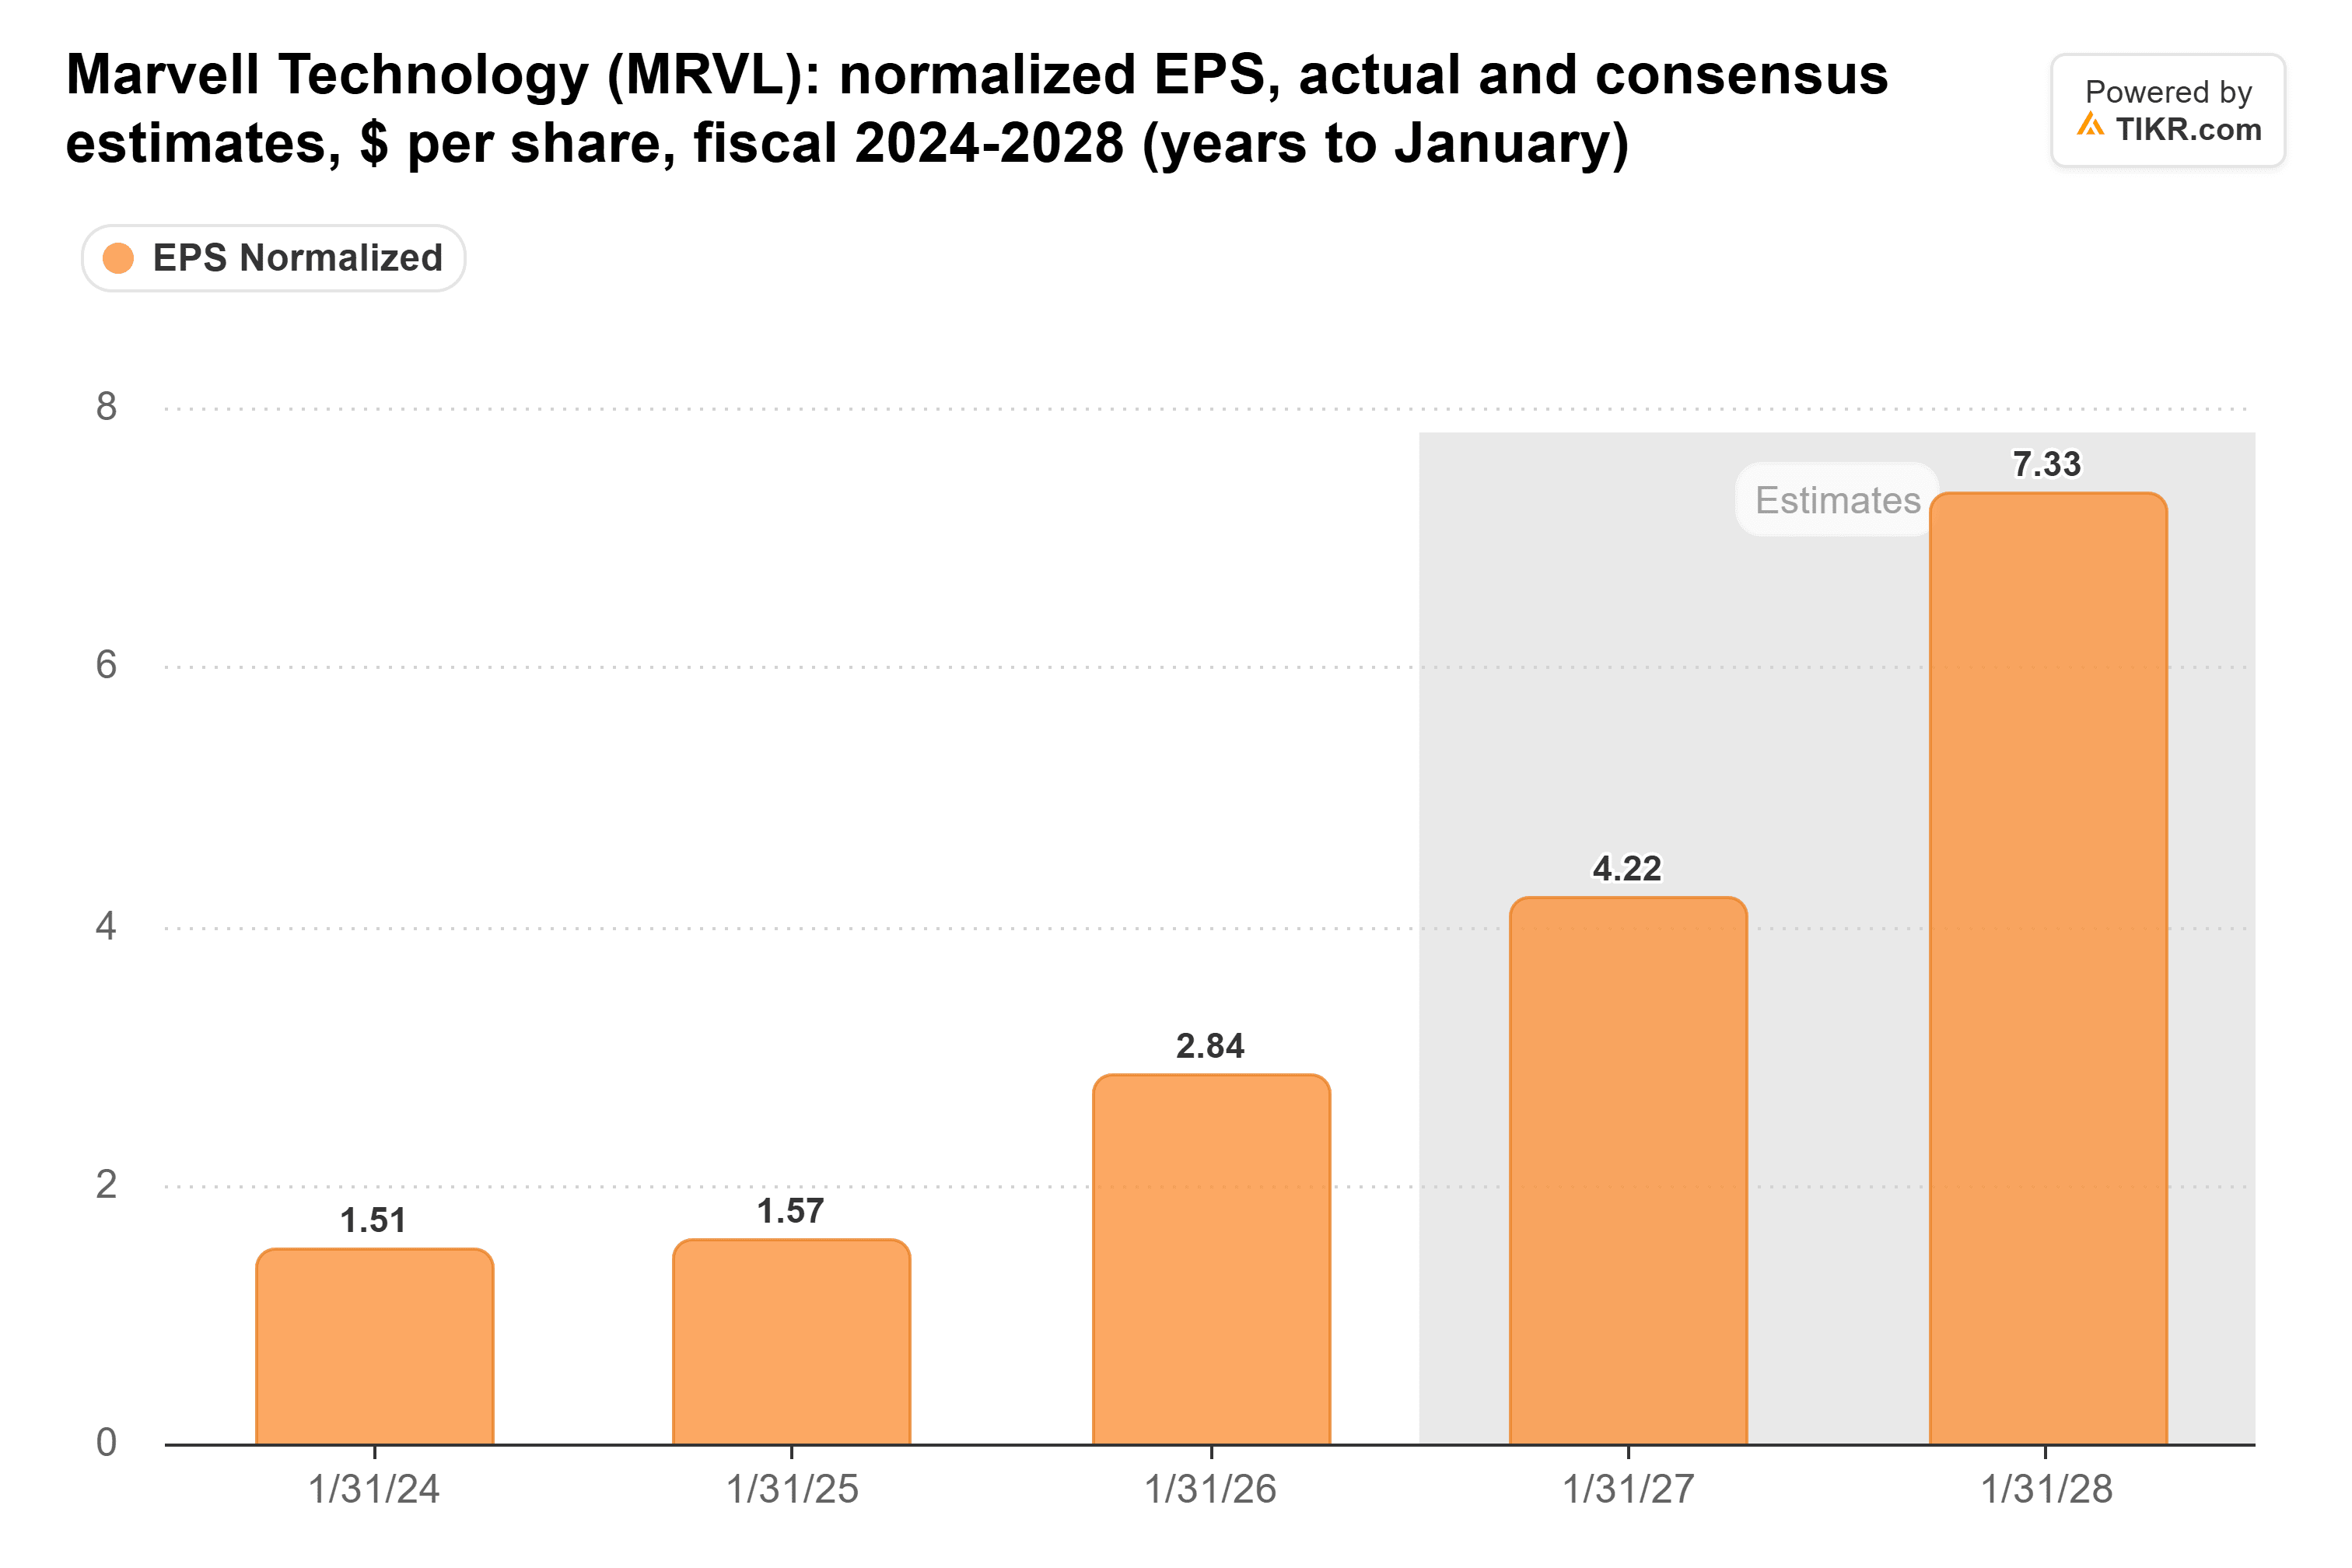
Those estimates are for Marvell alone, before any shares it issues for Lumentum, so expect them to be redone once the terms are out.
The multiple is the harder part. At Friday’s close, Marvell traded at 35x the earnings analysts expect over the next twelve months, against a five-year average of 33x:

Piper’s $400 works out to about 71x that $5.65 a share, a touch above the 70x peak Marvell hit on June 4, the day of its closing high.
The generous reading: by this time next year, the next twelve months will lean on fiscal 2029, when analysts expect $12.61 a share. If analysts are right, paying $400 then would mean a much lower multiple.
Wait for the terms
Raymond James analysts said the deal could leave Marvell’s earnings per share flat by 2028 or cut them by more than 10%, depending on its structure. And Marvell’s diluted share count already rose from 873.0 million to 921.2 million in the two quarters to Aug. 1.
Piper may be right about the lasers. But reaching $400 would take a peak multiple on estimates and an all-stock deal is about to rewrite, and I wouldn’t bank on it until Marvell shows how many shares it’s handing over.
Those terms could come as soon as next week, and Marvell reports its Q3 in early December, against guidance of $3.15 billion in revenue.
So what is Marvell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!