


Key Takeaways
- PayPal shares fell 5% after a CFO swap, new business heads and its risk chief’s exit.
- Clear Street sees a “lower likelihood” of a sale, so the turnaround has to work on its own.
- PayPal’s new Venmo chief challenges Block, and a reported takeover look at another company in the sector shows buyers still want it.
- PayPal trades far below its usual forward P/E, and its first scorecard comes in early February.
PayPal (PYPL) shares fell 5% today after it named a new CFO and three new business heads, and said its chief risk officer is leaving. Clear Street now sees a “lower likelihood” of a sale.
Block (XYZ), whose Cash App competes with Venmo, fell too. The Nasdaq is down 5% too.
Lores picks his team
CEO Enrique Lores says “our focus is now on execution.” Claire Bramley, Xero’s CFO, joins Feb. 1 to succeed CFO and COO Jamie Miller. Kartik Mani, from American Express, will run consumer financial services and Venmo.
So much for the takeover floor
A reported bid of more than $53 billion fell apart in August, but hopes for another bid lingered. Clear Street said the changes “substantially” cut the odds of a sale.
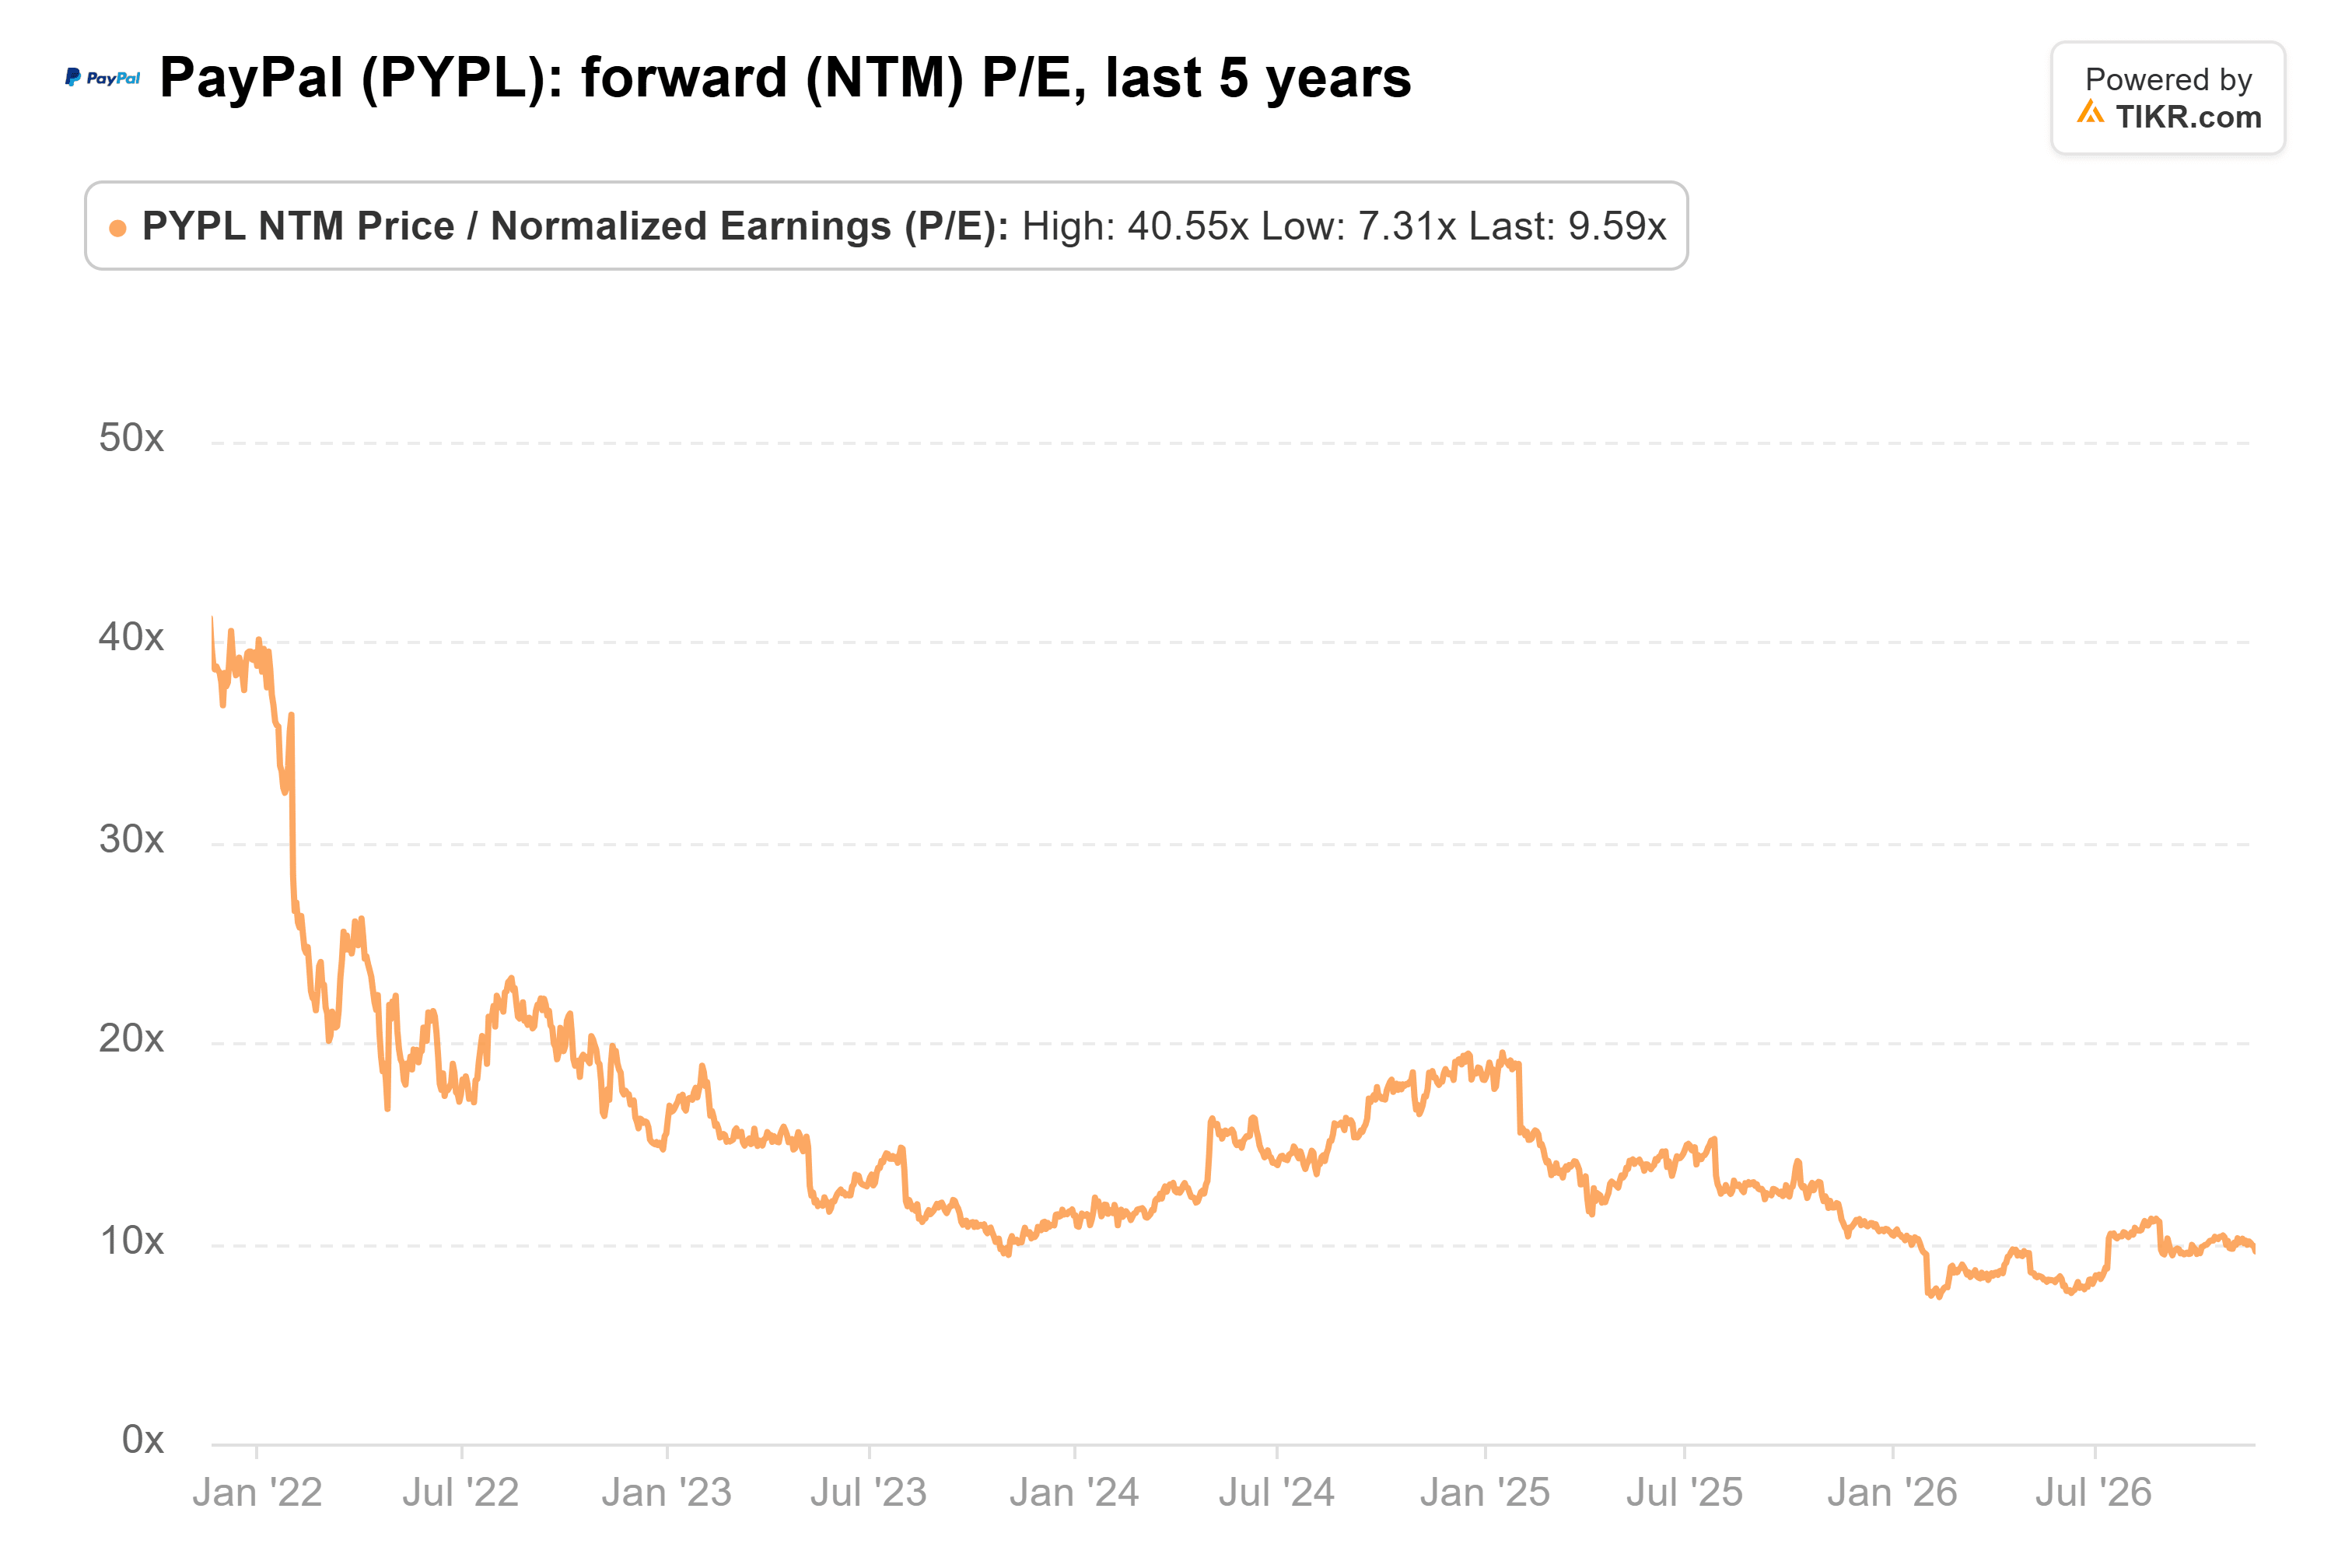
But Bloomberg reported that GTCR is exploring a roughly $50 billion takeover of Global Payments (GPN), which jumped 10%. My read: buyers are chasing the cheaper asset, at 5.4x forward earnings to PayPal’s 9.6x at the last close.
Block should pay attention to Mani’s hire. Cash App’s $2.07 billion of third-quarter gross profit, up 27%, beat Venmo’s $1.7 billion of 2025 revenue (excluding interest). If Venmo pushes into cards and credit, can Cash App keep that pace? Block, down 6%, reports Feb. 24.
TIKR tracks 43 analysts on PayPal. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PayPal, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PayPal’s Analyst Ratings
Now PayPal has to earn it
Analysts expect earnings to keep climbing:
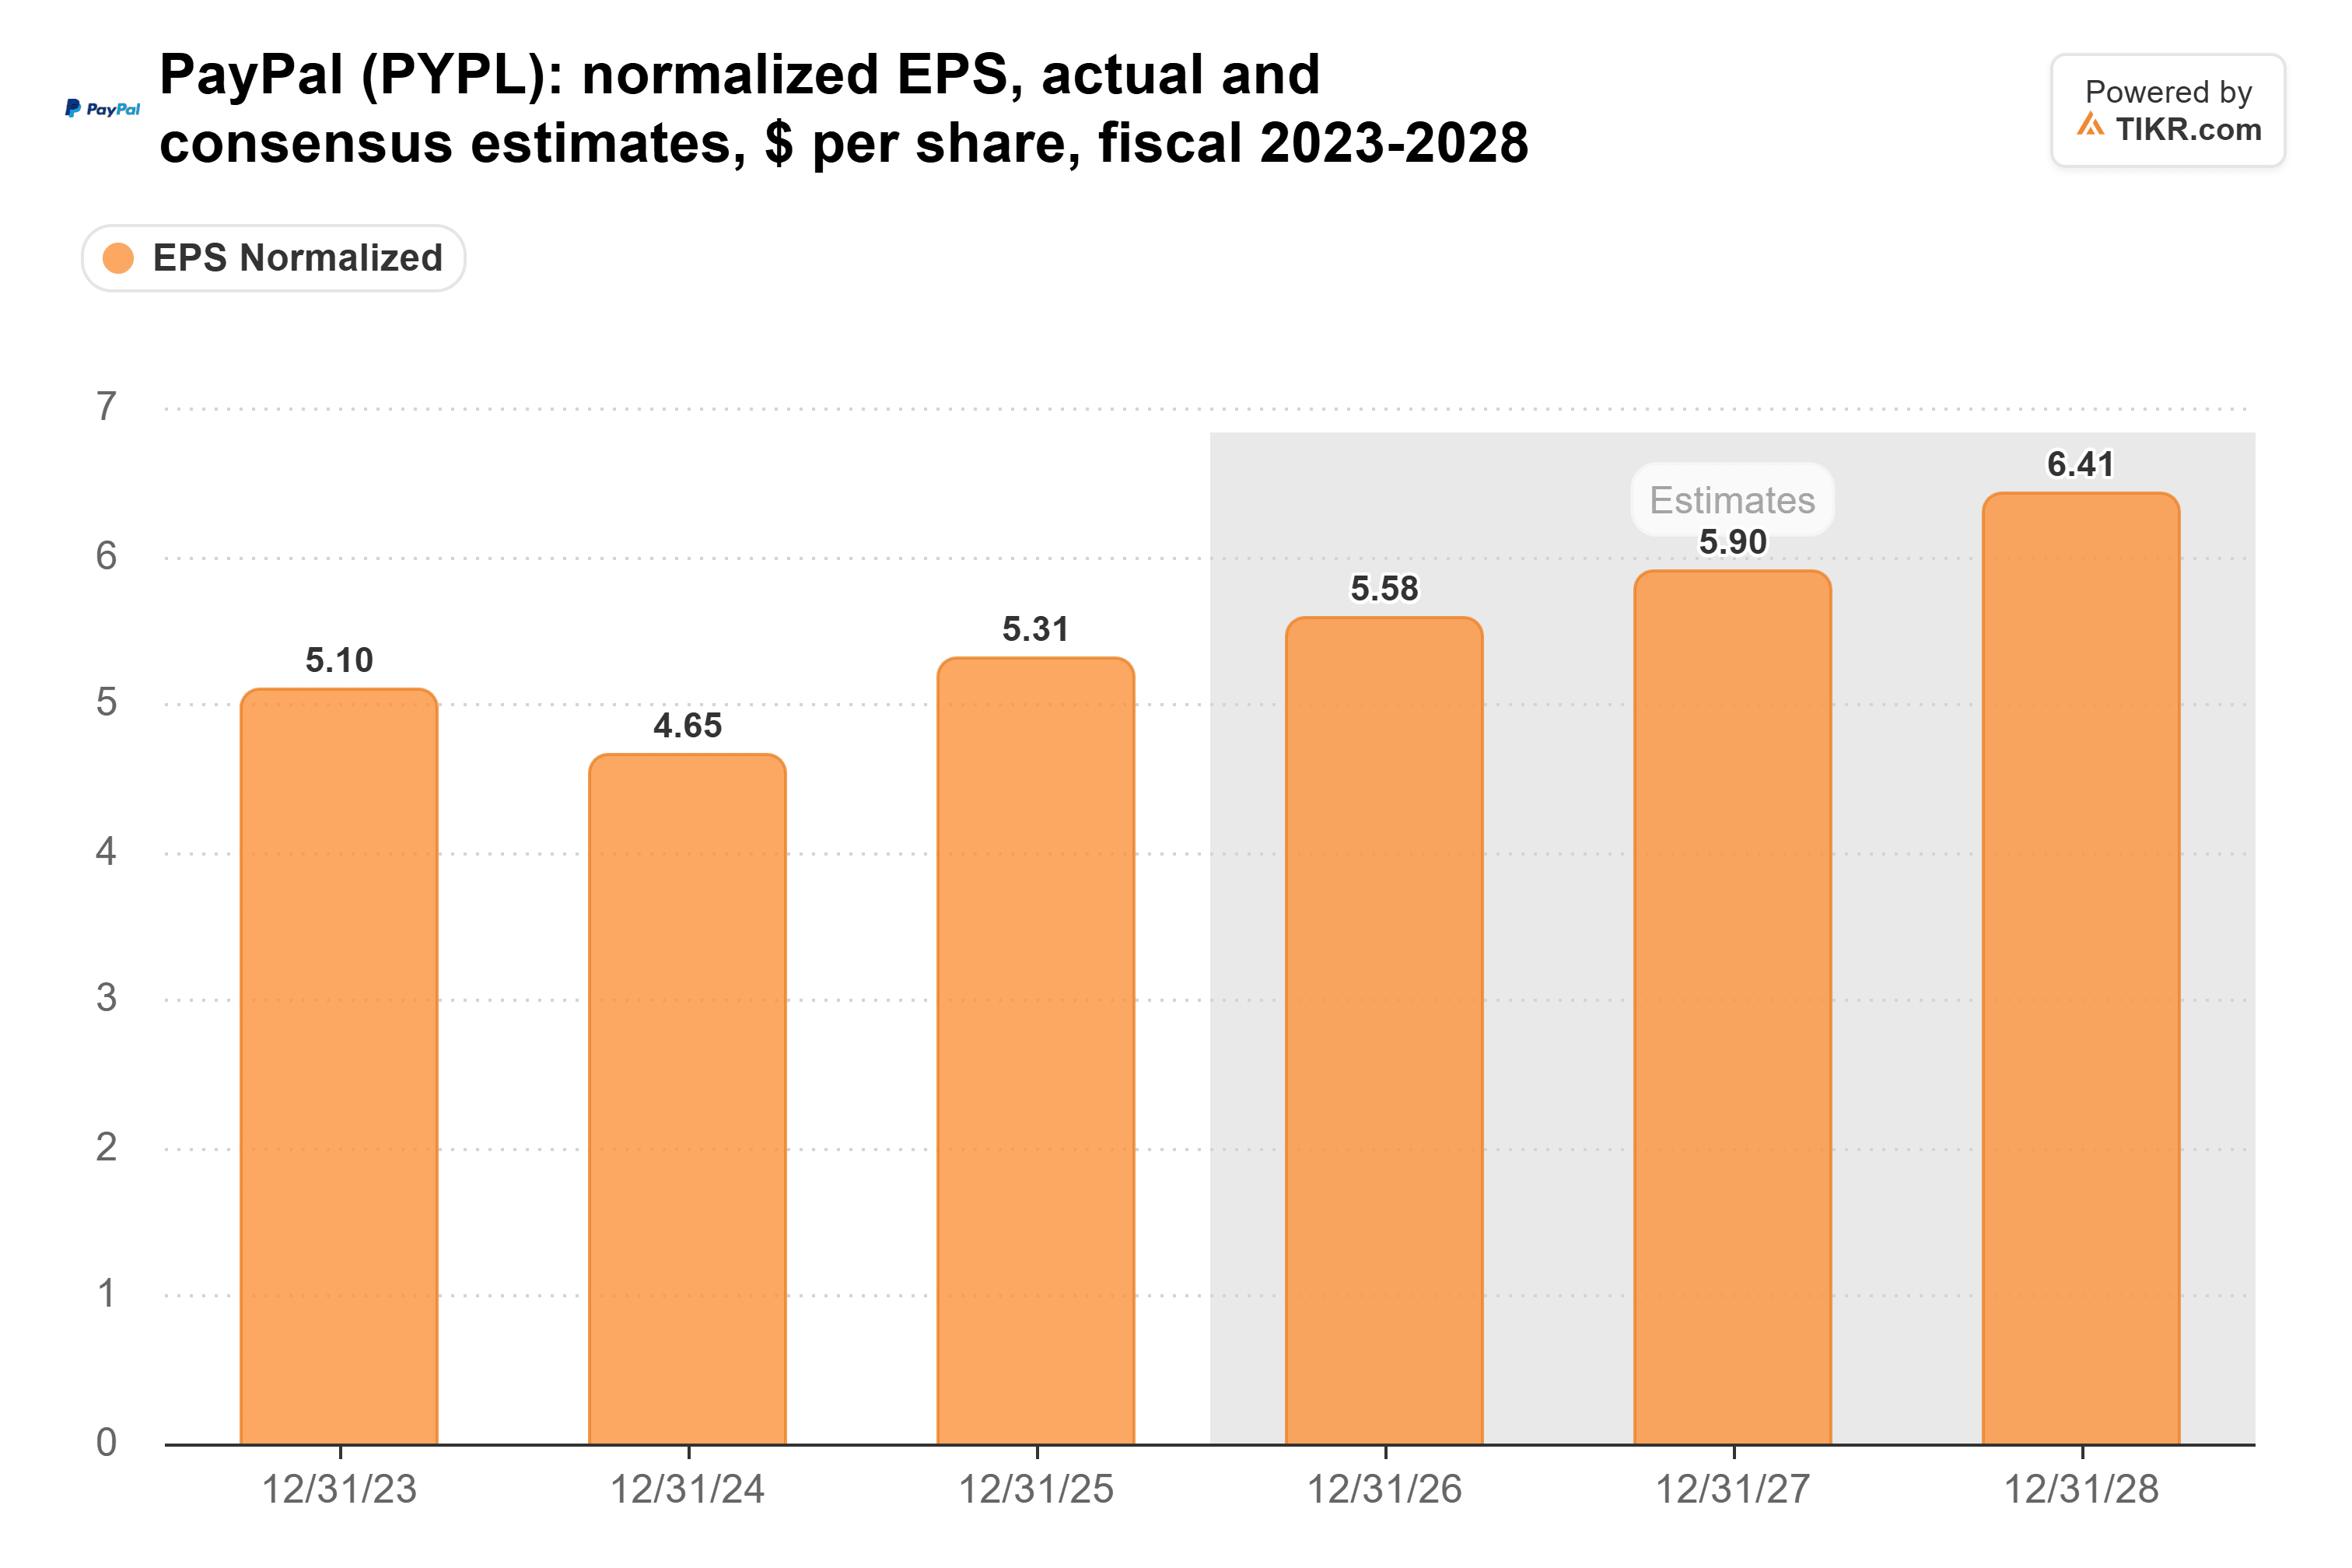
Much of that is buybacks: diluted shares fell to 882 million in the second quarter of 2026 from 977 million a year earlier.
The market isn’t paying for a turnaround. That 9.6x is far below PayPal’s five-year average of 15x, and today’s drop takes it lower:
Losing a risk chief as PayPal leans into lending isn’t ideal.
Still, losing the takeover floor hurts less than today’s drop suggests. At under 10x earnings, the new team just has to grow earnings faster than the share count shrinks. Lores promised an update with fourth-quarter results in early February, and currency-neutral branded checkout growth above 2%, its pace in each of 2026’s first two quarters, would be a good start.
So what is PayPal stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PayPal could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!








