Key Takeaways
- PayPal stock is up 11% in the past month, mostly before its Oct. 27 report, and Michael Burry called it a “Fat Pitch” again in his latest Substack post.
- Burry made the call amid buyout reports on Global Payments, and he sees even more value in Fiserv.
- Cost cuts and buybacks drove the profit gains, while revenue grew just 2%.
- At about 10x forward earnings, PayPal looks cheap enough to own, but it likely climbs only as fast as branded checkout.
PayPal (PYPL) stock is up 11% in the past month, even as the Nasdaq 100 slid into a correction. More than half of that gain came by Oct. 12, two weeks before earnings. The Oct. 27 profit beat held it, and the stock rose another 3.1% on Monday after Michael Burry’s latest post.
In his latest Substack post, Burry again called PayPal a “Fat Pitch” at prices in the $50s. He wrote it after Reuters reported that Clayton Dubilier & Rice was in early talks to buy Global Payments (GPN) alongside GTCR, its biggest shareholder, and he saved his biggest case for Fiserv (FISV).
Burry likes Fiserv best
Burry values Global Payments, up as much as 18% on Friday on the reports, at just $45-$60 a share, even with a control premium. He puts Fiserv’s takeout value at $100-$120, at least double the $50.02 he used.
He’s been bullish on PayPal since April, when he disclosed a position of about 3.5% of his portfolio. In July, he called Stripe and Advent’s reported $60.50-a-share offer too low, and the bid collapsed in August.
PayPal cleared a low bar
The third quarter beat on profit and missed on sales:
- Revenue rose 2% to $8.58 billion, short of the $8.71 billion expected.
- Non-GAAP EPS rose 8% to $1.45, against a $1.31 consensus.
- Management raised its 2026 non-GAAP EPS guide to about $5.60, from about $5.38.
Non-transaction operating expenses grew just 1%. But branded checkout, the button PayPal has called its main source of profit, grew only 1% on a currency-neutral basis, with the end of the EU’s duty exemption on low-value parcels costing it about 70 basis points.
Fewer shares, higher EPS
Consensus has normalized net income flat at about $4.7 billion in 2026 and 2028, so EPS grows only as PayPal retires shares, about 117 million over the past 12 months:
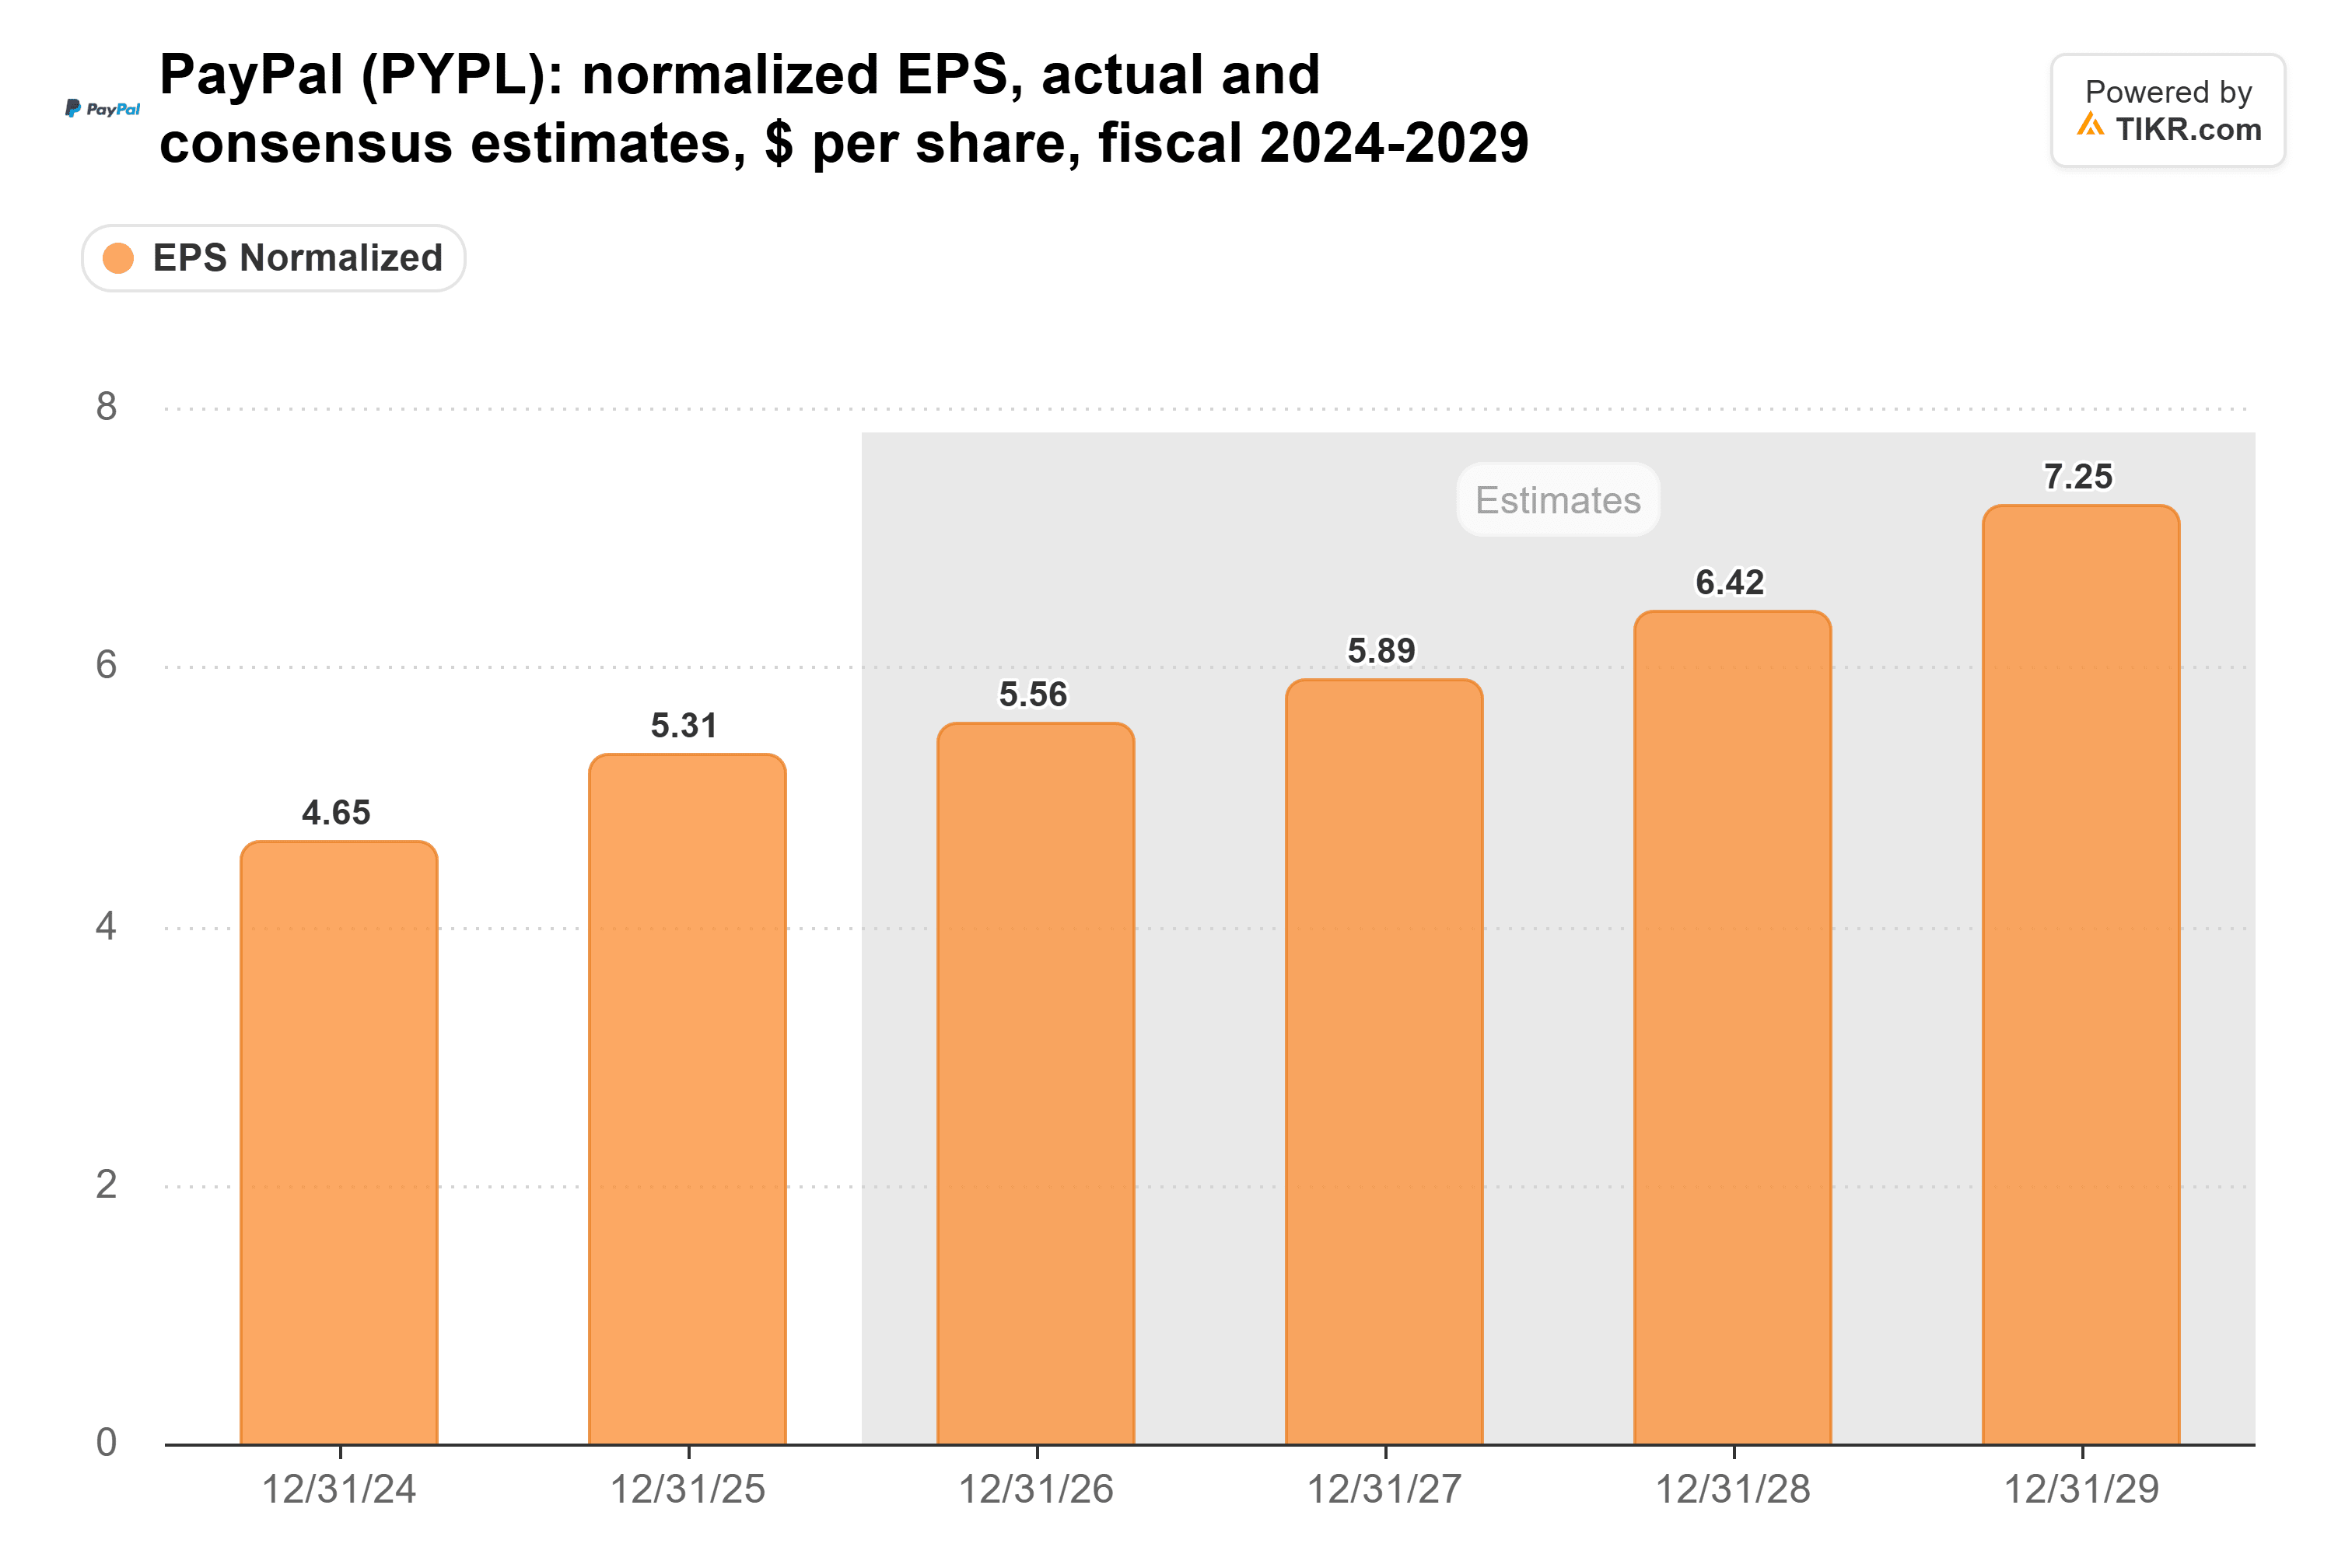
And I don’t expect big upward revisions: management called 2027 an investment year, with EPS growth similar to this year’s.
TIKR Tracks 43 Analysts on PayPal. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PayPal, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PayPal’s Analyst Ratings
Cheap enough to wait on
PayPal traded at 9.7x forward earnings on Oct. 30, against a five-year average of 16x:
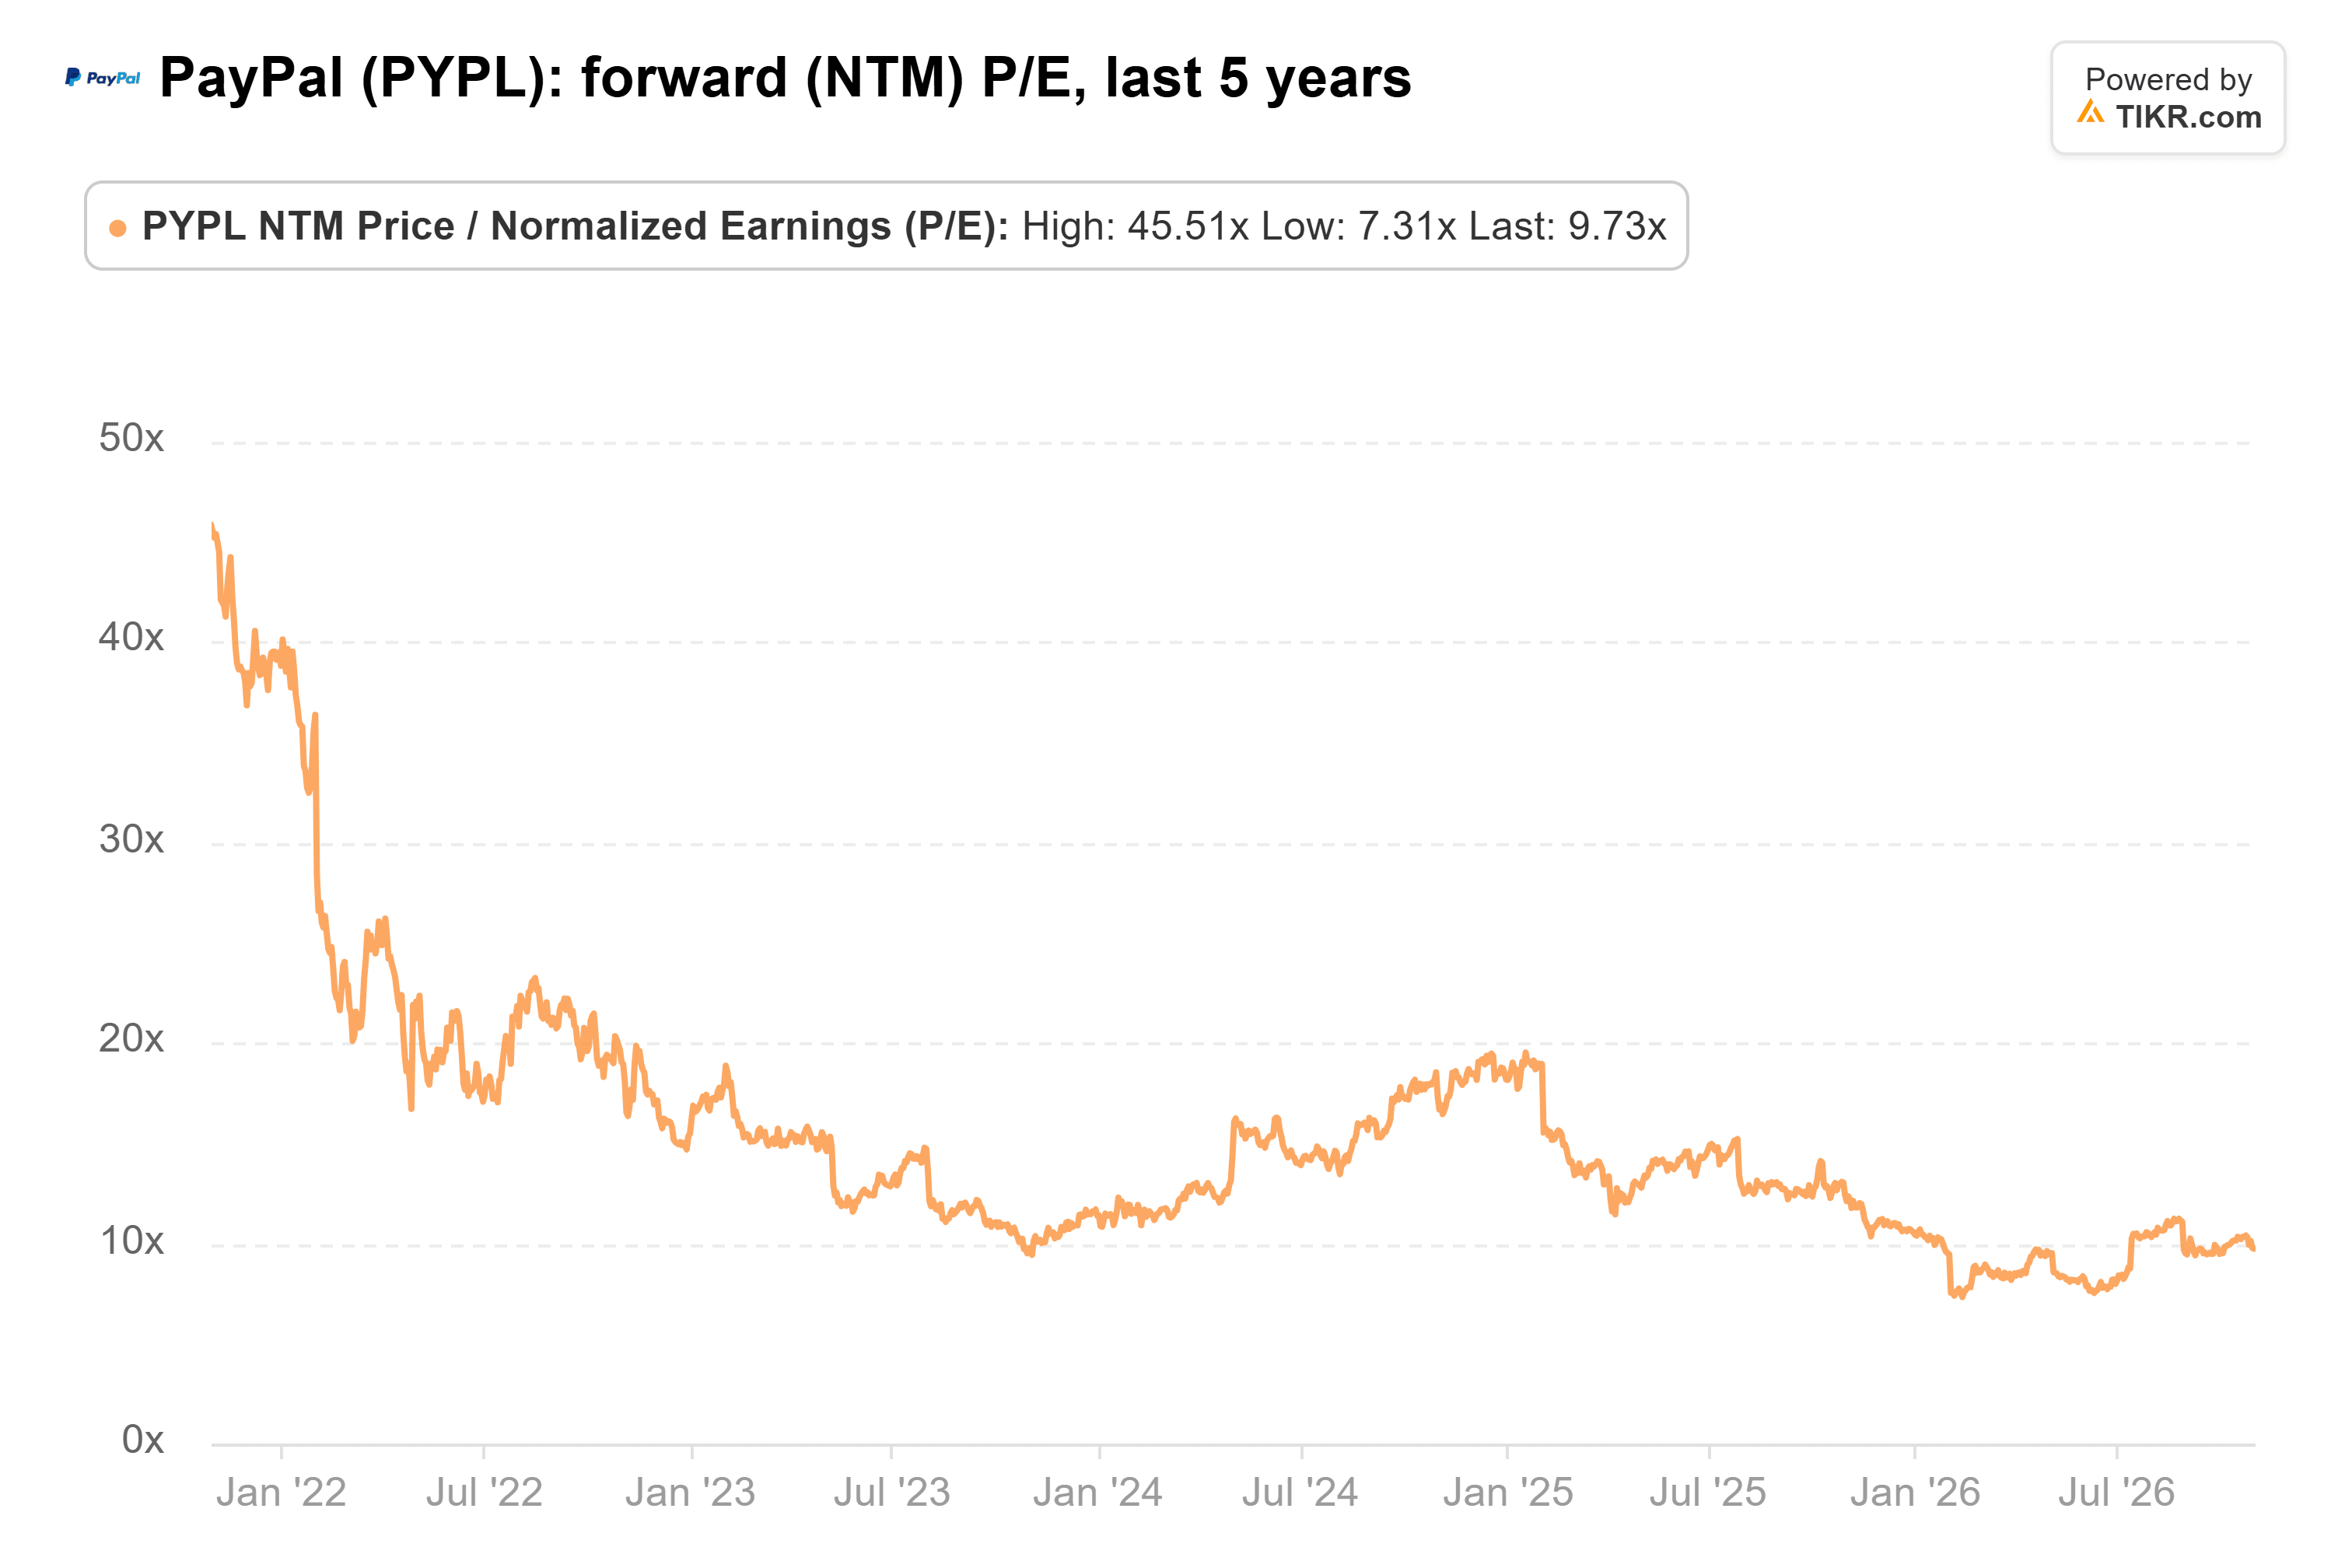
Wall Street still isn’t sold. Barclays downgraded the stock to Underweight on Oct. 29, citing slowing fundamentals, and the $57 consensus target sits below the share price.
Frankly, I think Burry has the better case. At about 10x earnings and with at least $6.5 billion of adjusted free cash flow guided for 2026, PayPal is cheap enough to own. But with net income flat, it likely climbs only as fast as branded checkout.
Fourth-quarter results early next year bring 2027 guidance, and a better read on branded checkout.
So what is PayPal stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PayPal could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!