Key Takeaways
- Freedom Capital Markets cut its Caterpillar (CAT) price target to $800 from $980 on Nov. 2 and kept its Buy rating, which still leaves 30% upside.
- Caterpillar is 42% below its June 30 closing high, even after a third quarter with record sales and a record $78 billion backlog.
- Analysts’ earnings estimates have held up through the slide, so the drop came from the multiple investors will pay.
- Freedom’s target needs about 27x forward earnings against a five-year average of 19x. That premium looks unlikely to return while management guides margins near the bottom of its range.
Caterpillar just reported the biggest sales quarter in its history, and the stock is still 42% below its June 30 closing high.
On Nov. 2, Freedom Capital Markets cut its price target to $800 from $980 and kept its Buy rating. That still leaves 30% upside.
AI jitters, then a softer Q4
Power for data centers made Caterpillar one of 2026’s AI trades, so worries about AI spending hit it hard. On Oct. 26, Wells Fargo cut its target to $840 from $1,155, which was further reduced to $805 later, citing mounting stress around AI funding.
Then came the Oct. 29 report. Q3 sales and revenues rose 17% from a year earlier to $20.7 billion, and power generation sales grew 30%, mostly on data center demand.
The Q4 outlook was softer. “For the Q4, we anticipate moderate sales growth versus the prior year,” CFO Kyle Epley said on the call.
Management expects construction dealers to cut about $1.6 billion of inventory in the quarter, roughly a $1 billion hit to that segment’s sales volume.
And excluding tariff refunds, it still expects this year’s adjusted operating margin near the bottom of its target range.
TIKR tracks 31 analysts on Caterpillar. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Caterpillar, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Caterpillar’s Analyst Ratings
Freedom still likes the business
Freedom says it remains constructive on Caterpillar’s long-term fundamentals, and that the cut reflects a more conservative view of what the shares are worth.
The backlog hit a record $78 billion at the end of September, up 96% in a year.
CEO Joe Creed said Caterpillar is now “taking some large reciprocating orders as far out as 2029 and turbine orders into 2030.”
$800 needs a 27x multiple
Thirty-one analysts cover Caterpillar. Their consensus target has climbed from $544 a year ago to $838 on Oct. 30, 36% above the stock price:

Freedom’s $800 sits 5% below that.
Earnings estimates have held up. Analysts expect normalized EPS of $27.50 in 2026, up from $24.72 three months ago and $19.06 in 2025. They expect $32.22 in 2027 and $38.77 in 2028:
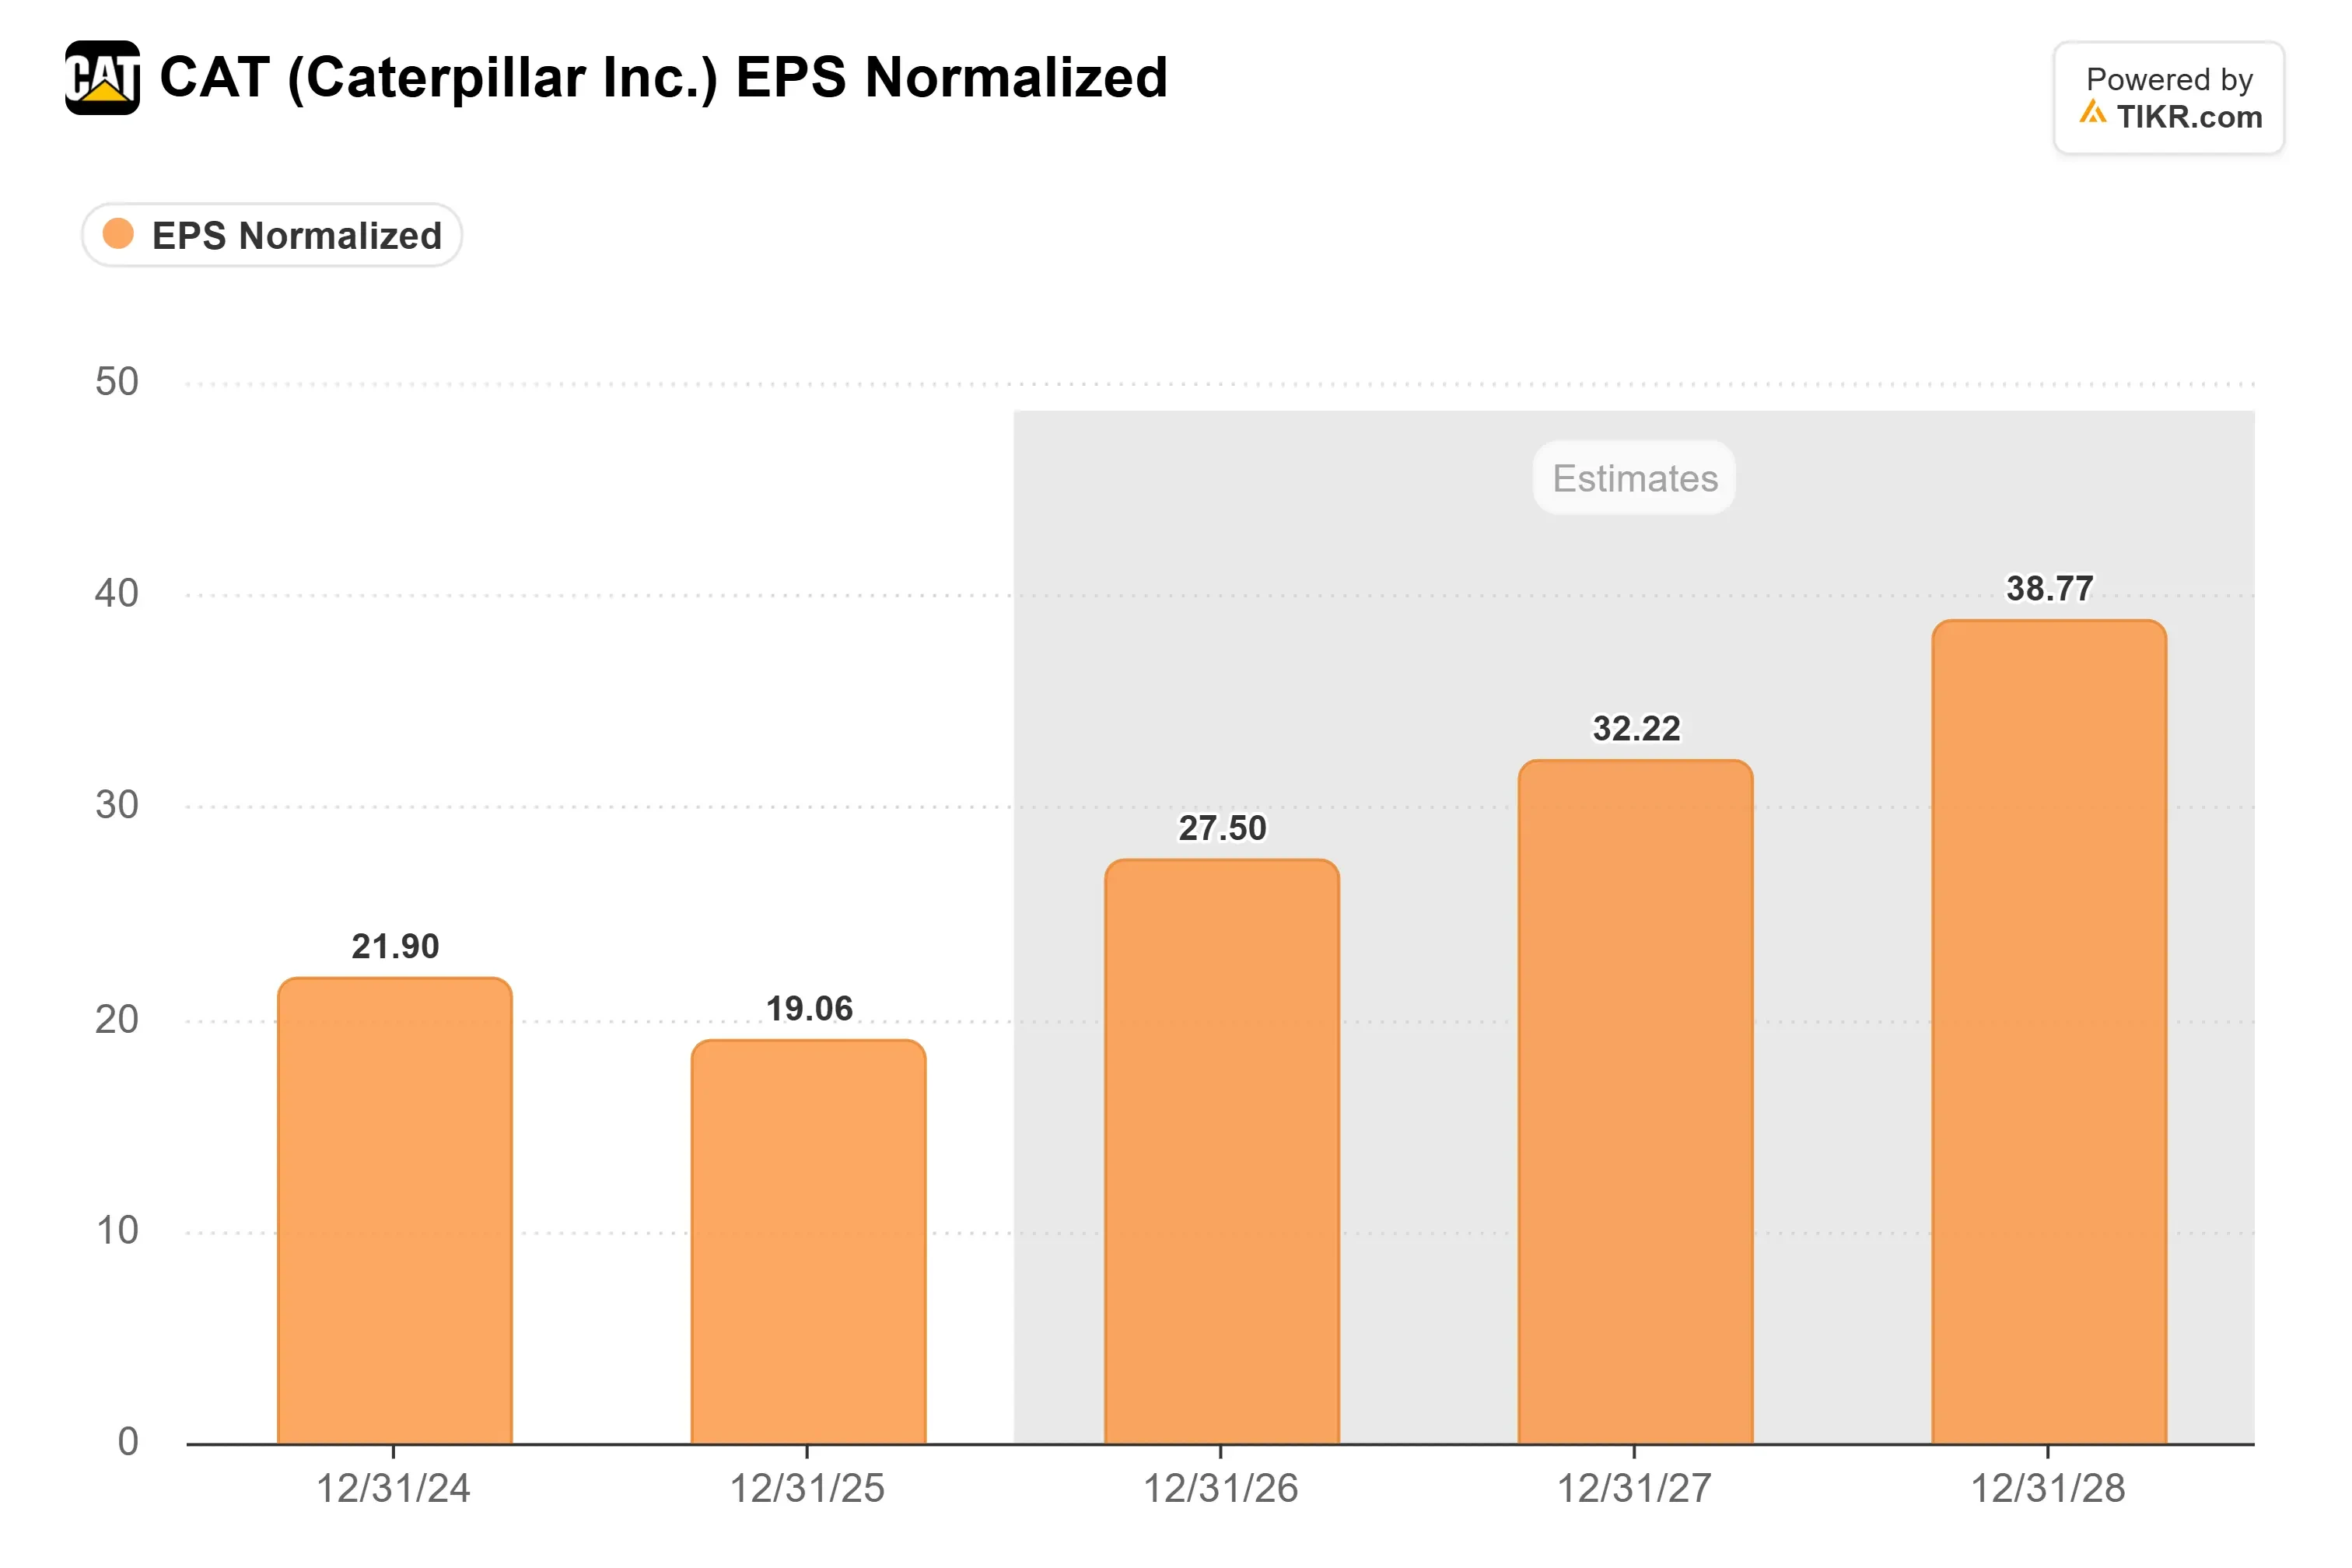
So investors are paying less for bigger earnings.
Caterpillar traded at 21x forward earnings at the Oct. 30 close, against a five-year average of 19x and a June 30 peak of 42x:

Divide Freedom’s $800 by the $29.95 a share analysts expect Caterpillar to earn over the next 12 months, and the target implies about 27x. That’s well above the five-year average.
Freedom’s case skips the margins
To pay 27x again, investors need to believe power has made Caterpillar’s earnings steadier than in past cycles.
Meanwhile, management is guiding margins near the bottom of its range, and freight and capacity-expansion costs are still rising.
I think that’s what Freedom’s call misses. Until margins move up the range, I don’t see investors paying 27x again, even with earnings climbing. So I wouldn’t count on $800 within a year.
Management gives its first look at 2027 with Q4 results in late January, including where in its margin range it expects to land.
A guide off the bottom would make $800 look a lot more reasonable.
So what is Caterpillar stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Caterpillar could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!