Key Takeaways
- Dan Loeb’s Third Point opened a 675,000-share stake in Performance Food Group (PFGC) in the quarter ended June 30, while Steadfast Capital Management, which manages $10.36 billion, sold 96% of its shares in the same quarter.
- Performance Food is down 10% since June 30, which so far is the better result for the seller.
- Analysts expect normalized EPS to jump from $4.55 in fiscal 2026 to $5.63 in fiscal 2027, and the stock trades at 18x forward earnings against a five-year average of 16x.
- Steadfast has the better case on today’s numbers, and Performance Food’s report in early November is the first test of the jump analysts expect.
Dan Loeb’s Third Point bought Performance Food Group in the three months to June 30. Steadfast Capital Management, which manages $10.36 billion, sold nearly all of its stake over the same stretch.
Both moves come from the funds’ 13Fs for that quarter. They were filed Aug. 14 and are still the latest.
The next ones, for the quarter ended Sept. 30, are due by Nov. 16, and Performance Food reports again in early November.
Loeb is in, and Steadfast is nearly out
Third Point’s 13F shows a new stake of 675,000 shares worth $75 million. That’s 1.6% of its 13F holdings and its 22nd-largest position, at a firm that manages $28.73 billion in all.
Steadfast’s filing shows the opposite move. It cut its shares by 96%, leaving 131,200 shares worth $15 million, or 0.4% of its 13F holdings. A quarter earlier, Performance Food accounted for 11% of the fund.
Neither filing says what the funds paid, or whether they still hold those shares. But the stock has fallen 10% from its June 30 close to Monday’s, so on price alone, Steadfast is ahead.
TIKR tracks 13 analysts on Performance Food Group. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Performance Food Group, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Performance Food Group’s Analyst Ratings
Analysts are counting on a big earnings jump
Performance Food’s fiscal 2026 results, released Aug. 12, show a business that’s growing, just not much per share.
Total case volume rose 3.5% in Q4, the three months to June, and cases sold to independent customers rose 8.0%. Adjusted EBITDA rose 9.2% for the full year, to $1.9 billion. But adjusted EPS grew just 2.6% in Q4, to $1.59.
Analysts expect that to change in a hurry. Their consensus has normalized EPS climbing from $4.55 in fiscal 2026 to $5.63 in fiscal 2027 and $6.69 in fiscal 2028:
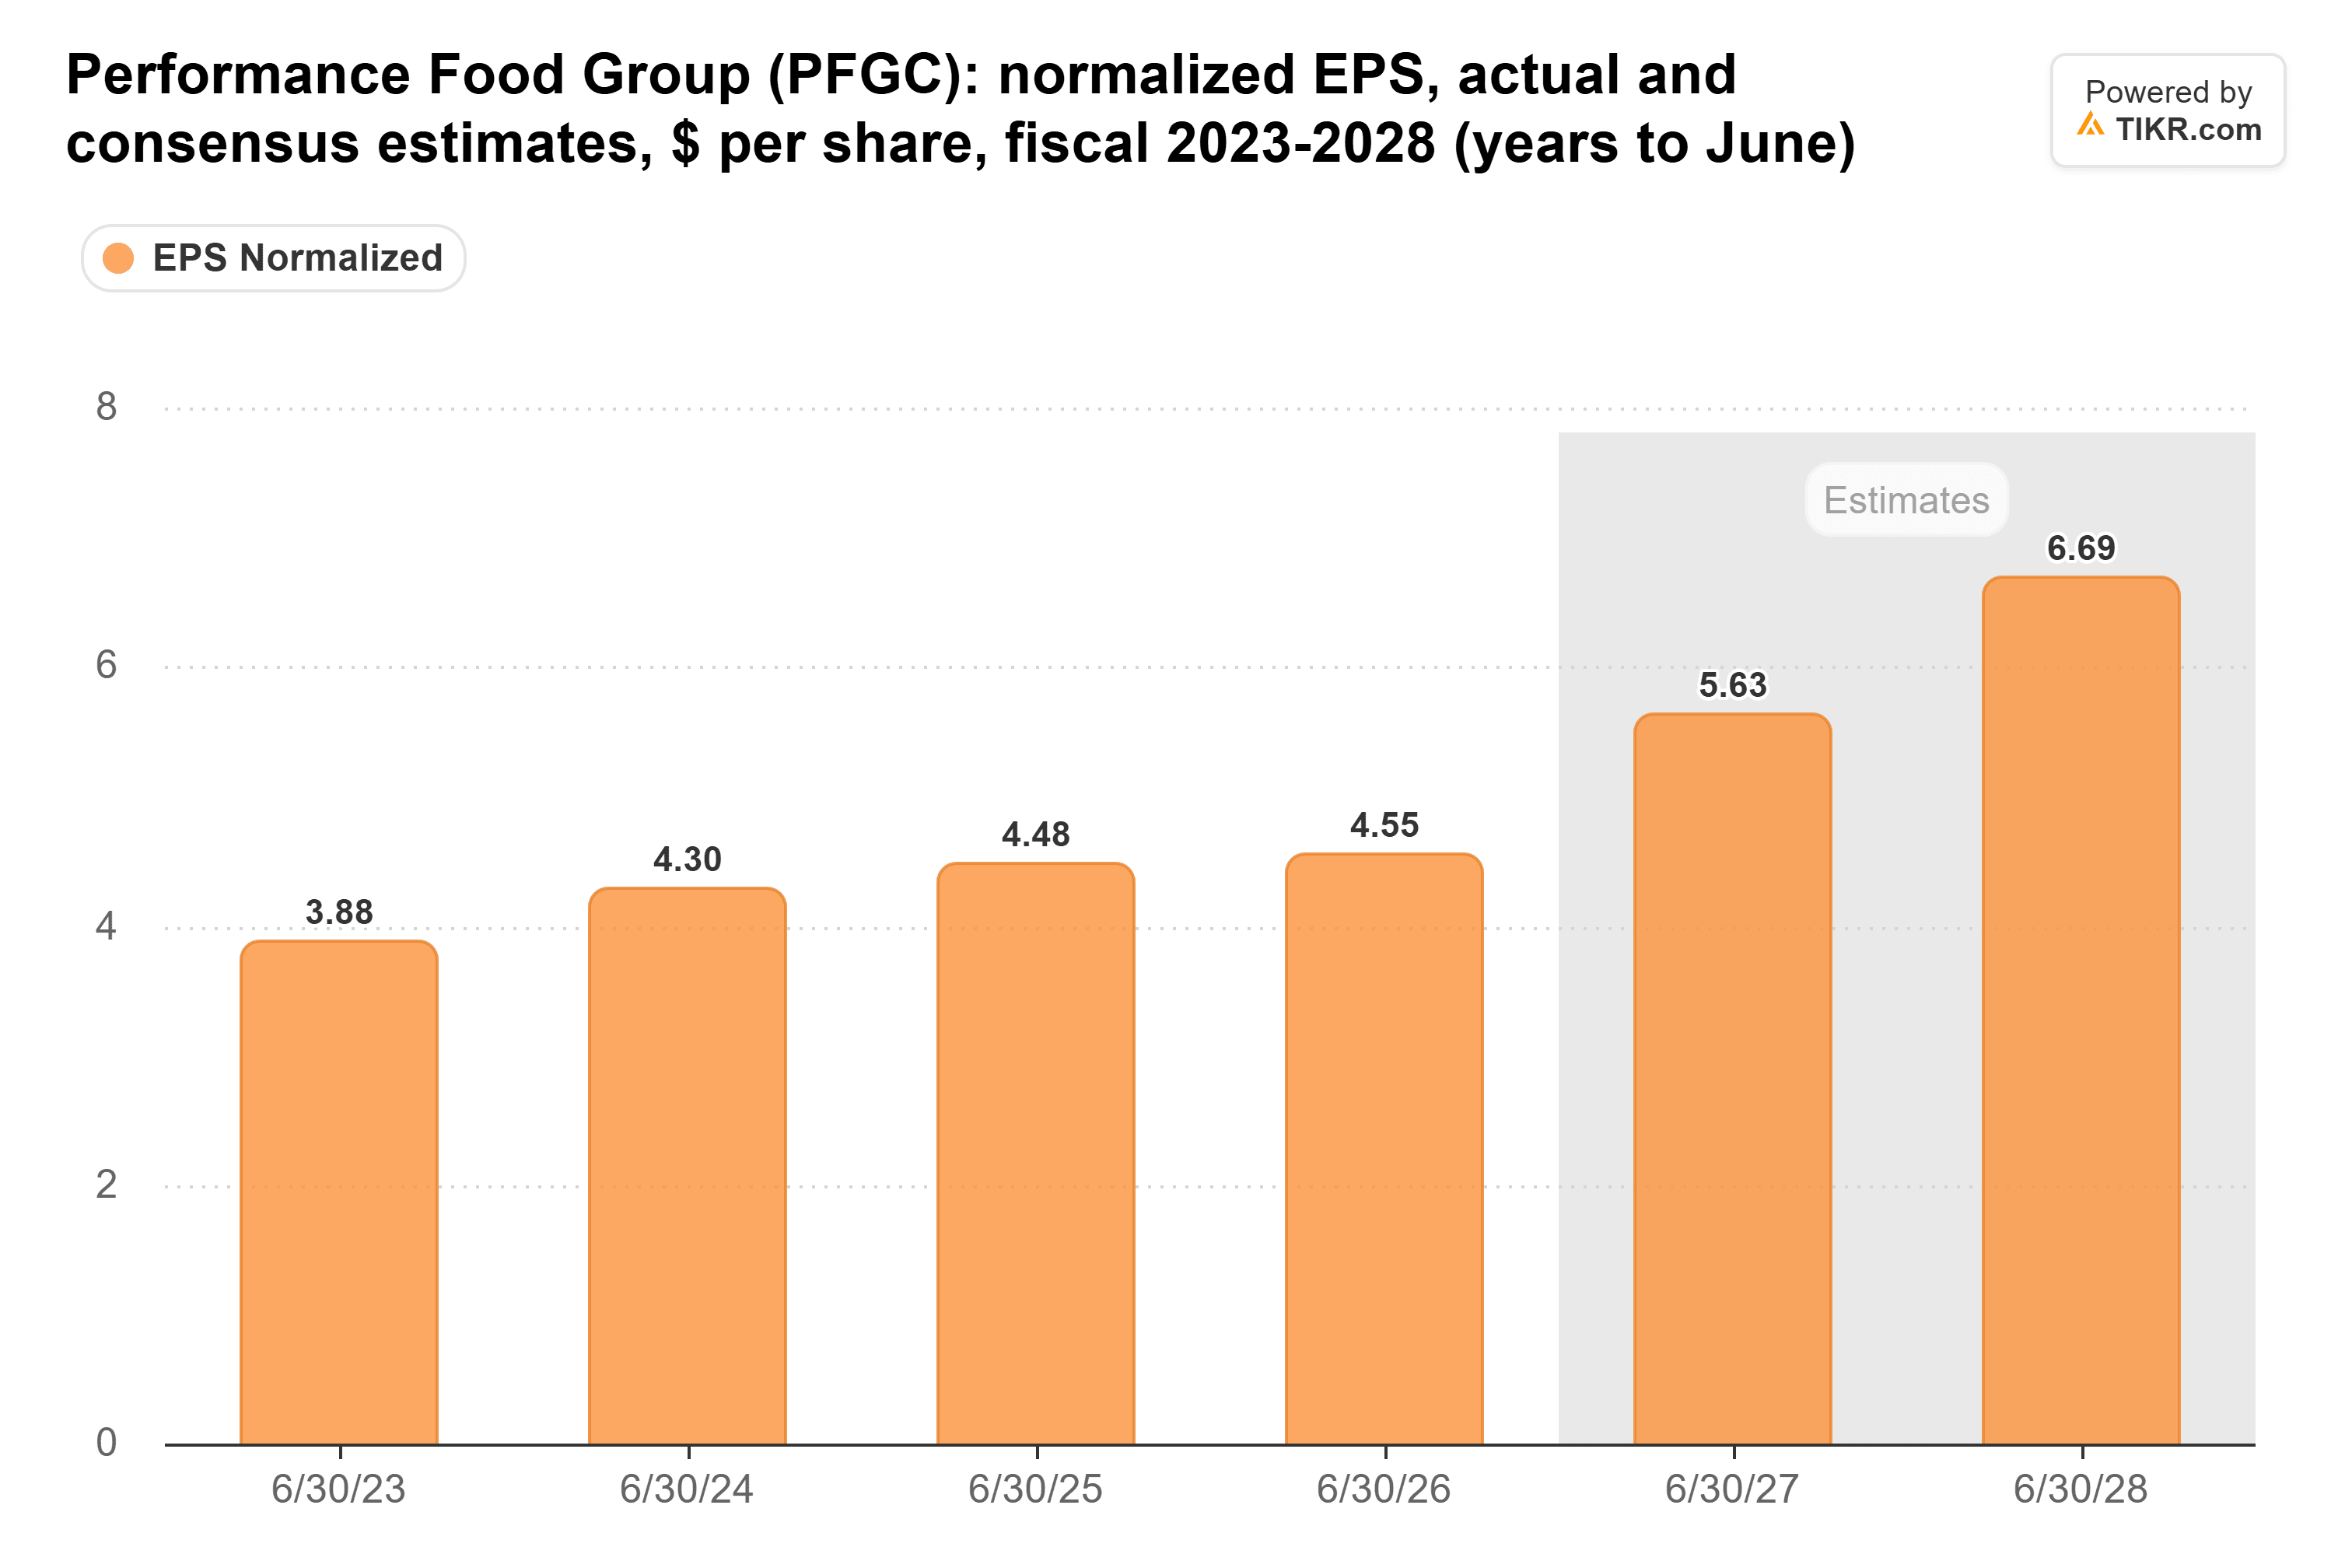
That’s about 24% growth this fiscal year, at a company whose normalized EPS went from $4.30 in fiscal 2024 to $4.55 in fiscal 2026.
Buying the stock here means betting that the jump arrives.
The stock isn’t cheap yet
Performance Food trades at 18x forward earnings. That’s above its five-year average of 16x, but well below the 22x it reached on July 29:
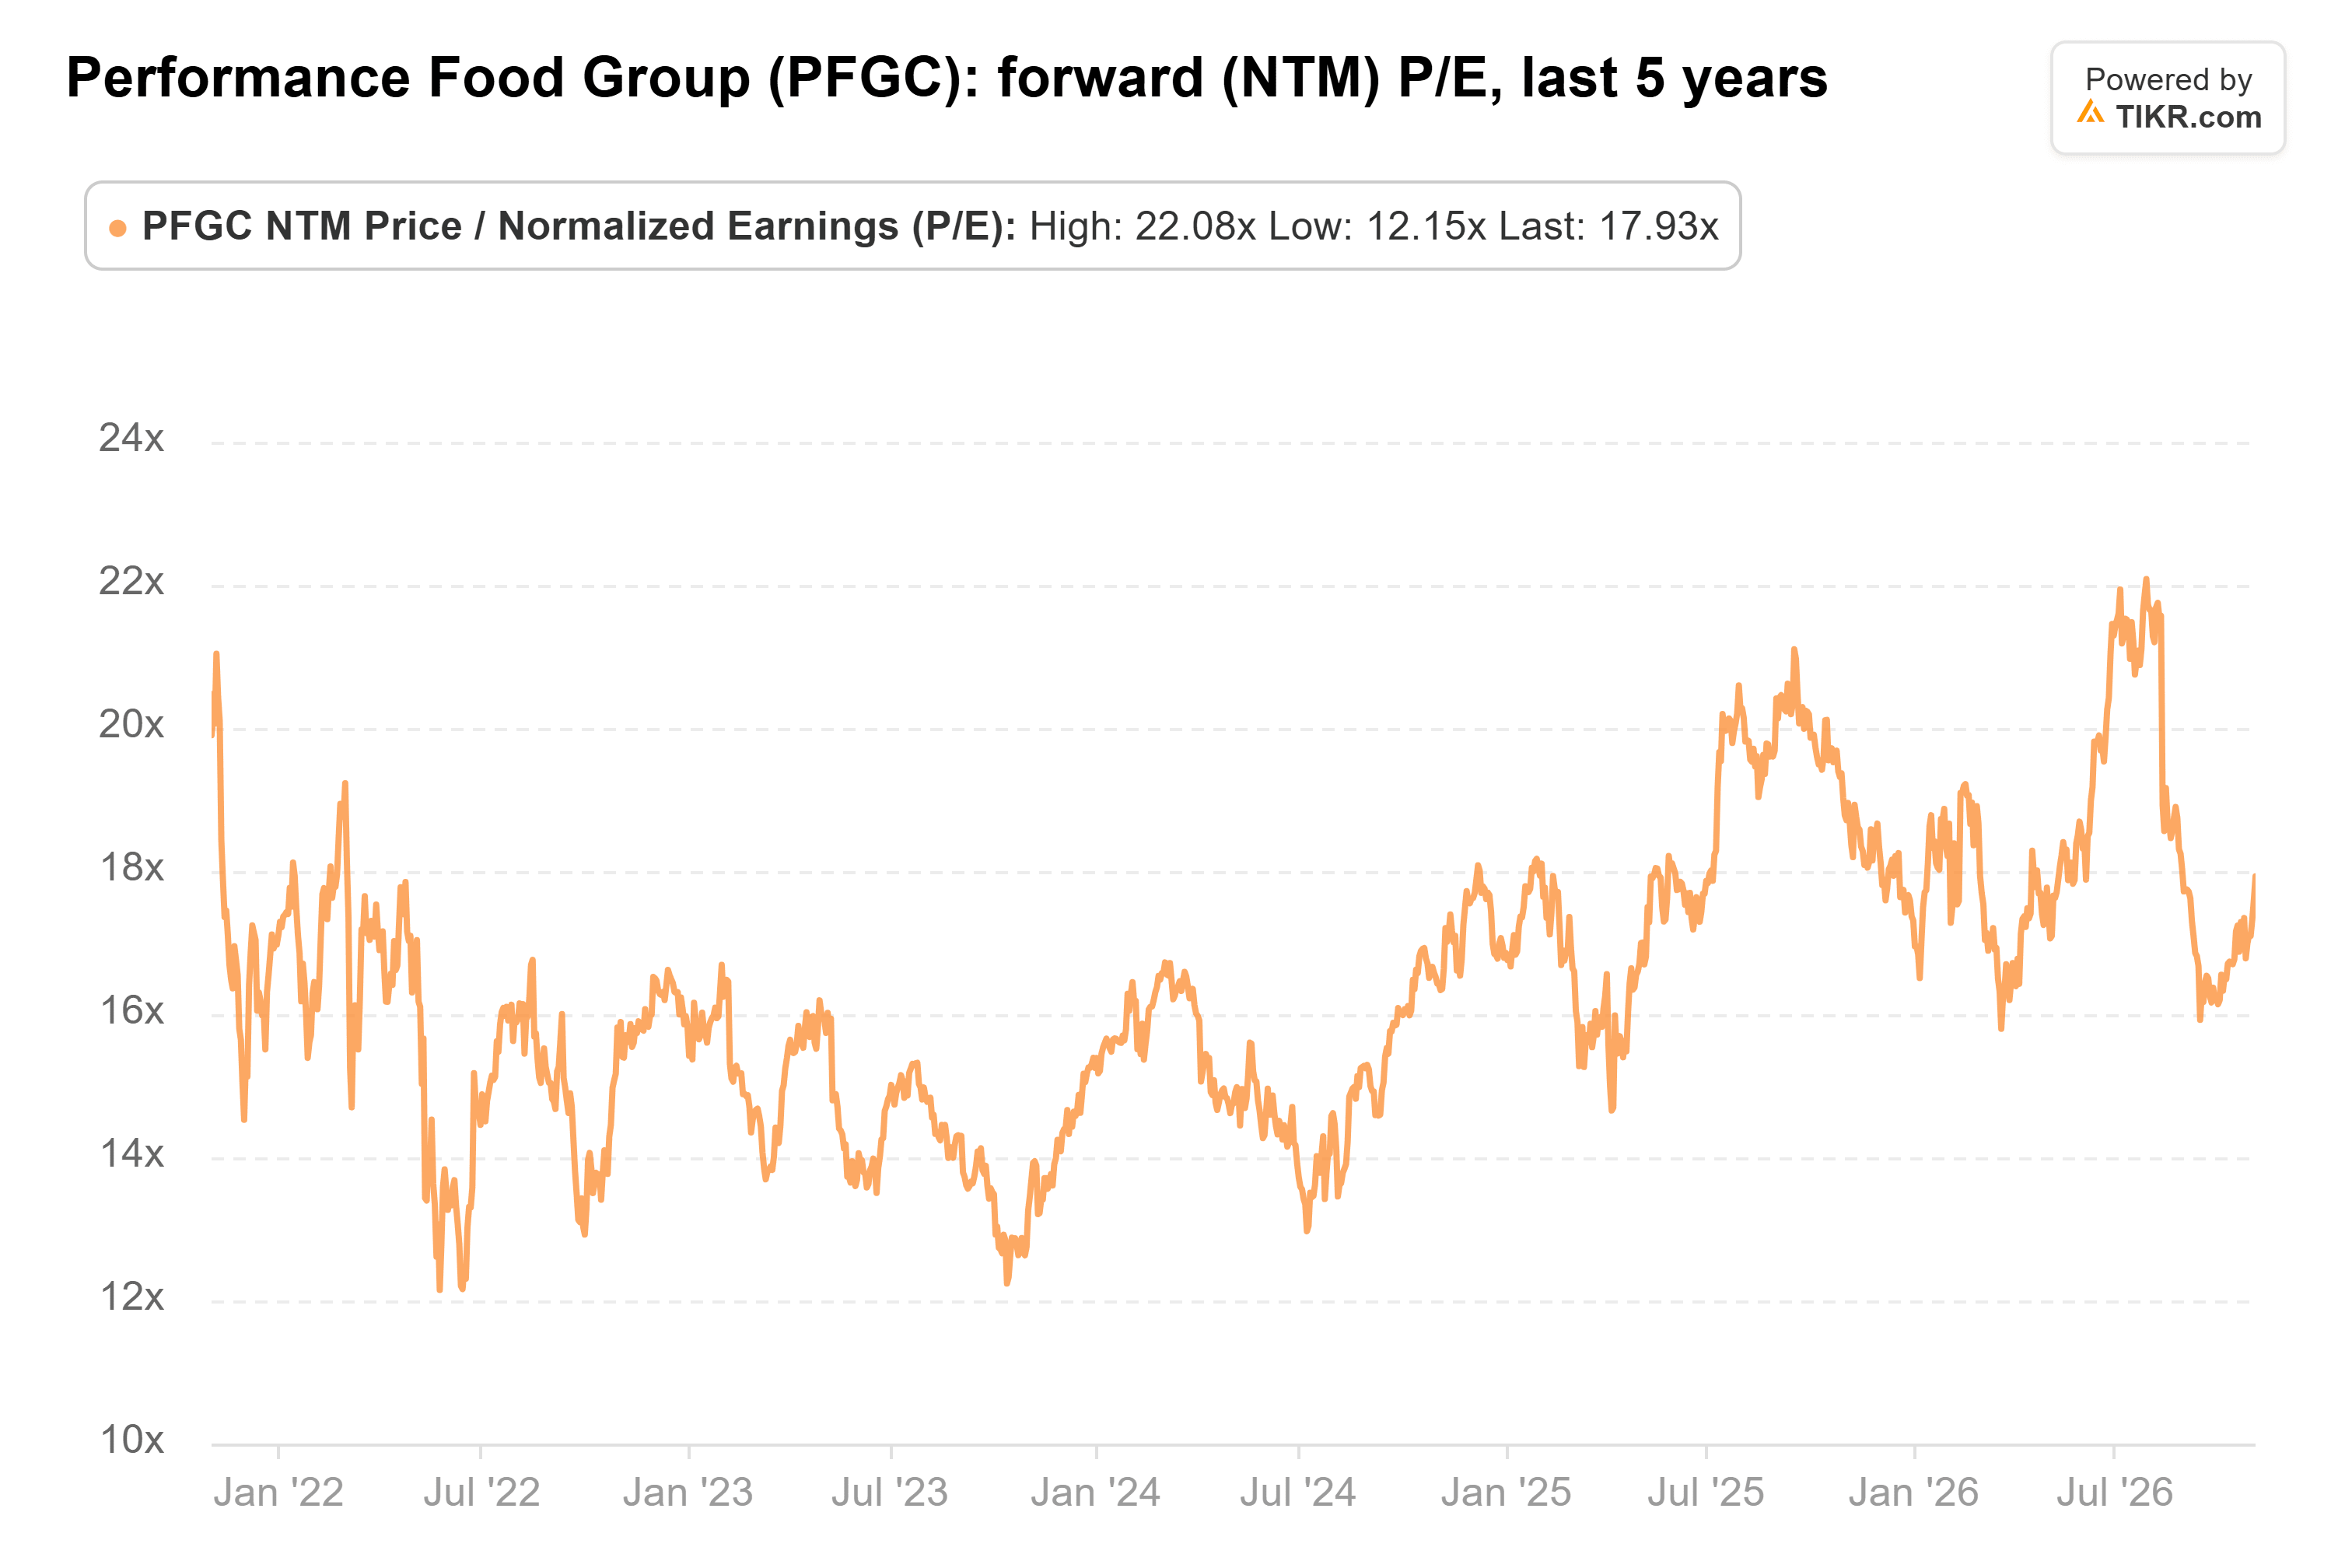
Investors are still paying more than usual for earnings the company hasn’t delivered yet.
Analysts haven’t lost faith, either. Their consensus target rose from $121 a year ago to $124 now, 23% above Monday’s close. Thirteen analysts cover the stock:
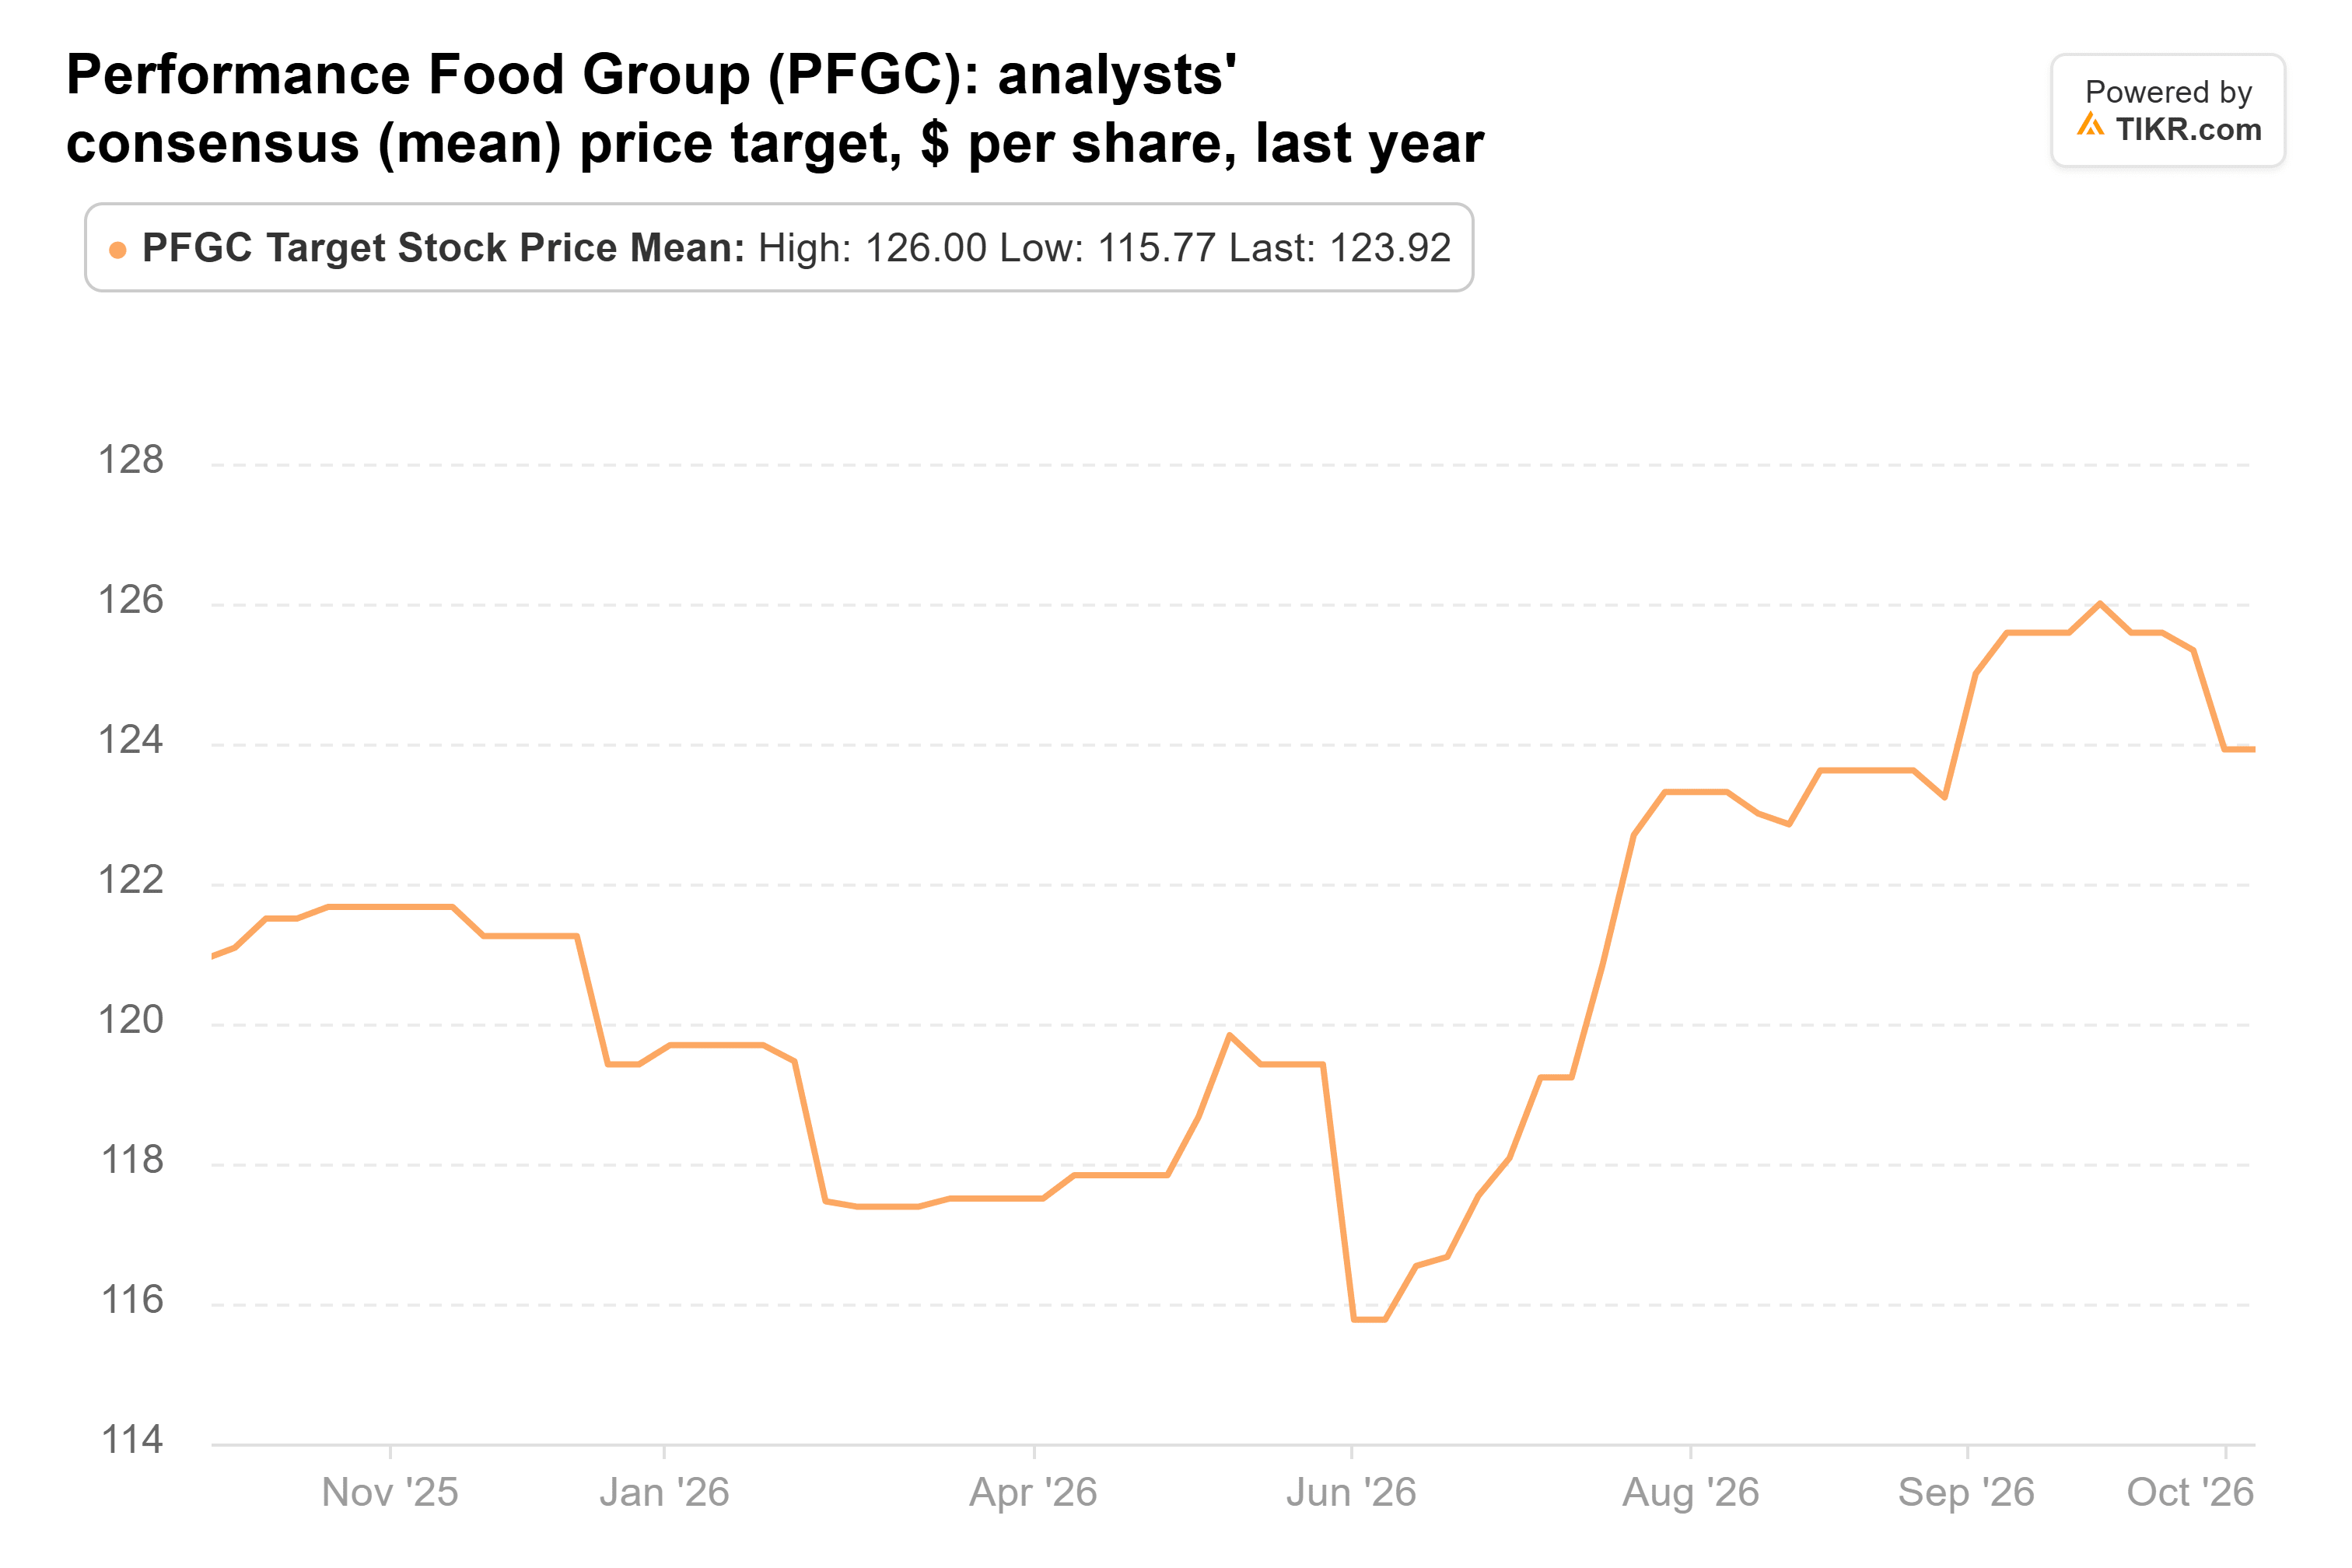
The range around that average has widened, though.
The highest target is $136, and the lowest has fallen from $114 a year ago to $79, below today’s price.
Steadfast has the better case, for now
The way I see it, Steadfast comes out ahead on these numbers. I’d want to see the fiscal 2027 jump start showing up before paying more than the stock’s usual multiple for it, especially after a Q4 of such slow per-share growth.
The low target falling to $79 tells me at least one analyst sees real downside if that jump doesn’t come.
Loeb’s side does have real support. The company keeps adding cases, and the consensus target has edged up through the year.
If the estimates hold, 18x won’t look like much for a business growing earnings that fast.
The early-November report covers Q1 of fiscal 2027, the three months to September, so it will give the first look at whether that jump is under way.
Then the 13Fs due by Nov. 16 will show whether Third Point held on through September, and whether Steadfast sold the rest.
So what is Performance Food stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Performance Food could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Performance Food for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!