Key Takeaways
- Palo Alto Networks reports fiscal first-quarter results on November 18, after a software selloff sent its shares down nearly 10% on November 5.
- Fortinet’s product revenue growth slowed to 37% from 52%, while Palo Alto’s product revenue grew 28.6% last quarter, so hardware demand is the first read.
- Palo Alto produced $4.41 billion in adjusted free cash flow in fiscal 2026 and is reportedly in talks to buy Clutch Security for about $500 million.
- Guidance calls for first-quarter revenue of $3.30 billion to $3.31 billion and a 38% adjusted free cash flow margin for fiscal 2027.
Palo Alto Networks (PANW) reports fiscal first-quarter results after the close on November 18. That setup got harder over the past two weeks.
The stock fell nearly 10% on November 5 as investors dumped this year’s software winners after the midterm elections. CrowdStrike (CRWD) dropped around 10% the same day, so the selling hit the whole group.
Fortinet (FTNT) had already shaken the sector a week earlier. Its third-quarter product revenue growth slowed to 37% from 52%, and its shares sank more than 25% the next morning.
That makes Palo Alto’s report the next big read on security demand. Its own numbers going in are solid, but they come with strings attached.
Firewalls are the first test
Palo Alto still sells a lot of hardware, so Fortinet’s slowdown hits close to home. Its fiscal fourth quarter, which ended July 31, held up well:
- Total revenue rose 34% to $3.41 billion.
- Product revenue grew 28.6% to $738 million.
- Subscription and support revenue climbed 36.2% to $2.67 billion.
Acquisitions inflate that 34% headline, though. Product revenue is the cleaner comparison with Fortinet, whose total revenue grew 20% to $2.08 billion last quarter.
Here is how Palo Alto’s product line has trended…
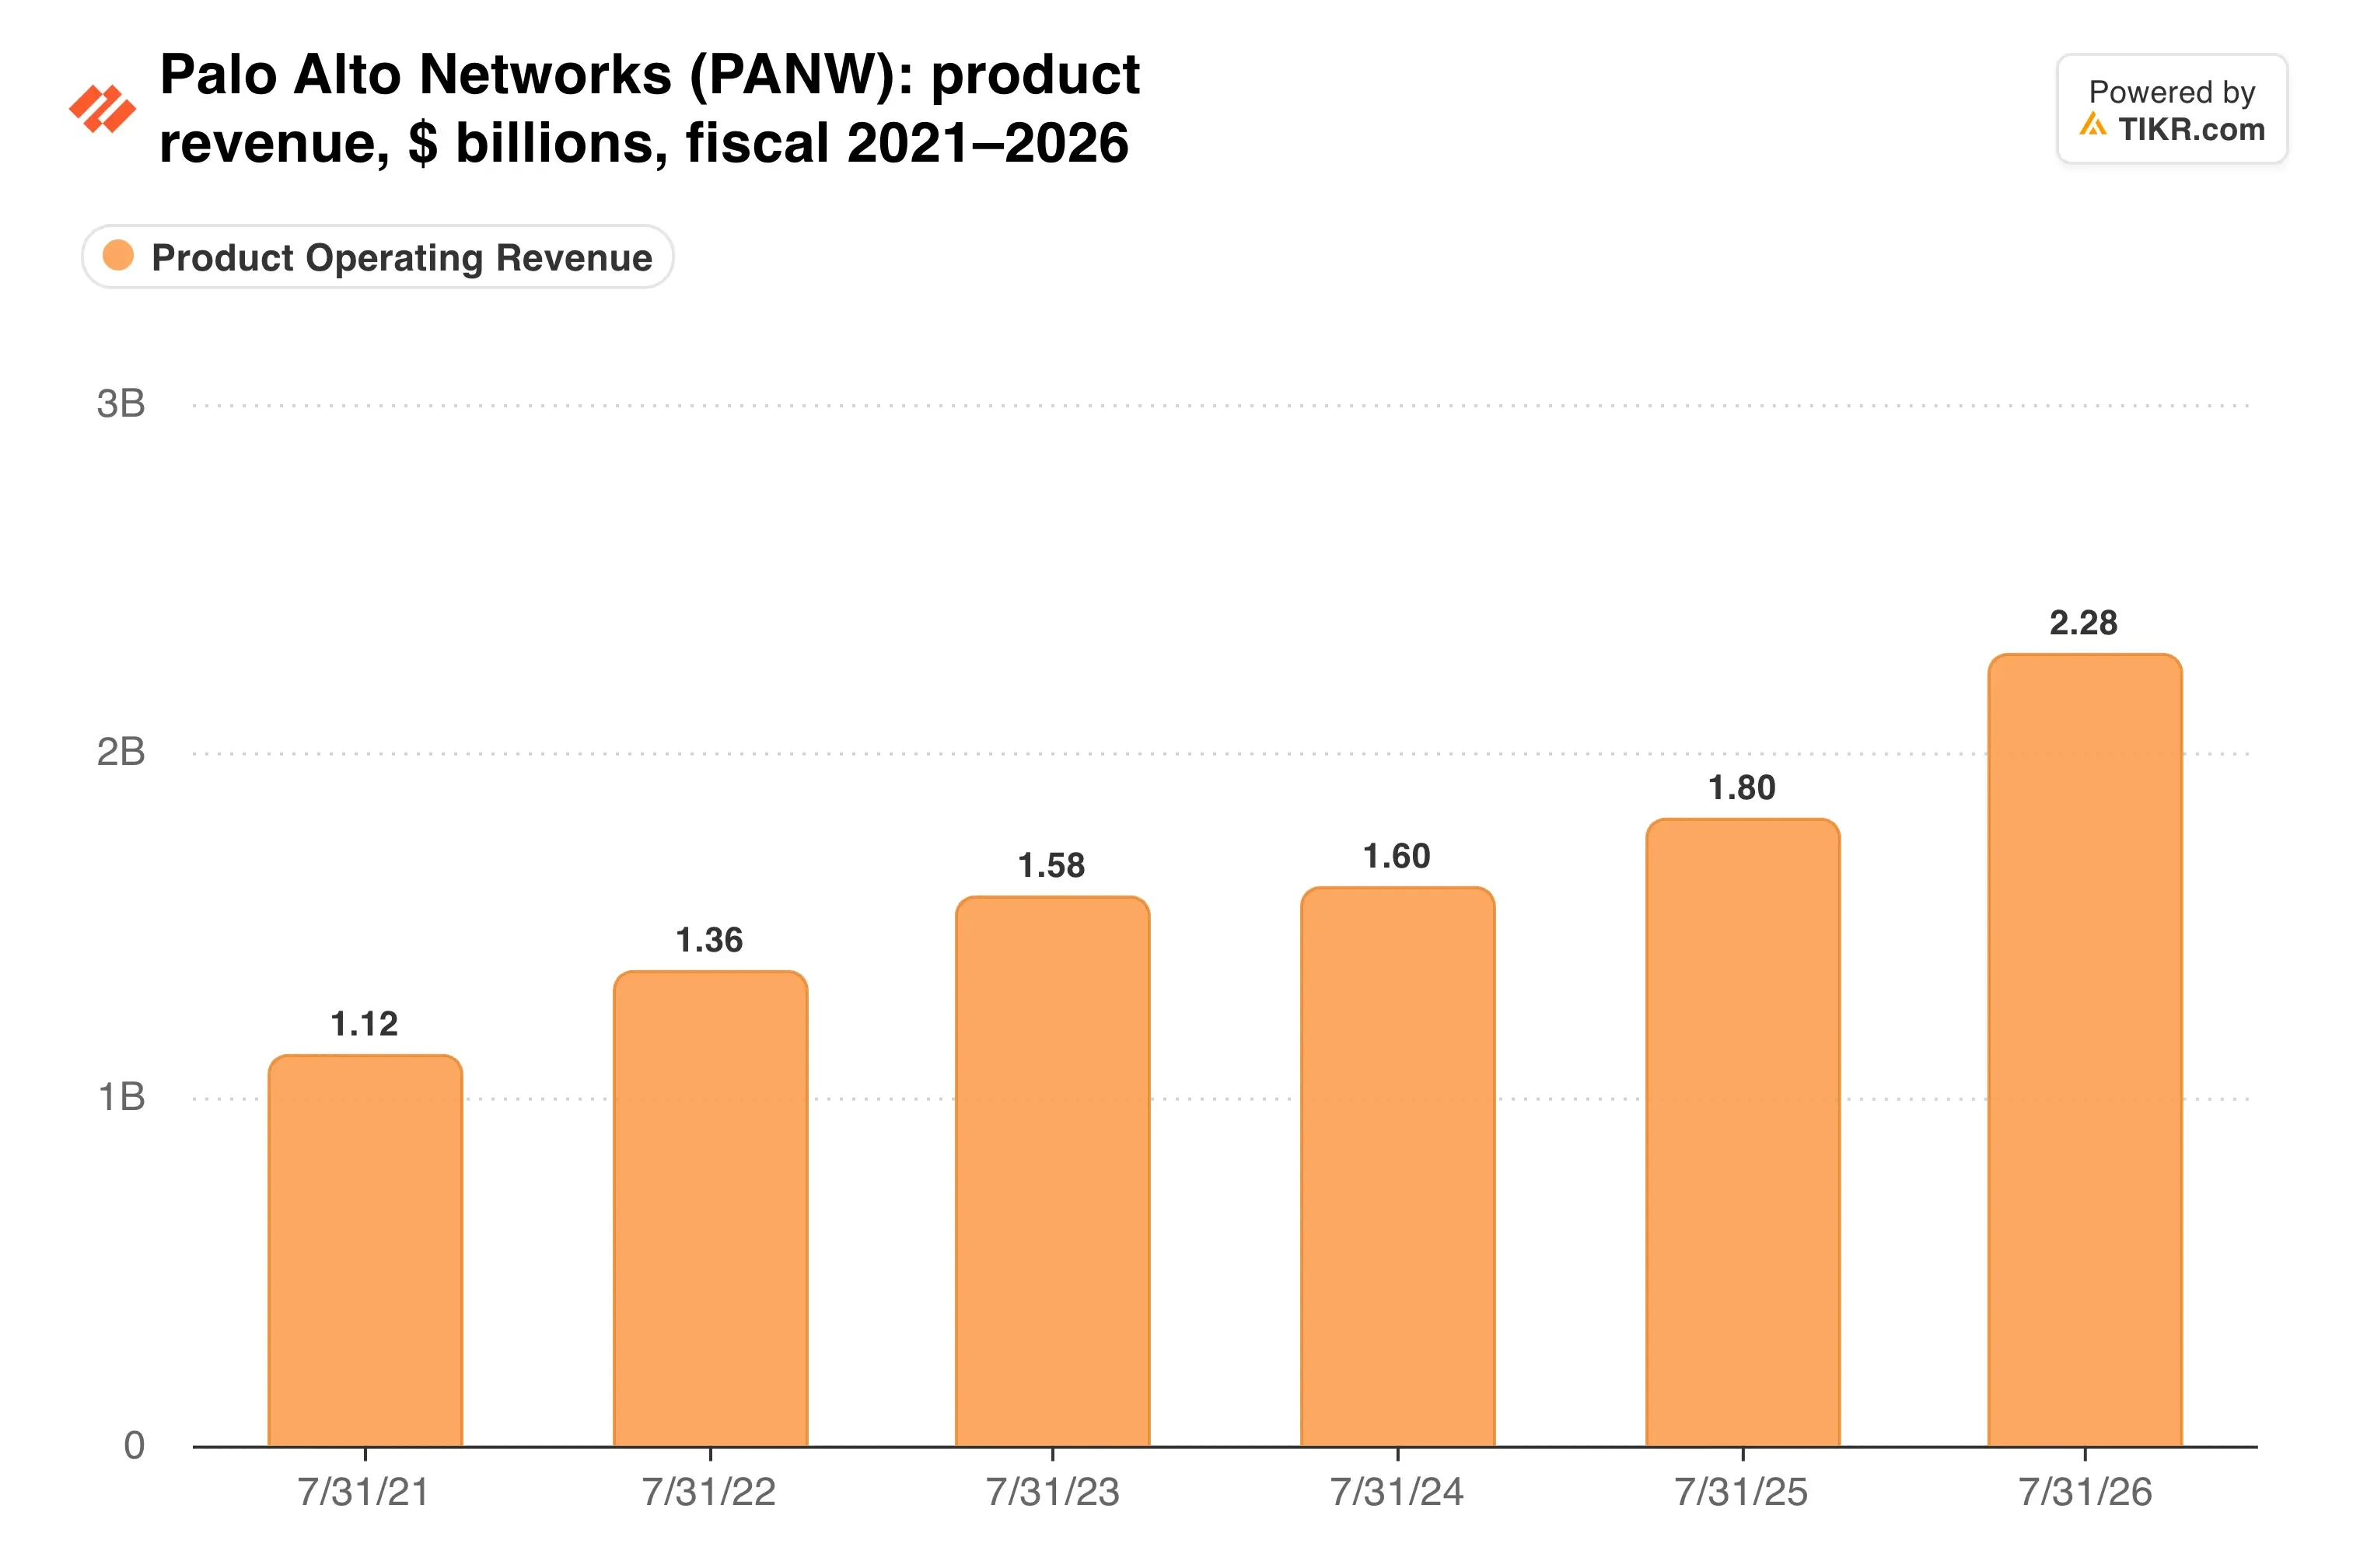
It reached $2.28 billion in fiscal 2026, up 26.5%. A sharp drop from that pace on November 18 would invite the same reaction Fortinet got.
Strong cash, busy checkbook
CEO Nikesh Arora said in the fourth-quarter release that AI advances “will serve as durable tailwinds” for the business. So far, the cash flow backs him up.
Palo Alto generated $4.41 billion of adjusted free cash flow in fiscal 2026, up 25.9%, for a 38.4% margin. Is that margin still rising?
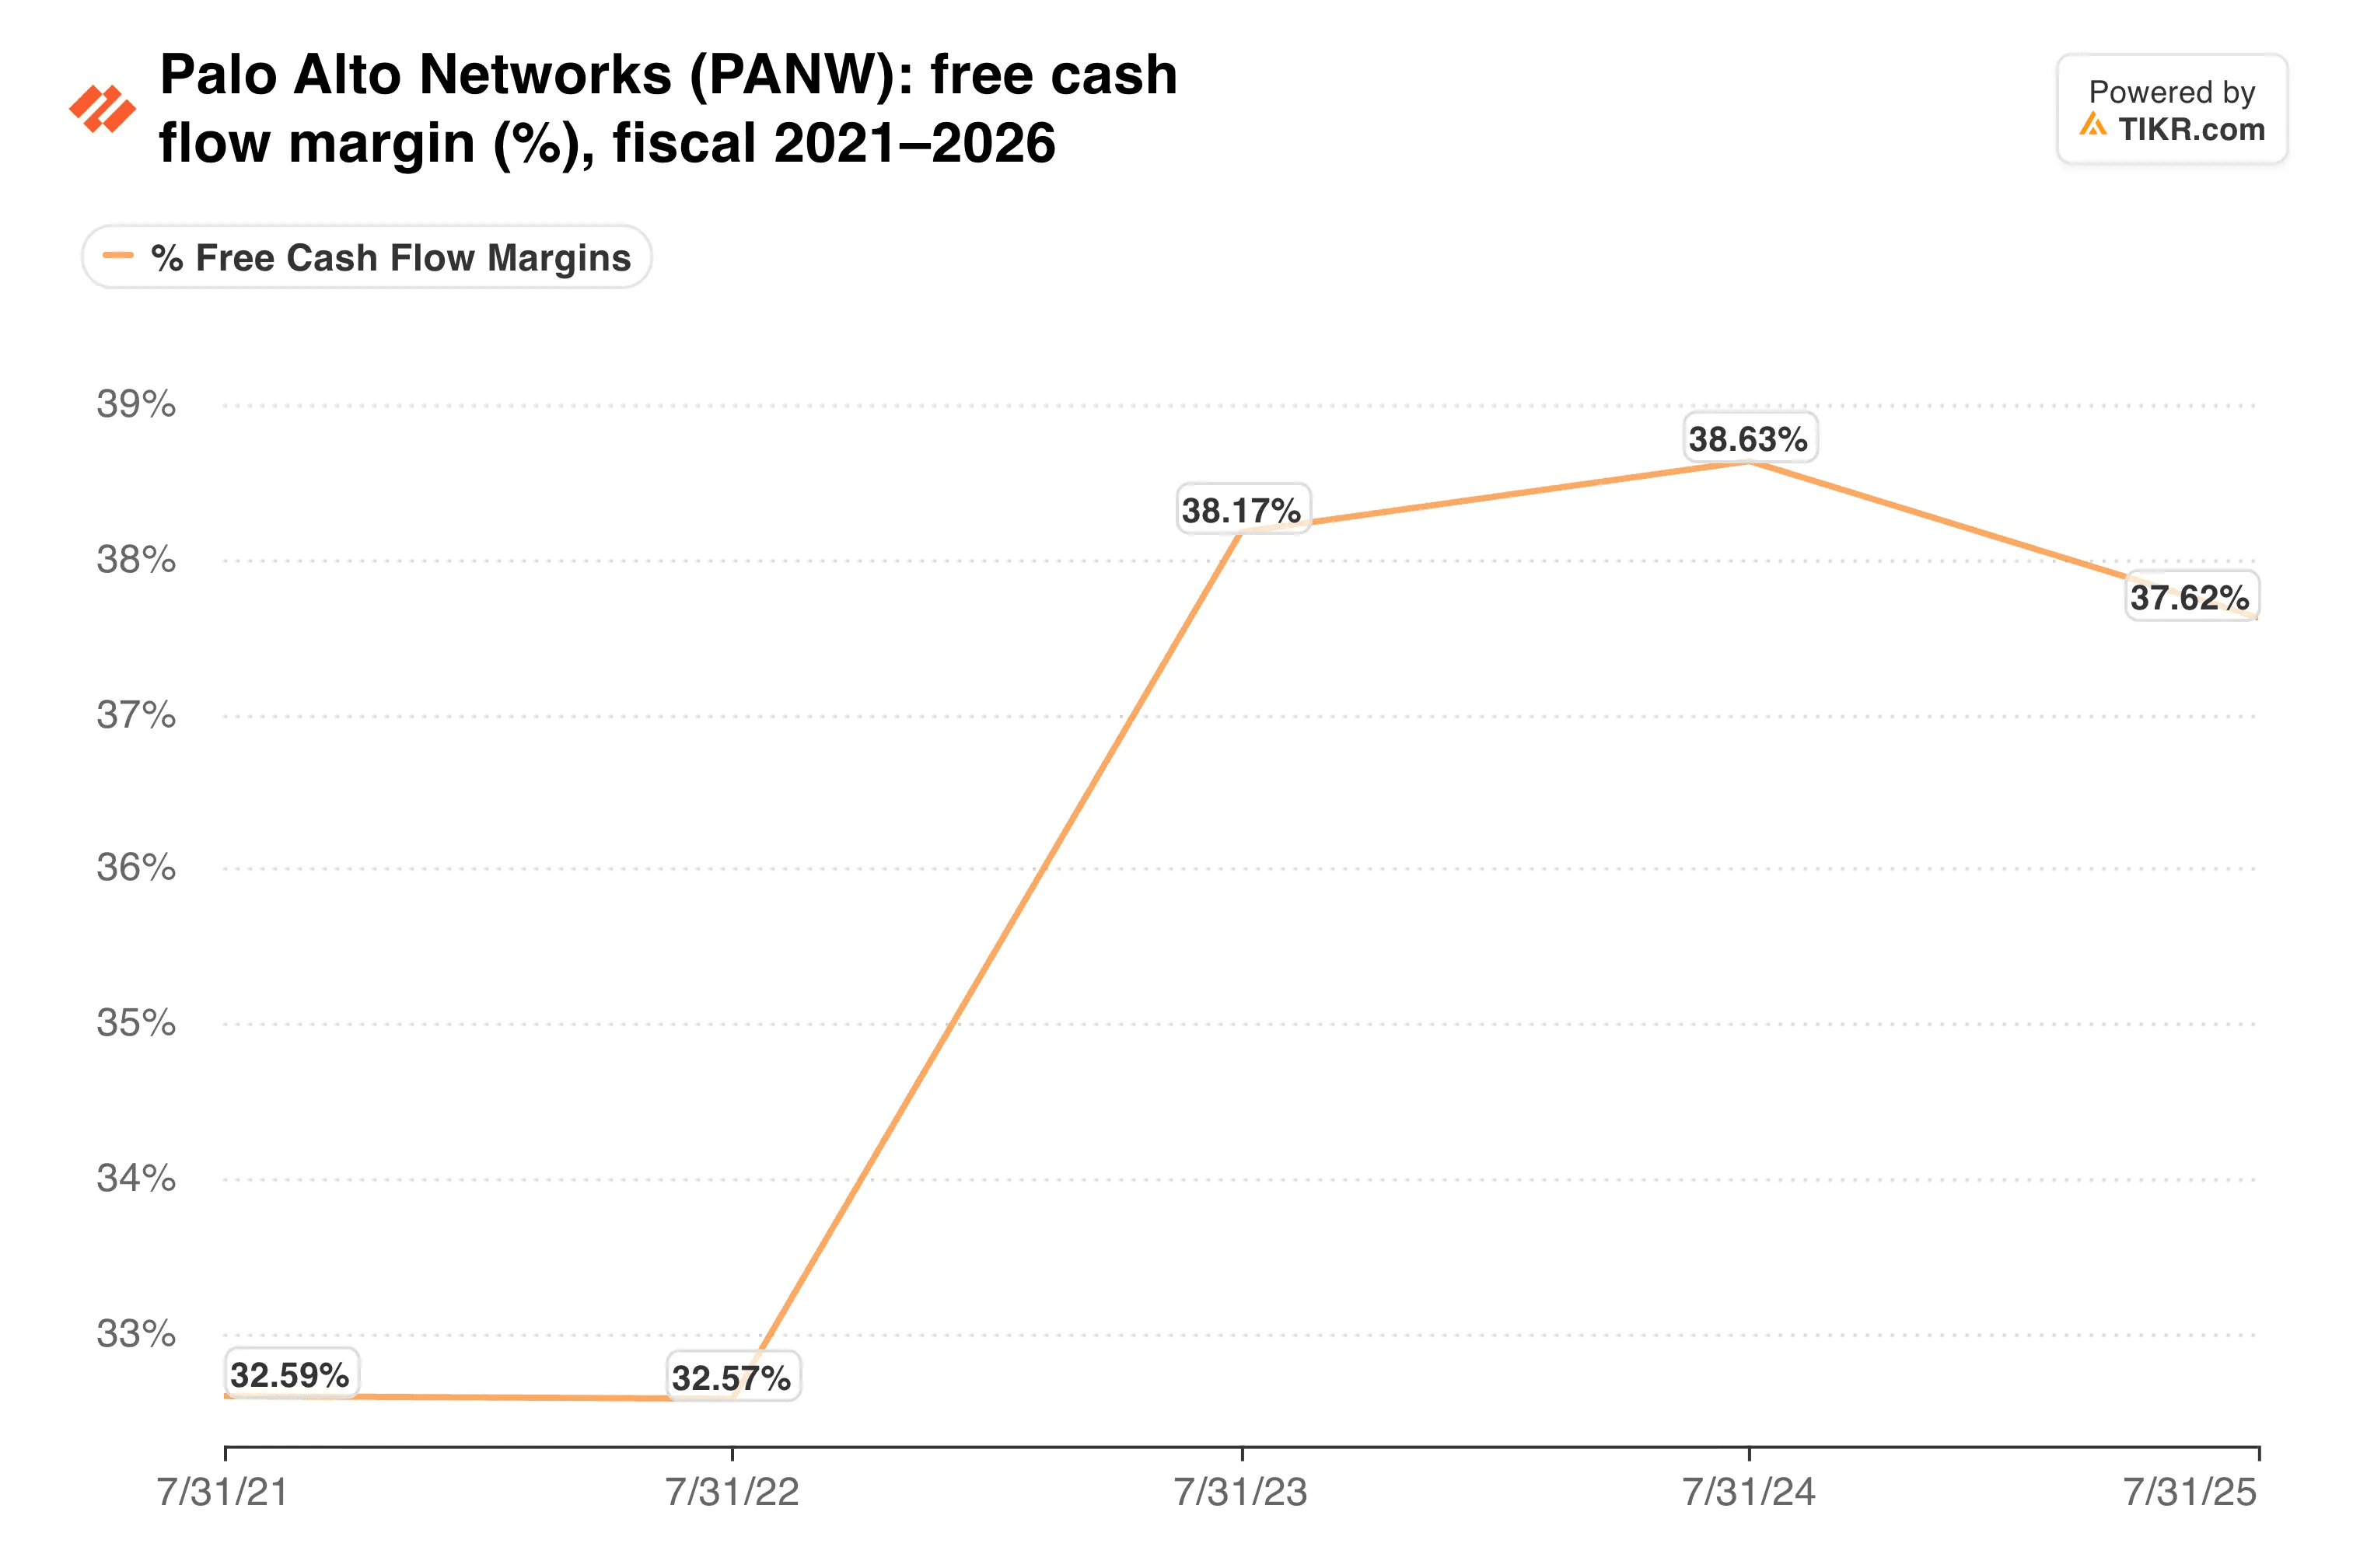
Not this year. Guidance calls for a 38% margin in fiscal 2027, while management still targets 40% for fiscal 2028.
Meanwhile, the shopping continues. The Information reported that Palo Alto is negotiating to buy Clutch Security, which secures the credentials AI agents use, for about $500 million. Palo Alto told the outlet it doesn’t comment on rumors.
Clutch would follow CyberArk, Chronosphere and Koi, plus Console in September. As a result, goodwill reached $22.0 billion at the end of July, up from $4.57 billion a year earlier.
TIKR tracks 56 analysts on Palo Alto Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palo Alto Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palo Alto Networks’ Analyst Ratings
Growth that per-share profit trails
First-quarter guidance calls for revenue of $3.30 billion to $3.31 billion, up 33% to 34%. Next-Generation Security ARR should land between $9.54 billion and $9.56 billion.
Per-share profit tells a slower story. Fiscal 2027 revenue is guided up 23% to 24%, yet non-GAAP EPS of $4.16 to $4.19 implies only about 8% to 9% growth from $3.84. CyberArk was paid for largely in stock, and non-GAAP diluted shares hit 832 million in the fourth quarter, up 17.7% from a year earlier.
And the valuation still assumes plenty of growth ahead.
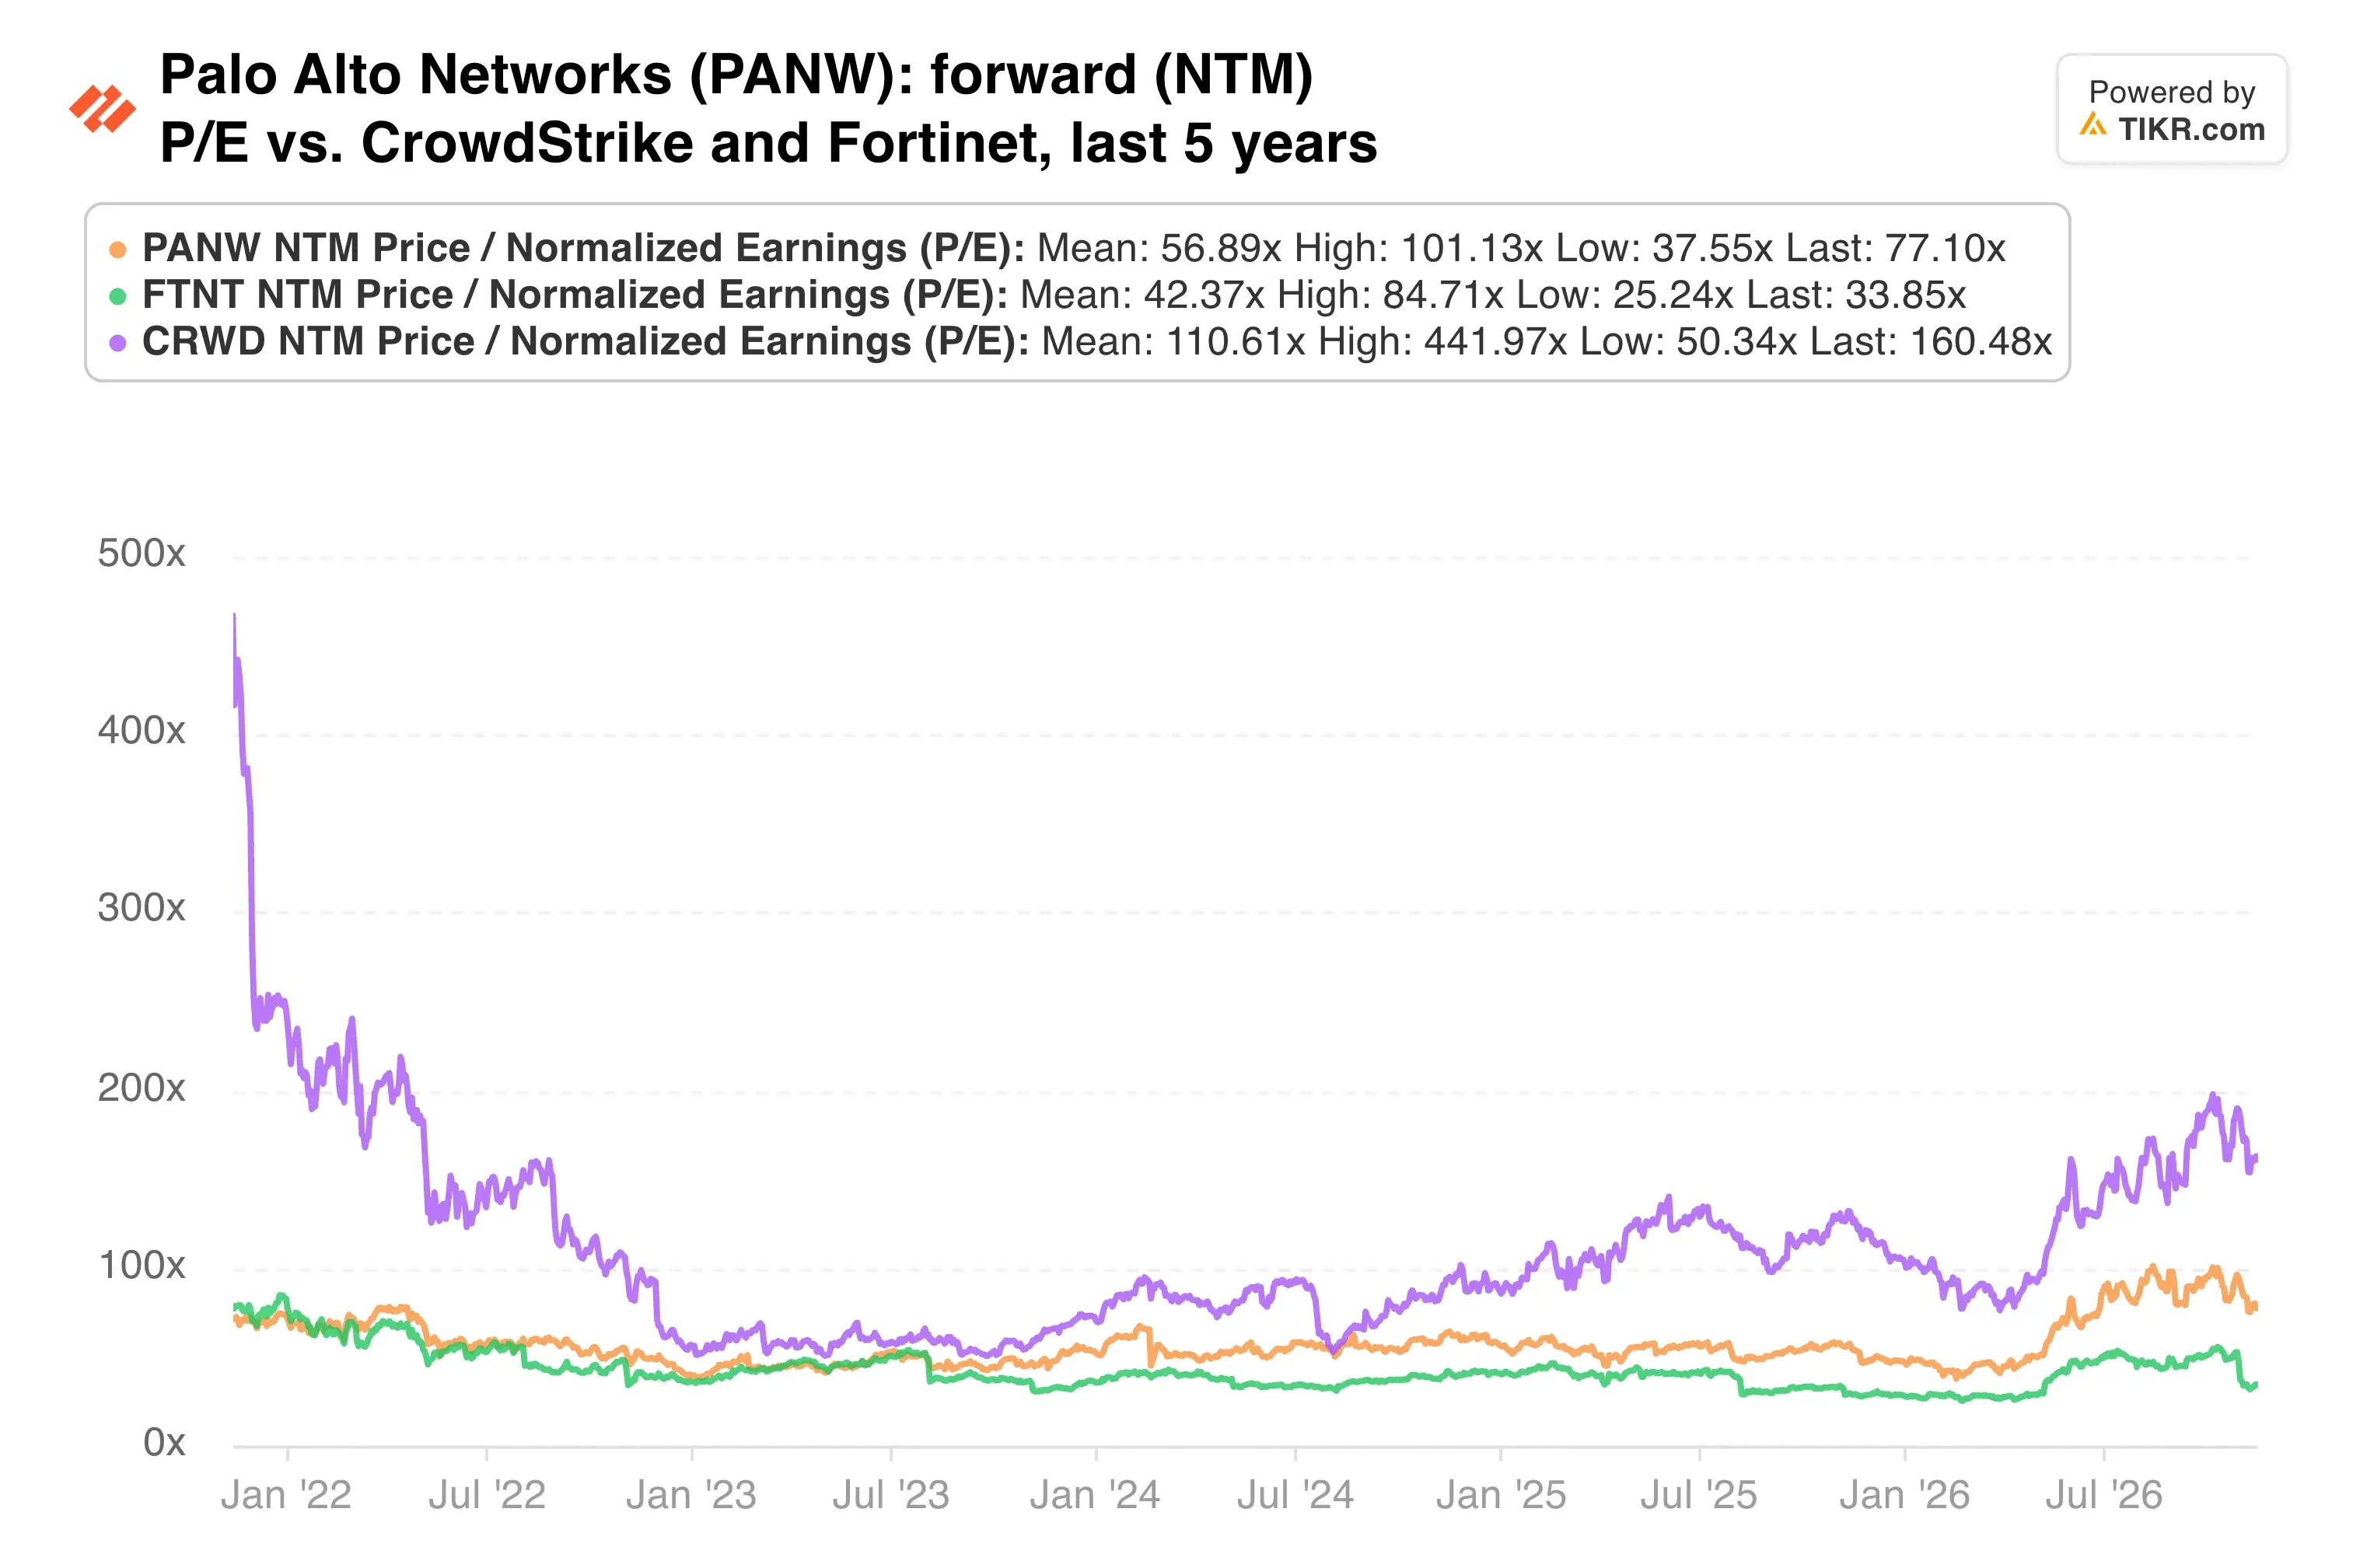
Even after the selloff, the forward multiple sits well above its five-year average.
My take: Palo Alto’s cash generation is real, and agent security looks like a genuine new budget line. Still, the stock needs organic strength to justify its premium. I’d wait for the report before buying, because product growth near the high 20s would ease the Fortinet worry while a weak number would likely extend the slide.
The report arrives after the close on November 18. Watch product revenue against Fortinet’s 37% and whether management holds its $14.10 billion to $14.20 billion fiscal 2027 revenue guide.
So what is Palo Alto stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palo Alto could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!