Key Takeaways
- A $1.2 million portfolio split evenly across General Mills, Plains All American Pipeline and Kraft Heinz pays about $81,300 a year in dividends at today’s prices, or about $6,770 a month.
- Plains covered its distribution 1.7x with distributable cash flow in 2025 and targets raises of $0.15 a unit a year.
- Kraft Heinz’s dividend took 50% of free cash flow over the last twelve months, but it has held at $1.60 a share since 2020.
- General Mills’ dividend is the most stretched, at 85% of free cash flow, and if it were halved, the portfolio’s income would fall to about $67,000 a year.
If you’re retired and living off your portfolio, a 7% yield is hard to ignore. And right now, General Mills (GIS), Plains All American Pipeline (PAA) and Kraft Heinz (KHC) all yield 6.6% or more.
So let’s take a hypothetical retiree with $1.2 million split evenly, $400,000 in each. Together, those stakes pay about $81,300 a year, or about $6,770 a month in dividend checks. That’s a 6.8% yield on this part of the portfolio. (Of course, no one should ever own just three stocks.)
But some of those checks are much better covered than others:
| Stock | Shares | Cost | Income a year | Share of income | Coverage (forward) |
|---|---|---|---|---|---|
| General Mills (GIS) | 11,655 | $400,000 | $28,438 | 34% | Cash dividend payout ratio: 85% (76%) |
| Plains All American Pipeline (PAA) | 16,366 units | $399,985 | $27,331 | 34% | Distributable cash flow coverage: 1.7x (1.7x) |
| Kraft Heinz (KHC) | 15,929 | $399,977 | $25,486 | 32% | Cash dividend payout ratio: 50% (64%) |
| Total | $81,256 |
Source: TIKR and StockAnalysis, at today’s prices, with dividends at each company’s current rate. Coverage is for the last twelve months reported (Plains: 2025), with analysts’ estimate for the current fiscal year in parentheses.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
General Mills is holding its dividend while it pays down debt
General Mills’ organic net sales were flat in the first quarter of fiscal 2027, which ended Aug. 30, 2026, against the same quarter a year before. For the full year, the company guides adjusted operating profit down 8% to 13% in constant currency.
The cash has already thinned. Free cash flow fell to $1.63 billion in fiscal 2026, the year ended May 2026, from $2.29 billion in fiscal 2025, against $1.32 billion of dividends paid:
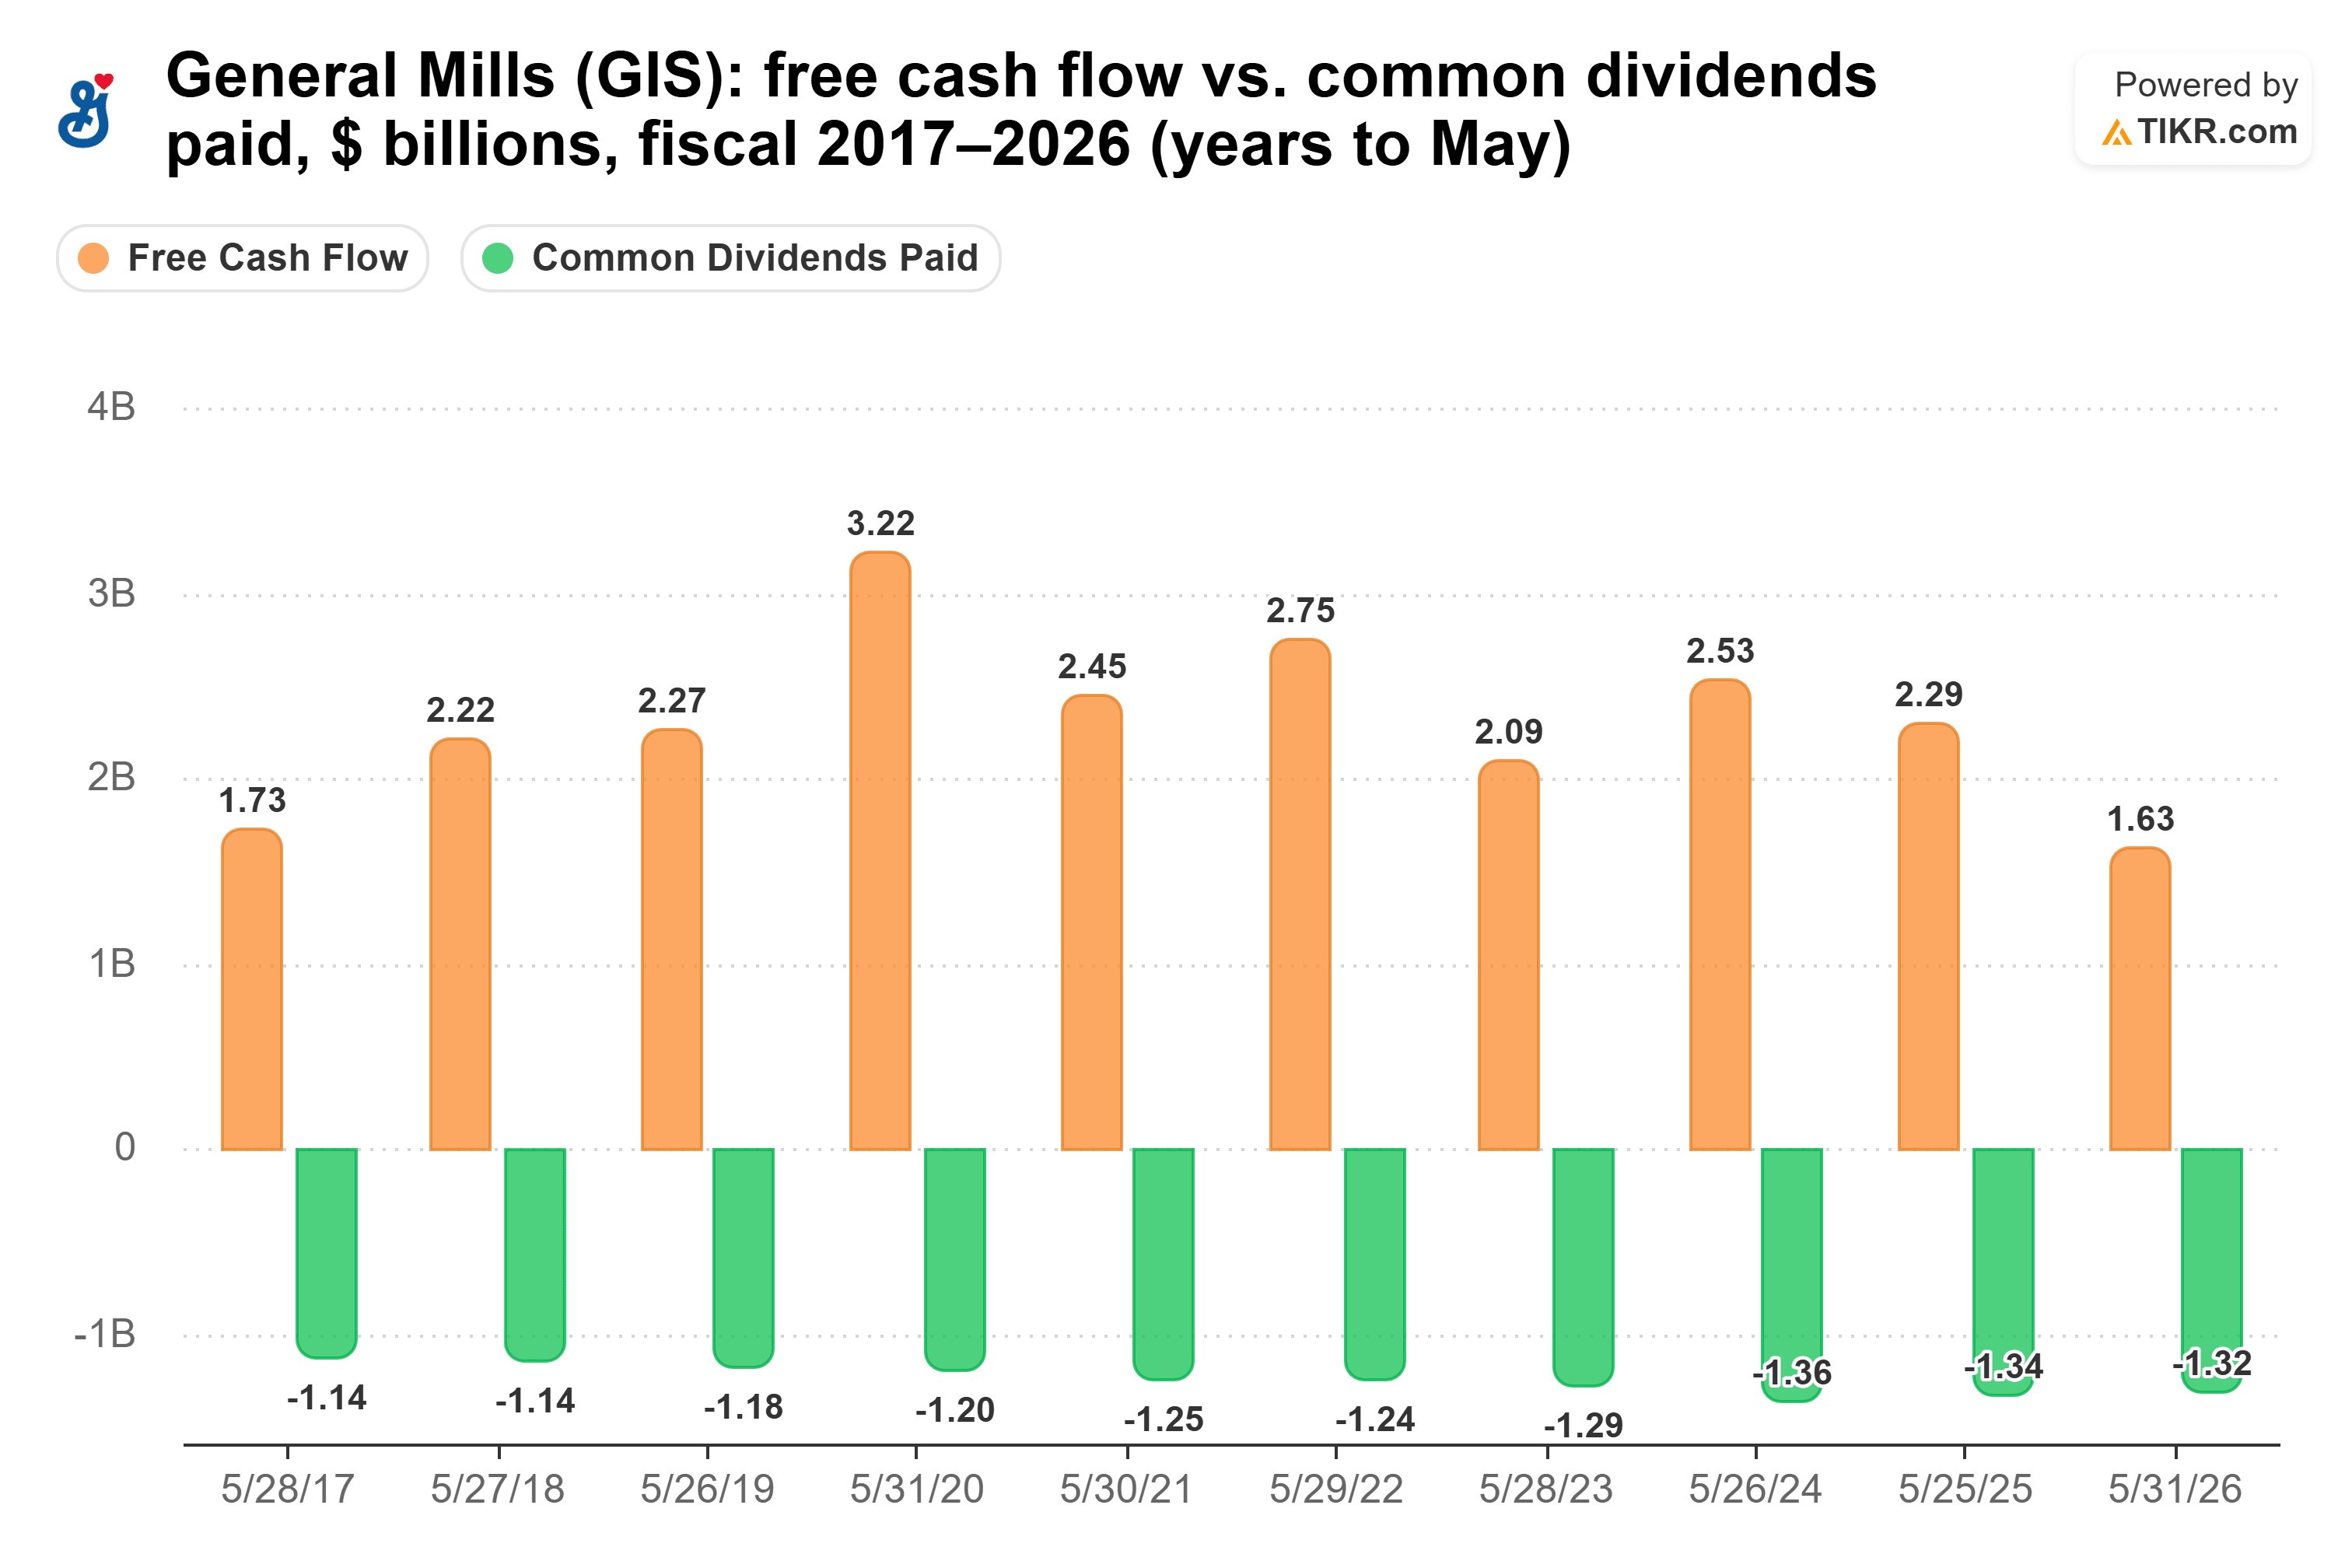
That left the dividend eating up a stretched 85% of free cash flow over the twelve months to Aug. 30, 2026. Analysts expect that to ease to 76% in fiscal 2027.
So raises are on hold. CFO Kofi Bruce said in September that the company expects “to maintain the current rate per share while we prioritize deleverage,” and the board kept the quarterly dividend at $0.61 a share on Sept. 29. With net debt at 3.7x EBITDA, Bruce expects it to take “at least a couple of years” to get back to 3x. Chief operating officer Dana McNabb becomes CEO on Jan. 1, 2027.
Plains has room for its yearly raises
General Mills is holding its payout, but Plains is still raising. Its third-quarter 2026 distribution of $0.4175 a unit was up 10% from $0.38 a year before, and it targets raises of $0.15 a unit a year. (It’s a partnership, so it pays distributions on units, with a K-1 at tax time.)
Plains sold its Canadian NGL business to Keyera in May 2026, which leaves it focused on crude oil. Third-quarter adjusted EBITDA rose 6% to $711 million from $669 million a year before.
Distributable cash flow covered the distribution a healthy 1.7x in 2025, and analysts expect the same 1.7x in 2026. But the cushion has narrowed every year since 2020, when it was 3.2x, as the payout climbed back:
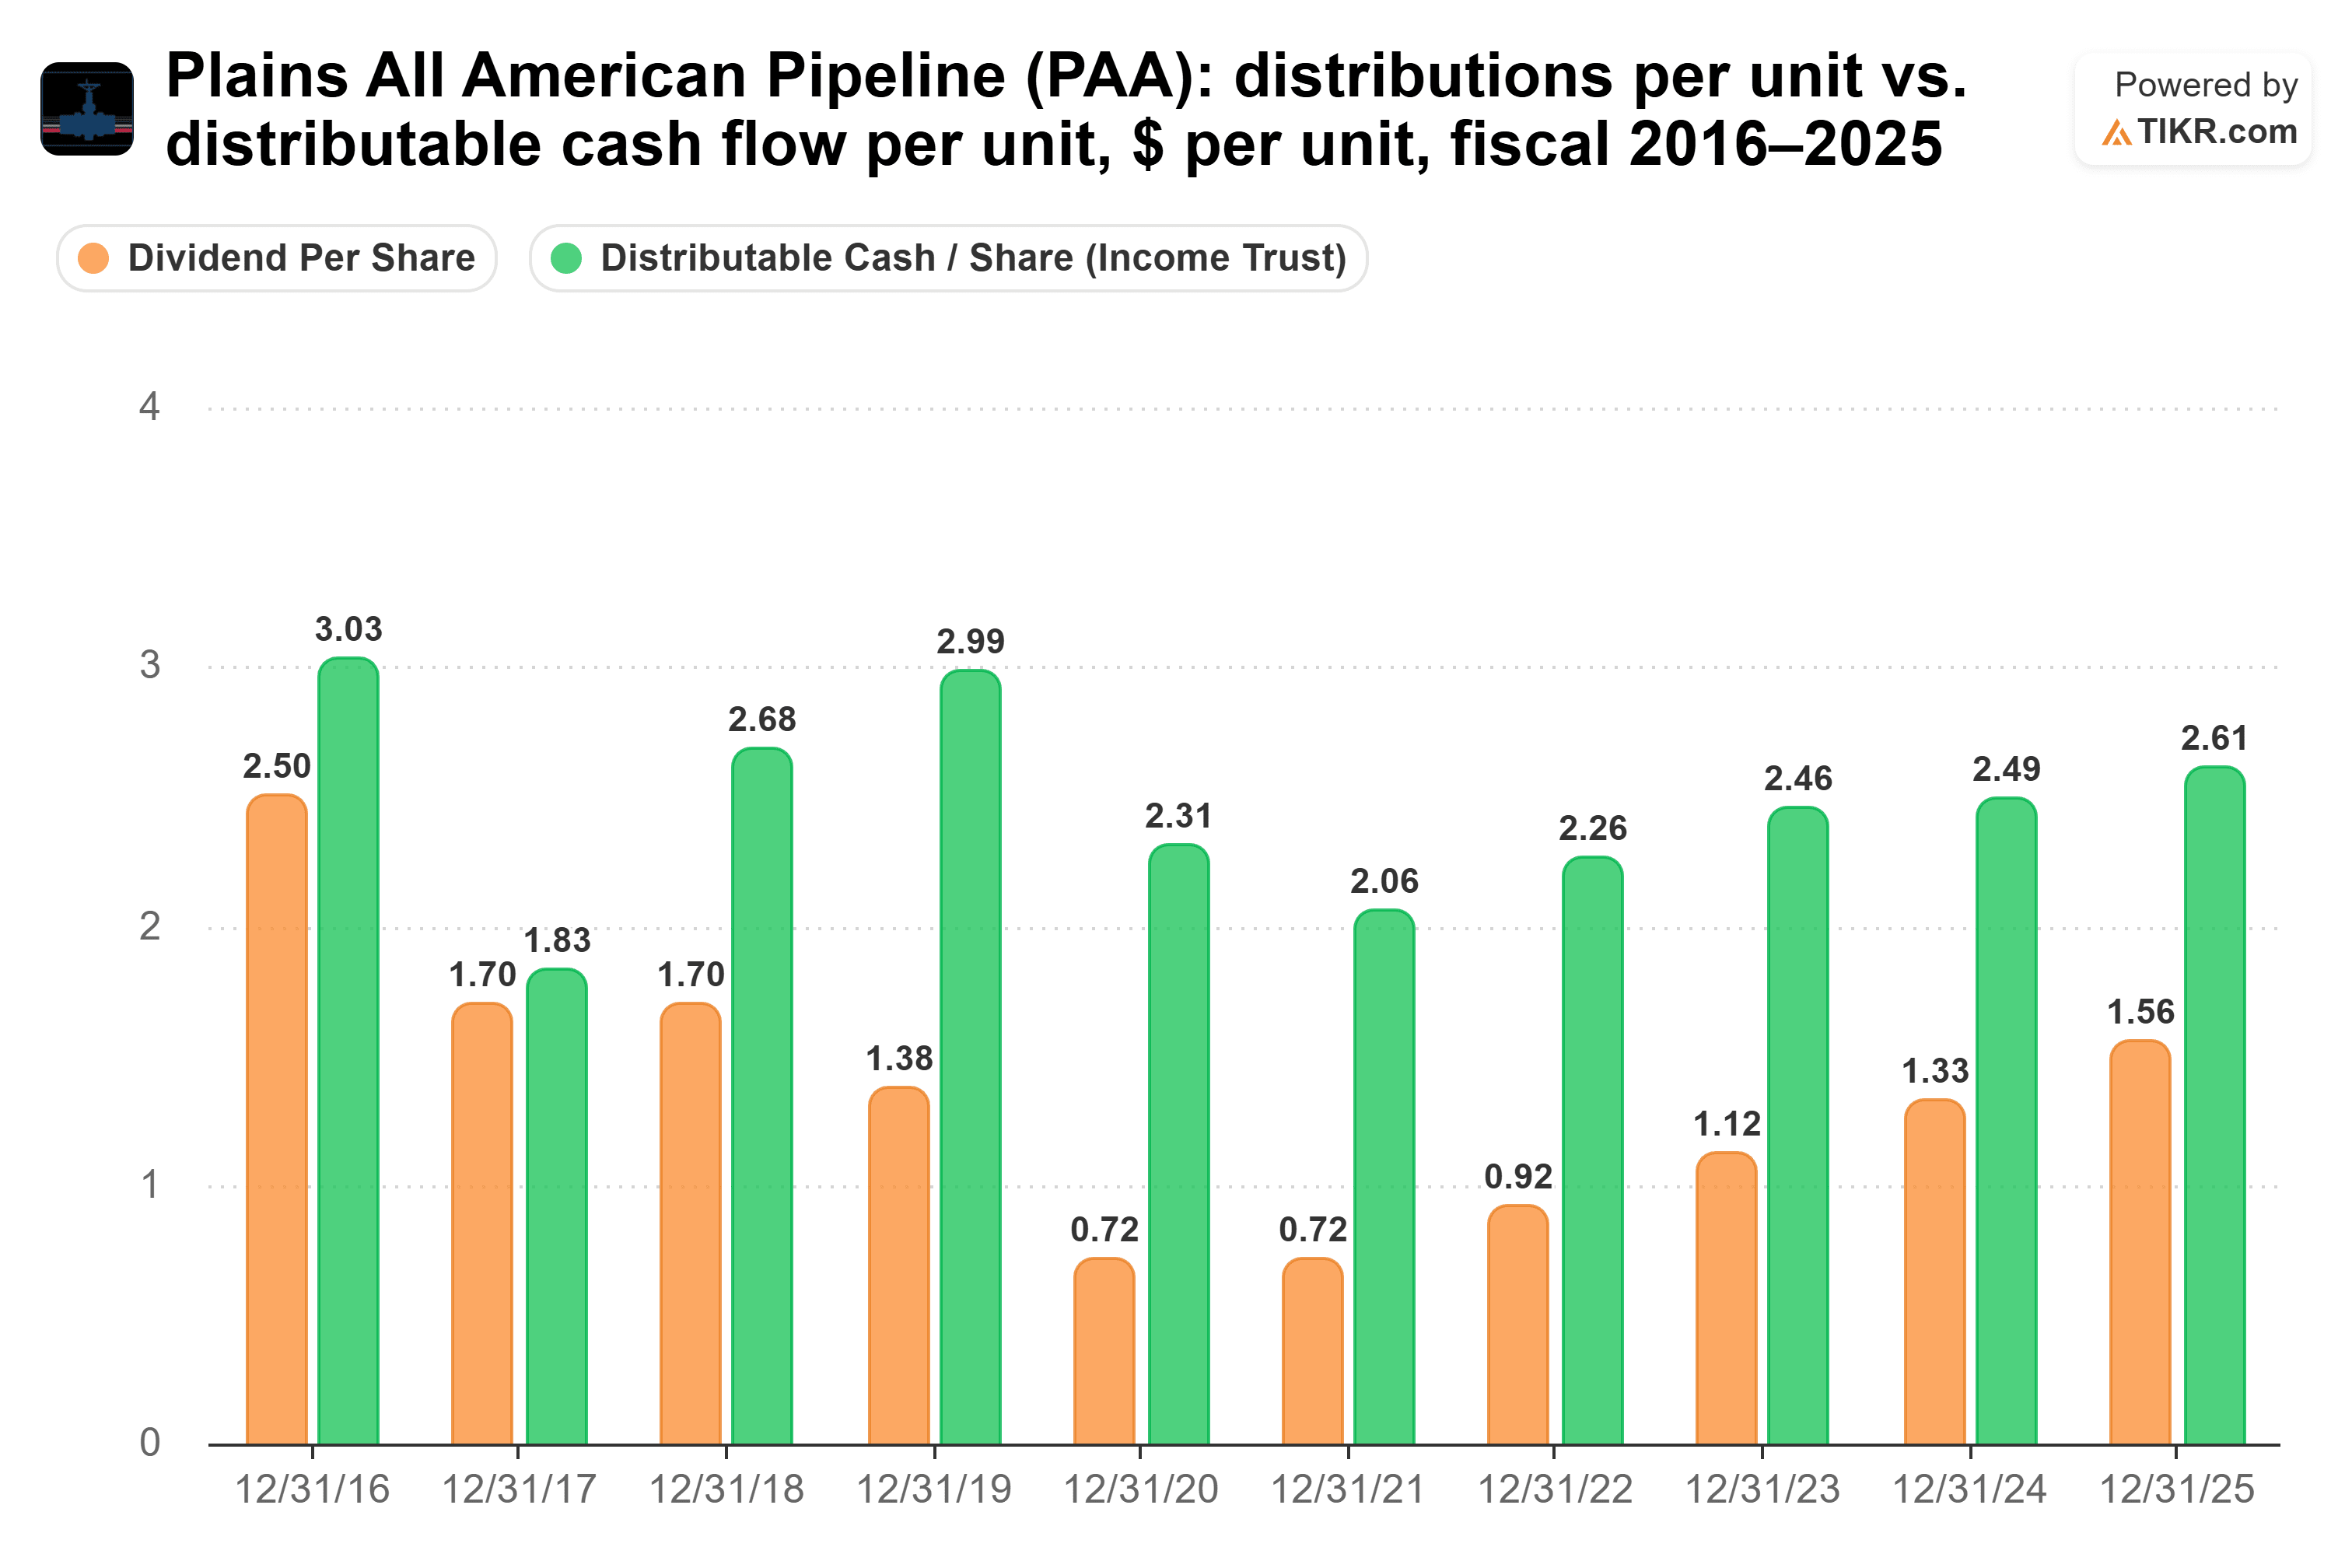
That 2020 cushion came after cuts that took the distribution from $2.50 a unit in 2016 to $0.72. With net debt at 3.7x EBITDA and oil prices volatile, I’d want to see coverage hold near 1.7x.
Kraft Heinz has plenty of room, and no raises
Kraft Heinz isn’t raising either, though it has far more room than General Mills. Its dividend was $1.60 a share every year from 2020 to 2025. Organic net sales fell 1.1% in the third quarter of 2026 against the same quarter a year before. Still, on Nov. 4 it raised its 2026 adjusted EPS guidance to $2.07 to $2.13, from $2.03 to $2.09.
Free cash flow fell short of the dividend in 2022, at $1.55 billion against $1.96 billion paid. It has covered the dividend easily since, with $3.66 billion against $1.90 billion in 2025:
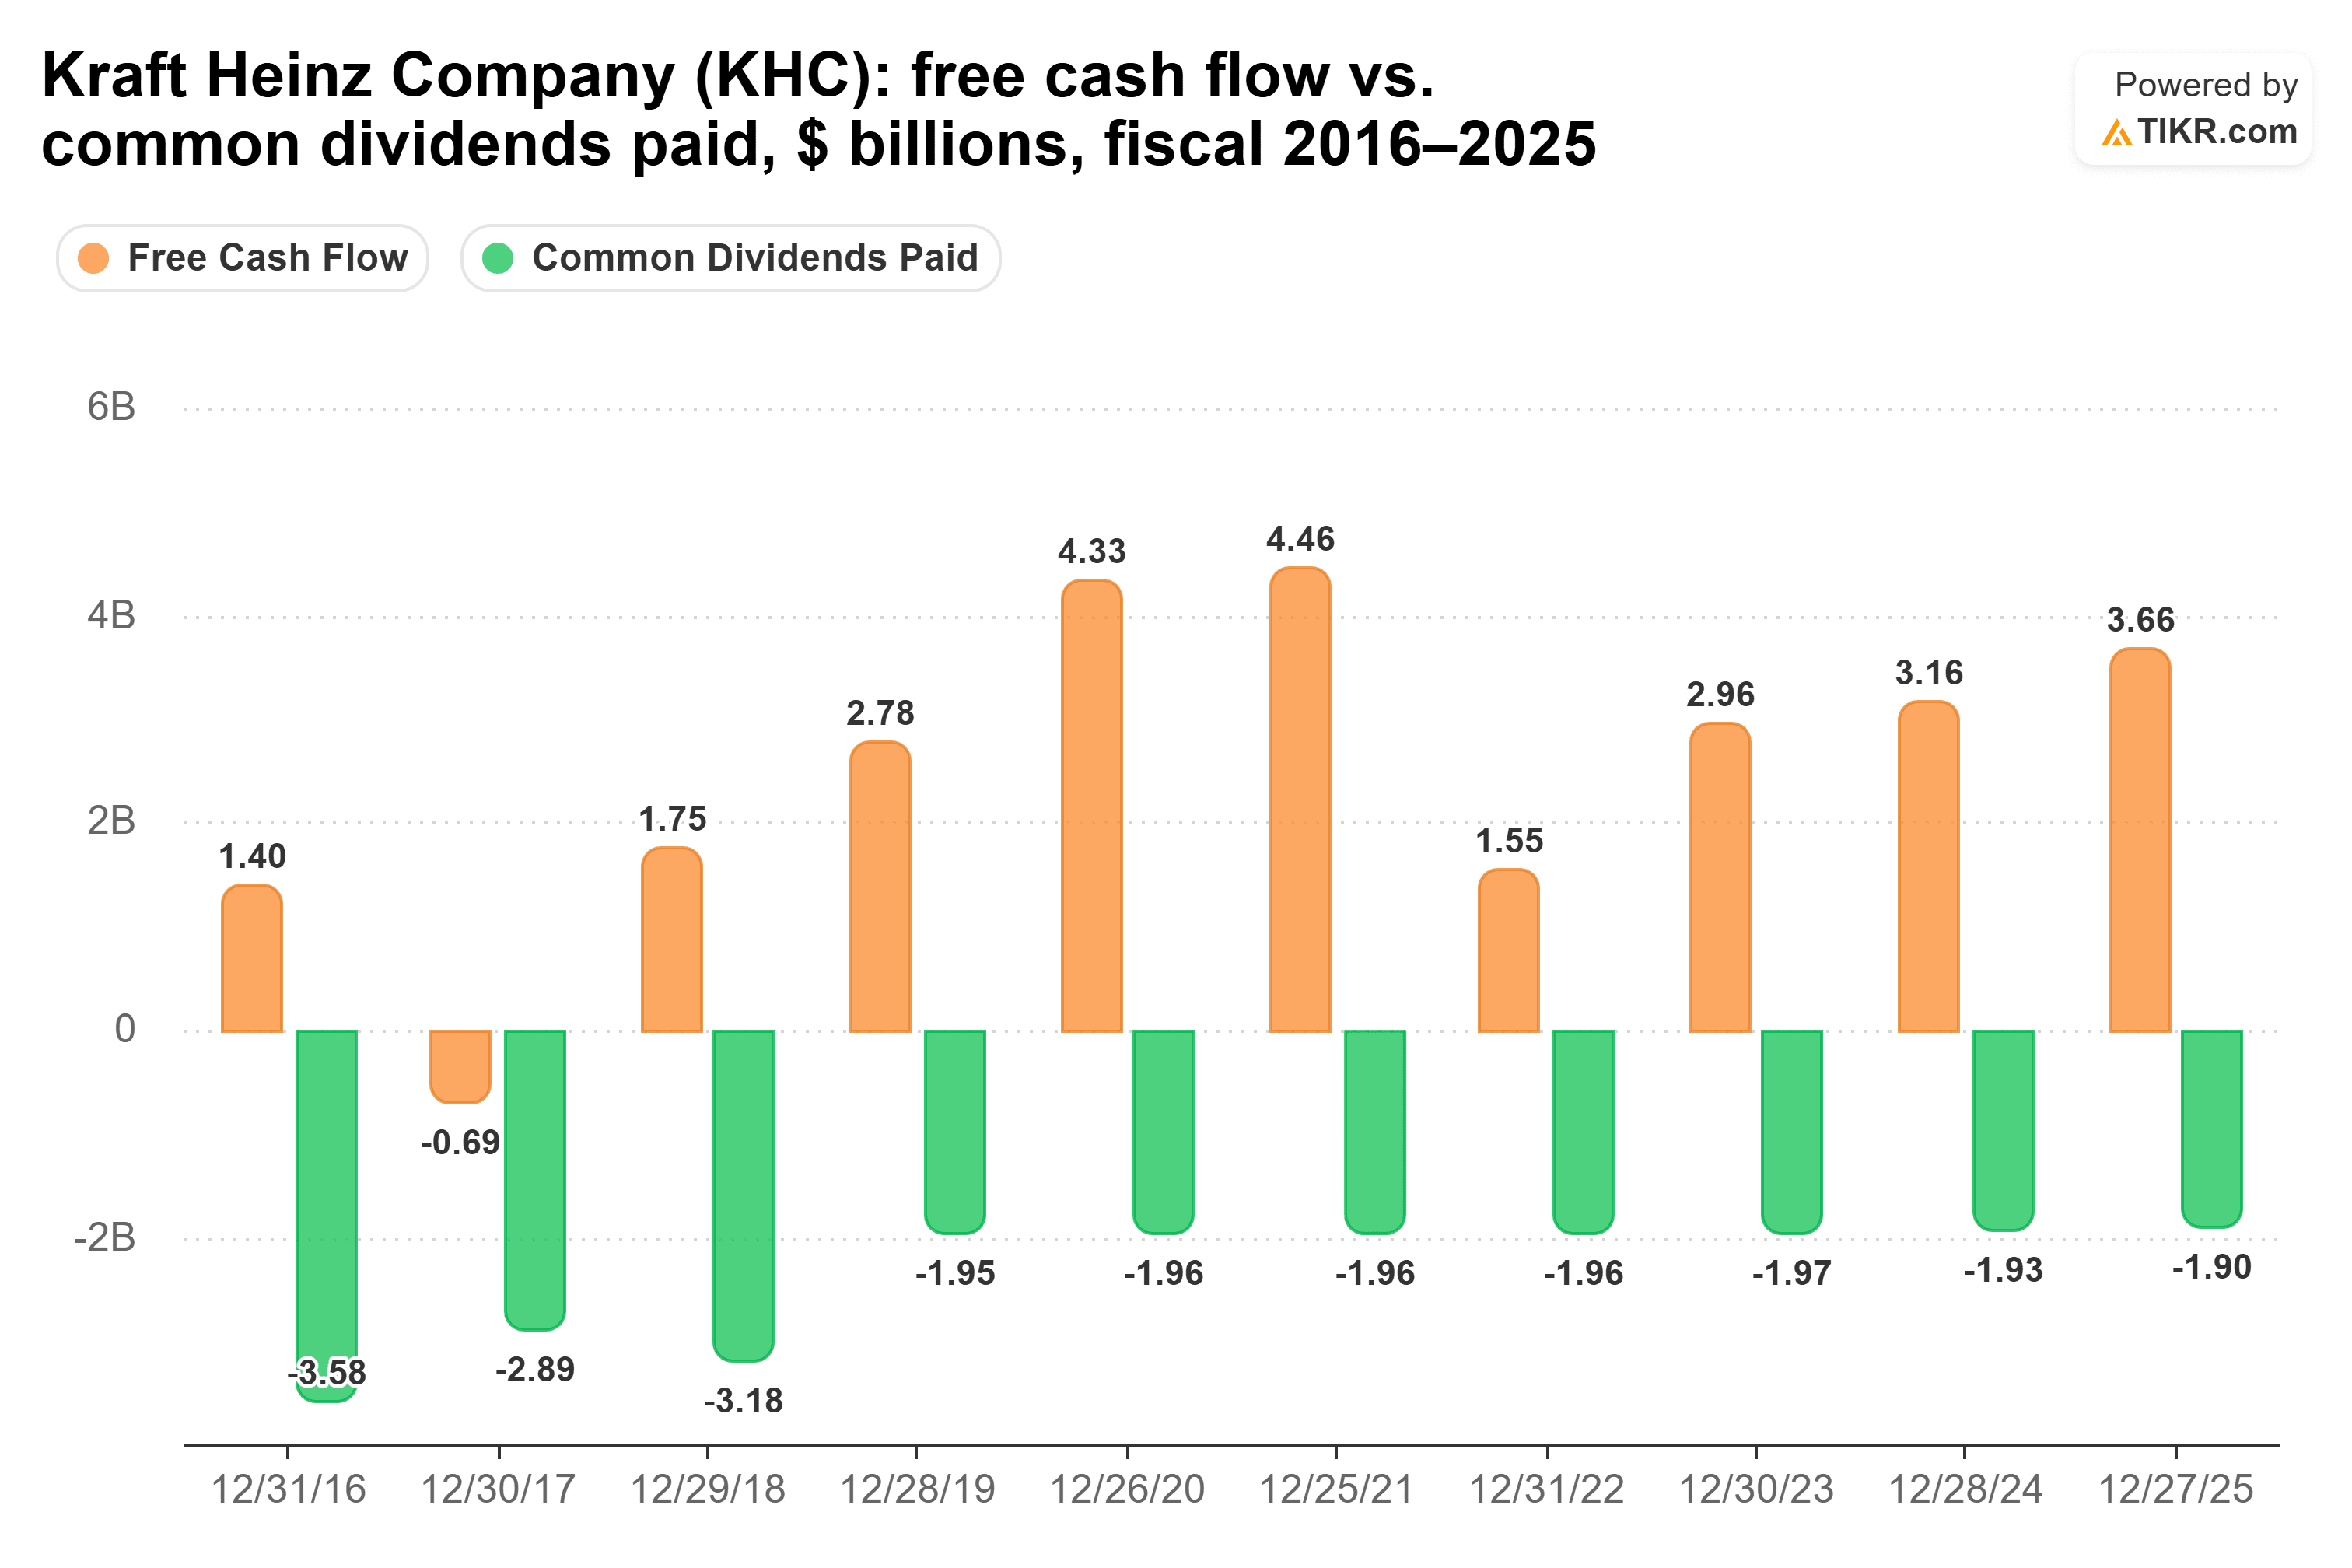
Over the twelve months to June 27, 2026, the dividend took a comfortable 50% of free cash flow. Analysts expect 64% in 2026, as free cash flow falls 19% from 2025. Kraft Heinz guides adjusted operating income down 16% to 18% in constant currency while it spends an extra $700 million behind its brands. Its latest release lists sustaining the dividend among its priorities, alongside investing in the business and paying down debt, so I’d expect the $1.60 to hold.
General Mills’ check has the least room
The way I see it, Plains is safe and growing, as long as distributable cash flow keeps pace with those $0.15 raises. Kraft Heinz is safe but slow. And General Mills, the biggest of the three checks, is the most stretched.
If General Mills halved its dividend, this portfolio’s income would fall to about $67,000 a year. If it stopped paying, the income would fall to about $52,800. Given Bruce’s plan to hold the rate, I’d bet on a long freeze before either, but it’s the check I’d watch most closely.
Of course, McNabb takes over on Jan. 1. If she gets debt down faster than Bruce’s couple of years, that $0.61 could start growing again sooner. And Plains gives its 2027 guidance on its February call, which should show us whether those raises still have room.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!