Key Takeaways
- A $3.2 billion fund, Blue Whale Capital, sold all of its AppLovin, Honeywell International and Honeywell Aerospace stock in the third quarter, its latest 13F shows.
- All three were small positions, while the fund added to Applied Materials and Lumentum, its No. 2 and No. 3 holdings.
- Wall Street has cut its Honeywell Aerospace target by more than a third since June, the strongest case for any of the three sales.
- AppLovin is the sale I’d second-guess, since its earnings estimates are rising and it trades below its five-year average multiple.
Blue Whale Capital walked away from three stocks in the third quarter. Its 13F for the quarter ended Sept. 30, filed Nov. 13, shows no shares left of AppLovin (APP), Honeywell International (HON) or Honeywell Aerospace (HONA).
None of them was a big bet. Blue Whale’s 13F holds $3.21 billion of US stocks in 24 positions, and at the end of June, AppLovin was 2.7% of the fund and each Honeywell 2.3%. The same filing shows 30% more Applied Materials (AMAT) shares and 68% more Lumentum (LITE) shares than in June, its No. 2 and No. 3 holdings at Sept. 30.
AppLovin’s estimates are still climbing
AppLovin is down 21% since Sept. 30, but the business is still growing fast. It beat in the third quarter and guided fourth-quarter revenue to $2.365 billion to $2.395 billion, up 43% to 44% from a year earlier. Analysts now expect $17.35 of 2026 earnings per share, up from $16.59 in late October.
The Street’s average target has come down from about $715 a year ago to about $450:
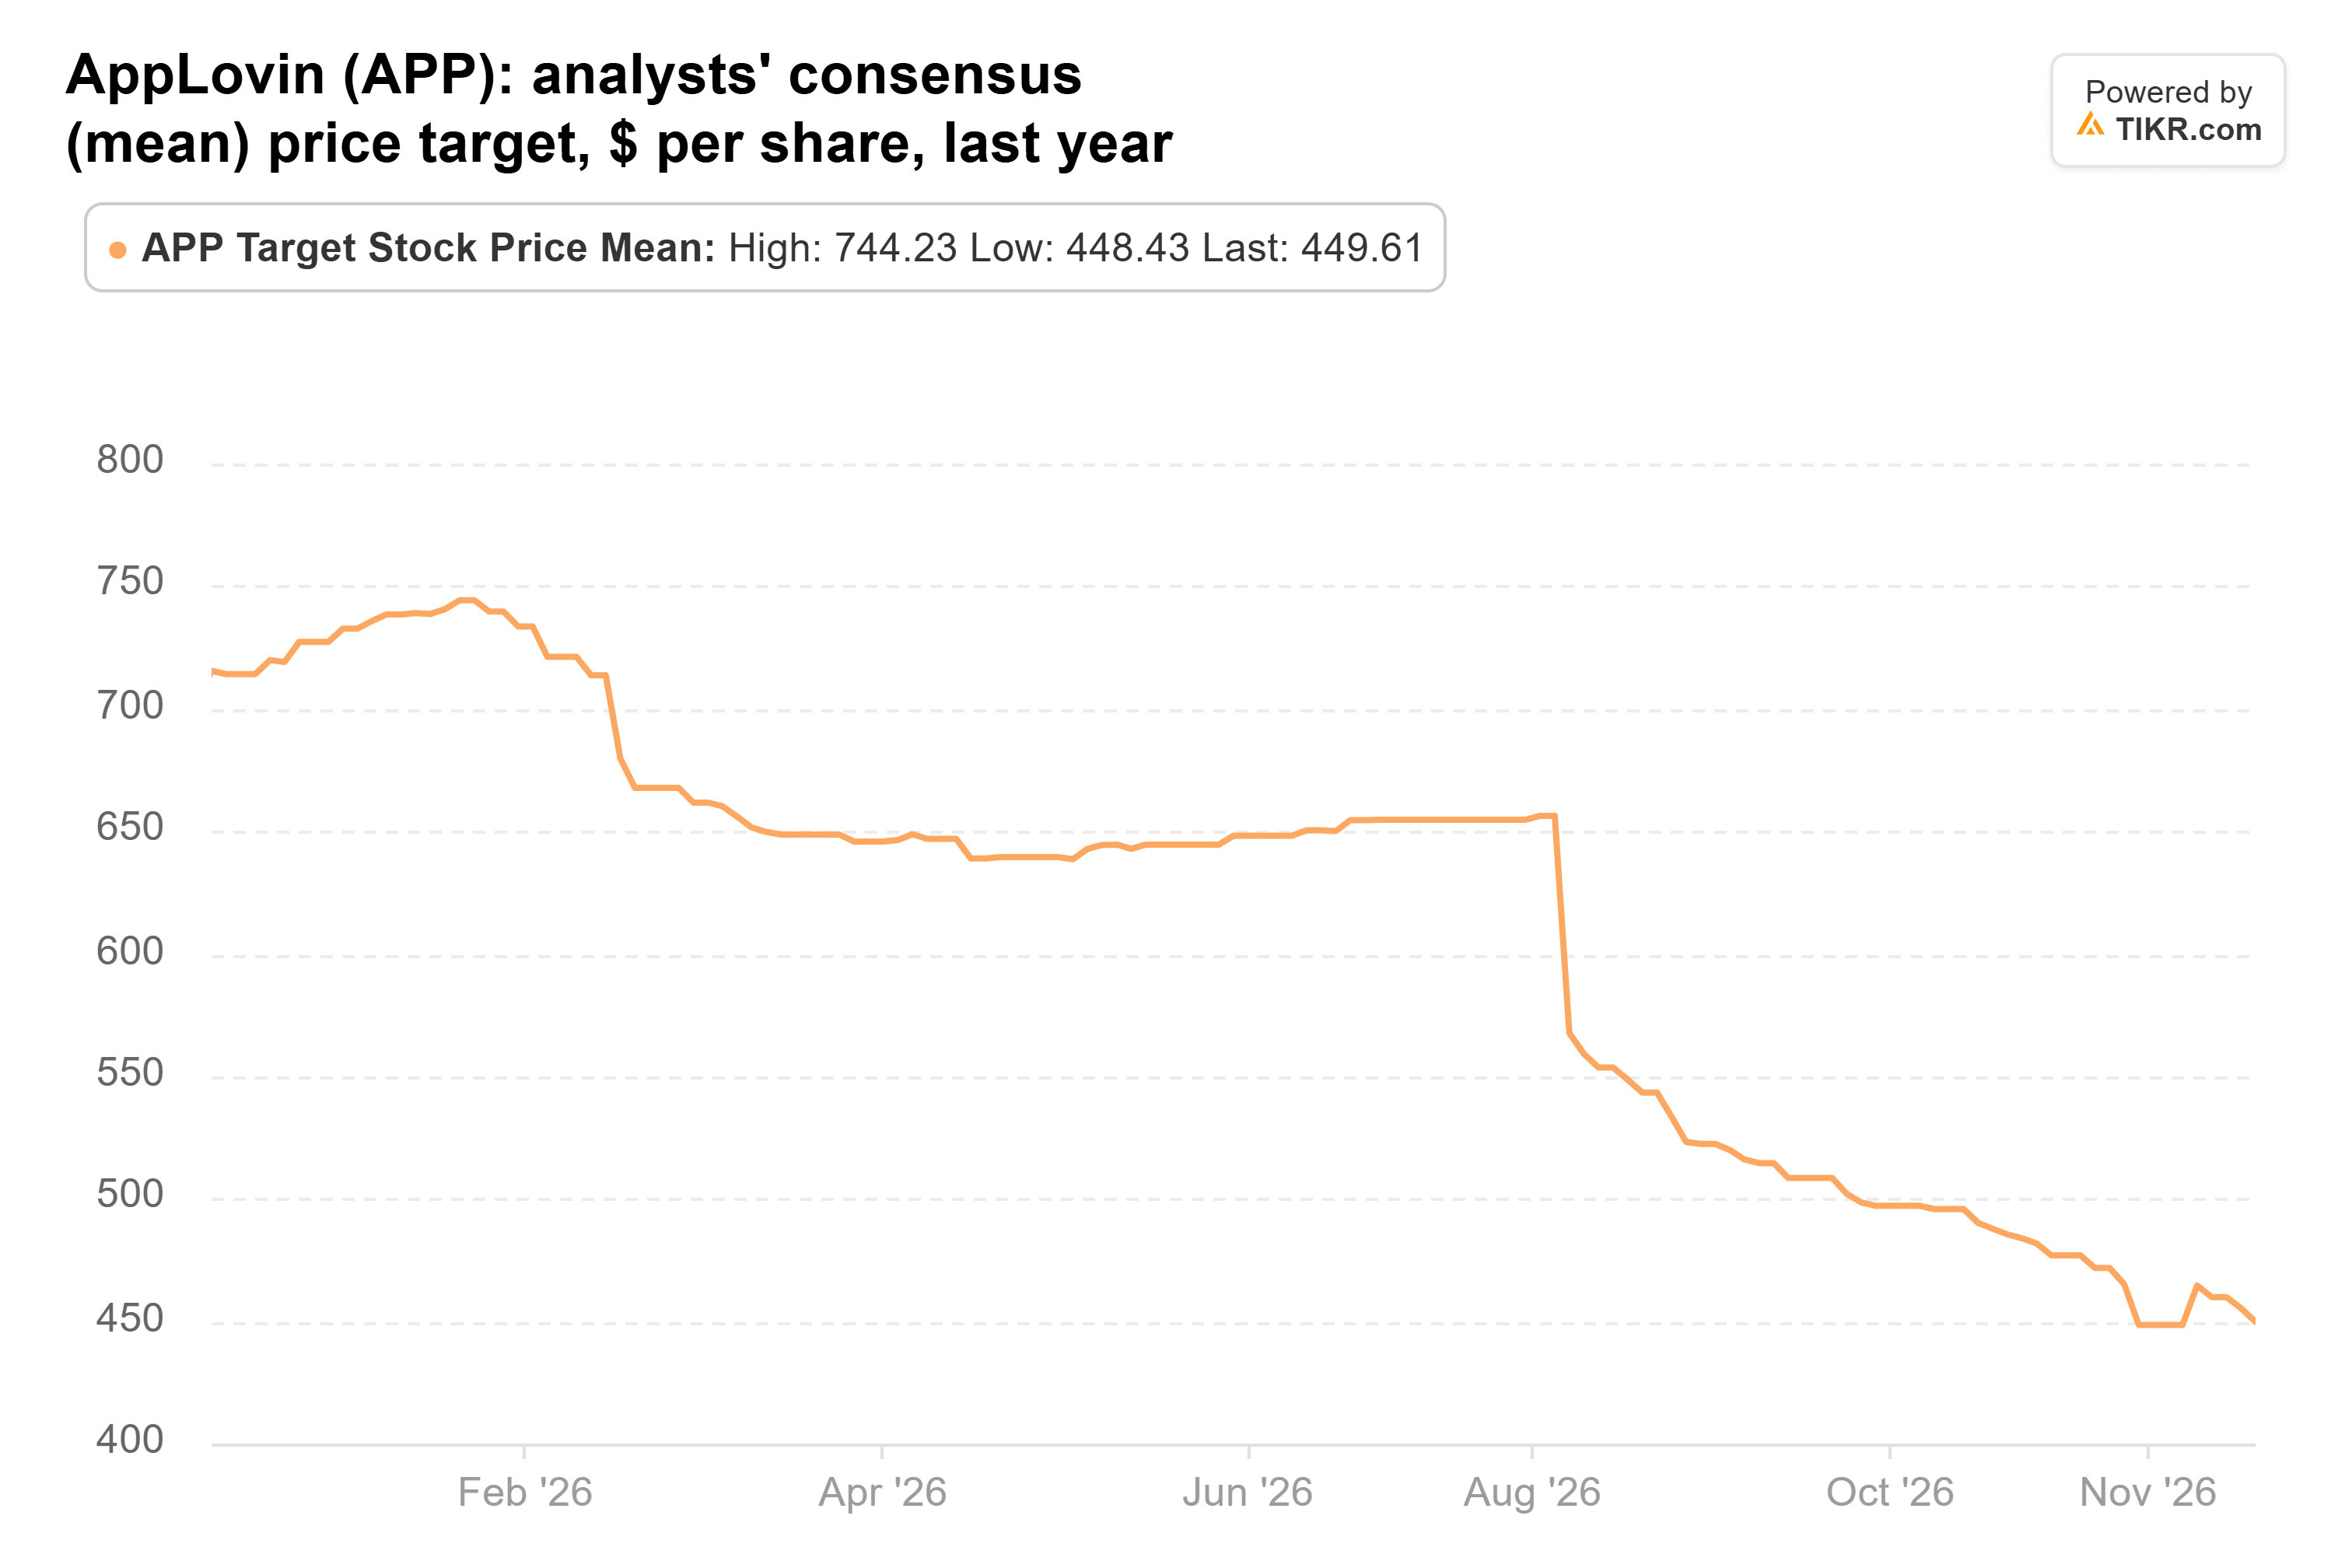
That average is only 10% above the last close. But AppLovin trades at about 21x forward earnings, below its five-year average of about 25x, and that looks cheap for a company still growing more than 40%.
TIKR tracks 32 analysts on AppLovin. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AppLovin, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AppLovin’s Analyst Ratings
Honeywell’s outlook went up
Honeywell International is what’s left after it spun off Honeywell Aerospace on June 29, and its stock is down just 0.6% since Sept. 30. Its third-quarter report in October showed organic sales up 7% and adjusted EPS up 34% to $2.27, and management raised its full-year adjusted EPS guidance to $8.40 to $8.45. The Street’s average target has risen from about $230 at the end of June to about $254:
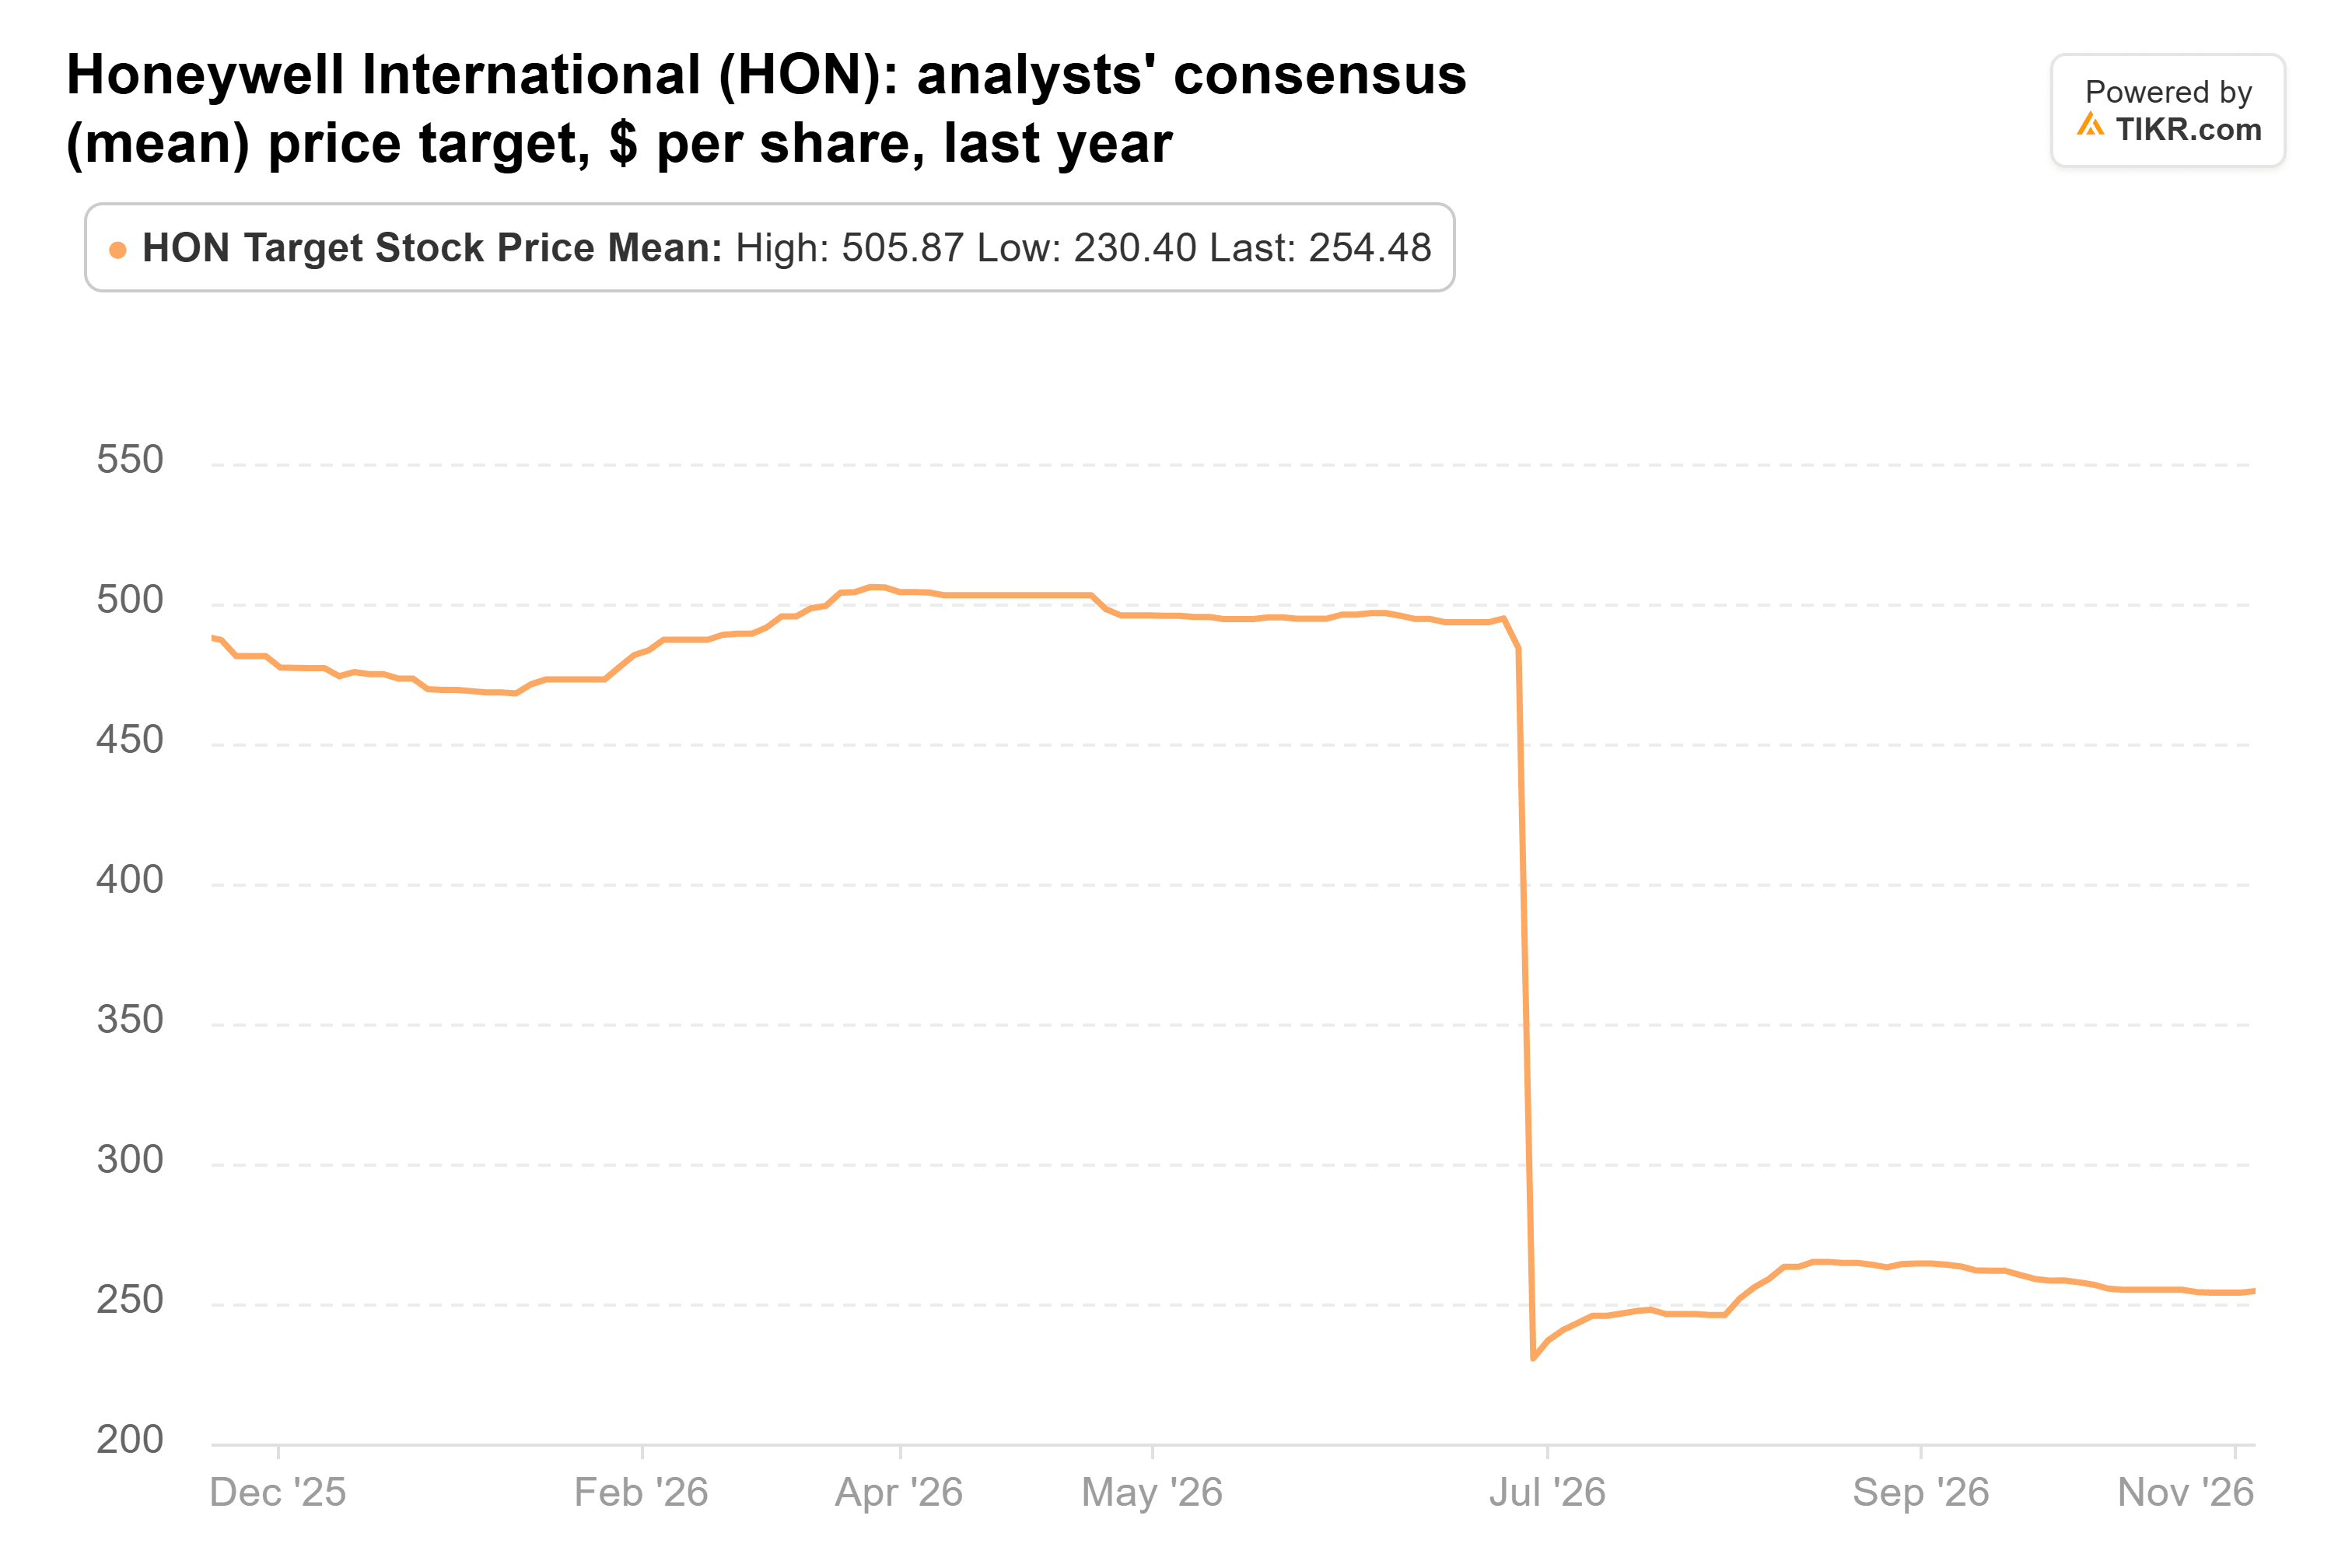
(The chart’s first half is the whole company before the spin-off, which is why the target halves in June.)
That target is 14% above the last close. But at about 23x forward earnings, Honeywell is fully priced for a company guiding to 4% to 5% organic growth this year, so I don’t think Blue Whale gave up much here.
Honeywell Aerospace can’t build fast enough
Honeywell Aerospace has had a rough start on its own. It’s down 25% since Sept. 30 and 45% below its 52-week high, and it sank 11% after its third-quarter report even though the quarter beat the company’s own expectations. Sales rose 2% organically to $4.6 billion, management raised its full-year adjusted EPS guidance, and the board declared a first dividend of $0.40 a quarter. The problem is supply: its 10-Q says some suppliers are still short of skilled labor, capacity and parts, and management said on the call that it couldn’t fill all of its third-quarter orders.
Analysts have cut their average target from $300 in late June to about $193:
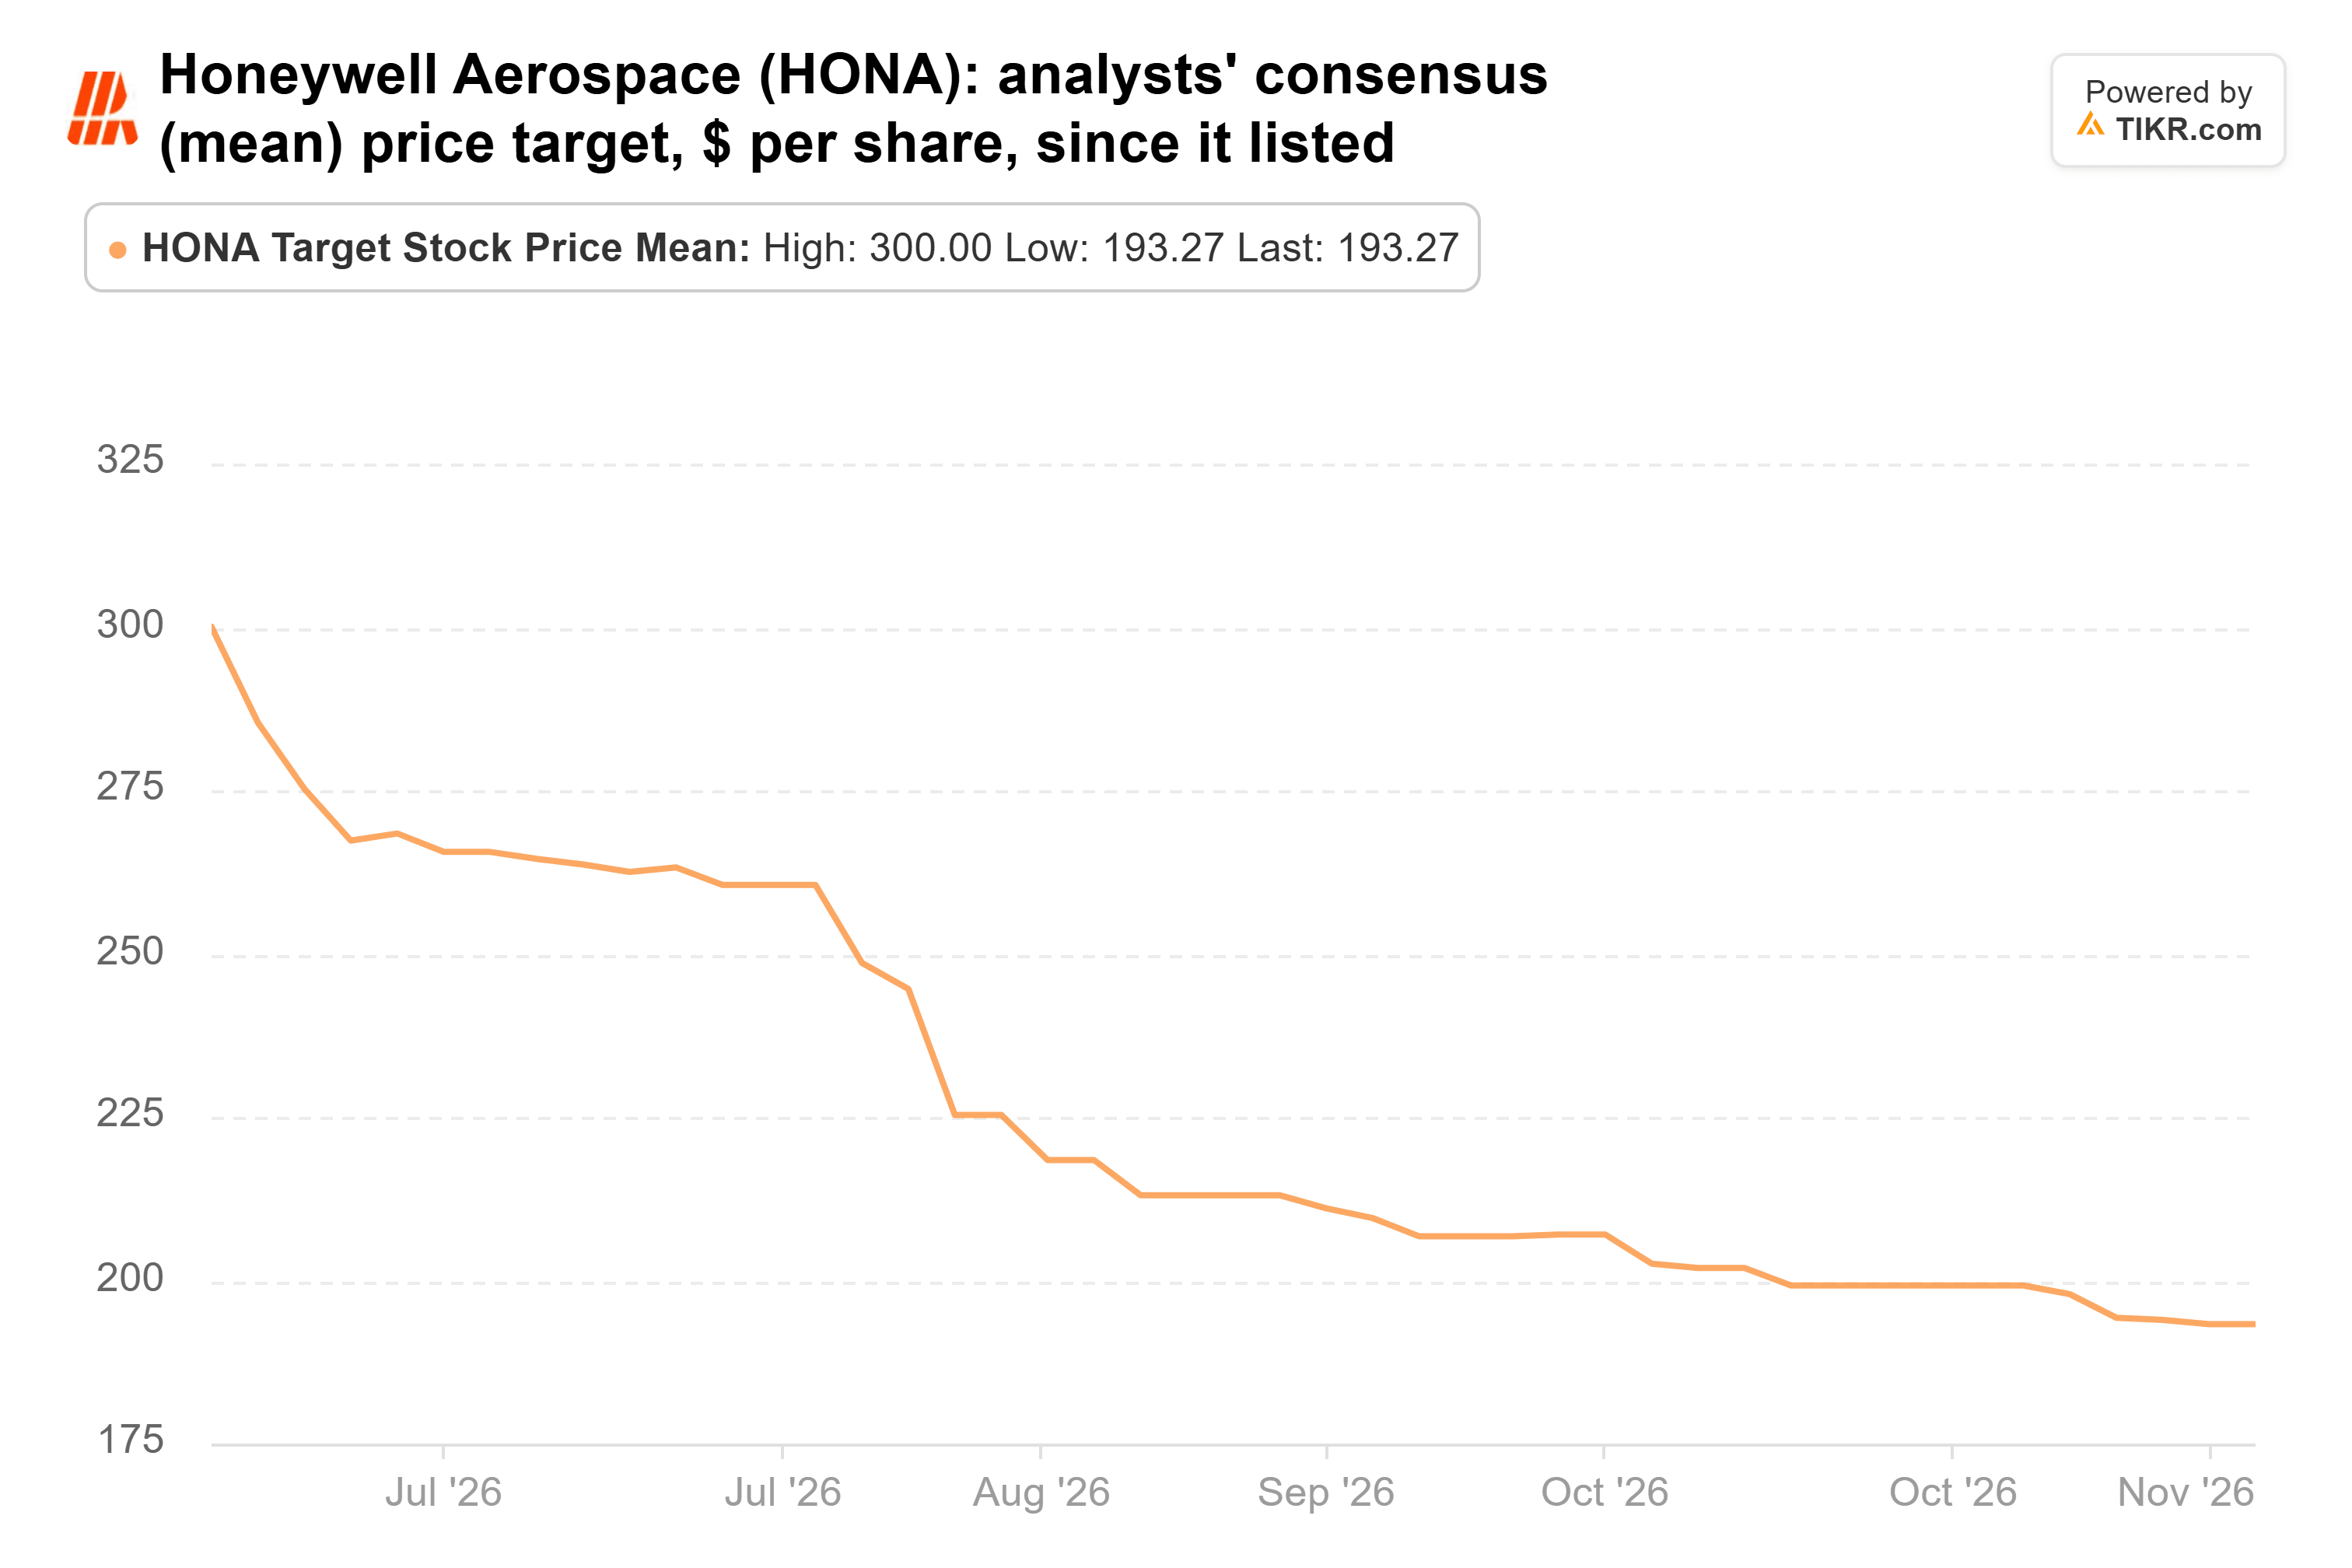
That’s still 17% above the last close, at about 20x forward earnings. But a Street that keeps cutting its targets on a company that can’t ship everything its customers want is the clearest case for selling of the three.
AppLovin is the sale I’d second-guess
The three sales were small next to the stakes Blue Whale built up. Applied Materials and Lumentum, 12.4% and 9.4% of the fund at Sept. 30, are down 28% and 39% since.
Of the three it sold, AppLovin is the one I’d want back: it’s growing fastest, and the stock is cheaper than usual. The risk is one its CEO has flagged himself: its gains won’t land on a perfect quarterly schedule, so a quarter like the second, when revenue grew just 4.4% from the first, can happen again.
AppLovin’s fourth-quarter report should come in February, and Blue Whale’s next 13F is due in mid-February. That filing will show whether the fund stayed away.
So what is AppLovin stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AppLovin could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!