Key Takeaways
- Datadog grew third-quarter revenue 35% to $1.20 billion, then guided the fourth quarter roughly flat as its largest AI customer cut usage.
- The guide assumes that customer drops to its contract minimum, and growth from everyone else is implied in the low to mid 30s.
- Cloudflare grew 39% and guided higher, a sign the slowdown is confined to one Datadog account and not cloud spending broadly.
- Datadog’s first 2027 outlook, expected with fourth-quarter results in February, is the next real test.
Datadog (DDOG) grew third-quarter revenue 35% to $1.20 billion, well above the top of its own range. Then it guided the fourth quarter to $1.19 billion to $1.20 billion, roughly flat with the quarter it just reported.
That flat line traces back to one account. Datadog’s largest customer, an AI company it doesn’t name, cut usage in the third quarter, and the guide assumes it falls to its contract minimum.
The shares sold off hard on the report. Yet one day later, Cloudflare (NET) posted 39% revenue growth to $782.5 million, so cloud budgets don’t look like they’re shrinking across the board.
The real question is whether this is a one-customer problem or the start of something wider.
A beat with a flat finish
The third quarter cleared every bar Datadog set for itself:
- Revenue of $1.20 billion, up 35% from $886 million, against guidance of $1.135 billion to $1.145 billion
- Non-GAAP operating margin of 28%, up from 23% a year earlier
- Free cash flow of $251 million, with $5.2 billion of cash and securities on hand
Customers paying $100,000 or more a year rose 20% to about 4,860. Datadog also lifted its full-year revenue outlook to $4.515 billion to $4.525 billion.
The problem is the shape of the next quarter. Here is the run the guide puts on pause…
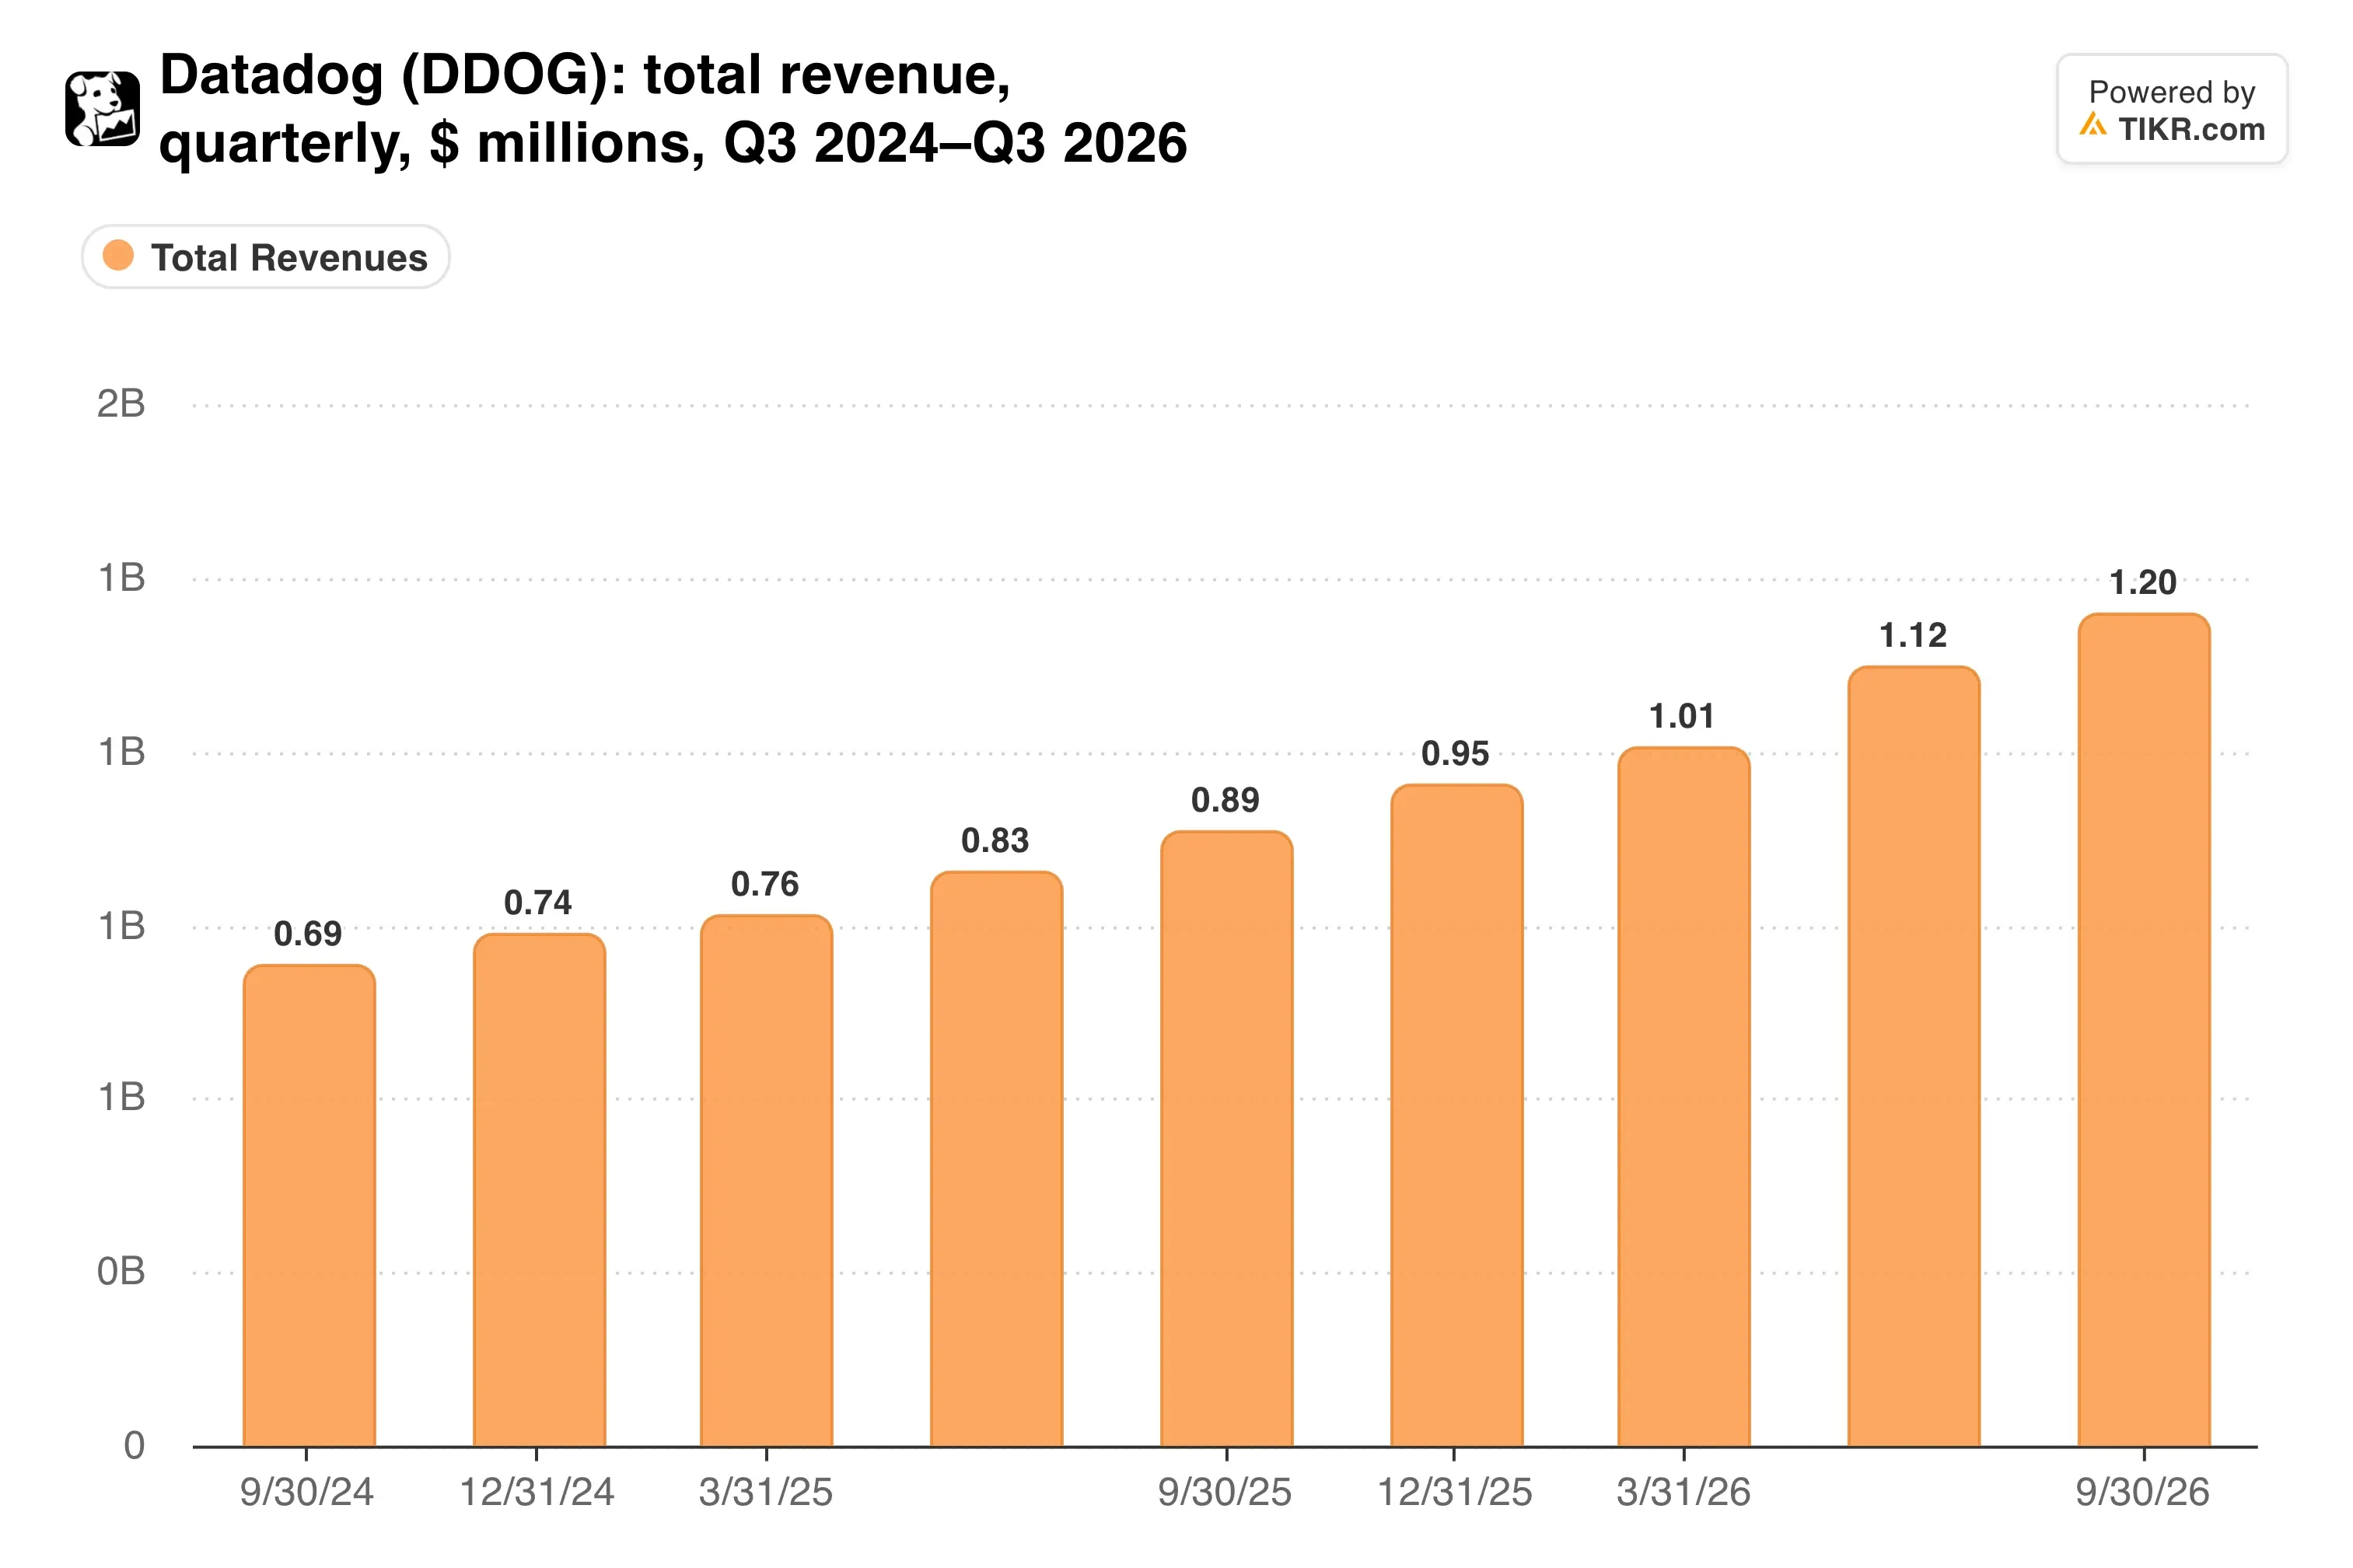
A flat fourth quarter would mean growth of about 25% from a year earlier, down from 35%.
One account, one big drag
CFO David Obstler said the largest customer still spent above its minimum in the third quarter. So any usage above that floor would add revenue the guide doesn’t count.
Strip that customer out, and fourth-quarter growth is implied in the low to mid 30s. Datadog also renewed several large accounts early, AI customers included, at bigger commitments but better volume pricing. That trims revenue in the short run.
CEO Olivier Pomel kept the longer pitch on AI. His team is building specialized models to help customers “move towards autonomous operations,” he said in the earnings release. The first one, Scout 1.0, now powers its Bits Investigation tool.
Cloudflare’s report backs the narrow reading. Its growth sped up to 39%, and it guided the fourth quarter higher again.
So what were analysts expecting before the cut showed up?
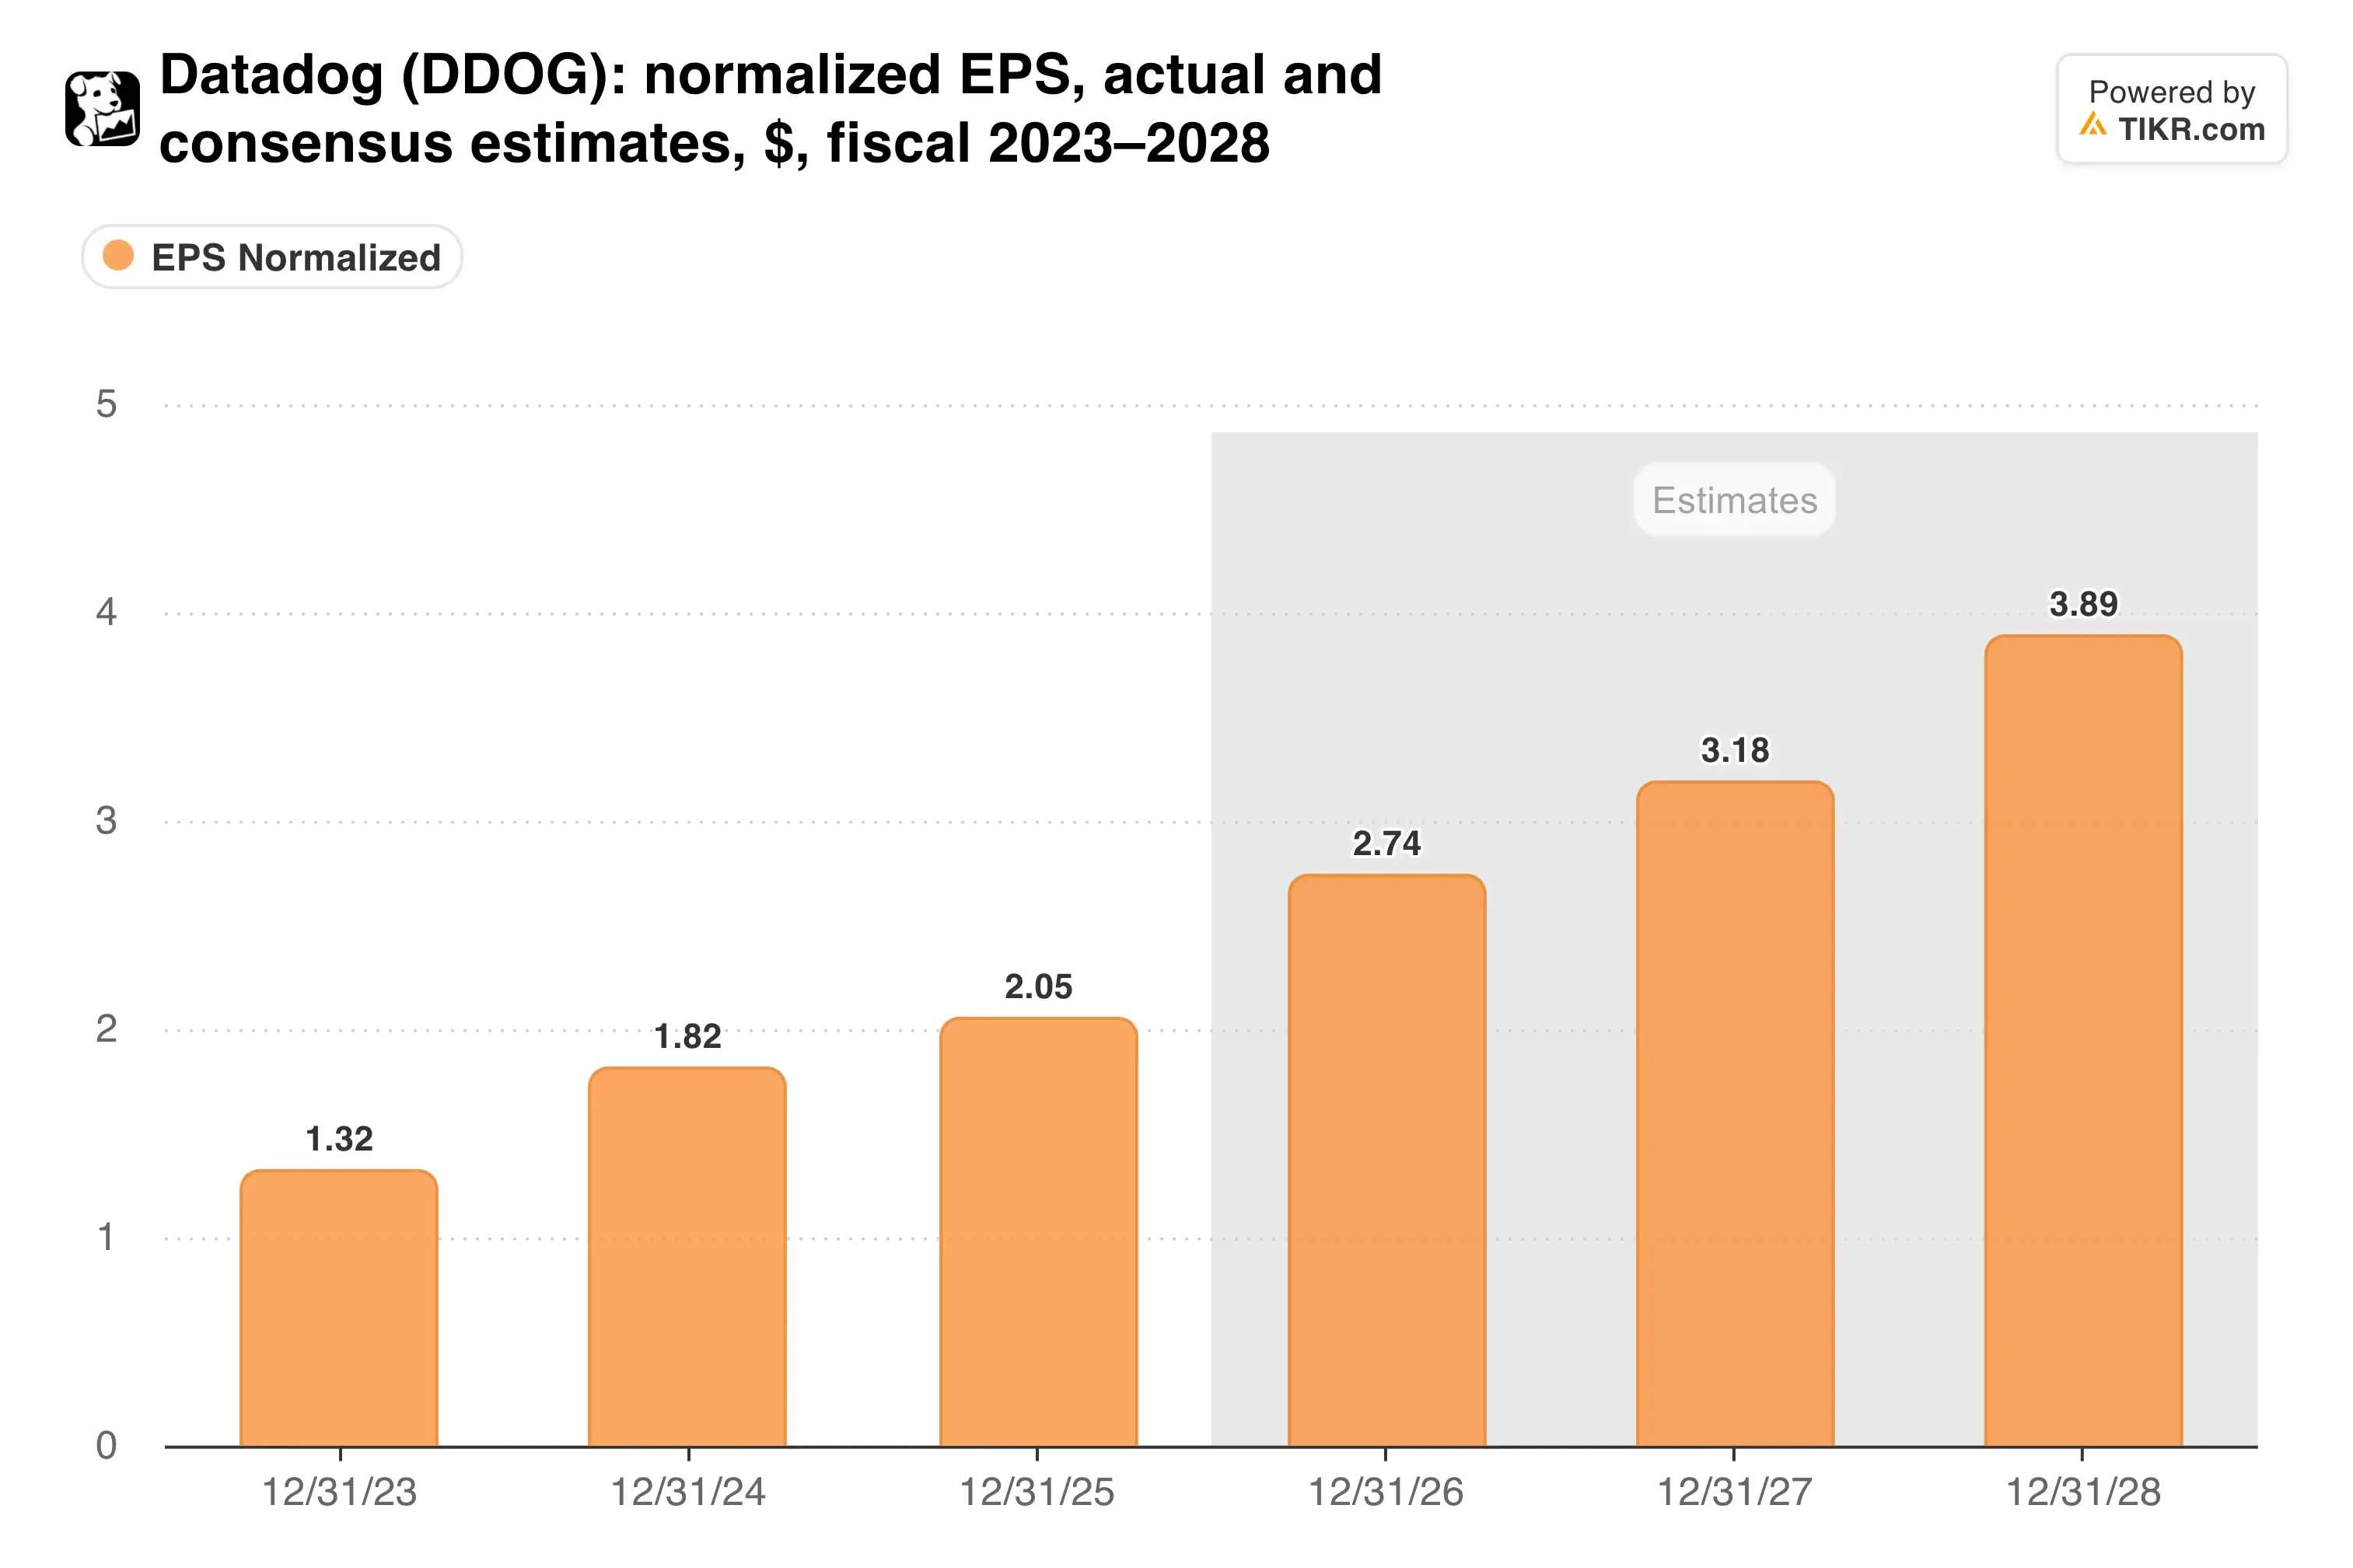
Estimates already pointed to steady earnings gains, and February’s outlook decides whether those numbers hold.
TIKR tracks 48 analysts on Datadog. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Datadog, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Datadog’s Analyst Ratings
Margins dip, cash holds up
The fourth-quarter guide also squeezes profit. Non-GAAP operating income of $280 million to $290 million works out to roughly 24% of revenue, down from 28% in the third quarter.
Cash generation is still the stronger part of the story.
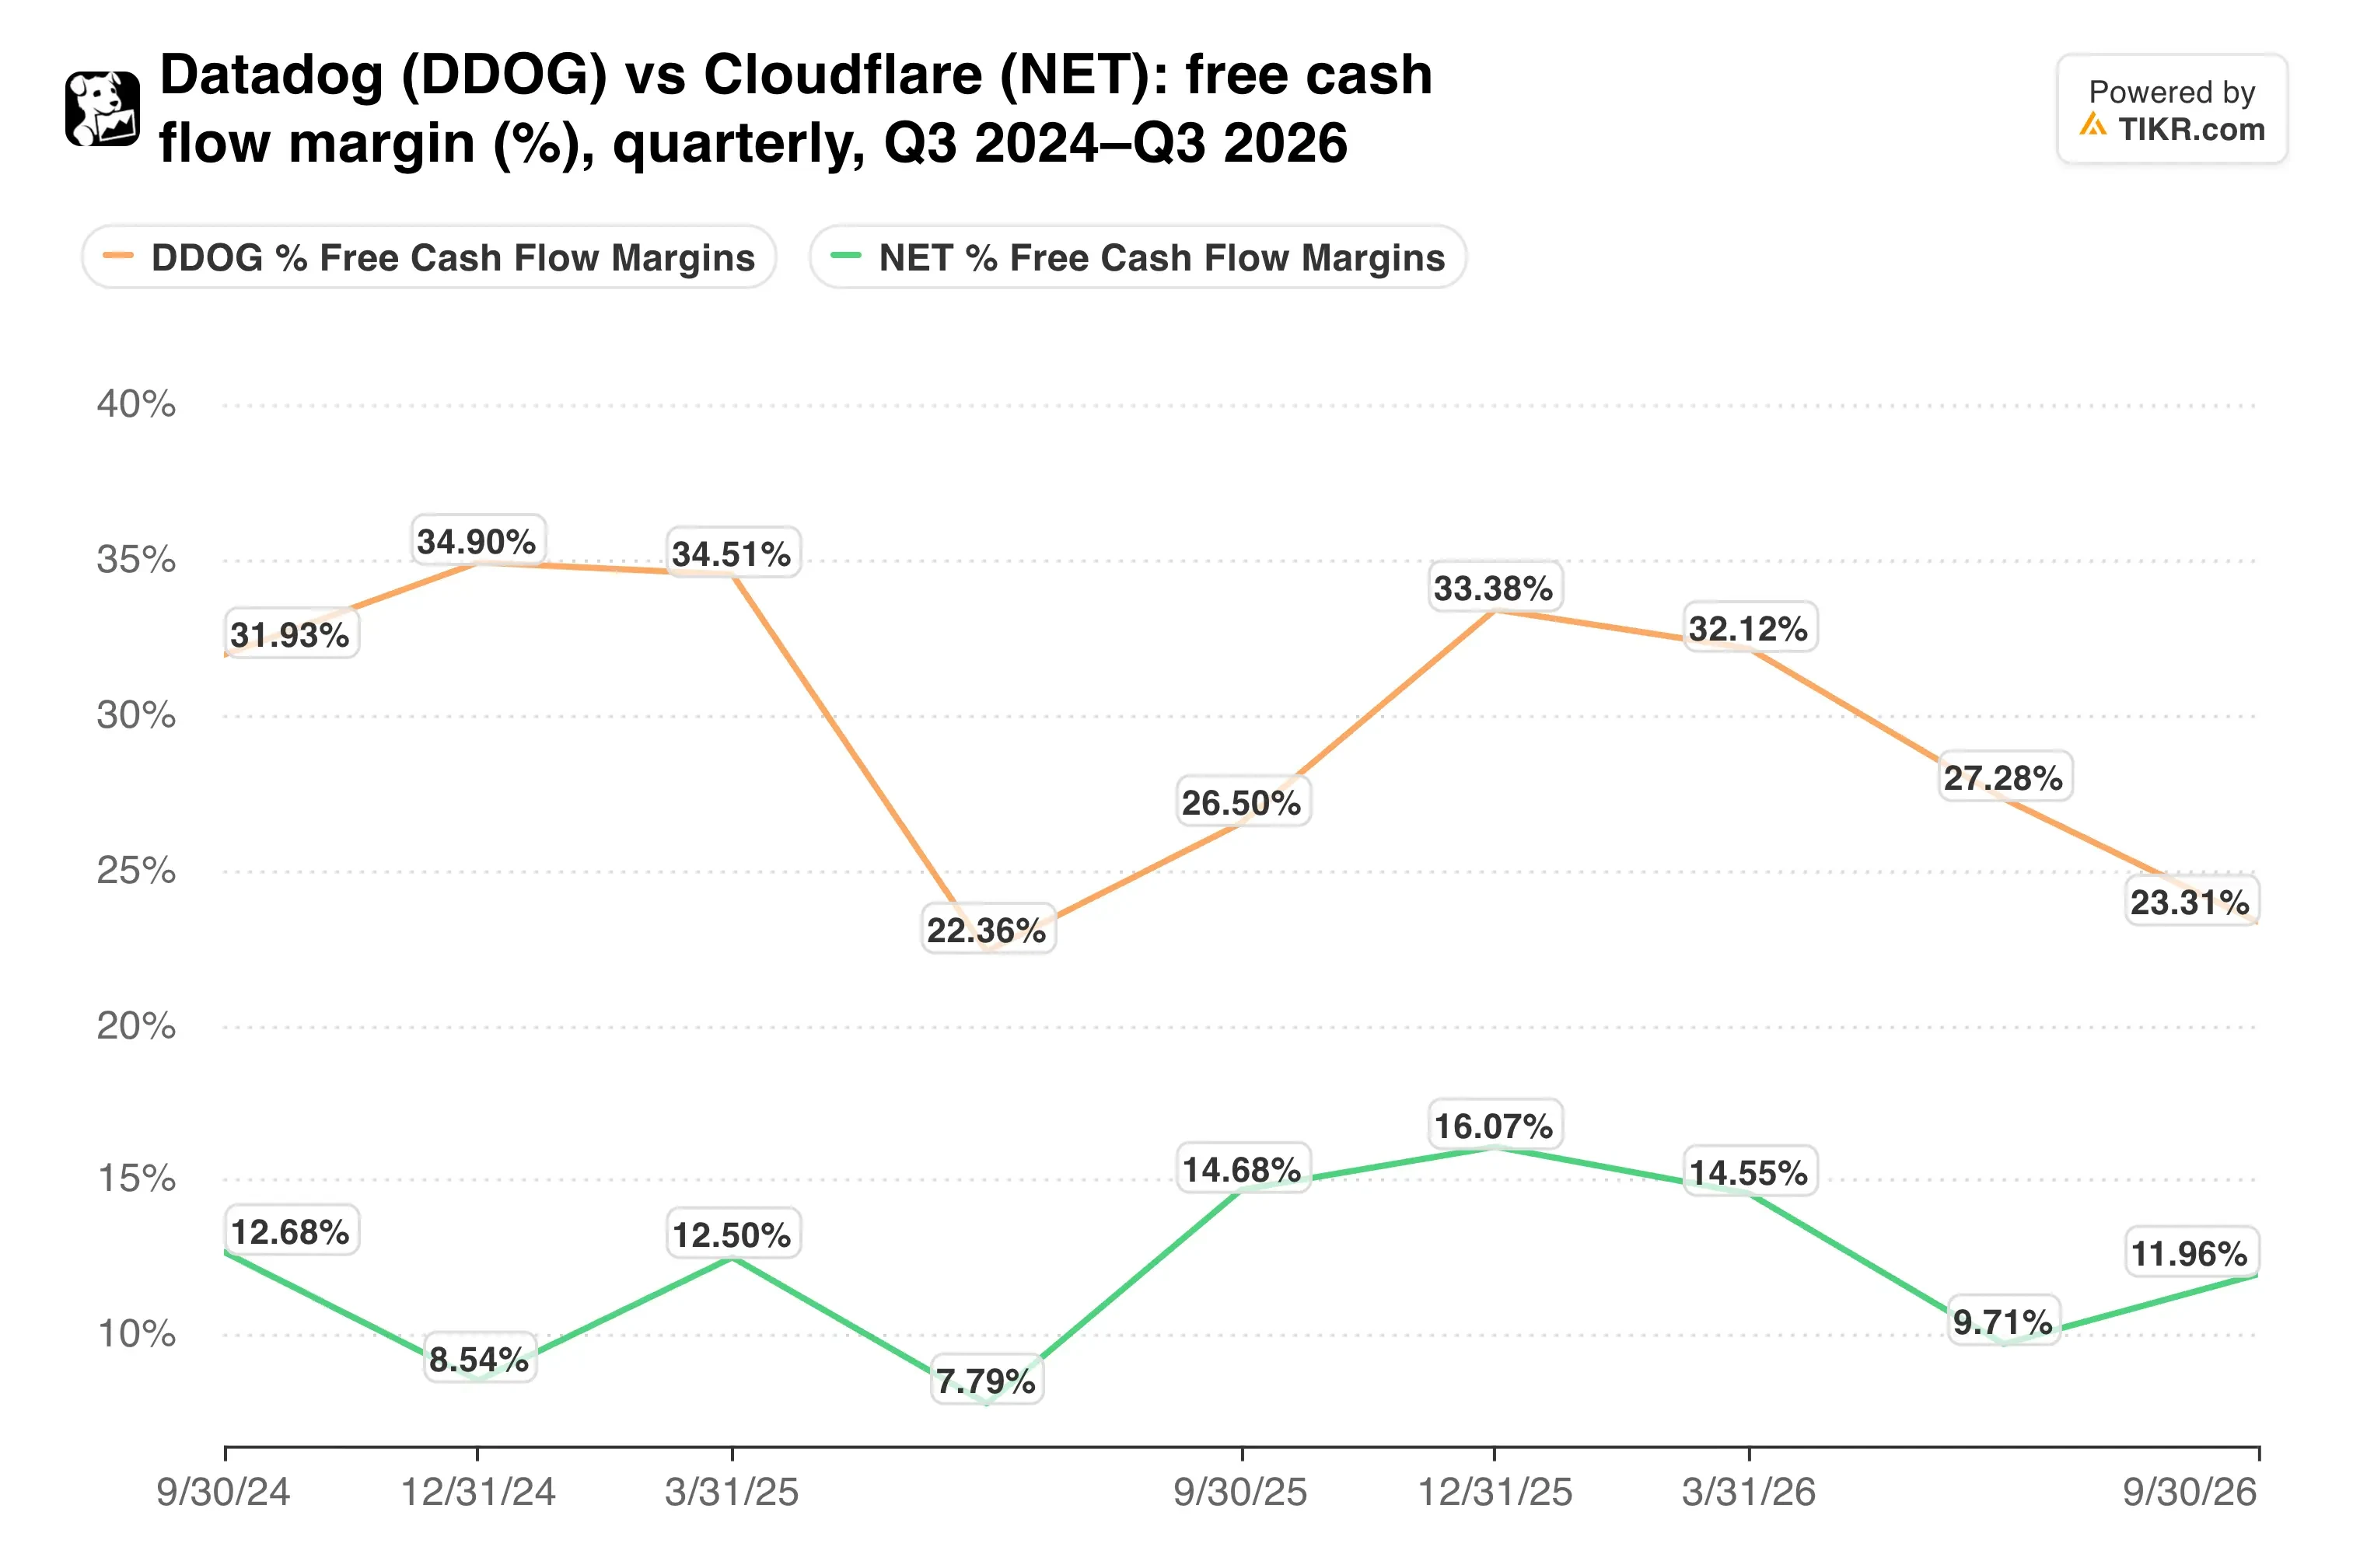
Datadog turned 21% of third-quarter revenue into free cash flow, while Cloudflare converted about 10%.
GAAP results are improving as well. Operating income reached $75 million, against a $6 million loss a year earlier.
Concentration remains the real risk, though. If one AI customer can trim usage in the middle of a contract, another can too, and AI accounts are a growing part of the base.
My take: The selloff treats one customer’s cut as a company-wide slowdown, but the rest of the numbers don’t show one. I think the stock looks reasonable at these levels, although I’d want proof before calling a bottom.
That proof arrives with fourth-quarter results, expected in February, when Datadog gives its first 2027 outlook. Growth in the high 20s or better, with the largest customer near its floor, would show the reset is done.
So what is Datadog stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Datadog could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!