Key Takeaways
- NIO stock fell 10.4% in the past month to a fresh 52-week low, about twice the Nasdaq 100’s drop, as delivery growth slowed to 7.7% in September.
- Geely buying 30% of NIO’s battery-swap unit is a real endorsement of the network, but the deal brings only RMB640 million in cash and does nothing directly for car sales.
- At 0.4x forward sales, the lowest in five years, the selling looks overdone, with free cash flow positive and deliveries up 49% in the first nine months of 2026.
- October deliveries come out in early November and will show whether NIO can reach its goal of more than 40,000 cars a month in the fourth quarter.

NIO (NIO) stock fell 10.4% in the past month (through Friday’s close) to a fresh 52-week low, about twice the Nasdaq 100’s 5% drop. A battery-swap deal with Geely gave the shares a brief lift, but the car sales underneath kept slowing.
A good deal, a bad month
On Sept. 27, NIO said a subsidiary of Geely Holding Group would take 30% of NIO Power, its battery-swapping and charging unit, valuing it at about RMB16 billion after the investment. Geely is paying with RMB640 million in cash plus its own battery-swap business for commercial fleets, and NIO keeps 63.6%.
A big automaker buying in is a real endorsement of the swap network. But the cash is small next to NIO’s RMB87.5 billion of revenue last year, and the stock gave back its gain the next day.
Then the delivery numbers came out. NIO delivered 37,408 cars in September, up just 7.7% from a year earlier. It delivered 109,178 in the third quarter, up 25.4%, after 49.4% growth in the second quarter. China’s market didn’t help: retail passenger car sales fell 28% in September from a year earlier, in what’s usually the peak season.
The market explains part of the drop: a broad tech sell-off hit the shares on Thursday, and they closed at another low on Friday. Slowing delivery growth adds a company-specific worry on top.
TIKR Tracks 23 Analysts on NIO. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on NIO, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See NIO’s Analyst Ratings
Volume is the problem
Management is aiming for more than 40,000 deliveries a month in the fourth quarter. The bottom of that goal, about 120,000 cars, sits roughly 4% below the fourth quarter of 2025, when NIO delivered 124,807.
Slower volume leaves less room for rising costs. On NIO’s Sept. 1 call, CFO Stanley Qu said material costs would climb another RMB2,000 to RMB3,000 per car in the second half, on top of about RMB14,000 per car since late 2025. The cheaper ONVO and Firefly brands supplied 46,678 of the third quarter’s cars. ONVO’s deliveries slipped to 27,728 from 29,124 in the second quarter.
Profit is thin: adjusted net profit fell to RMB26.1 million in the second quarter, from RMB726.8 million in the fourth quarter of 2025. But NIO turned free cash flow positive in the second quarter, and management expects it to stay positive through year-end.
Analysts still expect revenue to grow about 46% this year, to RMB128 billion, and another 19% in 2027.

Those estimates already build in only single-digit growth for the fourth quarter, so much of September’s slowdown is in this year’s number.
October’s number decides it
NIO reports October deliveries in early November. Clearing 40,000, about 7% more cars than September, would put the fourth-quarter goal within reach. Another month near 37,408 would cast doubt on the goal and on the growth behind the 2027 estimates.
Third-quarter results will likely follow in late November (NIO reported last year’s on Nov. 25). Watch whether vehicle margin held at the second quarter’s 18.5%, with the cheaper brands making up 43% of the cars.
NIO looks overdone, but October has to prove it
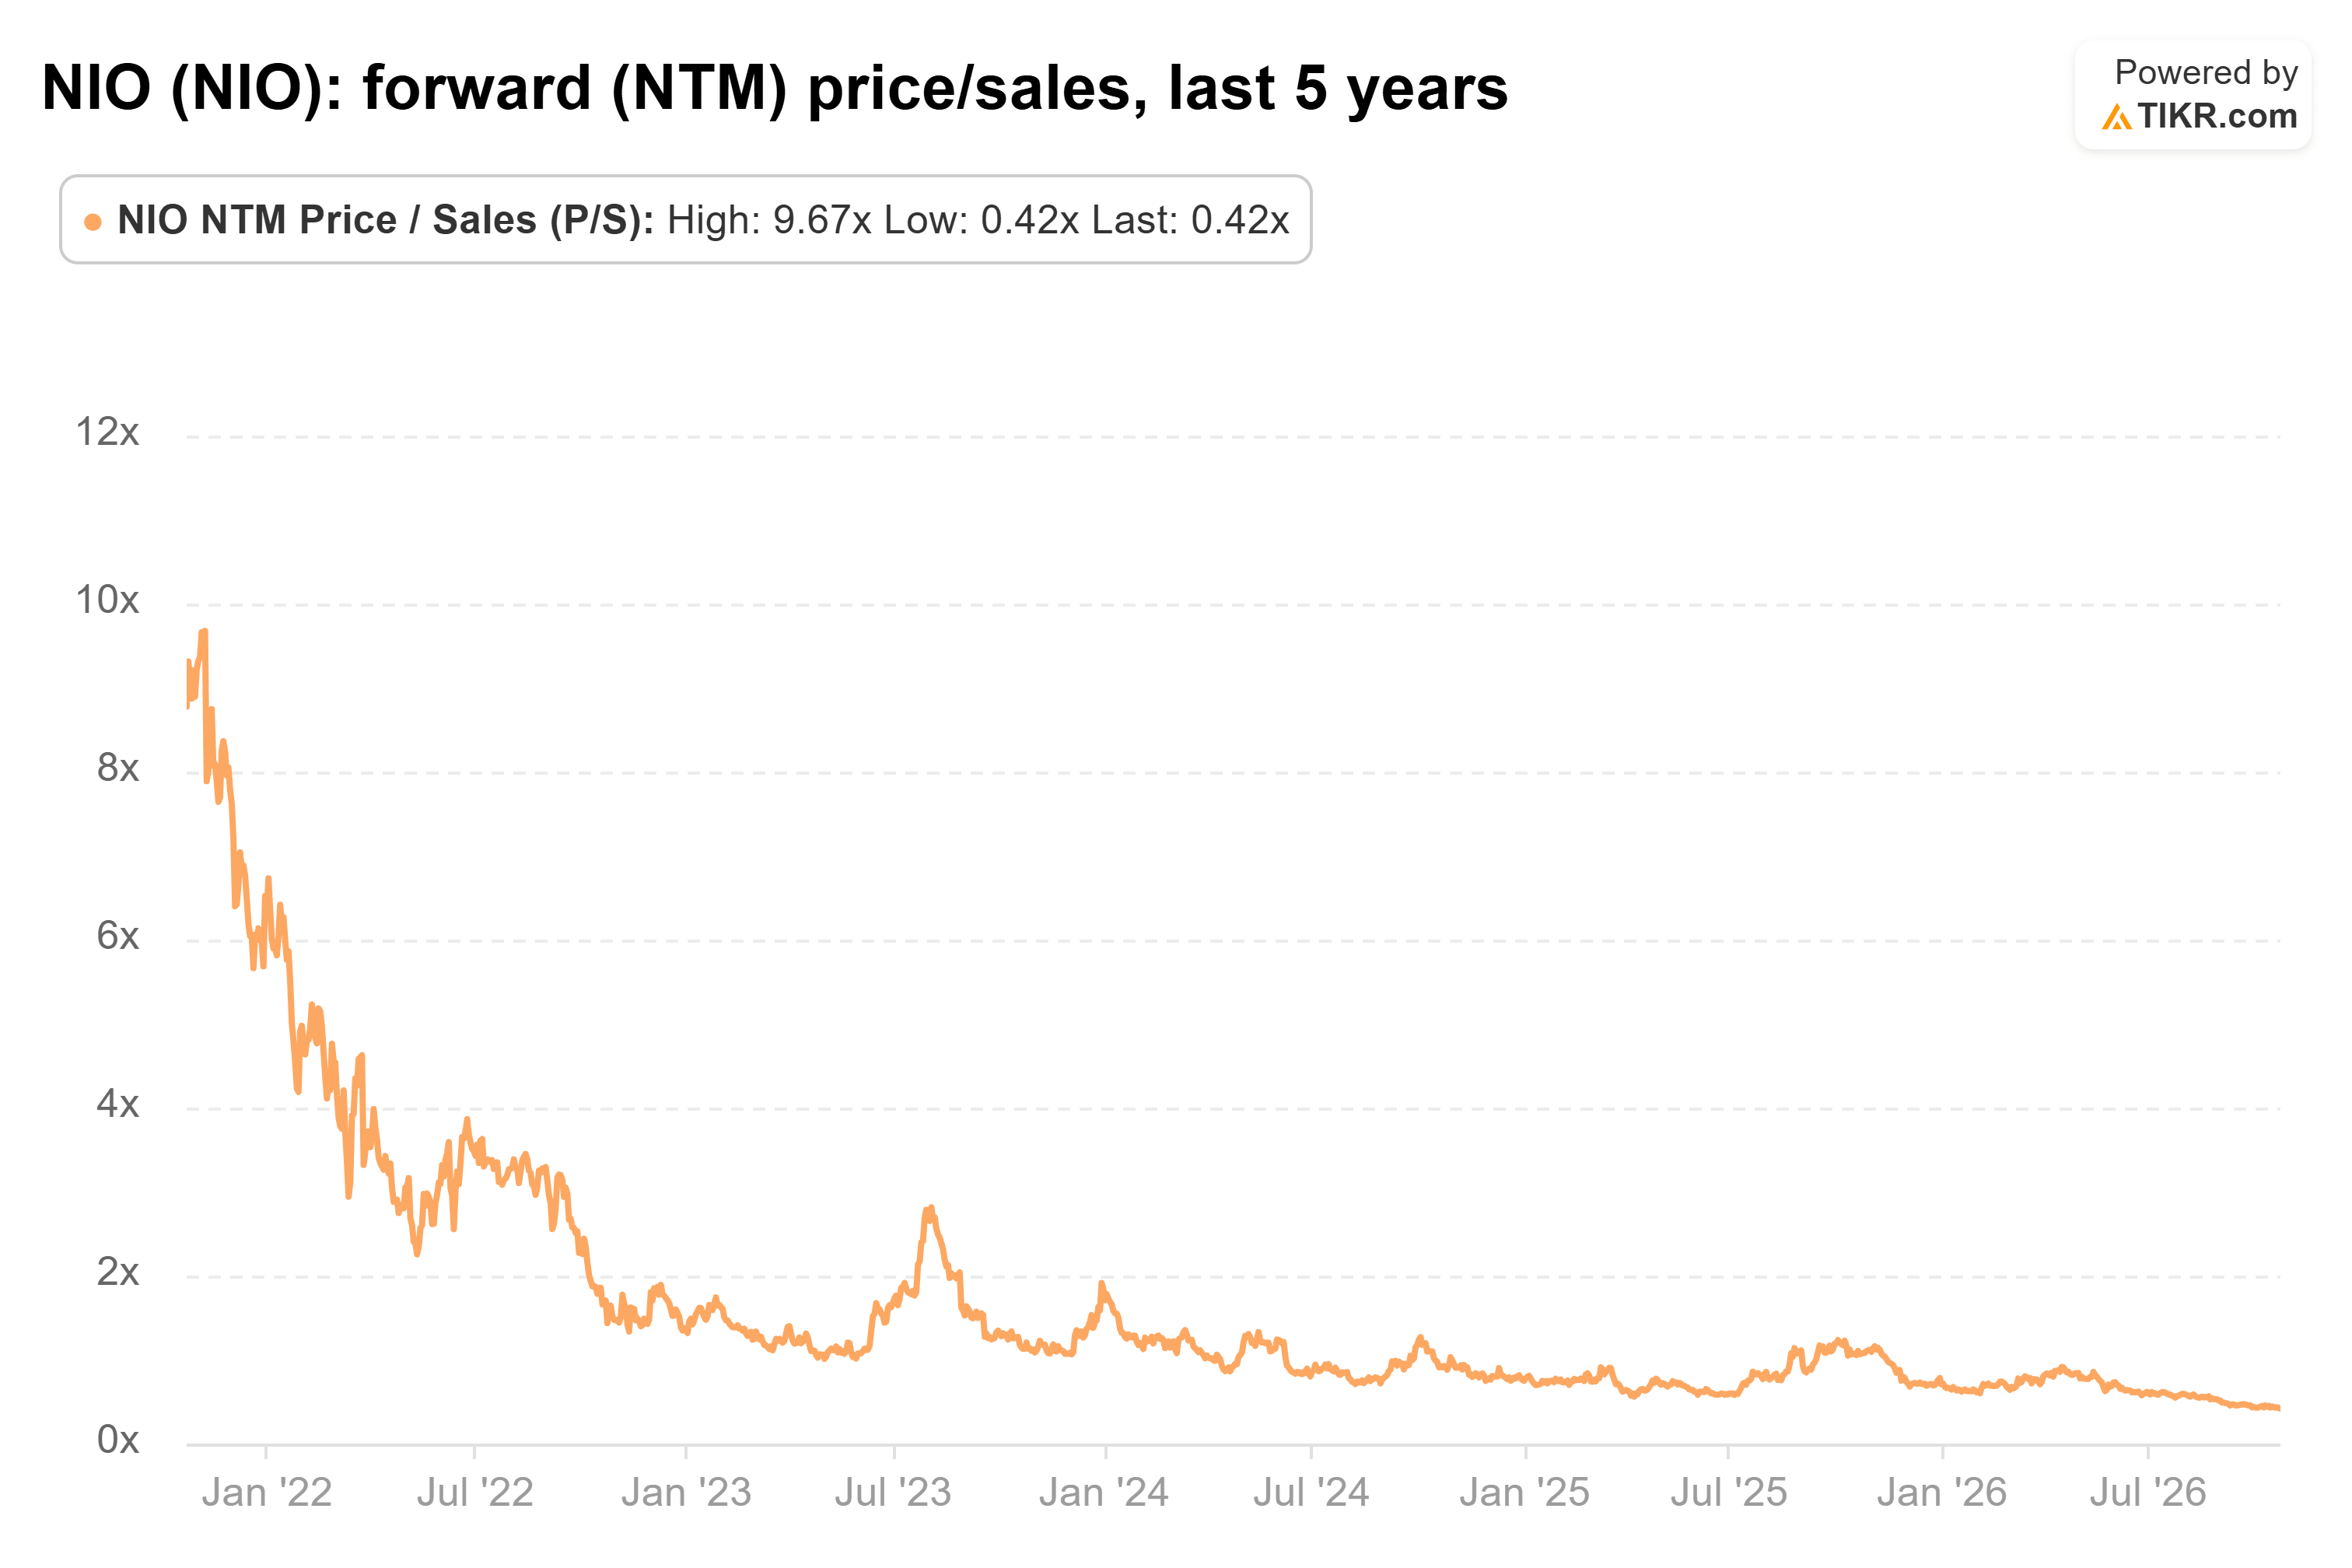
NIO trades at 0.4x forward sales, its lowest in five years and well below its 1.7x five-year average.
Even Bernstein, which rates NIO a Hold, has a $5 target, roughly 50% above Friday’s close.
The risk is a Chinese car market that keeps shrinking, which would make 40,000 a month harder to reach and squeeze margin on fewer cars.
So yes, I think the selling is overdone. A carmaker that grew deliveries 49% through September and now makes free cash flow shouldn’t trade at its lowest multiple in five years. October is the test, though: another month short of 40,000, and that 0.4x starts to look earned.
So what is NIO stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NIO could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!