Key Stats for Netflix Stock
- Current Price: $65.85
- Target Price (Mid): ~$126
- Street Target: ~$85
- Potential Total Return: ~91%
- Annualized IRR: ~17% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Netflix (NFLX) closed at $65.85 on October 23, down 29.8% in 2026, after a 5.31% drop on October 21 that followed a cut to its 2026 ad outlook and a fourth-quarter revenue guide below estimates. The longer-running problem surfaced on the October 20 earnings interview, when co-CEO Ted Sarandos graded the company’s U.S. shows as doubles and triples. Whether to sell or load up depends on whether Netflix can turn those into home runs, and how much bad news the price already carries.
Netflix’s U.S. Shows Are Hitting Doubles When the World Needs Home Runs
Sarandos put it plainly: “we had some really solid doubles and triples this year, but the other territories count on some of those titles being home runs so that they’ll travel around the world.” Big U.S. originals work as Netflix’s export product, so a U.S. show that only performs at home leaves growth unclaimed in every other region.
Local slates show what a hit is worth. Co-CEO Greg Peters said a strong Indian slate, led by a couple of standout titles, lifted India’s third-quarter view hours 24% on an absolute basis and drove nearly 20% revenue growth. U.S. revenue grew 14.9% in 2025 to $18.5 billion, the largest of any region, so a better U.S. hit rate moves the whole company.
Netflix is acting on it. It announced about 1,000 job cuts, roughly 6% of its workforce, and the next day named former Disney executive Peter Rice chief content officer, replacing Bela Bajaria, starting October 26. Film chief Dan Lin’s exit followed days later, and Sarandos said he believes Rice can shape projects already in the works, even in the short term. Peters set the goal as going “from very good to great on the performance of that slate,” pointing to fourth-quarter releases such as East of Eden and a 2027 slate that includes Narnia and new seasons of Wednesday and Bridgerton.

TIKR tracks 52 analysts on Netflix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Netflix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Netflix’s Analyst Ratings
Netflix Now Trades Closer to Disney Than to Spotify
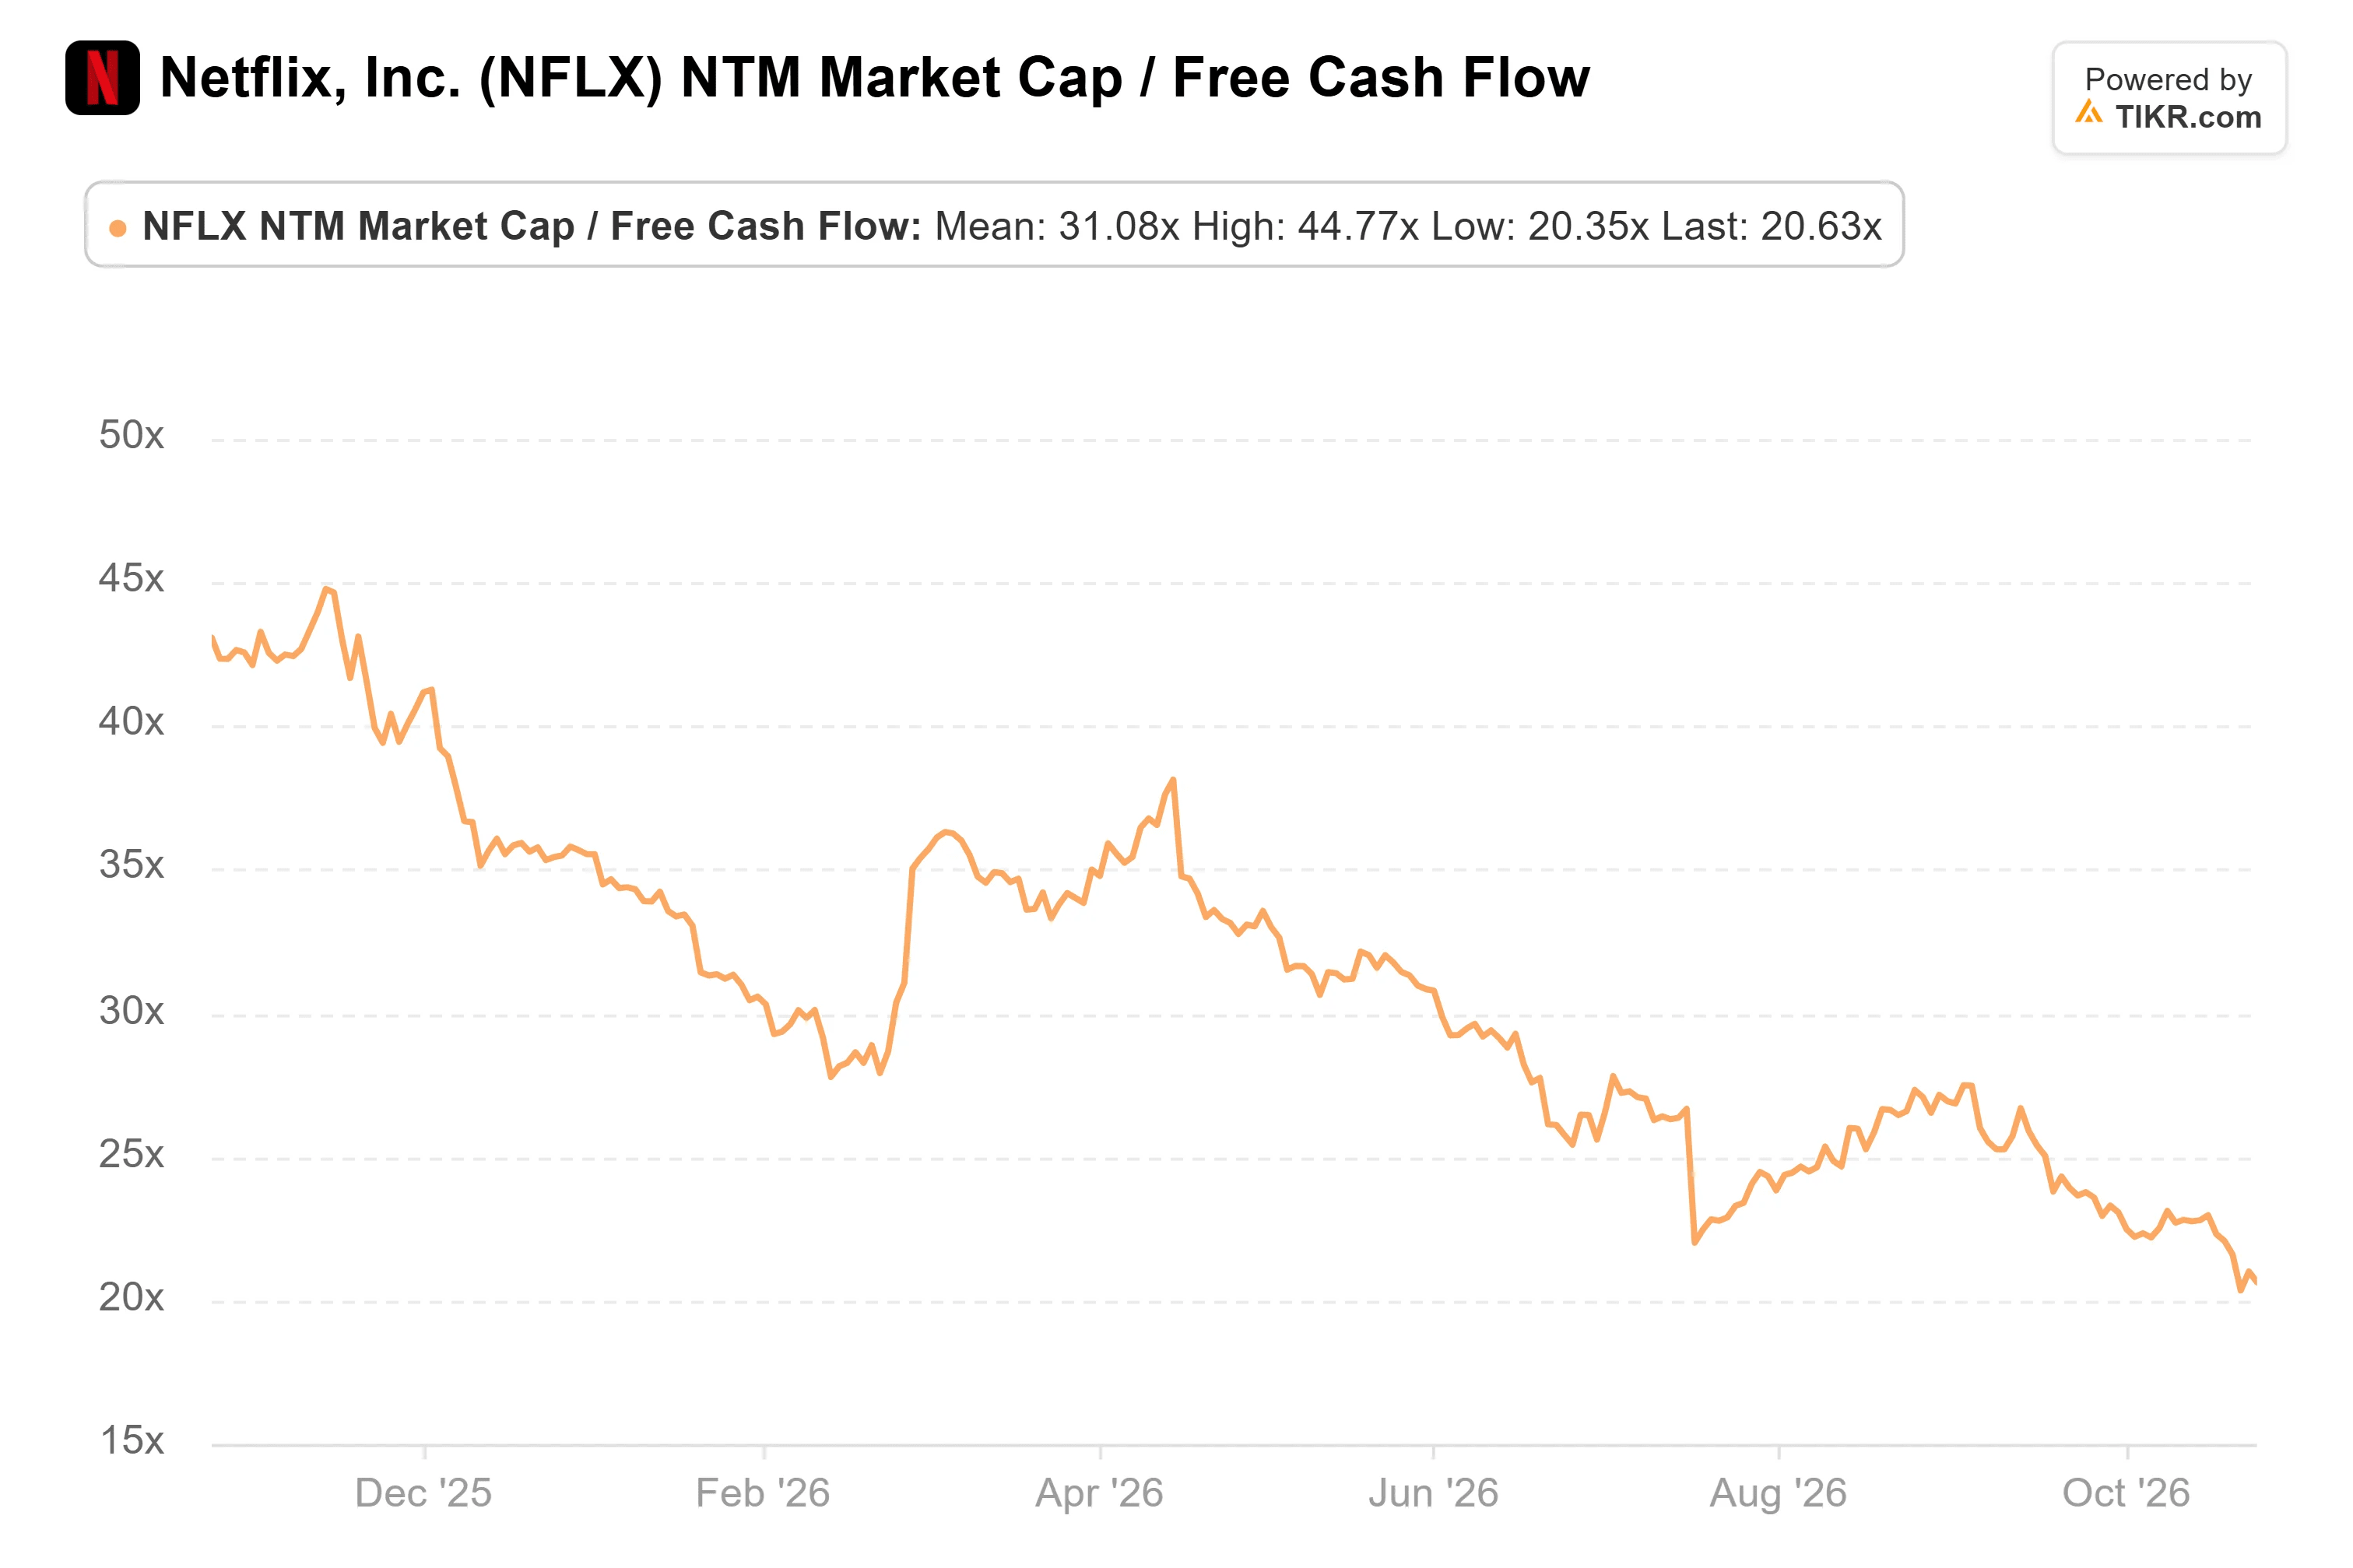
At around 18 times NTM earnings, Netflix trades closer to Disney (DIS) at around 15x than to Spotify (SPOT) at around 37x, despite guiding to 13% revenue growth in 2026. Its NTM levered free cash flow yield has risen to around 5%, from around 2% at the end of September 2025.
That discount reflects real setbacks. Third-quarter EPS of $0.87 beat the $0.82 estimate, but Netflix said its operating margin beat its own forecast primarily because of expense timing. It cut its 2026 ad revenue outlook to about $2.7 billion from about $3 billion after a slower rollout of some ad products, and guided fourth-quarter revenue to around $13.4 billion, below the pre-report consensus of about $13.5 billion. The around 26% fourth-quarter operating margin guide includes about 120 basis points of layoff costs and still tops the 24.5% of a year earlier. Free cash flow guidance fell to about $12 billion from $12.5 billion, mainly on a real estate deal closing in the fourth quarter. Since the end of September, the Street’s mean target has fallen to around $85 from around $93, Buy ratings have slipped to 26 from 28, and Sell ratings have risen to two from one.
TIKR Advanced Model Analysis
- Current Price: $65.85
- Target Price (Mid): ~$126
- Potential Total Return: ~91%
- Annualized IRR: ~17% / year
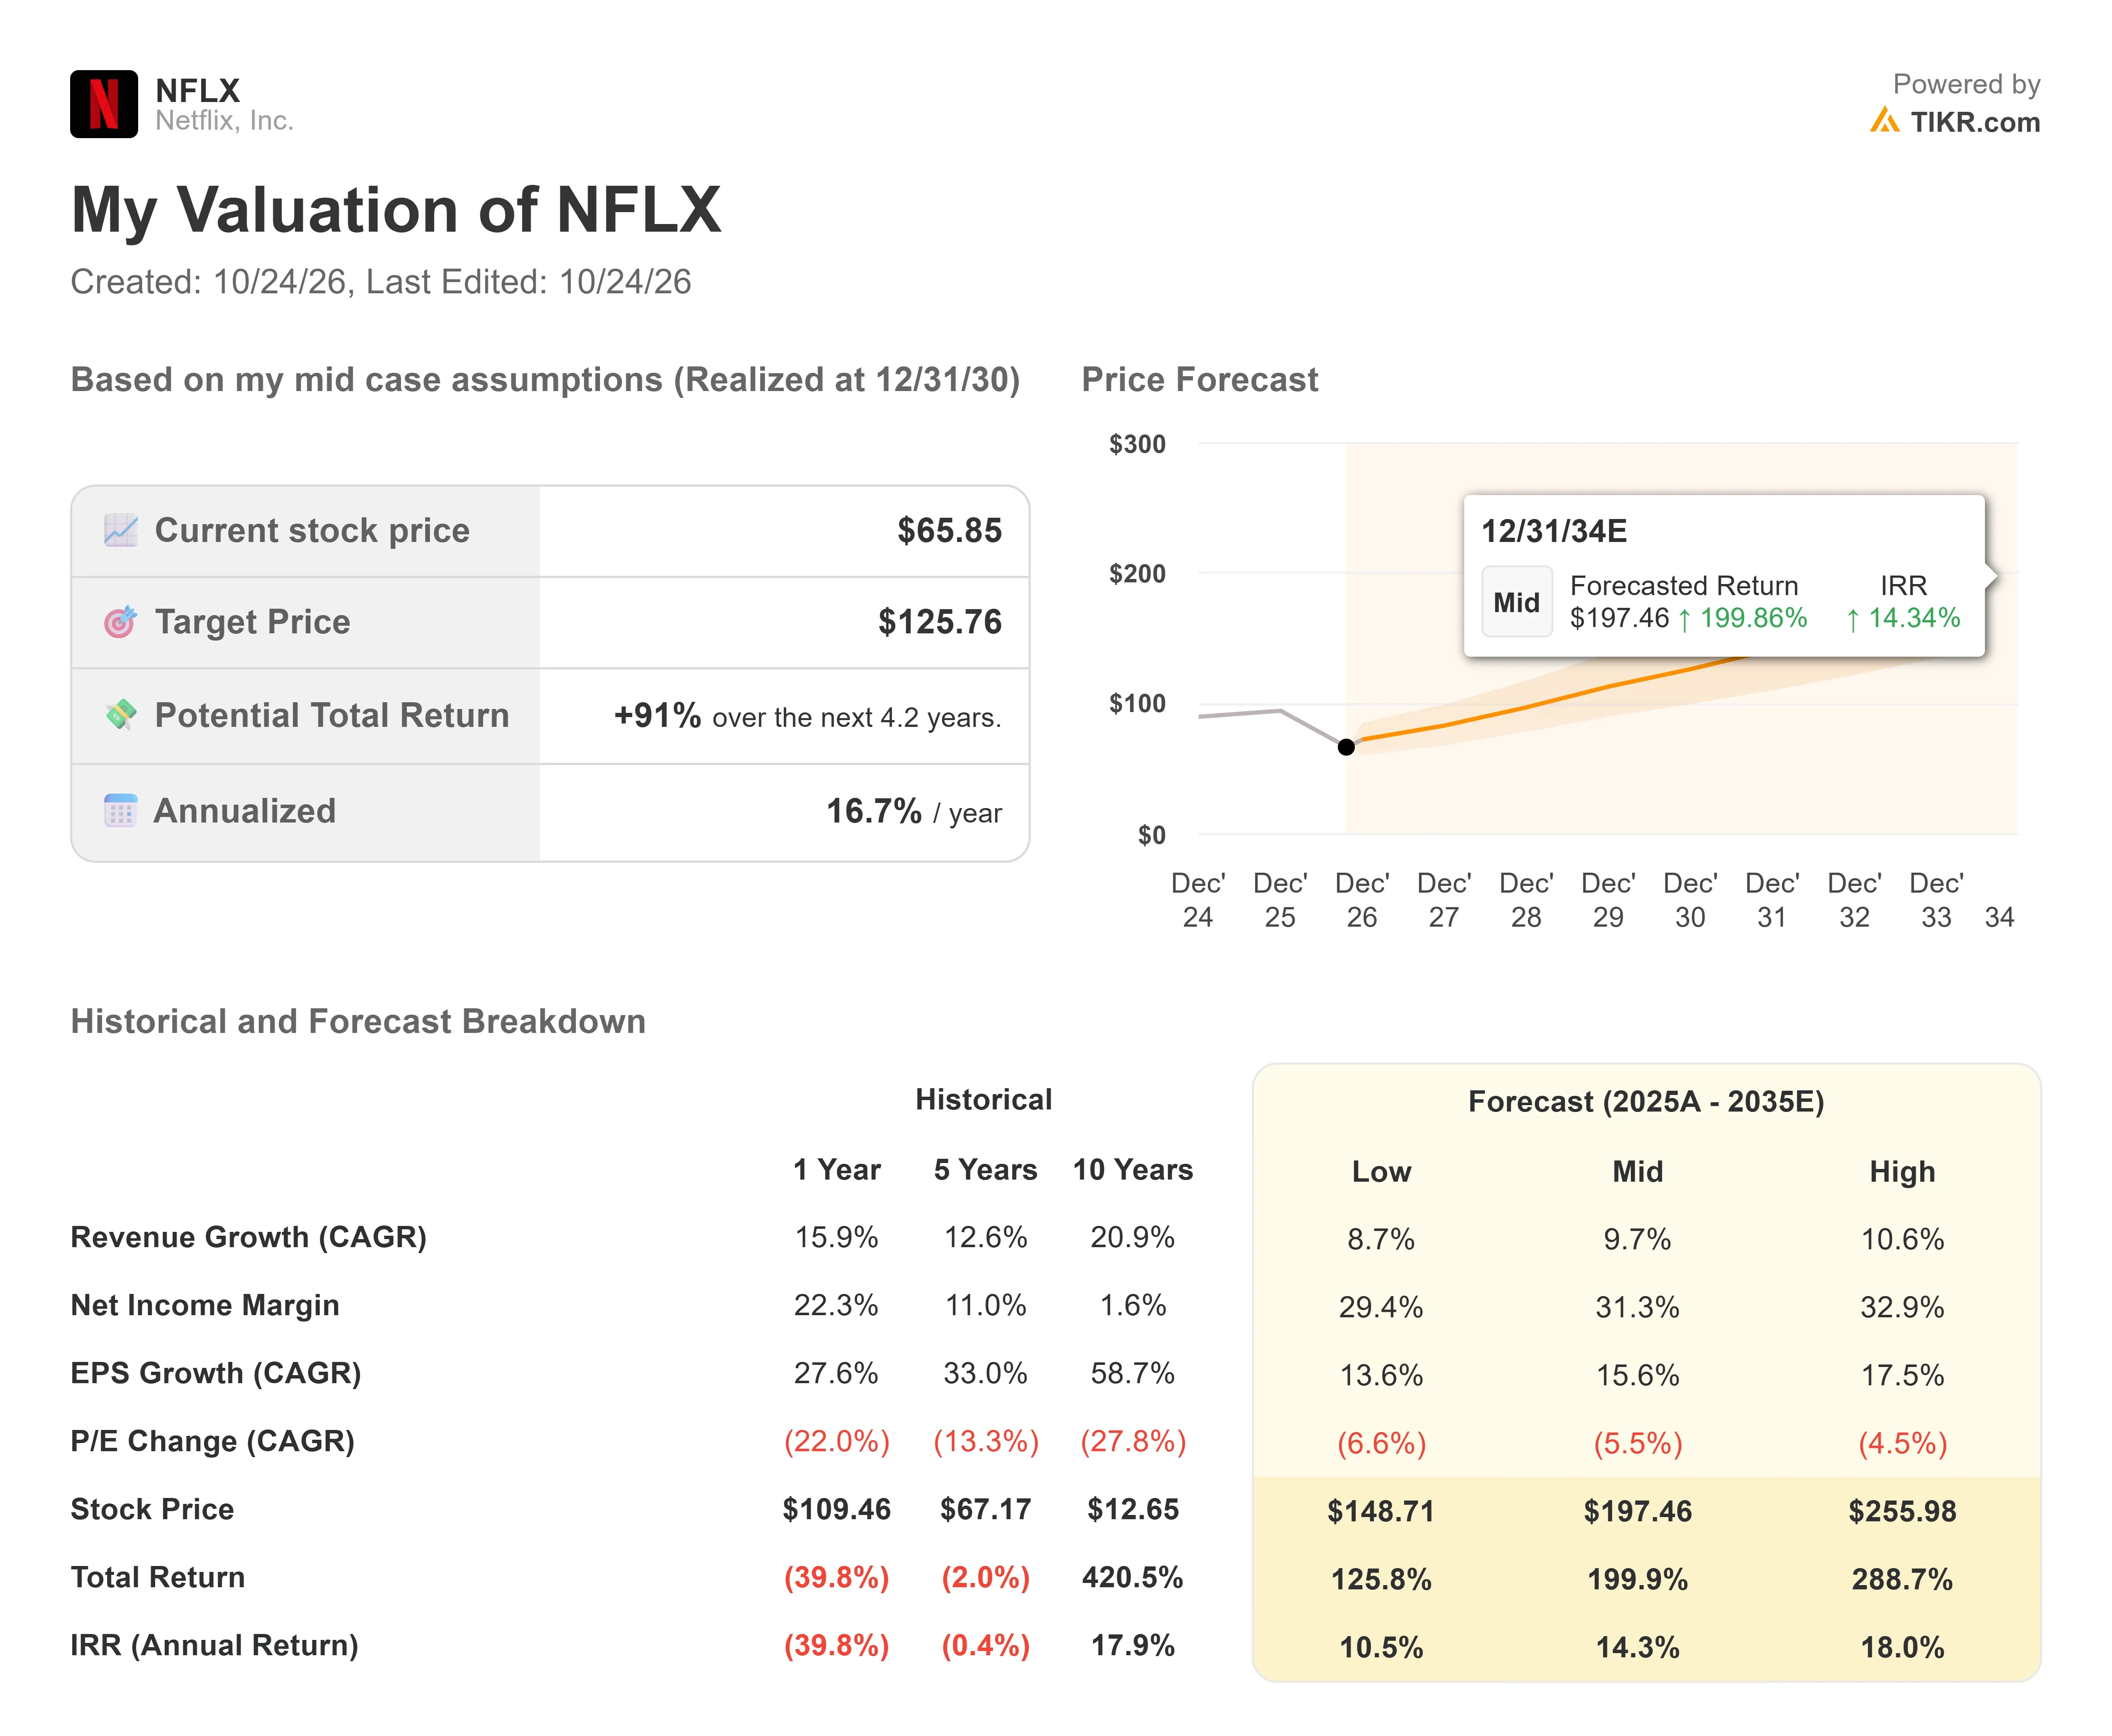
The TIKR mid case points to around $126 by December 31, 2030, about 91% above $65.85, or around 17% a year. It is a scenario, not a forecast. The model’s mid-case inputs assume around 10% annual revenue growth, below the double-digit pace CFO Spence Neumann said Netflix looks to “sustain.” The heavier lift is margin: around 31% net income margin, up from 24.3% in fiscal 2025, though the Street already expects around 30% for 2026. At $126, shares would trade near 20 times 2030 consensus EPS of around $6.20, close to today’s 19x trailing multiple.
The primary risk is estimate drift: 2027 revenue consensus slipped to around $56.6 billion from around $57.4 billion at the end of June. Upside comes from U.S. hits that travel like India’s; downside is a slate stuck at doubles, pulling estimates and the multiple toward Disney’s.
Conclusion
The mid case points higher, but the real test is Netflix’s fourth-quarter report in January, which brings 2027 guidance, including margins. A revenue guide at or above the roughly $56.6 billion consensus, about 11% growth, would show the engine still compounds. A guide below 10% would point to the U.S. slowdown spreading beyond viewing.
So what is Netflix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Netflix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Netflix on TIKR Free →
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!