Key Takeaways
- Nebius secured a $3.5 billion senior secured facility from Citi on October 22, its second contract-backed financing since July.
- Q2 revenue rose 454% to $582.3 million, but the $7 billion to $9 billion run-rate target implies a steep second-half ramp.
- Roughly $10 billion of convertible debt and a 364-day maturity on the new facility keep refinancing risk front and center.
- The November 12 Q3 report, with consensus revenue near $905 million, will test how quickly contracts turn into revenue.
Nebius Group (NBIS) has found a new way to pay for its buildout. Instead of selling another convertible, it is borrowing against the customers it already signed.
The company secured a $3.5 billion senior secured facility from Citigroup (C) on October 22. Shares still fell 6.8% last week to $159, caught in a neocloud selloff tied to AI debt fears.
That leaves the stock about 47% below its $299.86 high, even though Street targets average $281.
I find the financing shift more interesting than the headline number. It changes who bears the risk if the buildout slips.
A one-year loan for long assets
The Citi deal has three features worth noting:
- A 364-day maturity, so it functions as bridge capital
- Pricing at Term SOFR plus 2.75%, stepping up to a maximum of 3.50%
- Proceeds aimed at data center development, GPU procurement and general corporate purposes
It follows Nebius’s first secured facility, a $775 million loan in July priced at SOFR plus 2.50% and maturing in 2030. Deployed GPUs and contracted cash flows from an investment-grade customer back that one.
Before July, convertibles did most of the work. Nebius closed $5.75 billion of notes in August, leaving roughly $10 billion of convertible debt outstanding.
So how much debt has the balance sheet absorbed so far?

Total debt stepped up sharply in 2026, and the Citi facility adds to that before any refinancing.
Contracts doing the collateral work
The pitch to lenders rests on more than $40 billion of long-term contracts with investment-grade customers, including Microsoft (MSFT) and Meta Platforms (META). Those contracts can serve as collateral for future asset-backed deals.
Growth gives the strategy credibility. Q2 revenue rose 454% to $582.3 million, and first-half revenue reached $981.3 million, up 529%.
New channels keep arriving, too. A $1 billion-plus compute deal with Reflection runs through 2029, and a partnership with Palantir Technologies (PLTR) adds a sovereign AI channel for government and enterprise buyers.
Nebius also plans roughly 1 gigawatt of Nvidia (NVDA) Vera Rubin capacity in 2027.
Here is how steep the Street expects the climb to be:

Consensus implies revenue compounding near 380% annually over two years, a pace that depends on power arriving on schedule.
TIKR tracks 23 analysts on Nebius. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nebius, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nebius’ Analyst Ratings
The run-rate math gets steep
The target is a $7 billion to $9 billion annualized revenue run rate by the end of 2026. Q2’s $582.3 million annualizes to about $2.3 billion, so Nebius needs to roughly triple its run rate in two quarters.
Losses remain heavy during the build. Nebius posted a Q2 net loss of $190 million and an adjusted EBITDA loss of $92 million, while spending $5.7 billion on capex in the quarter.
Its balance sheet looks lighter than its closest peer’s. Nebius carries about $2.2 billion of net debt, while CoreWeave (CRWV) carries about $46 billion.
Investors reward that gap in the multiple…
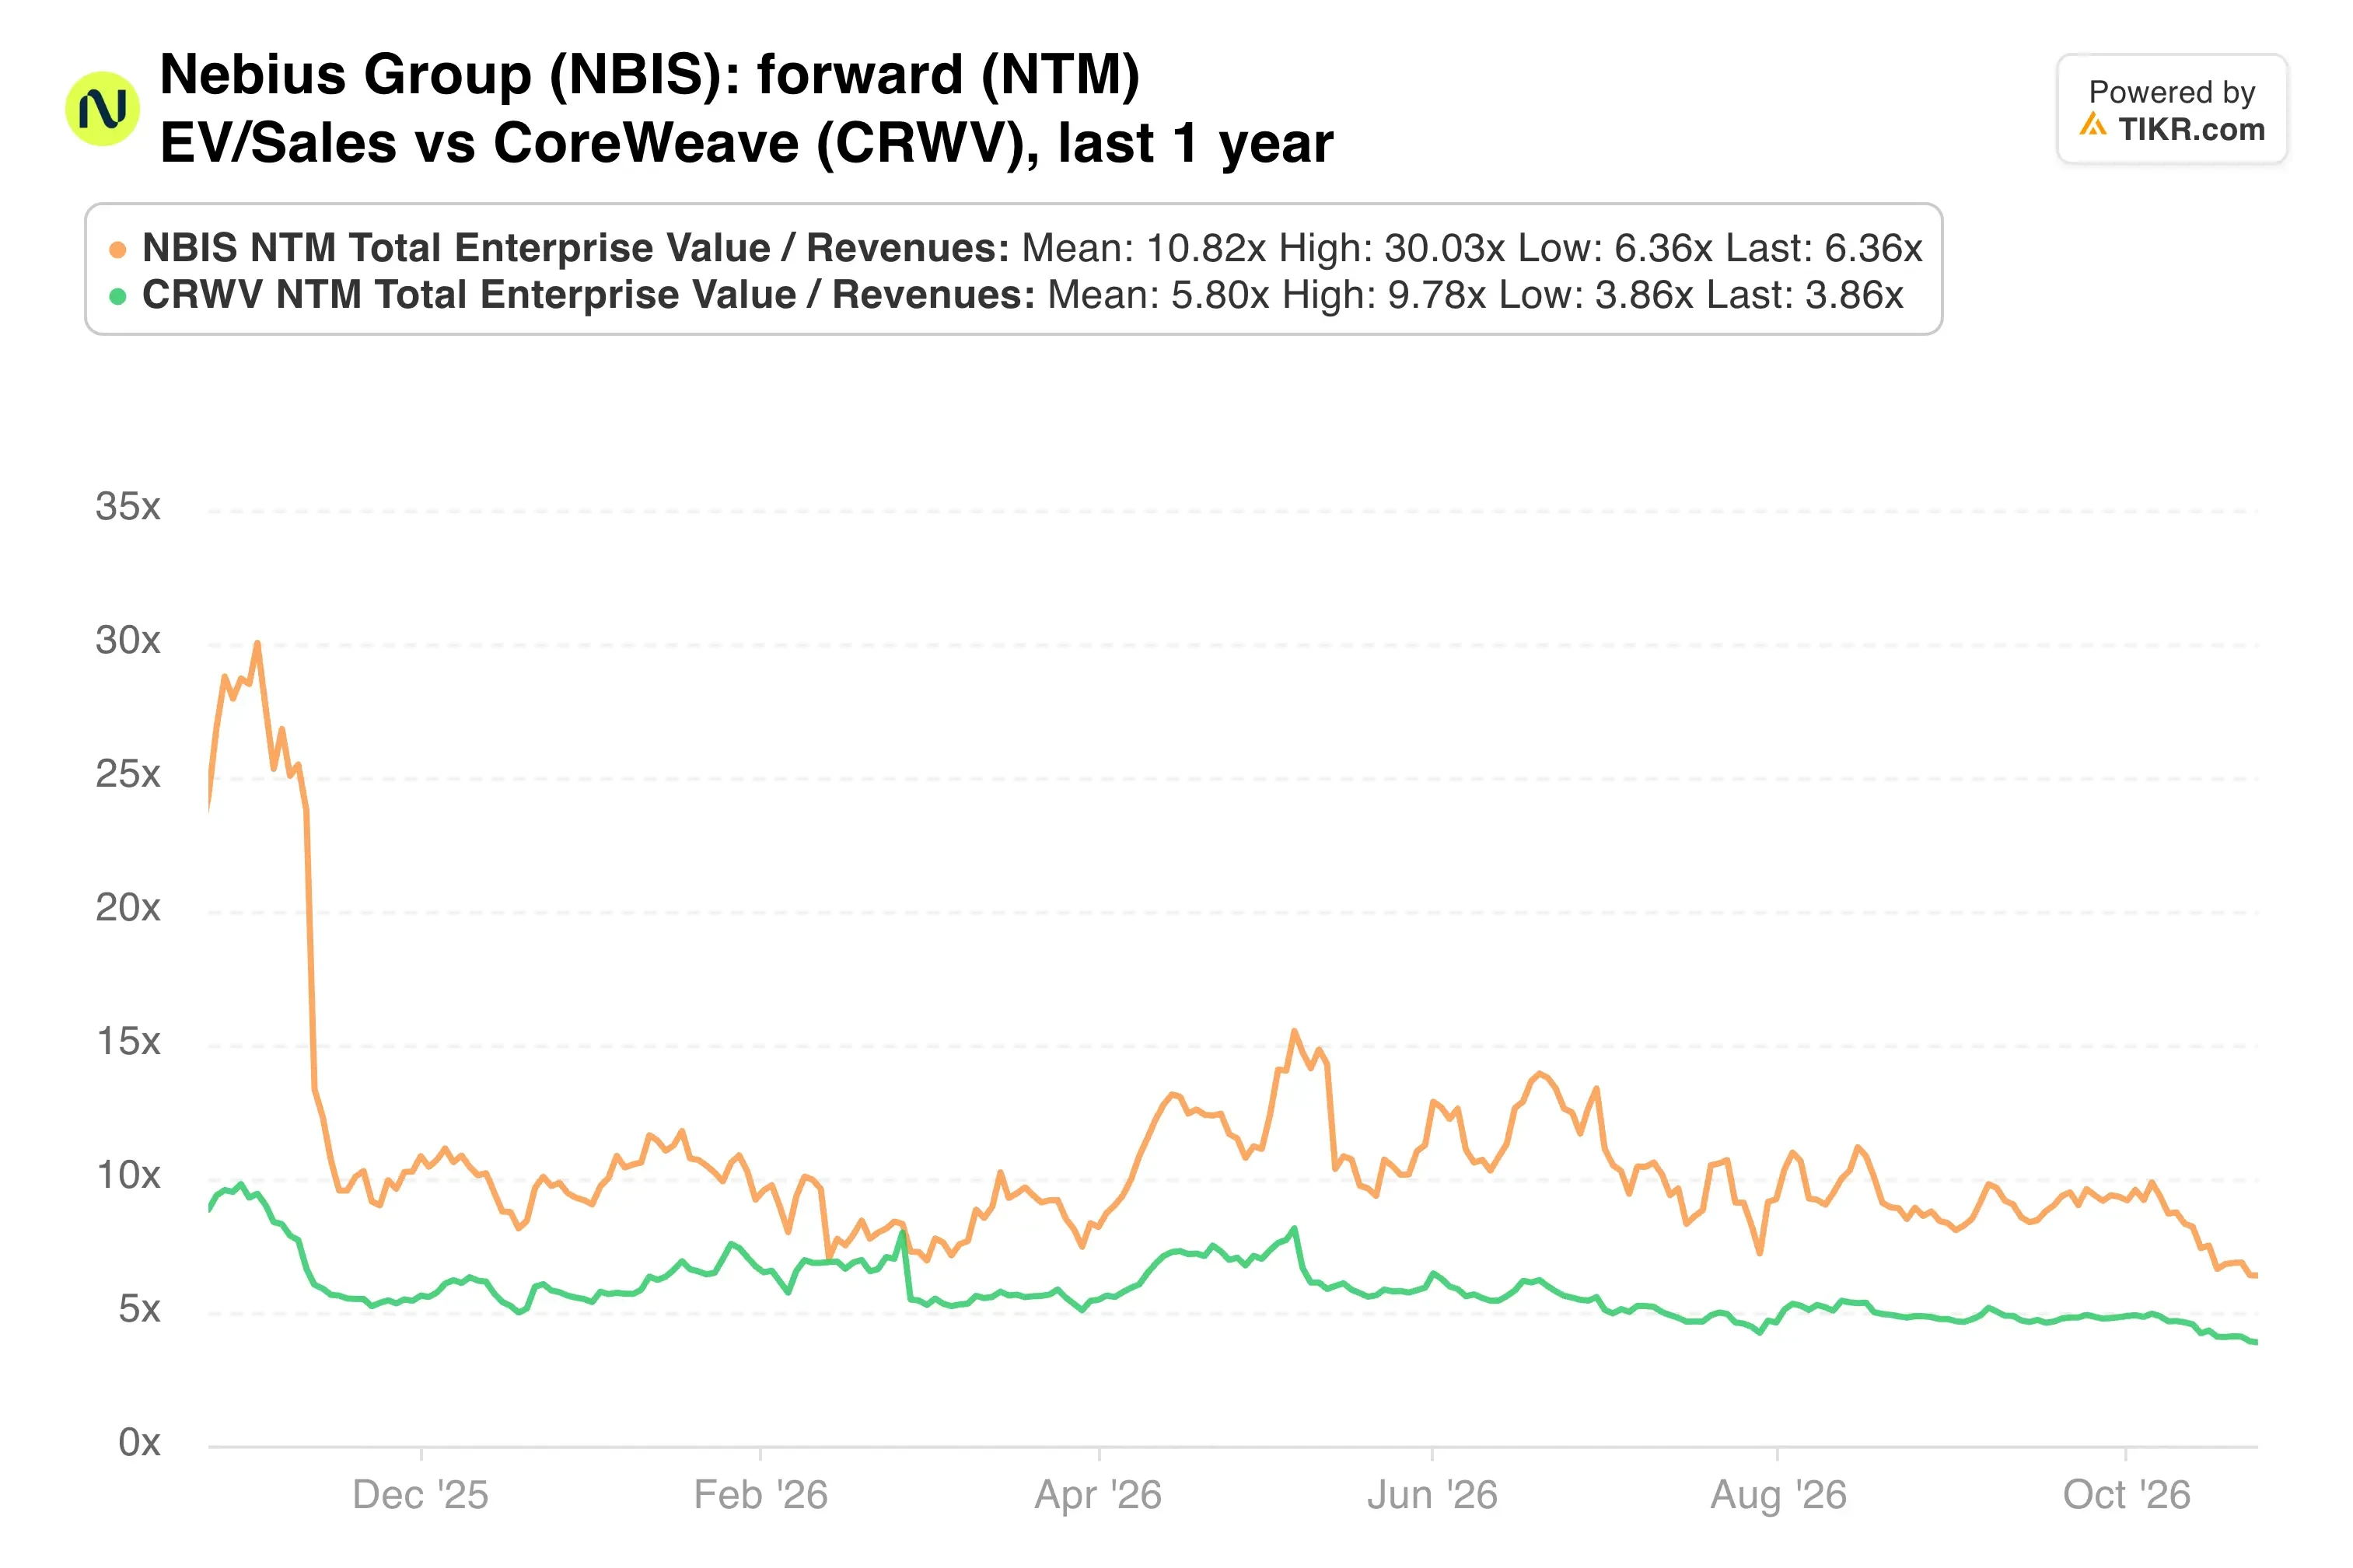
Nebius trades at 6.4x forward EV/Sales against 3.9x for CoreWeave, so the market already credits its cleaner capital structure.
My take: Borrowing against signed contracts beats diluting shareholders at $159, and a 74% gross margin suggests the unit economics hold up. Still, a 364-day facility means Nebius must refinance into a market that just punished neocloud credit. I like the strategy, but the premium multiple leaves little room for a delayed data center.
The November 12 Q3 report is the checkpoint. Consensus revenue sits near $905 million, and anything short of that would make the year-end run-rate target look stretched.
So what is Nebius stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nebius could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!