Key Takeaways
- Nebius CEO Arkady Volozh said prepayments on new contracts now cover more than 100% of the capital behind them, up from 50% to 60% last quarter.
- Prepayments and asset-backed loans should fund 75% to 85% of 2027’s $40 billion to $45 billion capex plan.
- Third-quarter operating cash flow was still negative $273 million, as receivables jumped $3.76 billion.
Nebius Group (NBIS) sold off after its Nov. 12 report lifted 2026 capex guidance to $27 billion, from $20 billion to $25 billion, and set 2027’s at $40 billion to $45 billion, against FactSet’s $28.77 billion consensus. But customers are now paying for more of the build, the same answer CoreWeave (CRWV) gave on Nov. 10, when it ruled out unsecured debt at today’s yields.
CEO Arkady Volozh opened the third-quarter call by asking, “How fast can AI build-out happen, and who will pay for it?” His answer to the second: “the prepayments on new contracts now cover more than 100% of the capital needed to bring this contracted capacity online,” up from 50% to 60% last quarter.
Nebius Customers Are Paying More, Up Front
Third-quarter deals carried annual contract value above $25 million per megawatt, up from $20 million to $25 million in the second quarter, so “payback in Q3 shortened to one year and seven months from one year and 10 months a quarter earlier.” That’s on one- to three-year deals, excluding prepayments.
Nebius expects $10 billion of committed prepayments this year and $17 billion to $20 billion in 2027. Those prepayments plus asset-backed loans on existing investment-grade contracts should fund 75% to 85% of 2027 capex, its shareholder letter says. That leaves $6 billion to $11.25 billion for its $7.43 billion of cash and new capital.
The Cash Hasn’t Caught Up
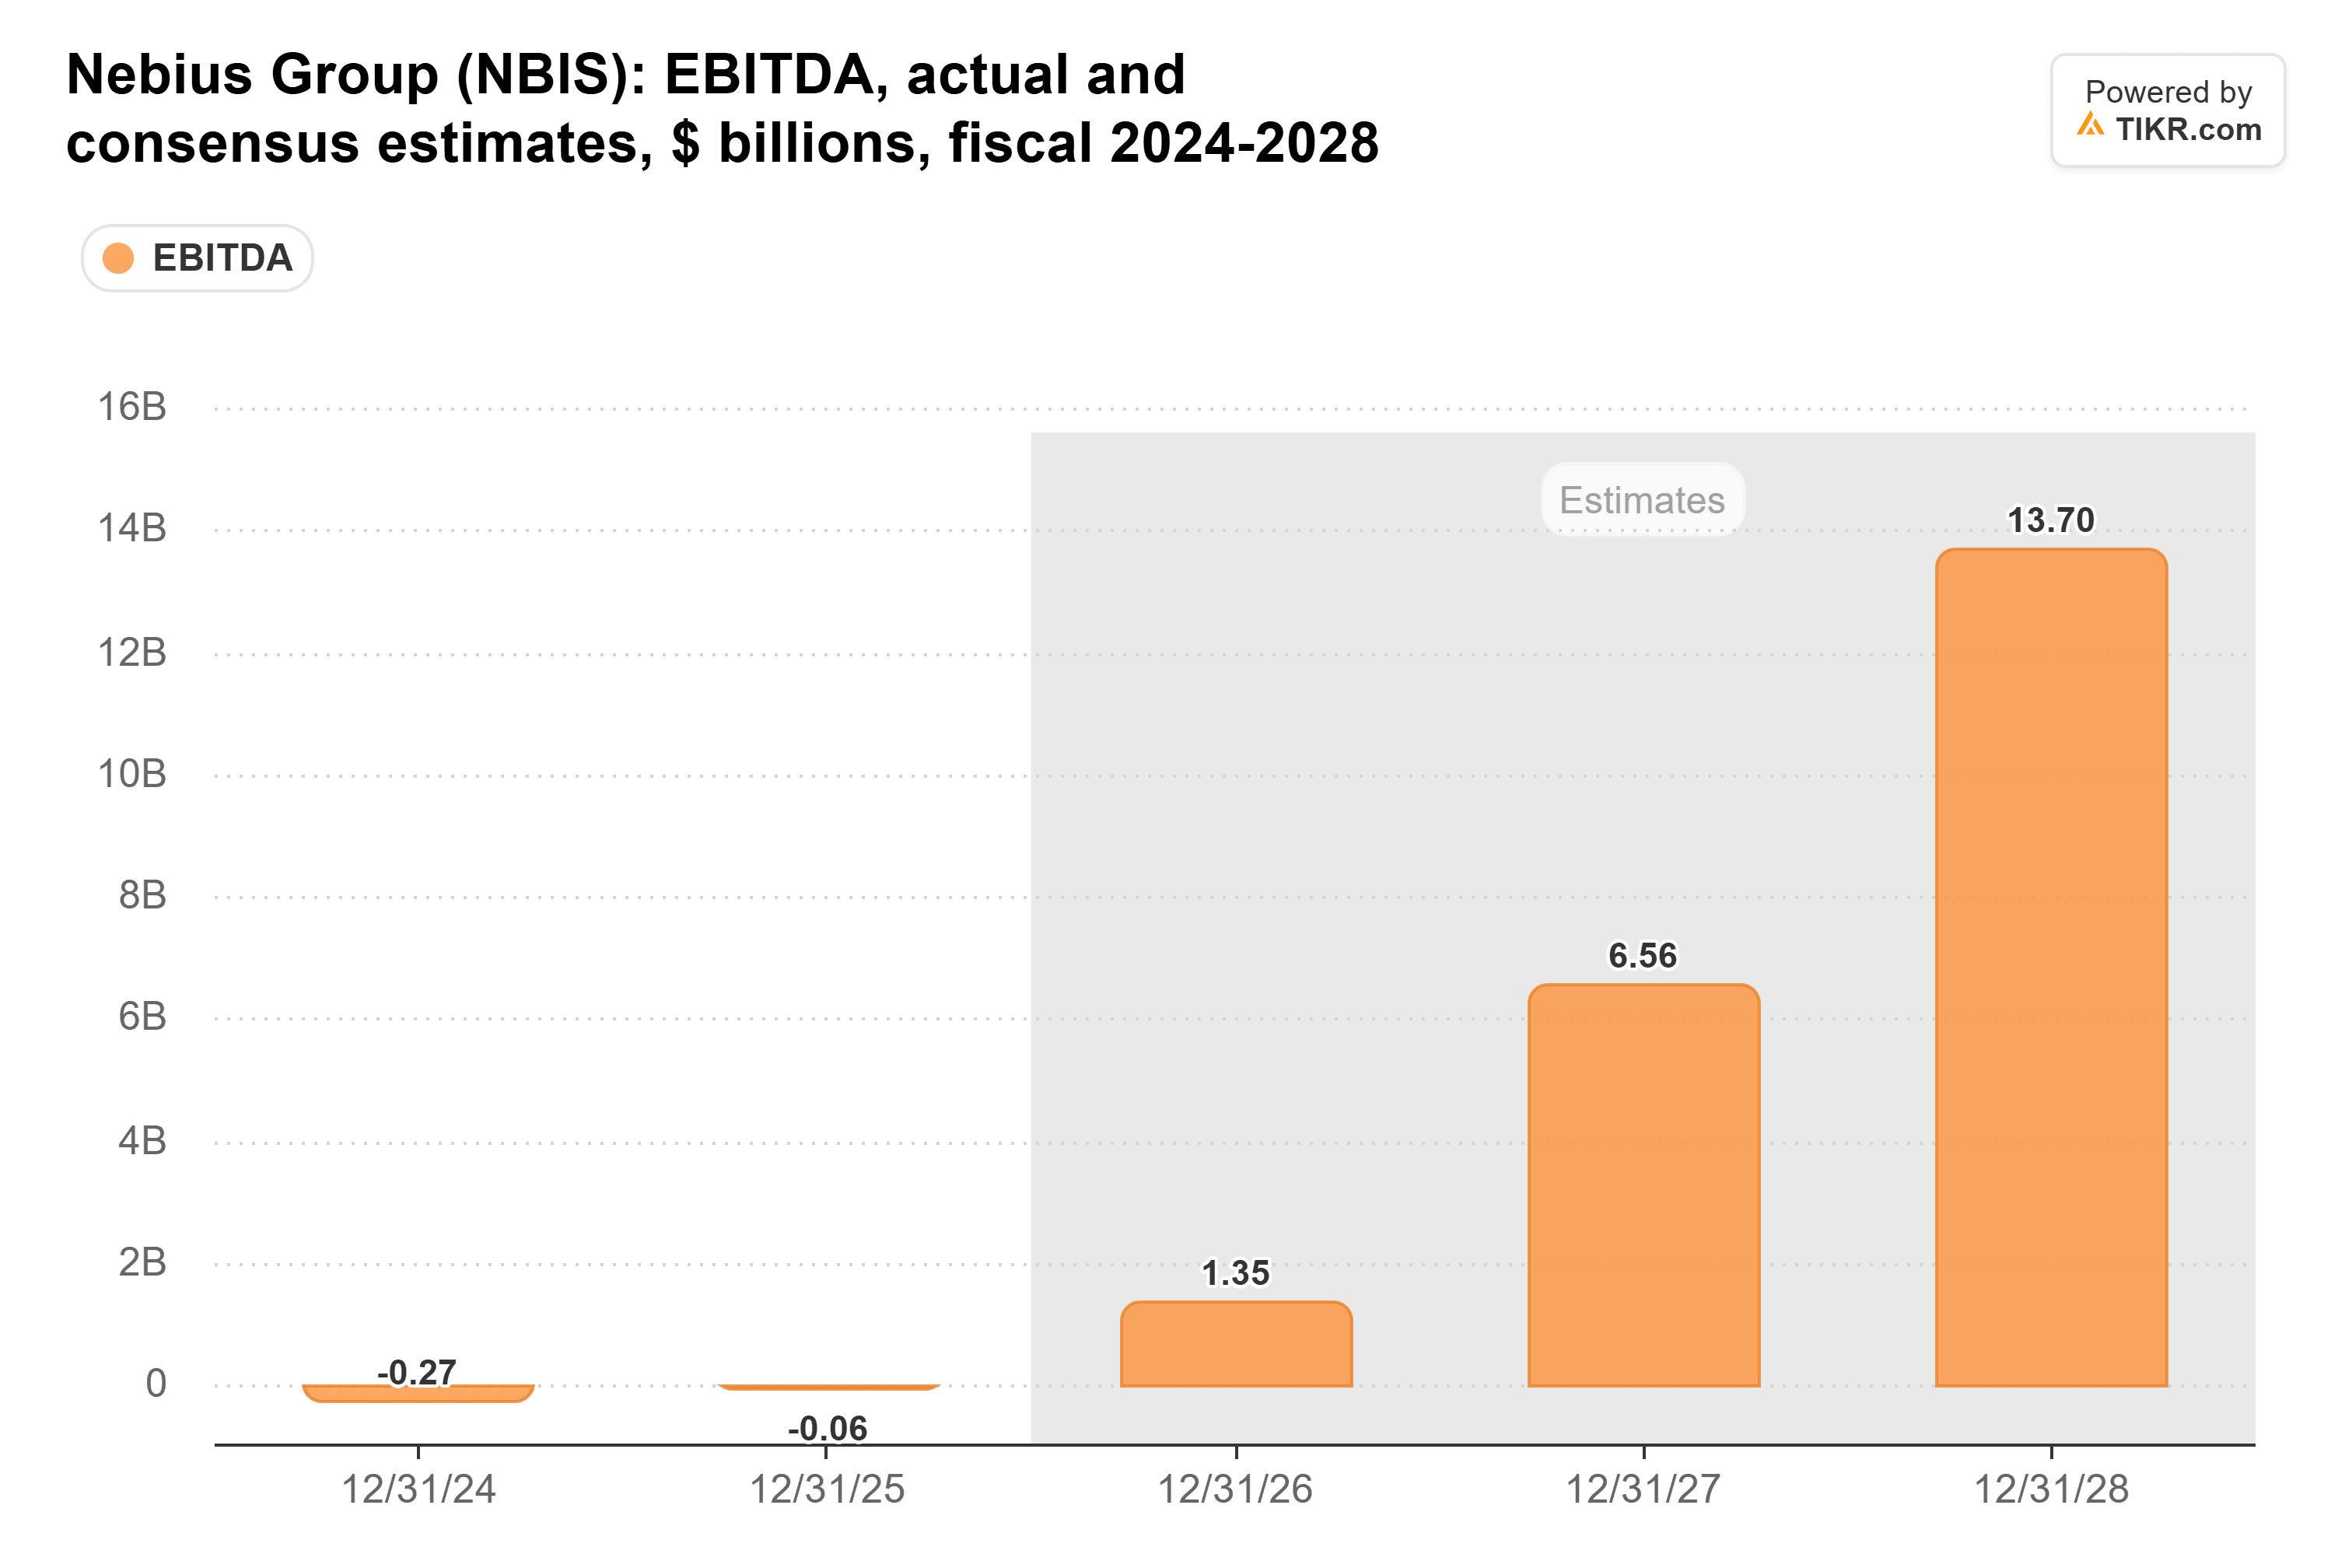
Atreides Management’s Gavin Baker posted on X on Nov. 10 that the shift to prepayments “means that OCF to EBITDA is the most important metric.” If customers pay up front, operating cash flow should run ahead of EBITDA, which analysts see climbing from $1.35 billion this year to $13.7 billion in 2028:
Through June, it did, with operating cash flow above $2 billion a quarter even as June-quarter capex climbed to $5.7 billion:
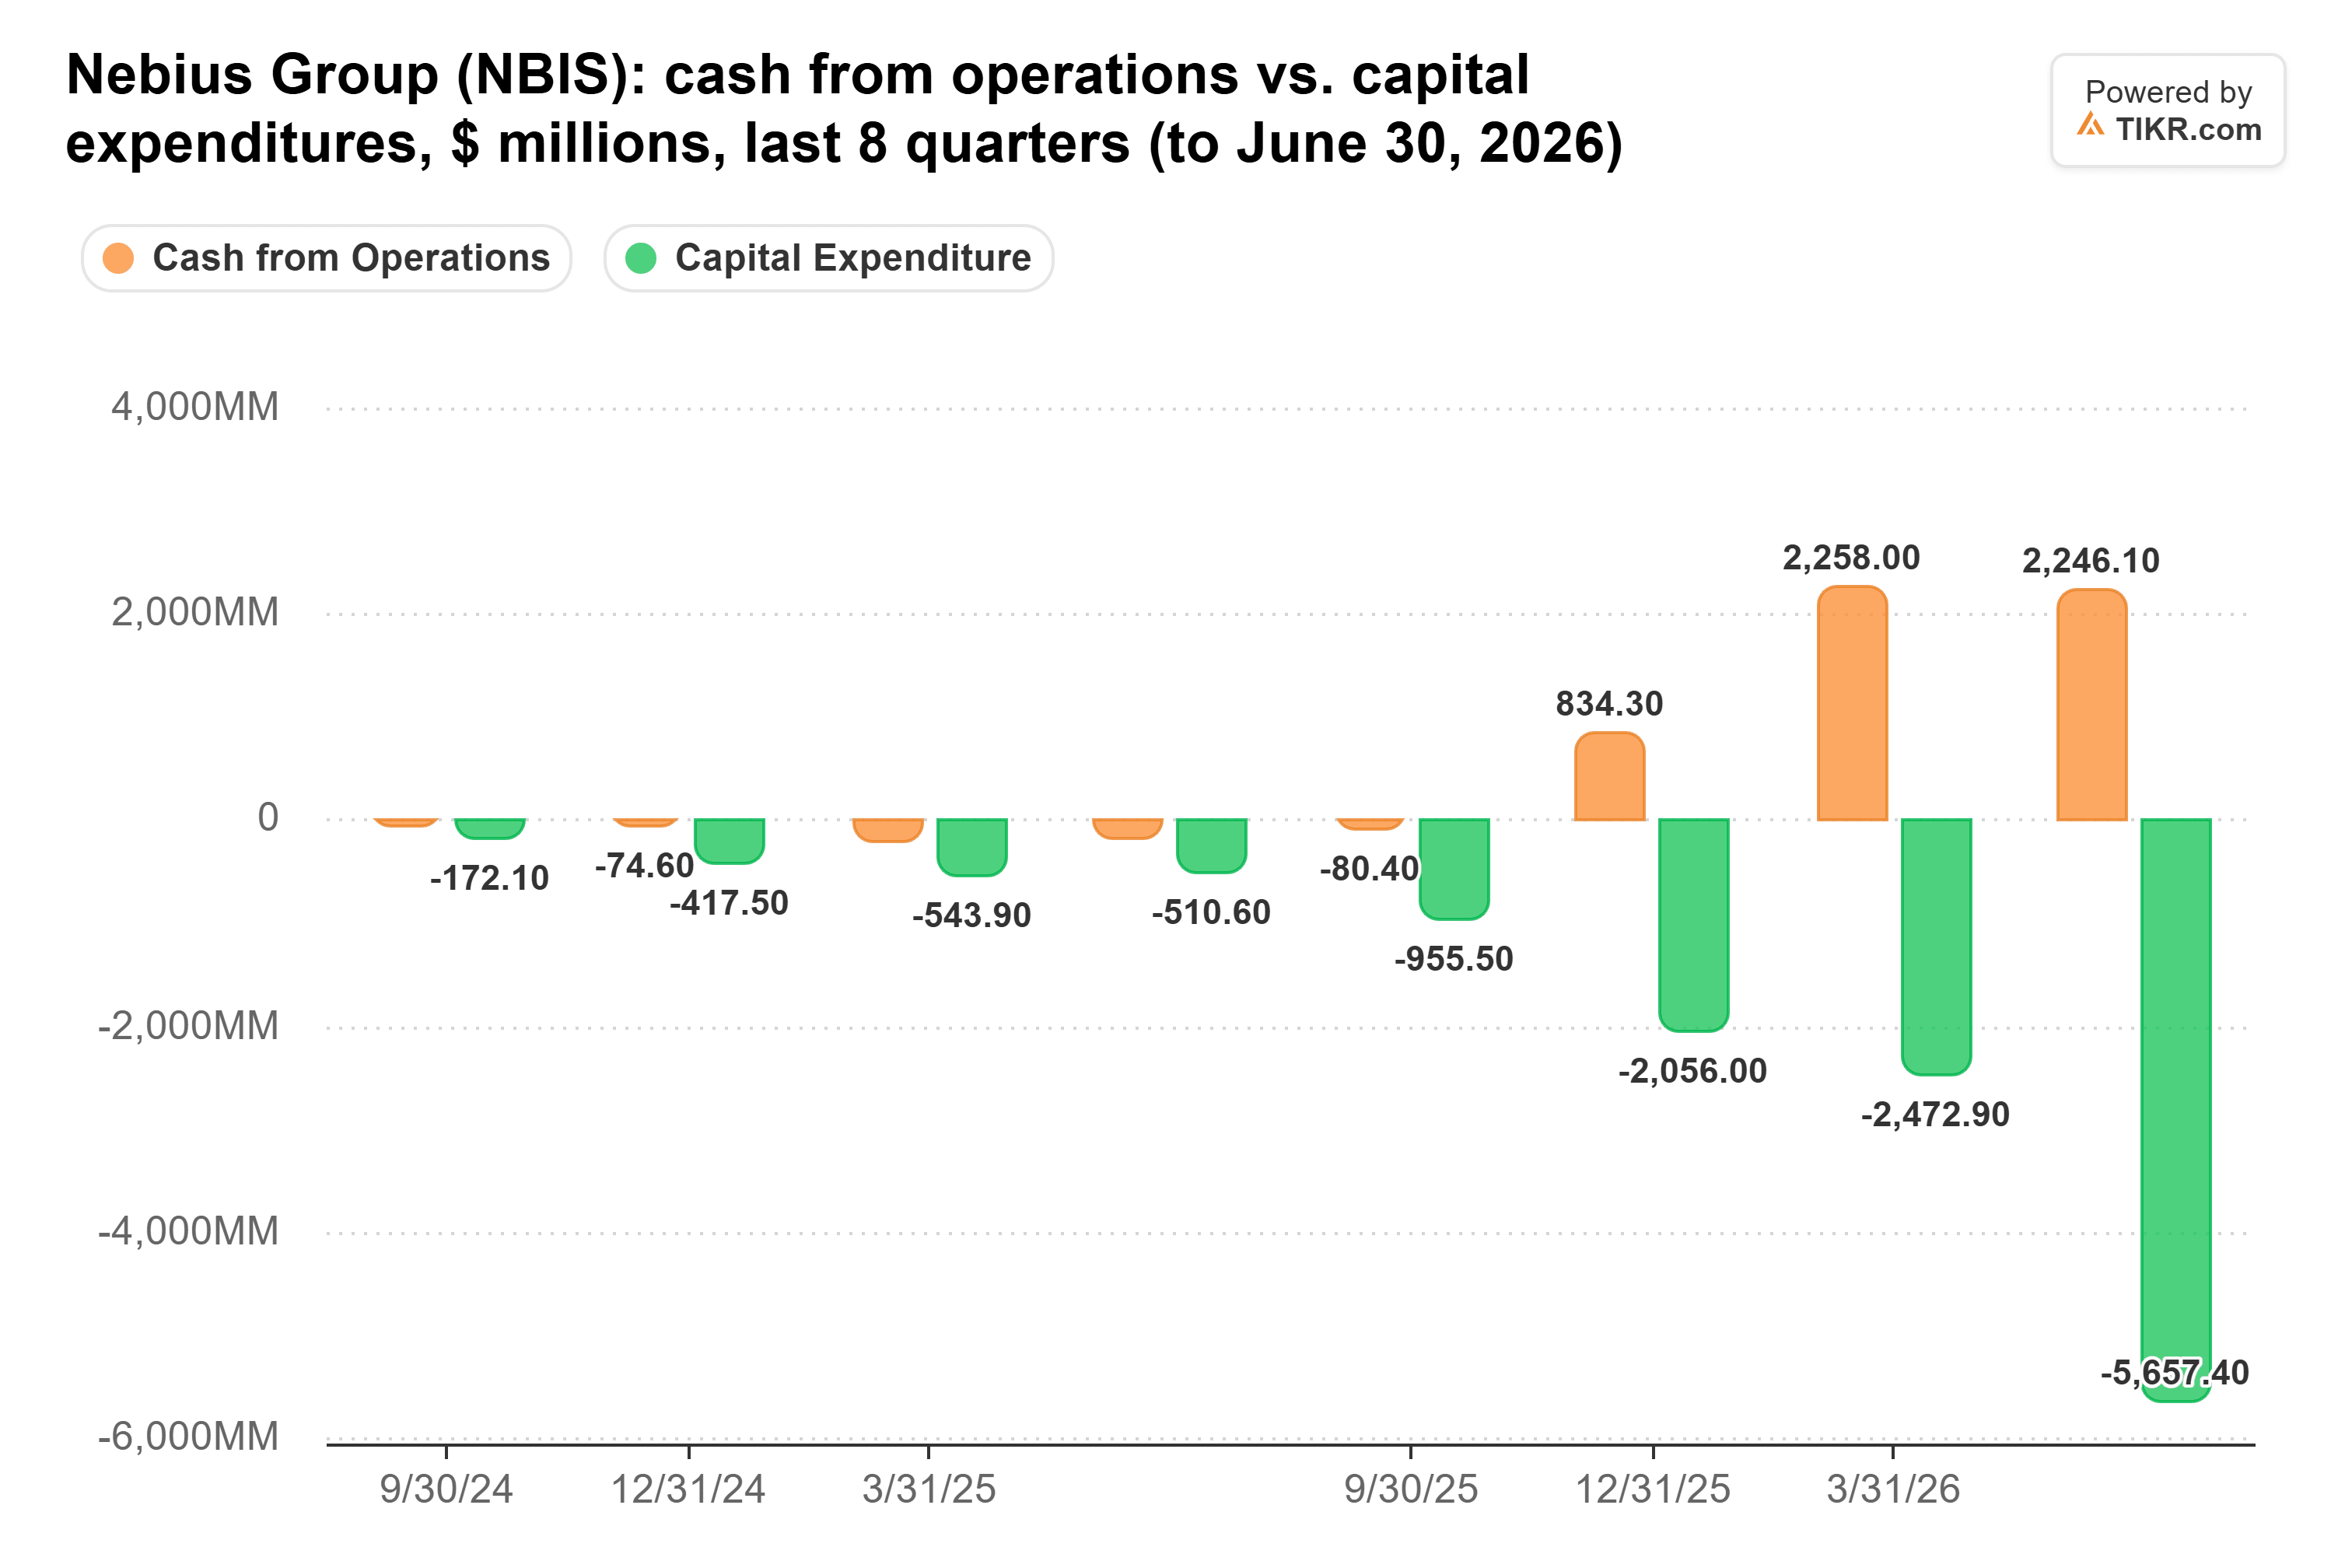
Then it flipped. Third-quarter operating cash flow was negative $273 million against $465.8 million of adjusted EBITDA. Deferred revenue rose $3.43 billion, but receivables rose $3.76 billion, almost four times the quarter’s $980.8 million of revenue. My read: collections haven’t kept pace with billings.
Strong prepayment terms haven’t prevented a quarterly operating cash outflow.
TIKR Tracks 22 Analysts on Nebius. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nebius, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nebius’ Analyst Ratings
A Prepayment Is Capacity Nebius Owes
Some colocation sites, including New Jersey, are behind schedule, Volozh said, so some “planned revenue moves into the start of next year,” though none of that capacity is canceled. Nebius now expects 2026 revenue of $3 billion to $3.2 billion, down from $3 billion to $3.4 billion.
Total debt reached $10.2 billion by June 30:
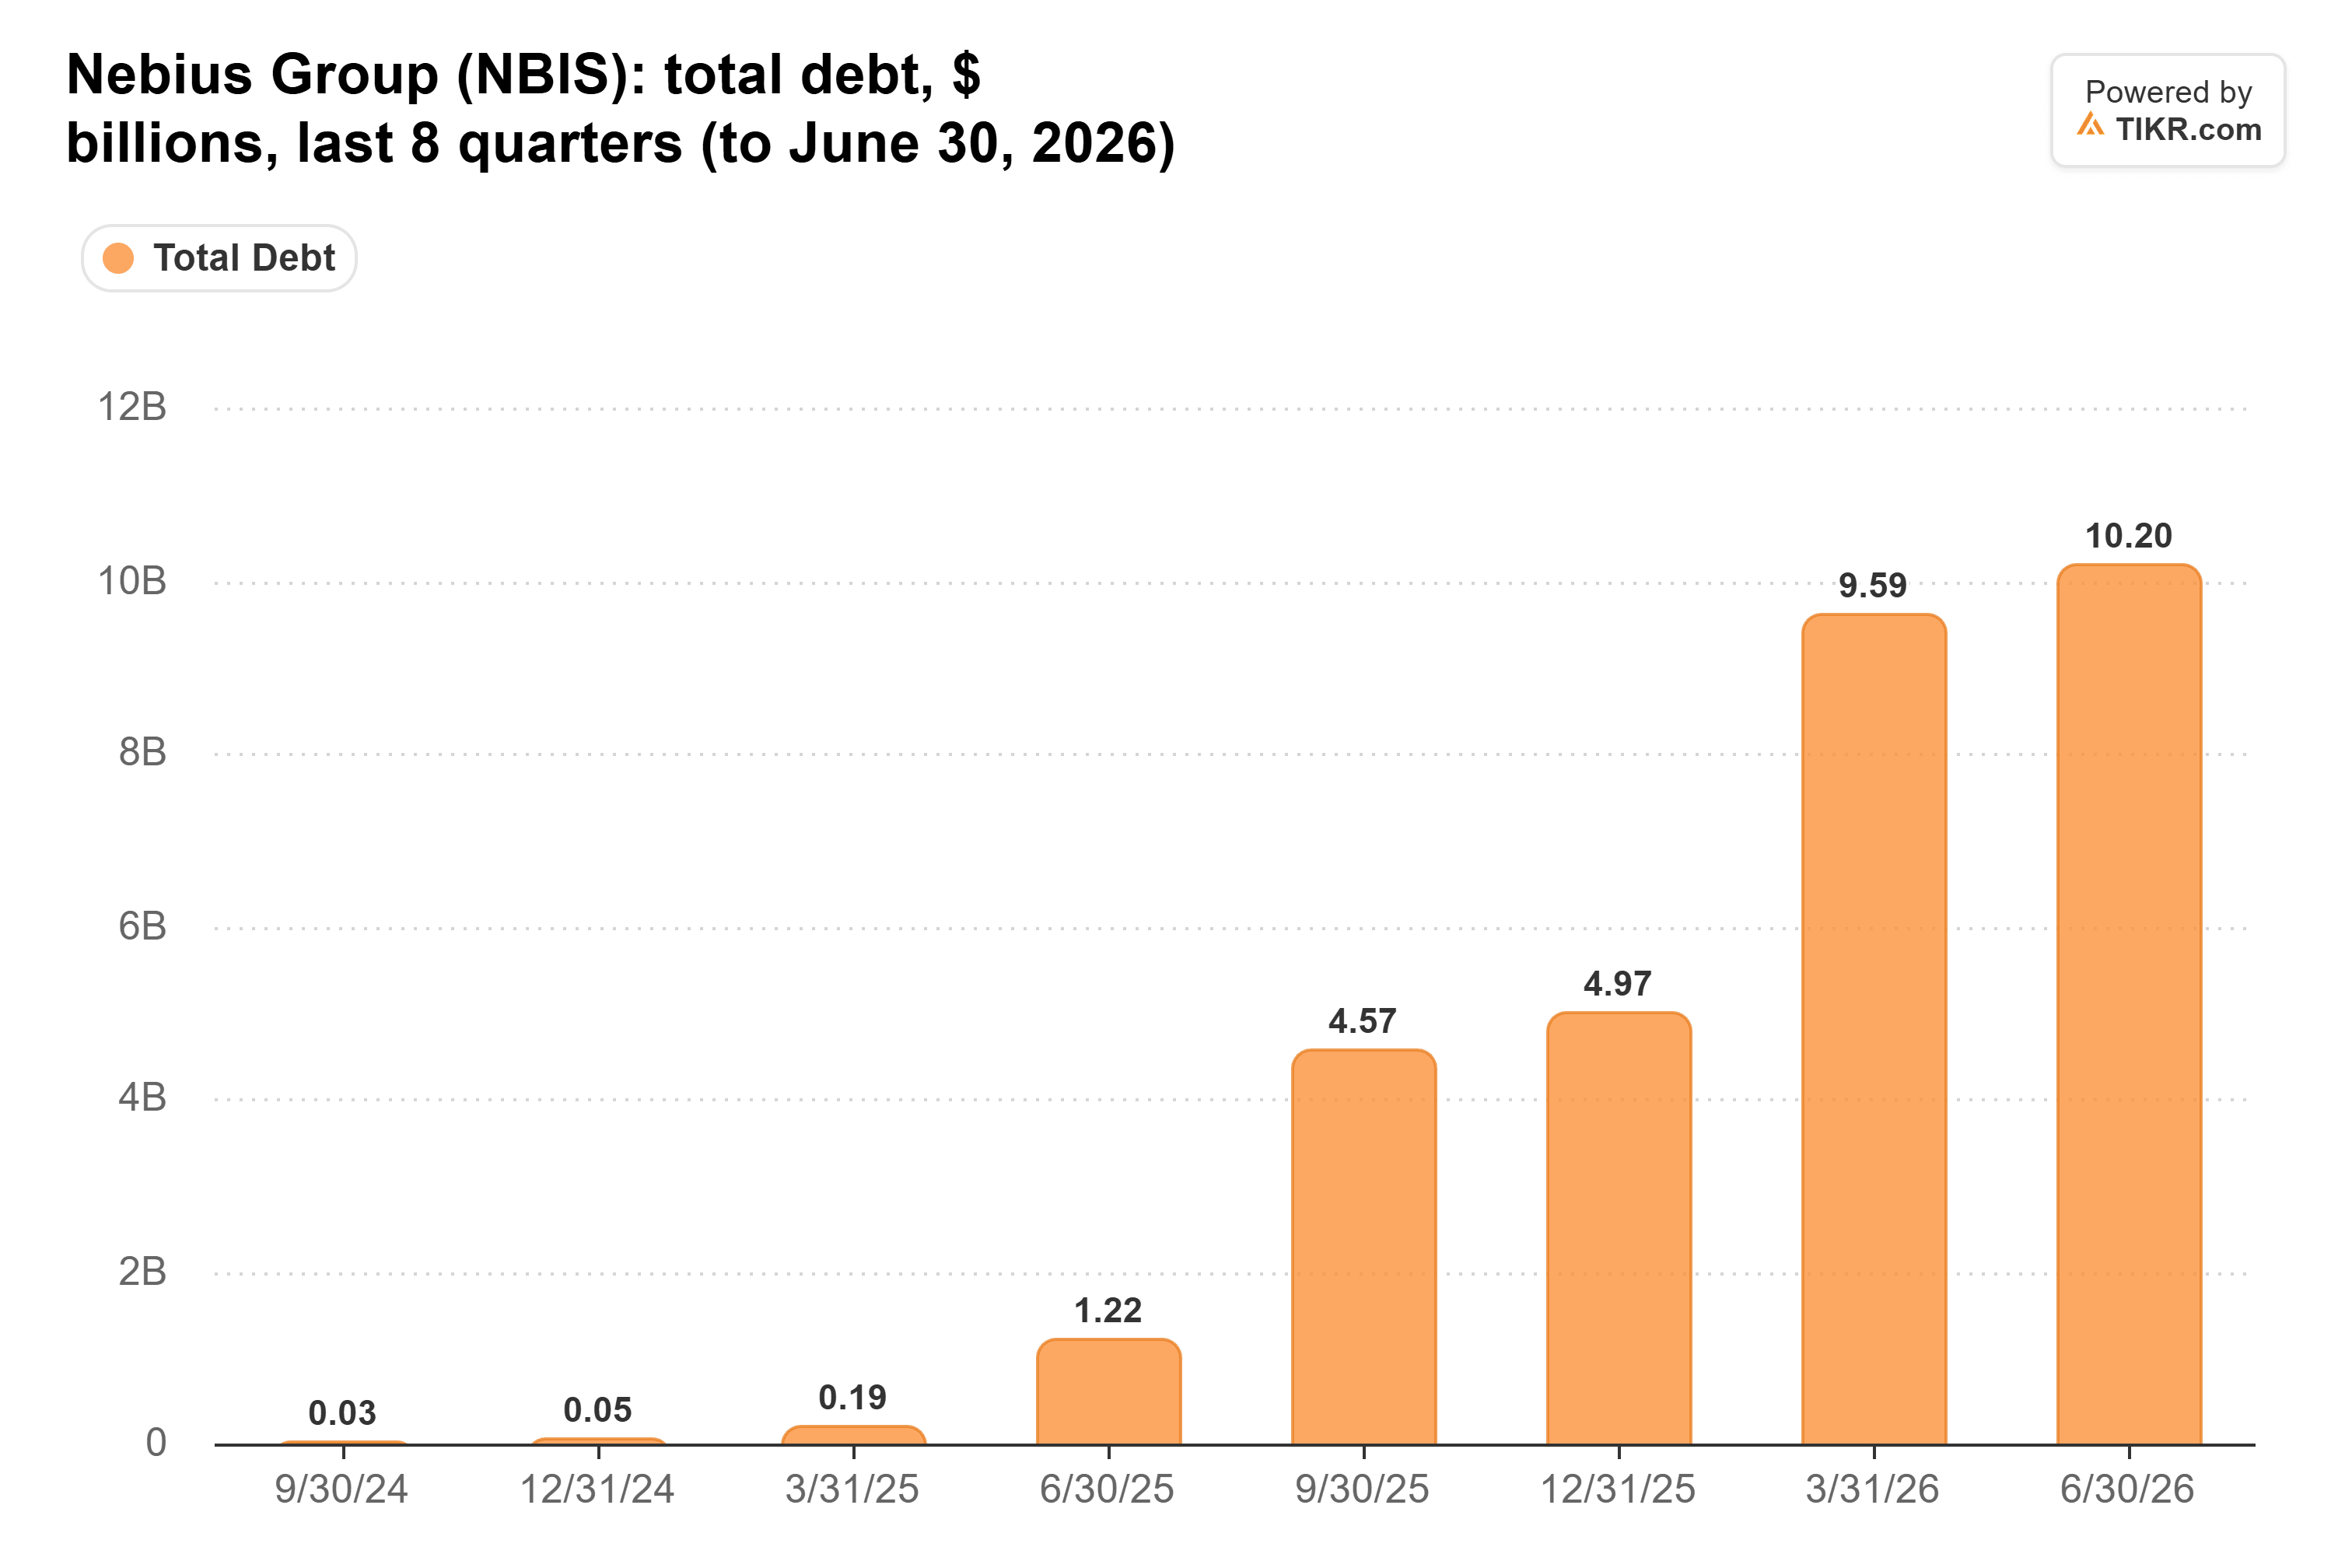
Leave out leases, and cash covered nearly all of it: net borrowings were $504 million at June 30, against $29.5 billion at CoreWeave. After $5.75 billion of convertible notes in August, debt excluding leases was $14.19 billion at Sept. 30, against $7.43 billion of cash.
Nebius Still Has to Collect
Customers paying for their own capacity makes a $40 billion-plus plan far more fundable than the selloff suggests, and I’d side with the bulls on that. But a contract funds nothing until the cash lands, and receivables stood at $4.04 billion on Sept. 30. If those bills are paid by Dec. 31, fourth-quarter operating cash flow should swing back above EBITDA, right where Baker says to look.
So what is Nebius stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nebius could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!